
 Natural Dog Treat Market | 2026-2036
Natural Dog Treat Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Dog Treat Market Insights
Millennial and Gen Z pet owners is rotating toward functional, human-grade treats, displacing conventional mass-market buyers as the dominant spending cohort. Mars Petcare leverages its veterinary channel partnerships to anchor premium positioning. Blue Buffalo Company differentiates through grain-free and limited-ingredient formulations. Wellness Pet Company sustains loyalty via science-backed functional claims across digestive and dental segments.
Natural dog treats comprise consumable pet products formulated without artificial preservatives, colors, or synthetic additives, typically manufactured through low-temperature dehydration, freeze-drying, or cold-pressing to preserve nutritional integrity and enzymatic activity. Their primary commercial purpose centers on rewarding behavior, delivering targeted health outcomes, and deepening human-animal bond engagement through transparent ingredient provenance. Dental treats and jerky command margin pools due to repeat purchase frequency and premium pricing elasticity, while chews anchored by free-range meat sourcing represent the fastest-growing ingredient-led segment. Grain-free formulations retain volume leadership in North American retail channels despite ongoing regulatory scrutiny.
The FDA's Center for Veterinary Medicine enforces ingredient safety and labeling standards, while the USDA regulates organic claims and meat sourcing traceability, collectively elevating compliance costs but also filtering out subscale private-label entrants. State-level feed control officials in California and Texas administer additional facility inspection protocols that shape regional distribution economics. Stakeholders must monitor evolving AAFCO nutrient profiles and state raw-feeding restrictions to anticipate reformulation mandates and channel access shifts.
Market Dynamics
Clean-label ingredient sourcing requirements are compressing formulation flexibility while elevating compliance costs, forcing manufacturers to rebuild supply chains around certified organic and free-range protein channels.
Growth Catalysts
- USDA Organic Certification:Federal traceability mandates for meat sourcing enable premium pricing and filter out subscale competitors lacking documentation infrastructure.
- Freeze-drying technology:Low-temperature dehydration preserves enzymatic activity and extends shelf life without synthetic preservatives, attracting functional-focused buyers.
- Veterinary channel expansion:Mars Petcare's clinic partnerships demonstrate how professional endorsement anchors consumer trust and repeat purchase behavior.
Market Restraints
- Free-range protein cost volatility:Input prices for grass-fed beef and pasture-raised poultry fluctuate with feed grain markets and seasonal availability.
- FDA grain-free scrutiny:Ongoing investigations into dilated cardiomyopathy links create reformulation risk and label liability exposure.
- Dehydration equipment concentration:Commercial-scale freeze-dryer manufacturing clusters in Germany and Italy, creating import dependency for North American processors.
Strategic Opportunities
- Insect protein formulations:Black soldier fly larvae offer complete amino acid profiles with lower land-use intensity, appealing to sustainability-positioned brands.
- Subscription direct-to-consumer:Chewy and Amazon's recurring delivery models reduce customer acquisition costs and build predictable revenue streams.
- California Proposition 12 compliance:Stricter confinement standards for pork and veal create first-mover advantage for brands already sourcing pasture-raised inputs.
Industry Challenges
- AAFCO nutrient profile navigation:Evolving standards for complete-and-balanced claims require ongoing formulation testing and label revisions.
- Cold-chain logistics scaling:Raw and fresh treat segments demand refrigerated distribution infrastructure that conflicts with conventional pet retail warehousing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Dog Treat Market |
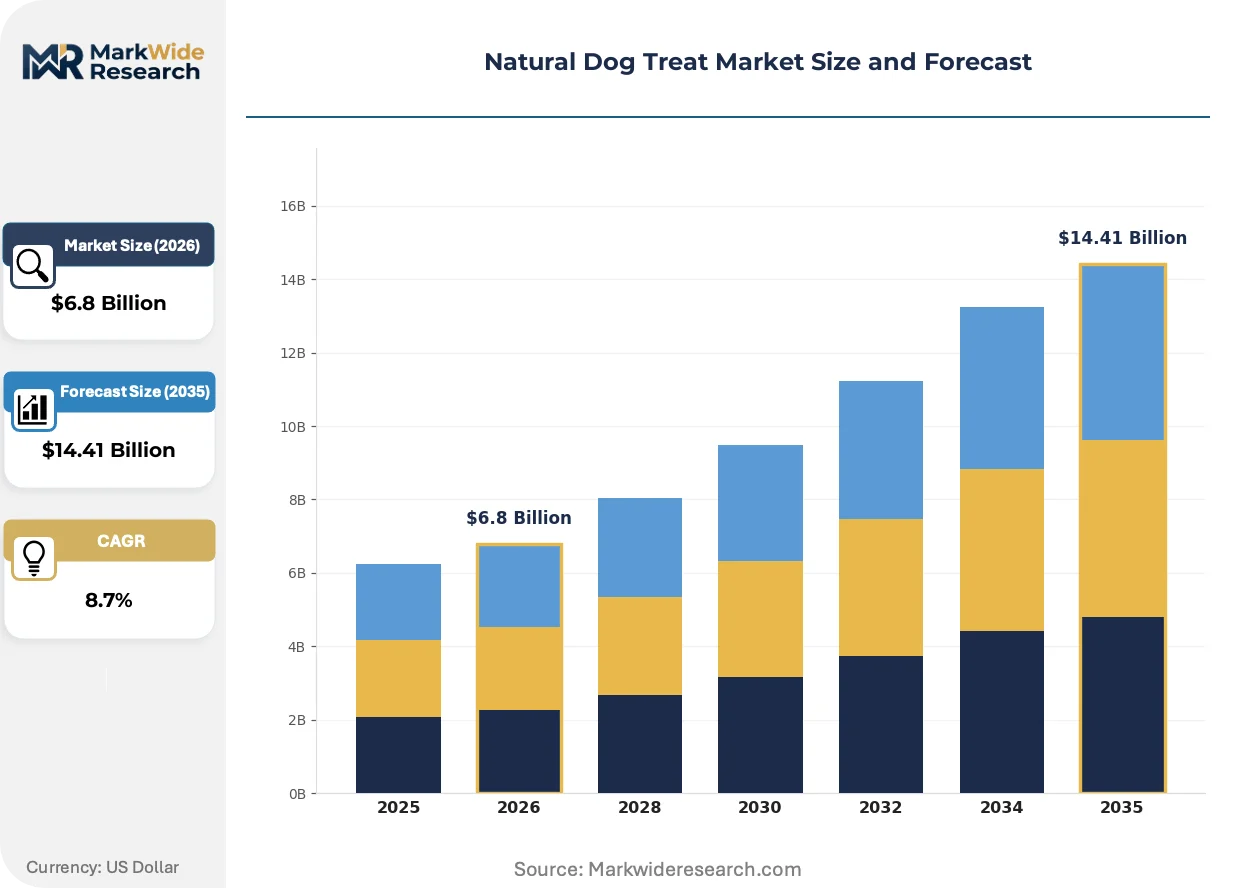
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biscuits, Jerky, Chews, Rawhide, Dental Treats Ingredient Source: Organic Vegetables, Free-Range Meat, Grain-Free, Gluten-Free, Non-GMO Application: Training Aid, Dental Health, Weight Management, Skin & Coat Care, Digestive Support Customer Type: Pet Specialty Stores, Online Retailers, Veterinarians, Supermarkets |
| Companies Covered | Mars Petcare, Nestlé Purina PetCare, Blue Buffalo Company, Wellness Pet Company, The J.M. Smucker Company, General Mills, Freshpet, Farmina Pet Foods, Stella and Chewy's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Dog Treat Market Trends and Innovations
Processing technology and regulatory transparency are converging to redefine what constitutes premium positioning, with functional claims now requiring substantiation through ingredient provenance rather than marketing narrative.
High-pressure processing is displacing traditional thermal pasteurization in raw treat manufacturing. Premium private-label suppliers serving boutique retailers have adopted HPP systems at accelerating rates since 2022. This non-thermal pathogen reduction method preserves raw nutritional integrity while satisfying FDA safety expectations, compressing the competitive gap between raw and conventional formats.
EFSA's expanded novel food assessments for insect proteins are reshaping European formulation roadmaps. The regulator's 2023 guidance on allergen labeling for crustacean-cross-reactive species forced reformulation of several black soldier fly product lines. German and Dutch manufacturers now lead in pre-submission safety dossiers, creating regulatory moats against faster-moving but less prepared competitors.
Pet humanization has compressed the quality gap between human snack and pet treat procurement standards. Millennial buyers now apply clean-label criteria—no artificial colors, single-source proteins, transparent supply chains—previously reserved for their own consumption. This behavioral shift is most visible in coastal US metropolitan markets where specialty pet boutiques have displaced mass retail for treat purchasing decisions.
Natural Dog Treat Market Segmentation
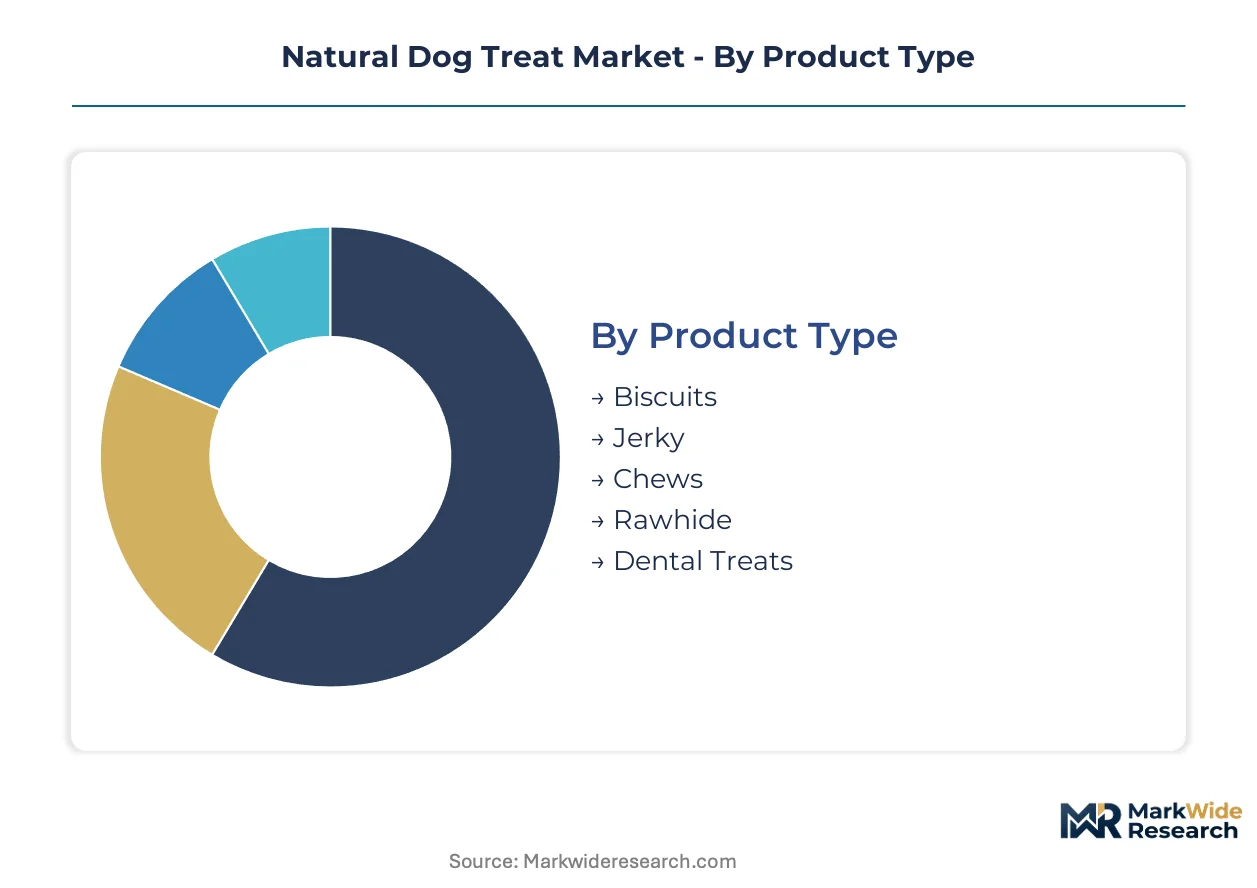
Segmentation in natural dog treats reveals how functional claims, ingredient provenance, and channel access create distinct margin pools. Manufacturers must align formulation investments with the specific compliance and sourcing requirements of each segment cluster.
Product Type:
Jerky and rawhide face the strongest substitution pressure from freeze-dried alternatives and novel protein formats, forcing incumbents to defend positioning through sourcing transparency.
- Biscuits:Baked formulations using single-source flours and cold-pressed oils serve mass-market rotation toward clean-label standards. Demand concentrates in supermarket channels where price-per-pound visibility drives trial.
- Jerky:Dehydrated muscle meat strips retain enzymatic activity through low-temperature processing. Coastal US metropolitan buyers prioritize grass-fed beef provenance, compressing margins for conventional feedlot sourcing.
- Chews:Long-duration consumption formats from free-range meat sources. Collagen-rich variants appeal to dental health positioning.
- Rawhide:Traditional hide-based chews face reformulation pressure from digestibility concerns and veterinary channel exclusion.
- Dental Treats:VOHC-recognized formulations with mechanical abrasion claims. Repeat purchase frequency anchors premium pricing.
Jerky retains volume leadership; chews hold the steepest expansion curve.
Ingredient Source:
Cost tier stratification separates certified organic inputs from conventional natural claims, with documentation infrastructure becoming the primary competitive filter.
- Organic Vegetables:USDA-certified produce inputs require full supply chain traceability from farm to finished good. Pet specialty stores in California and New York metro areas command shelf space premiums for verified organic SKUs.
- Free-Range Meat:Pasture-raised protein sourcing with third-party welfare verification. Input cost volatility from feed grain markets constrains formulation flexibility.
- Grain-Free:Legume and tuber-based carbohydrate replacements. FDA dilated cardiomyopathy investigations create label liability exposure.
- Gluten-Free:Celiac-sensitive positioning for owners with cross-contact concerns. Niche demand relative to broader grain-free.
- Non-GMO:Identity-preserved ingredient sourcing without full organic certification. Mid-tier pricing bridges conventional and organic tiers.
Grain-free retains volume leadership; free-range meat holds the steepest expansion curve.
Application:
Customer type concentration in veterinary channels elevates clinical substantiation requirements for functional positioning.
- Training Aid:Small-format, low-calorie pieces designed for high-frequency reward cycles. Online retailers capture bulk purchase behavior through subscription models.
- Dental Health:Mechanical cleaning claims supported by VOHC or equivalent third-party validation. Veterinary endorsement anchors premium pricing.
- Weight Management:Reduced-calorie density with fiber supplementation. Obesity-focused veterinary protocols drive professional recommendation.
- Skin & Coat Care:Omega fatty acid enrichment from fish oil or flaxseed. Breed-specific coat quality concerns concentrate demand in purebred owner segments.
- Digestive Support:Probiotic and prebiotic formulations with live culture stability requirements. Cold-chain considerations constrain retail distribution.
Dental health retains volume leadership; digestive support holds the steepest expansion curve.
Customer Type:
Geographic concentration of pet humanization behavior shapes channel-specific assortment requirements.
- Pet Specialty Stores:Curated assortments with staff consultation and ingredient education. Coastal US metros show highest basket values for premium treat categories.
- Online Retailers:Subscription mechanics and review-driven discovery reduce customer acquisition costs. Chewy and Amazon fulfillment infrastructure enables fresh and frozen format expansion.
- Veterinarians:Professional endorsement channels with clinical outcome claims. Mars Petcare's clinic partnerships demonstrate trust-anchored repeat purchase.
- Supermarkets:Mass-market penetration with price-promotional mechanics. Clean-label rotation lags specialty channels by 18-24 months.
Online retailers retain volume leadership; veterinarians hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US-based manufacturers dominate export flows into Canadian and Mexican retail channels, while European producers supply premium formulations to Middle Eastern and Asian markets through specialized pet distributors.
United States
Coastal metropolitan buyers in California and New York drive functional treat adoption with clean-label procurement standards. The FDA's Center for Veterinary Medicine enforces grain-free labeling requirements while investigating dilated cardiomyopathy correlations. Austin and Denver clusters host subscription-model startups targeting millennial pet owners with direct-to-consumer freeze-dried formats.
Germany
Discerning owners in Berlin and Munich prioritize organic-certified SKUs with full meat traceability documentation. EFSA's novel food assessments for insect proteins shape formulation roadmaps for black soldier fly-based products. Hamburg serves as the primary distribution hub for Nordic markets, with cold-chain logistics providers specializing in raw treat segments.
United Kingdom
London pet specialty boutiques anchor premium basket values for human-grade positioning and single-source protein claims. The Food Standards Agency coordinates with veterinary regulators on raw feeding safety protocols. Manchester-based processors concentrate on private-label manufacturing for supermarket own-brand natural treat lines.
Japan
Tokyo's aging pet demographic sustains demand for dental health formulations with VOHC-equivalent validation. METI guidelines on functional food claims extend to pet treat substantiation requirements. Osaka manufacturers lead in small-format training aid production for apartment-dwelling dog owners.
Australia
Sydney and Melbourne buyers demonstrate strong preference for free-range kangaroo and wild-caught fish protein sources. The Department of Agriculture enforces strict biosecurity protocols on imported meat-based inputs. Brisbane processing facilities specialize in dehydration technology for export markets across Southeast Asia.
Natural Dog Treat Market Competitive Landscape
Player mix skews toward diversified consumer packaged goods conglomerates with dedicated pet divisions, creating a tiered structure where veterinary-channel specialists command premium positioning against mass-market brands. Three archetypes dominate: multinational food conglomerates leveraging scale economies, mid-size specialists anchored in ingredient provenance narratives, and emerging direct-to-consumer brands built on subscription mechanics. Consolidation activity concentrates on acquiring freeze-drying technology capabilities, while partnership strategies prioritize veterinary clinic network access.
Among the diversified conglomerate tier, Mars Petcare and Nestlé Purina PetCare exemplify scale-driven archetypes with cross-category portfolio breadth. Blue Buffalo Company occupies a position within the ingredient-specialist segment, representing the free-range and limited-ingredient formulation approach. Wellness Pet Company sits within the science-backed functional claims tier, anchoring veterinary endorsement strategies.
| Leading Market Players |
|---|
| Mars Petcare |
| Nestlé Purina PetCare |
| Blue Buffalo Company |
| Wellness Pet Company |
| The J.M. Smucker Company |
| General Mills |
| Freshpet |
| Farmina Pet Foods |
| Stella and Chewy's |
| Others |
Pricing and Supply Chain Analysis
Freeze-dried protein substitution for conventional baked formulations simultaneously relocates manufacturing gravity toward Germany and Italy's equipment clusters and compresses margin structures for processors lacking captive dehydration infrastructure. Coastal US buyers absorb transport premiums for European-sourced machinery while demanding domestic ingredient provenance, creating bifurcated cost stacks that stratify competitive positioning.
Pricing Analysis
Three-tier pricing structure across premium freeze-dried, standard dehydrated, and economy baked levels anchors the market, with USDA organic certification and veterinary channel endorsement as the primary price differentiation drivers. Pricing pressure stems from free-range protein input volatility as feed grain markets fluctuate, compressing margins for mid-tier natural claims. Mass-market supermarket buyers exhibit highest price sensitivity, while veterinary channel purchasers demonstrate lowest elasticity due to clinical trust anchoring.
Supply Chain Analysis
Inbound logistics costs from Hamburg and Rotterdam port congestion ripple through North American processors dependent on German freeze-dryer imports, elevating capital expenditure timelines. Supply concentrates in the United States for formulation and packaging, Australia for free-range kangaroo and wild-caught fish proteins, and Germany for dehydration equipment manufacturing. Raw material dependencies center on pasture-raised poultry, grass-fed beef, and black soldier fly larvae. Single-source vulnerability in European equipment sourcing creates structural risk. Distribution runs through pet specialty boutiques in coastal metros, subscription direct-to-consumer platforms, and veterinary clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment services attach recurring revenue layers expanding faster than single-transaction treat sales, with Chewy and Amazon's auto-delivery mechanics building predictable lifetime value from initially hardware-like product trials.
For Market Incumbents: Secure exclusive veterinary channel partnerships before Mars Petcare's clinic network reaches saturation density, and acquire freeze-drying technology capabilities to defend against raw-format entrants. Ingredient-specialist mid-caps with certified organic supply chains represent the primary acquisition threat, while backward integration into pasture-raised protein sourcing offers margin protection against feed grain volatility. For New Entrants and Emerging Players: Digestive support formulation gaps where incumbents under-serve probiotic stability requirements offer the most penetrable white-space target, particularly in refrigerated direct-to-consumer channels bypassing conventional retail warehousing. California and New York metro pet specialty boutiques concentrate early-adopter demand for novel protein formats. Launch through veterinary endorsement programs rather than mass retail placement to anchor premium positioning from inception. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ingredient-provenance specialists possessing USDA organic infrastructure but lacking veterinary channel scale. Long-term viability across the analysis window hinges on regulatory navigation capacity as FDA grain-free scrutiny intensifies. Acquisition targets should demonstrate freeze-drying technology ownership or exclusive black soldier fly protein supply agreements. The signal to watch is state-level raw-feeding restriction passage, which would force portfolio reformulation and channel access recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Mars Petcare's clinic network demonstrates how professional endorsement anchors consumer trust and repeat purchase behavior. |
| Freeze-Drying Technology Acquisition | German and Italian equipment concentration creates regulatory moats for processors with captive dehydration infrastructure. |
| Subscription Direct-to-Consumer Launch | Chewy and Amazon fulfillment mechanics reduce customer acquisition costs and build predictable revenue streams. |
| California Proposition 12 Compliance | Stricter confinement standards create first-mover advantage for brands already sourcing pasture-raised inputs. |
| Insect Protein Formulation Development | EFSA's expanded novel food assessments reshape European roadmaps and filter out unprepared competitors. |
Research Methodology
A spread of perspectives from brand managers at diversified pet food conglomerates, category buyers at pet specialty retailers, veterinary clinic procurement leads, and supply planners at freeze-dried protein processors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation from FDA Center for Veterinary Medicine guidance documents, USDA organic certification databases, AAFCO nutrient profile publications, and Nielsen retail audit data. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates.
Segmentation dimensions modeled span product type, ingredient source, application, and customer type across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Industry-specific forecast inputs incorporated FDA dilated cardiomyopathy investigation timelines and EFSA novel food assessment pipelines.
Material uncertainties — regulatory reformulation mandates, feed grain price shocks, and veterinary channel consolidation — sit outside the modeled envelope. Forecasts reflect documented assumptions about clean-label procurement trend persistence and freeze-drying technology diffusion rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Hotels Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Dog Food Market
Pet Care Products
US Pet Treats Market
Pet Care Products
Canada Pet Boarding Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Pet Cups Market
Pet Care Products
Dog Brush Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Small Breed Dog Food Market
Pet Care Products
Aquarium Market
Pet Care Products
Pet Pens Market
Pet Care Products
Pet Care E-Commerce Market
Pet Care Products
Weight Management Dog Food Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
Fresh and Frozen Dog Food Market