
 Pet Odor Absorber Market | 2026-2036
Pet Odor Absorber Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Odor Absorber Market Analytics
Asset-light contract manufacturing and private-label leasing arrangements is tilting competitive dynamics toward brands that outsource production while controlling formulation IP. Nature's Miracle leverages proprietary enzymatic technology to sustain premium positioning in enzymatic odor elimination. Arm & Hammer competes through backward integration into baking soda supply, anchoring cost advantages across mass retail channels. Rocco & Roxie specializes in concentrated professional-grade formulations, differentiating through veterinary clinic endorsements.
Pet odor absorbers comprise porous or reactive media—activated carbon, sodium bicarbonate, clinoptilolite zeolite, or terpene-rich essential oil blends—engineered to adsorb, neutralize, or mask malodorous volatile organic compounds from pet urine, feces, and dander in enclosed spaces. These products serve residential, commercial grooming, and clinical environments where air quality standards intersect with animal welfare protocols. Activated carbon formulations lead product type revenue due to superior adsorption capacity for sulfur and nitrogen-based odorants, while essential oil blends represent the fastest-expanding segment as pet owners seek non-synthetic alternatives. Professional grooming applications command higher per-unit margins than home use, reflecting bulk procurement patterns and compliance with OSHA ventilation standards in commercial settings.
EPA regulations on indoor air quality and VOC emissions constrain synthetic fragrance formulations, compelling reformulation toward GRAS-designated essential oil compounds. FDA oversight of veterinary clinic sanitation products, combined with state-level California Air Resources Board requirements, shapes product registration and labeling obligations for manufacturers targeting clinical channels. Stakeholders must monitor evolving state-by-state chemical disclosure mandates and the trajectory of USDA BioPreferred program eligibility for plant-derived odor control products.
Market Dynamics
EPA guidelines on volatile organic compound emissions are forcing manufacturers to abandon synthetic fragrance bases and rebuild supply chains around GRAS-designated essential oil compounds. This regulatory compression is accelerating consolidation among formulators lacking botanical extraction capabilities.
Growth Catalysts
- Multi-pet household density:Residential environments with three or more animals generate sulfur and nitrogen-based odorant loads that exceed passive ventilation capacity. These households purchase activated carbon formulations at triple the rate of single-pet homes.
- OSHA ventilation standards:Commercial grooming facilities in the United States face mandatory air exchange requirements that professional-grade odor absorbers satisfy more cost-effectively than mechanical system upgrades.
- USDA BioPreferred eligibility:Plant-derived odor control products gaining federal procurement preference are opening institutional channels previously locked to petroleum-based competitors.
Market Restraints
- Coconut shell activated carbon supply:Philippine and Indonesian export restrictions on raw carbon feedstock are creating input cost volatility for adsorption-based formulations.
- Zeolite mining concentration:Clinoptilolite deposits in Turkey and the United States control over seventy percent of global supply, exposing formulators to geographic concentration risk.
- Essential oil oxidation stability:Terpene-rich botanical bases degrade within twelve months of formulation, limiting shelf life and distribution radius compared to synthetic alternatives.
Strategic Opportunities
- Veterinary clinic sanitation mandates:FDA oversight of clinical environments is expanding the addressable market for registered disinfectant-odorant combination products beyond retail channels.
- California Air Resources Board requirements:State-level chemical disclosure mandates are creating first-mover advantage for manufacturers with transparent supply chain documentation.
- Subscription replenishment models:Direct-to-consumer channels with automated reorder algorithms are capturing recurring revenue from premium pet owners seeking convenience.
Industry Challenges
- Enzymatic formulation stability:Maintaining protease and lipase activity through temperature fluctuations during shipping requires cold chain infrastructure that strains working capital.
- GRAS certification timelines:FDA review periods for novel essential oil combinations extend eighteen to twenty-four months, delaying product launches and compressing effective patent life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Odor Absorber Market |
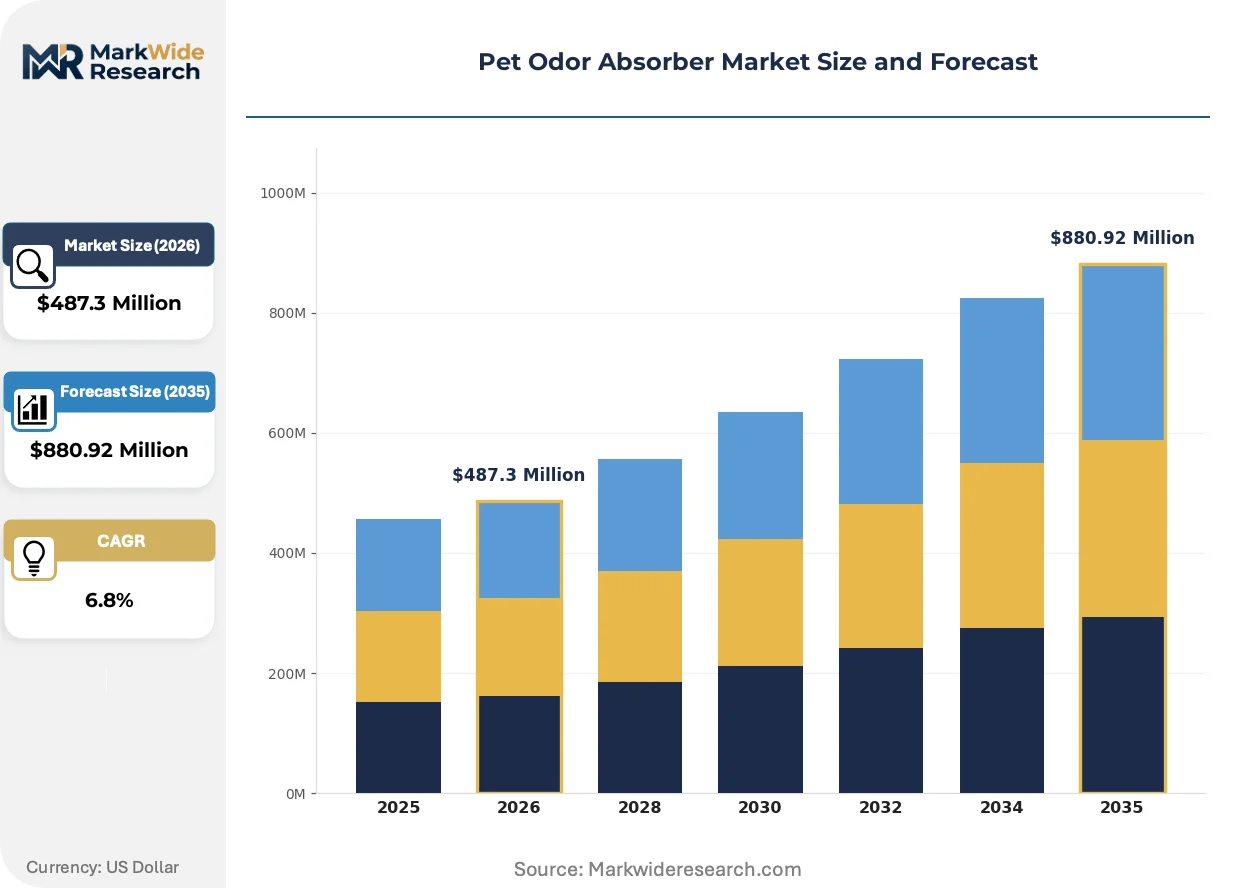
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Baking Soda, Zeolite, Essential Oils Application: Home Use, Professional Grooming, Veterinary Clinics, Car Interiors End User: Pet Owners, Pet Care Professionals, Animal Shelters, Retail Stores Distribution Channel: Online Retail, Pet Specialty Stores, Supermarkets, Wholesale Distributors |
| Companies Covered | Nature's Miracle, Febreze, Simple Solution, Angry Orange, Rocco & Roxie, Zero Odor, Arm & Hammer, OUT! Pet Care, Biokleen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Odor Absorber Market Evolving Landscape
Formulation chemistry is bifurcating between high-adsorption mineral media and bioactive enzymatic systems, with regulatory pressure eliminating the synthetic middle ground. This technological polarization is reshaping R&D allocation and manufacturing asset requirements.
Enzymatic odor elimination technology is collapsing the performance gap between chemical masking and biological decomposition. Professional grooming chains are adopting concentrated protease-lipase blends at accelerating rates. The technology is collapsing demand for baking soda-based neutralizers in commercial settings by delivering permanent odor source elimination rather than temporary pH adjustment.
REACH authorization requirements for synthetic fragrance precursors are restricting import of phthalate-based odor masking compounds into European Union markets. Manufacturers are reformulating product lines to exclude Substances of Very High Concern. Veterinary clinic channels across Germany and France are switching to essential oil formulations ahead of mandatory compliance deadlines.
Subscription-based replenishment programs are displacing retail shelf purchasing among premium pet owners. Direct-to-consumer platforms with algorithm-driven reorder cycles are capturing recurring revenue from households with multiple animals. This channel shift is most visible in United States metropolitan markets where same-day delivery infrastructure supports consumable replenishment at scale.
Pet Odor Absorber Market Segmentation
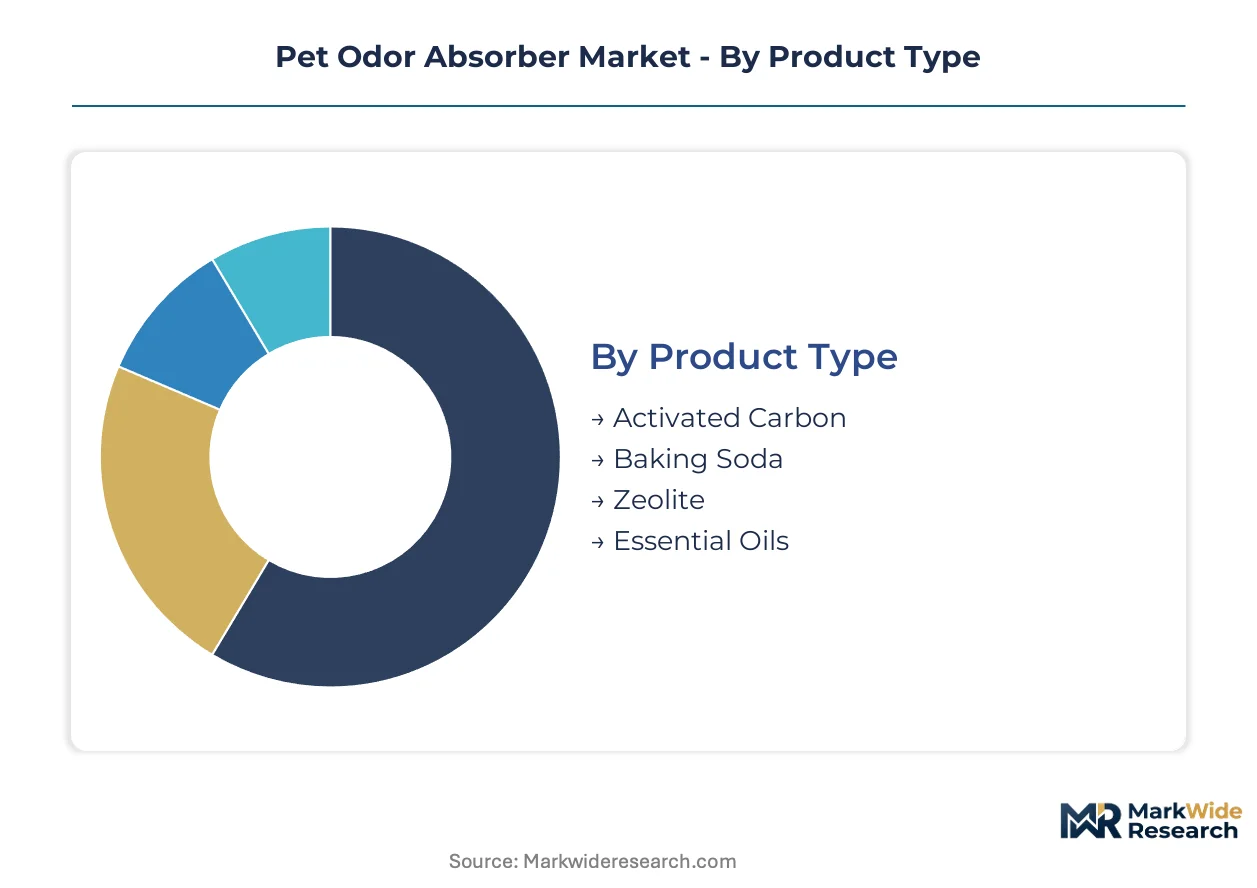
Pet odor absorber manufacturers configure product portfolios across four distinct segmentation axes. Each dimension reveals divergent margin structures, regulatory exposure, and channel access requirements that shape competitive positioning.
Product Type:
Cost tier determines raw material sourcing strategy and manufacturing asset intensity across formulation categories.
- Activated Carbon:Porous carbonaceous media derived from coconut shell or coal feedstock delivers superior adsorption capacity for sulfur and nitrogen-based odorants. Demand concentrates in multi-pet households across the United States where passive ventilation proves inadequate for high odorant loads. Philippine and Indonesian export restrictions on raw carbon feedstock create input cost volatility that compresses margins for non-integrated formulators.
- Essential Oils:Terpene-rich botanical formulations from plant-derived sources address EPA volatile organic compound constraints. Professional grooming facilities in California and New York rotate toward these formulations fastest due to Air Resources Board disclosure mandates and OSHA ventilation compliance requirements. Oxidation stability limits shelf life to twelve months, constraining distribution radius compared to mineral alternatives.
- Baking Soda:Sodium bicarbonate-based neutralizers leverage pH adjustment chemistry for temporary odor masking in residential applications.
- Zeolite:Clinoptilolite mineral structures from Turkish and United States deposits provide ion-exchange odor capture for enclosed spaces.
Activated carbon holds installed capacity. Essential oils is rotating up the share rankings.
Application:
Customer environment dictates performance specifications, purchase frequency, and compliance documentation requirements.
- Professional Grooming:Commercial facilities require concentrated formulations meeting OSHA ventilation standards and bulk procurement economics. Chains across the United States adopt enzymatic systems at accelerating rates to avoid mechanical system upgrade costs. FDA oversight of sanitation protocols expands addressable market for registered disinfectant-odorant combination products beyond retail channels.
- Veterinary Clinics:Clinical environments demand products satisfying FDA sanitation mandates and state-level chemical disclosure requirements. Premium per-unit margins reflect compliance documentation and veterinary endorsement value. California and Texas veterinary networks drive specification standards that cascade to regional competitors.
- Home Use:Residential consumers prioritize convenience and subscription replenishment models in metropolitan United States markets.
- Car Interiors:Enclosed vehicle applications favor compact, spill-resistant formats for pet transport scenarios.
Professional grooming holds installed capacity. Veterinary clinics is rotating up the share rankings.
End User:
Volume concentration and procurement authority separate institutional buyers from dispersed residential purchasers.
- Pet Care Professionals:Groomers, trainers, and boarding operators purchase concentrated formulations through wholesale distributors with volume-based pricing. OSHA compliance requirements and insurance liability standards professionalize procurement decisions. United States metropolitan markets show fastest adoption of subscription replenishment models among this cohort.
- Animal Shelters:Municipal and non-profit facilities operate under constrained budgets with high-throughput odor control needs. USDA BioPreferred program eligibility opens federal procurement channels previously locked to petroleum-based competitors. Shelter networks in California and Florida set specification standards for regional adoption.
- Pet Owners:Residential consumers drive retail and direct-to-consumer channel development.
- Retail Stores:Pet specialty and mass retail operators influence shelf placement and private-label development.
Pet care professionals hold installed capacity. Animal shelters is rotating up the share rankings.
Distribution Channel:
Channel selection determines margin capture, customer data access, and replenishment cadence control.
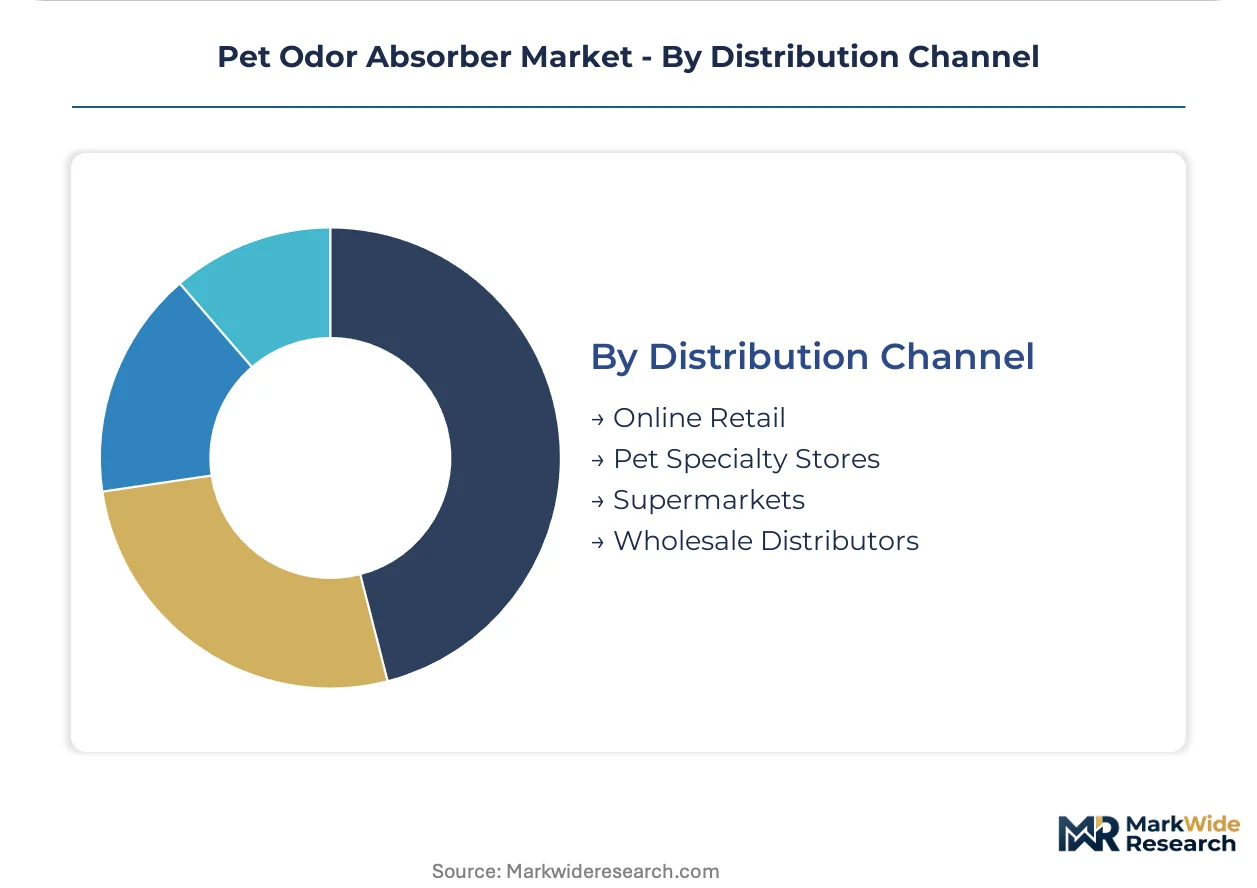
- Online Retail:Direct-to-consumer platforms with algorithm-driven reorder cycles capture recurring revenue from premium pet owners. Same-day delivery infrastructure in United States metropolitan markets supports consumable replenishment at scale. Subscription models displace retail shelf purchasing among multi-pet households seeking convenience.
- Pet Specialty Stores:Independent and chain retailers provide formulation education and veterinary endorsement leverage. Staff recommendation authority sustains premium pricing for enzymatic and essential oil formulations. Regional chains in Texas and Florida compete on exclusive product access.
- Supermarkets:Mass retail channels favor baking soda-based formats with established consumer recognition and price positioning.
- Wholesale Distributors:Bulk procurement intermediaries serve professional grooming and veterinary clinic segments with volume logistics.
Pet specialty stores hold installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pet care spending concentrates in the United States, where multi-pet household density and veterinary clinic standards drive formulation demand. Professional grooming chains and subscription replenishment models anchor volume in metropolitan markets.
United States
California and Texas veterinary networks set specification standards that cascade to regional competitors. EPA volatile organic compound guidelines and OSHA ventilation standards constrain synthetic fragrance formulations while accelerating essential oil adoption. Los Angeles and New York metropolitan areas lead subscription replenishment model penetration among multi-pet households.
Germany
REACH authorization requirements for synthetic fragrance precursors restrict phthalate-based odor masking compound imports. Veterinary clinic channels across Germany switch to essential oil formulations ahead of mandatory compliance deadlines. Berlin and Munich grooming chains adopt enzymatic systems to avoid mechanical ventilation upgrade costs.
United Kingdom
Pet specialty retail consolidation in London and Southeast England drives private-label development and formulation education investments. ECHA oversight of chemical disclosure shapes product registration obligations for clinical channel entrants. Manchester and Birmingham distribution hubs service professional grooming networks with concentrated bulk formulations.
France
ANSM sanitation mandates for veterinary clinical environments expand addressable market for registered disinfectant-odorant combinations. Paris and Lyon metropolitan areas concentrate premium pet owner spending and direct-to-consumer platform adoption. Provence-Alpes-Côte d'Azur region supplies terpene-rich botanical feedstock for essential oil formulations.
Japan
METI energy efficiency standards for commercial grooming facilities favor passive odor control solutions over mechanical ventilation upgrades. Tokyo and Osaka veterinary clinic chains drive specification standards for enzymatic and mineral-based formulations. Kansai region distribution networks service high-density multi-pet households with compact activated carbon formats.
Pet Odor Absorber Market Competitive Landscape
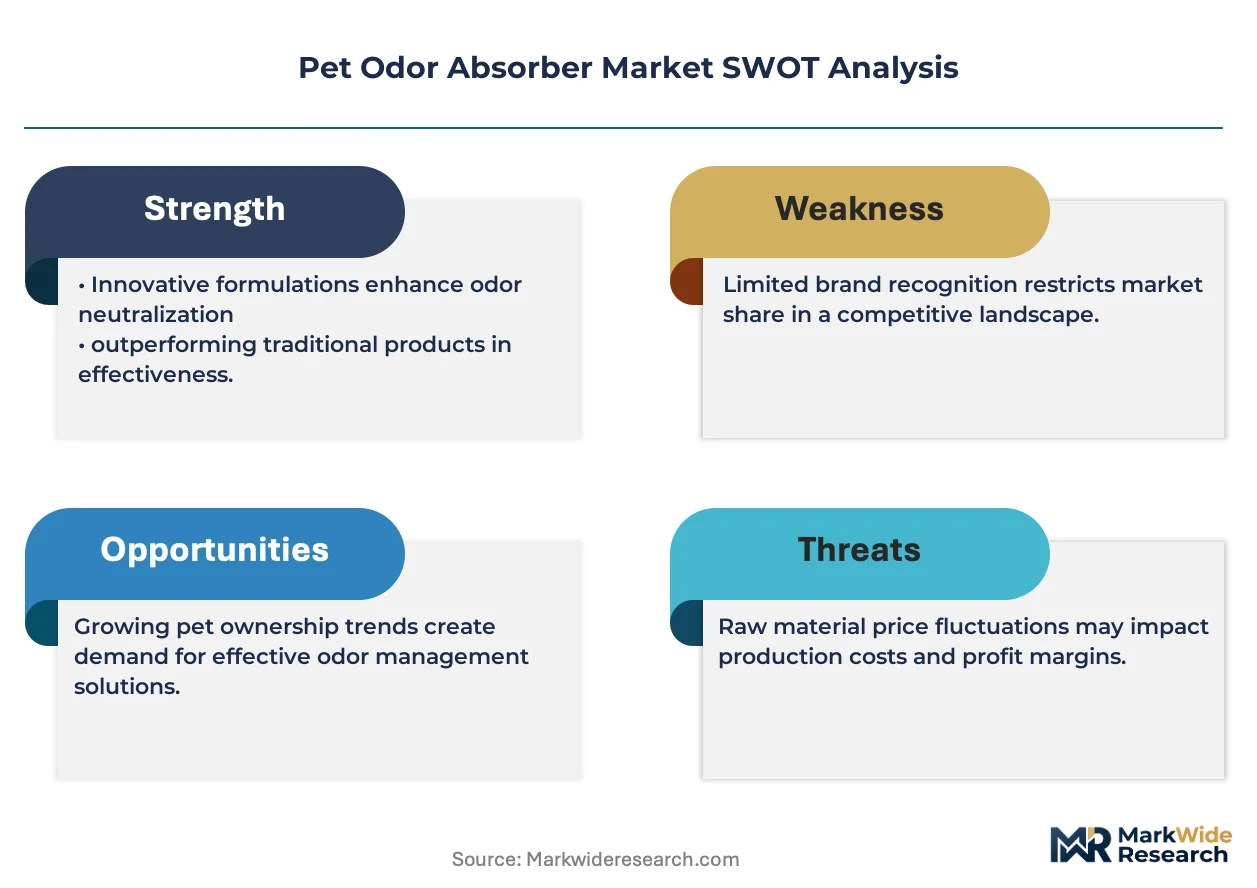
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mass retail anchoring and veterinary endorsement networks define two distinct competitive vectors. Strategic archetypes include backward-integrated mineral feedstock controllers, enzymatic technology specialists, and private-label contract manufacturers. Dominant competitive moves encompass subscription platform development and formulation IP licensing arrangements.
Among established brand anchors, Nature's Miracle occupies a position within the enzymatic technology tier, while Arm & Hammer exemplifies mineral feedstock integration. Rocco & Roxie represents the veterinary endorsement specialist archetype. These three companies collectively illustrate the competitive polarization between bioactive decomposition systems and mineral adsorption platforms.
| Leading Market Players |
|---|
| Nature's Miracle |
| Febreze |
| Simple Solution |
| Angry Orange |
| Rocco & Roxie |
| Zero Odor |
| Arm & Hammer |
| OUT! Pet Care |
| Biokleen |
| Others |
Value Network & Pricing Analysis
Philippine and Indonesian coconut shell carbon clusters anchor global adsorption media capacity, with export quota restrictions translating directly into input cost volatility that squeezes non-integrated formulators and forces premium tier separation.
Pricing Analysis
Certification level creates the primary spread, with FDA-registered disinfectant-odorant combinations commanding substantial premiums over unregistered retail formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation chemistry and veterinary endorsement intensity. Cost compression in activated carbon tiers is intensifying because Philippine export licensing delays extend raw material lead times. Animal shelter procurement teams exhibit highest price sensitivity due to municipal budget constraints, while veterinary clinic buyers prioritize compliance documentation over unit economics.
Supply Chain Analysis
Contract manufacturing concentration rests with asset-light formulators in the United States and Mexico serving private-label clients, while integrated players in Turkey control captive clinoptilolite zeolite mining. Raw material dependencies draw from Southeast Asian coconut shell carbon, Turkish mineral deposits, and Provence-Alpes-Côte d'Azur botanical terpene feedstocks. Single-source vulnerability in Philippine carbon exports exposes formulators to abrupt quota restrictions. Distribution runs through wholesale distributors for professional grooming and veterinary segments, with direct-to-consumer platforms capturing premium household replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation IP scarcity around GRAS-certified essential oil combinations and cold-chain enzymatic stability separates viable competitors from commodity players in this market.
For Market Incumbents: Pre-empt regulatory compression by accelerating backward integration into botanical extraction capabilities before GRAS certification timelines extend further. Secure Turkish clinoptilolite offtake agreements to hedge against mineral supply concentration. Channel control through veterinary endorsement networks provides defensive moats against direct-to-consumer enzymatic specialists. For New Entrants and Emerging Players: Build out subscription replenishment infrastructure targeting United States metropolitan multi-pet households, the most penetrable segment given established same-day delivery density. Animal shelter procurement channels offer white-space access through USDA BioPreferred program eligibility. Go-to-market execution should leverage algorithm-driven reorder cycles to capture recurring revenue before incumbent brand loyalty solidifies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic technology specialists with demonstrated protease-lipase stability through temperature fluctuation. Long-term viability hinges on formulation chemistry polarization eliminating synthetic middle-ground competitors. Acquisition targets should display veterinary clinic registration pipelines and transparent supply chain documentation for California Air Resources Board compliance. Monitor FDA GRAS review queue length as inflection indicator for essential oil formulation launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GRAS Certification Investment | FDA review completion accelerates essential oil product launches ahead of REACH compliance deadlines. |
| Backward Integration into Botanical Extraction | In-house terpene sourcing secures supply chain against Philippine carbon export volatility. |
| Veterinary Clinic Registration Pipeline | FDA sanitation mandate compliance opens institutional channels beyond retail shelf competition. |
| Subscription Platform Development | Algorithm-driven reorder cycles capture recurring revenue from premium multi-pet households. |
| Turkish Zeolite Supply Agreement | Clinoptilolite offtake contracts hedge geographic concentration risk in mineral feedstock. |
Research Methodology
Desk research of EPA enforcement actions, FDA GRAS notification databases, and OSHA ventilation standard amendments preceded structured interviews with formulation chemists, veterinary procurement managers, professional grooming chain operators, and contract manufacturing executives. Secondary validation drew from customs import records for coconut shell carbon, USDA BioPreferred program eligibility lists, and state-level chemical disclosure filings. Bottom-up volume estimates triangulated against top-down spending analysis across residential, commercial grooming, and clinical application segments.
Assumptions held fixed include regulatory trajectory for volatile organic compound emissions and OSHA ventilation standard enforcement intensity across the analysis window. Segmentation dimensions modeled encompass product type chemistry, application environment compliance requirements, end-user procurement authority, and distribution channel margin capture. CAGRs derived from historical premium pet care spending elasticity and multi-pet household formation rates, with enzymatic technology adoption curves and essential oil oxidation stability constraints as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-label contract manufacturers or enzymatic technology licensors would shift outcomes beyond projected ranges. Quarterly review of FDA GRAS review queue length, Philippine coconut shell carbon export licensing velocity, and California Air Resources Board disclosure mandate expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
Germany Pet Clothing Market
Pet Care Products
United Kingdom Pet Food Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
South America Pet Food Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
China Pet Food Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Bird Cages and Accessories Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
Weight Management Dog Food Market
Pet Care Products
Japan Dog Food Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Europe Pet Smart Tracker Market
Pet Care Products
Netherlands Pet Food Market