
 Pet Clean-Up and Odor-Control Products Market | 2026-2036
Pet Clean-Up and Odor-Control Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Clean-Up and Odor-Control Products Market Analytics
The capital-intensity divergence between mass-market incumbents and emerging natural-formulation specialists is bifurcating competitive returns in pet clean-up products. The Procter & Gamble Company leverages its household products infrastructure to sustain national distribution density at thin margins. Church & Dwight Co., Inc. anchors its position through Arm & Hammer brand recognition in odor-neutralization chemistry. Rocco & Roxie Supply Co. differentiates via concentrated enzymatic formulations and direct-to-consumer channel control.
Pet clean-up and odor-control products encompass enzymatic, surfactant-based, and absorbent formulations engineered to degrade organic waste compounds and neutralize volatile malodors from urine, feces, and dander on household surfaces and textiles. These products serve commercial and residential end-users by restoring hygienic conditions, preserving flooring and fabric integrity, and satisfying olfactory standards in human-pet cohabitation spaces. Spray-format odor eliminators dominate unit velocity in retail channels while enzymatic stain removers capture expanding margin pools as pet owners prioritize efficacy over price. Waste bags in compostable substrates represent the fastest-growing product type as municipal organic waste diversion mandates proliferate across California, Washington, and Oregon municipalities.
EPA Safer Choice certification and state-level VOC restrictions in California under CARB shape permissible ingredient panels and labeling requirements for household chemical products sold to pet owners. The USDA BioPreferred program and emerging state compostability standards for plastic alternatives create dual compliance pathways that favor suppliers with verified biodegradable supply chains. Stakeholders must monitor pending FTC Green Guides revisions and municipal extended producer responsibility frameworks for pet waste packaging to anticipate compliance cost reallocations.
Market Dynamics
Enzymatic biodegradation chemistry is displacing legacy surfactant formulations as EPA Safer Choice certification and state-level VOC restrictions in California under CARB tighten permissible ingredient panels for household chemical products.
Growth Catalysts
- Multi-pet household expansion:Deepening pet humanization drives disproportionate consumption velocity for specialized odor-neutralization and stain-removal formulations.
- CARB VOC regulations:California's stringent volatile organic compound limits accelerate reformulation investments toward low-emission enzymatic alternatives.
- Compostable substrate innovation:Municipal organic waste diversion mandates in California, Washington, and Oregon create pull-through demand for certified biodegradable waste bags.
Market Restraints
- Enzyme stability costs:Temperature-sensitive biocatalysts require cold-chain logistics and specialized packaging that elevates unit economics above surfactant baselines.
- Supply concentration in Southeast Asia:Bulk enzyme production clusters in contract fermentation facilities across Thailand and Indonesia, creating single-source vulnerability.
- Performance perception gaps:Consumer skepticism toward enzymatic efficacy on set-in stains limits trial conversion despite laboratory validation data.
Strategic Opportunities
- Veterinary clinic channel penetration:Professional endorsement protocols and bulk dispensing systems remain underdeveloped relative to retail saturation.
- USDA BioPreferred procurement tailwinds:Federal purchasing mandates for biobased products create institutional demand pools in military housing and government facilities.
- Sensor-integrated dispensing systems:Convergence of IoT odor detection hardware with automated treatment release enables subscription-based service models.
Industry Challenges
- FTC Green Guides compliance timeline:Pending revisions to environmental marketing standards create labeling uncertainty and require defensive claim substantiation investments.
- Enzymologist formulation talent scarcity:Specialized biochemistry expertise for pet-specific waste degradation remains concentrated in agricultural biotechnology sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Clean-Up and Odor-Control Products Market |
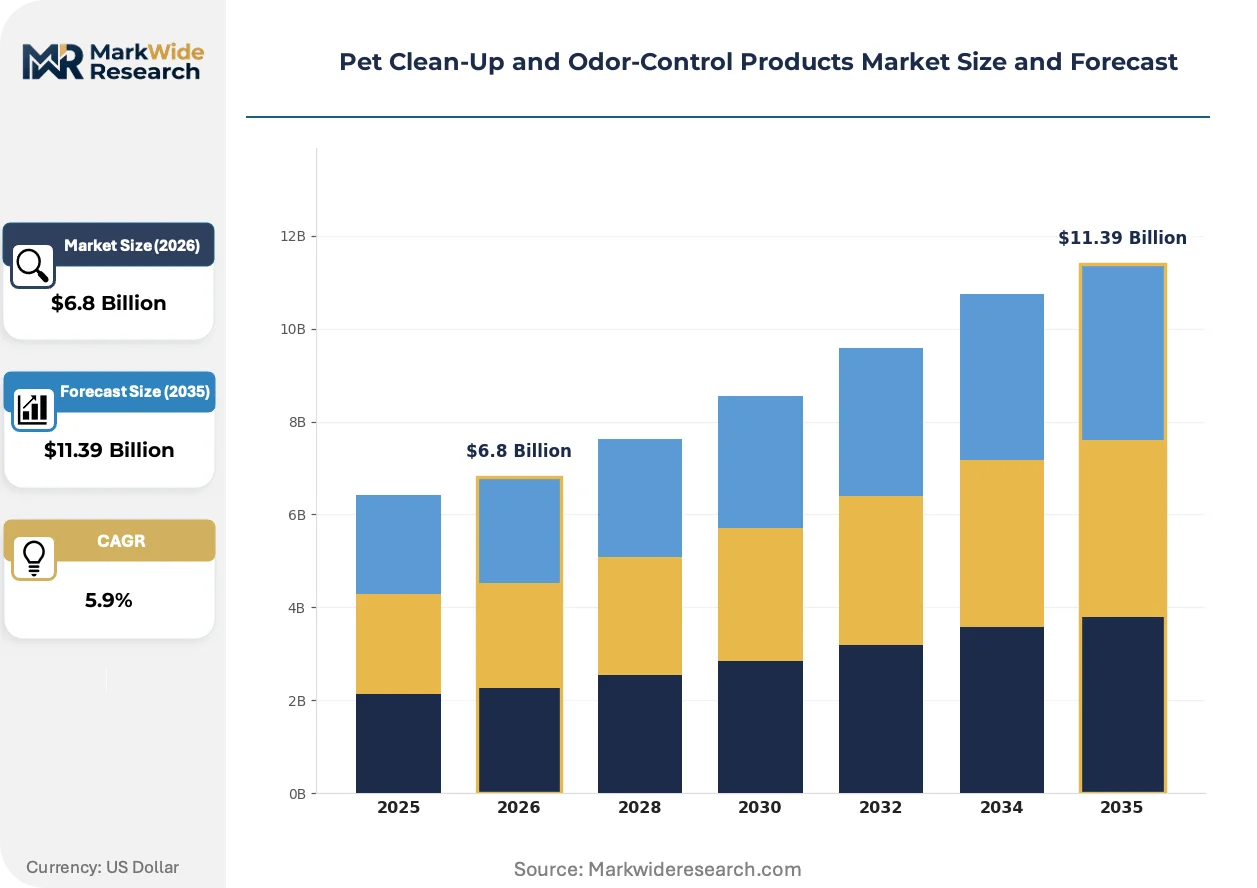
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stain Removers, Odor Eliminators, Waste Bags, Litter Boxes Form: Spray, Powder, Granule, Wipe Application: Indoor, Outdoor, Car, Travel Customer Type: Pet Owners, Veterinarians, Pet Stores, Groomers |
| Companies Covered | The Procter & Gamble Company, Spectrum Brands, Inc., Church & Dwight Co., Inc., The Clorox Company, Rocco & Roxie Supply Co., BISSELL Inc., Ecolab Inc., SC Johnson, Betco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Clean-Up and Odor-Control Products Market Evolving Landscape
Formulation science and regulatory compliance frameworks are converging to reshape product architecture, with biodegradability verification and direct-to-consumer channel control emerging as the primary axes of competitive differentiation.
Probiotic and enzymatic cleaning systems is supplanting quaternary ammonium compound disinfectants in premium pet care applications. Multi-pet households and veterinary facilities are accelerating adoption of these living-culture formulations. This biological approach is supplanting chemical residual toxicity concerns with continuous microbial competition that extends efficacy windows between applications.
REACH substance restriction candidate list expansions in Europe and pending EPA TSCA Section 6 restrictions on per- and polyfluoroalkyl substances are forcing reformulation of stain-resistant coatings and moisture barriers in pet accessory textiles. Manufacturers serving EU and US markets simultaneously face divergent compliance timelines that favor centralized formulation platforms with regional variant production.
Subscription-based replenishment models are capturing recurring revenue pools previously dominated by impulse retail purchases. Chewy and direct-to-consumer specialists are disintermediating mass-market shelf space allocation decisions. This channel migration concentrates most visibly in enzymatic concentrate refills and compostable waste bag auto-ship programs across coastal metropolitan markets.
Pet Clean-Up and Odor-Control Products Market Segmentation
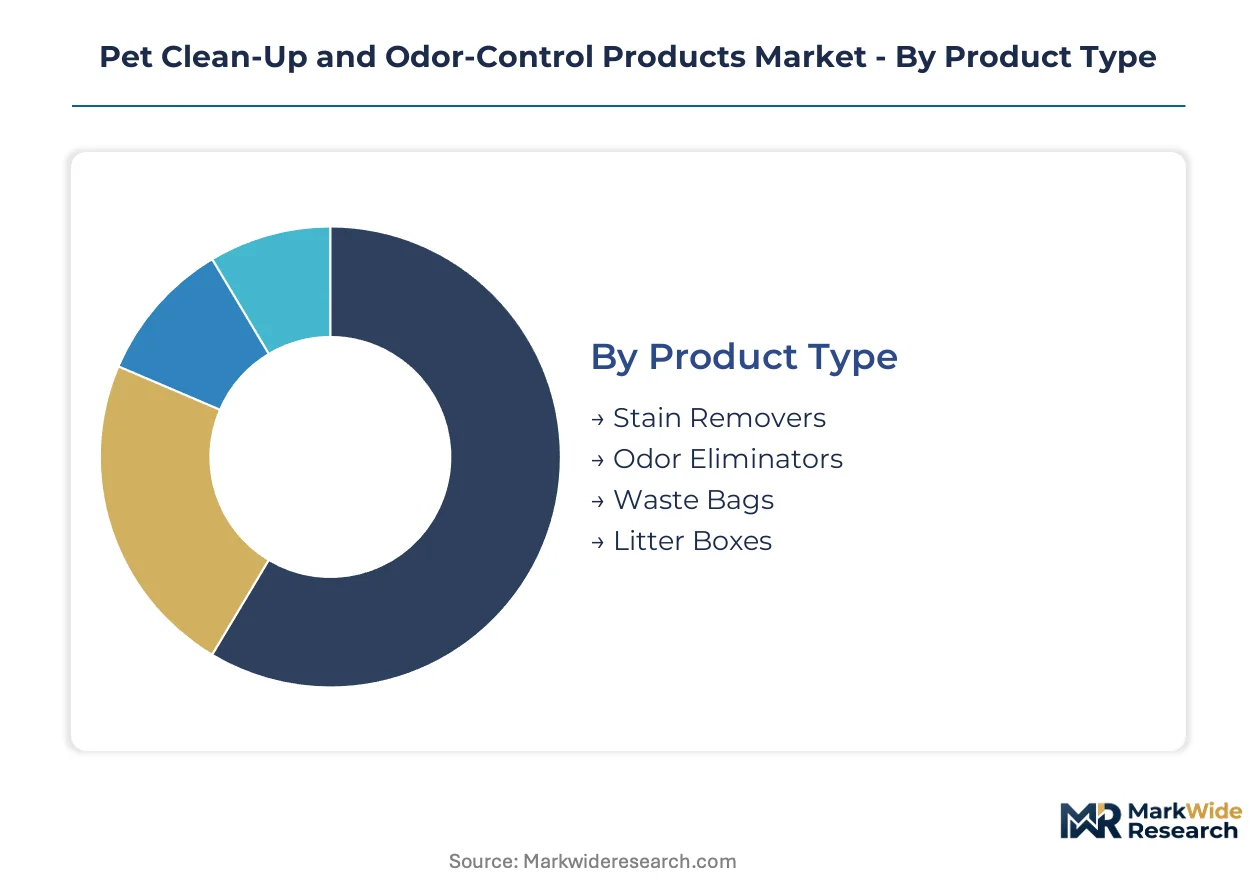
Segmentation in pet clean-up products reveals how enzymatic chemistry, substrate innovation, and channel specialization create divergent margin structures across otherwise similar functional categories. Understanding these fault lines exposes where formulation investments concentrate and which customer relationships command pricing power.
Product Type:
Stain removers face the most acute substitution pressure from DIY home remedies and dilutable concentrates that erode brand loyalty through cost arbitrage.
- Stain Removers:Enzymatic formulations incorporating bacterial cultures and proteolytic enzymes break down uric acid crystals and organic proteins in carpet fibers and upholstery. Multi-pet households in suburban United States markets drive disproportionate velocity for concentrated pretreatment sprays that require dwell time before extraction.
- Odor Eliminators:Volatile organic compound-compliant spray formats deploy cyclodextrin encapsulation or zinc-based neutralization chemistry to bind malodor molecules rather than masking them. CARB regulatory thresholds in California and Washington compel reformulation away from legacy fragrance-heavy approaches toward verified zero-VOC certification.
- Waste Bags:Compostable substrates certified to ASTM D6400 or BPI standards displace conventional polyethylene in municipal organic waste diversion zones across Portland, Seattle, and San Francisco metropolitan areas.
- Litter Boxes:Self-cleaning mechanical systems and disposable lined trays reduce manual scooping frequency for urban apartment dwellers with space constraints.
Odor eliminators retain volume leadership; waste bags hold the steepest expansion curve.
Form:
Spray formats concentrate margin capture through subscription replenishment models, while powder and granule alternatives compete on per-use cost efficiency in bulk commercial applications.
- Spray:Trigger-dispensed liquid formulations dominate retail shelf space and direct-to-consumer auto-ship programs through Chewy and Amazon Subscribe & Save. Fine-mist nozzle engineering ensures even coverage on vertical surfaces and fabric weaves without oversaturation damage.
- Powder:Absorbent clay and diatomaceous earth blends target carpet deodorization and kennel flooring in veterinary and boarding facilities where broadcast application speed matters more than precision targeting.
- Granule:Slow-release zeolite or activated carbon pellets extend efficacy windows in litter box substrates and outdoor pet run areas through continuous vapor-phase adsorption.
- Wipe:Pre-moistened towelettes impregnated with enzymatic solution serve travel and spot-cleaning scenarios where water access is limited and disposal convenience outweighs unit cost premiums.
Spray commands the revenue base; wipes are climbing fastest through travel-format innovation.
Application:
Indoor applications anchor formulation R&D spending, while outdoor and mobility segments fragment across specialized substrate and portability requirements.
- Indoor:Hard surface, textile, and airborne treatment protocols dominate SKU proliferation as EPA Safer Choice certification becomes table stakes for entry into Petco and PetSmart shelf resets. Flooring manufacturers specify pH-neutral enzymatic cleaners to preserve warranty coverage on luxury vinyl plank and sealed hardwood installations.
- Outdoor:Yard spray concentrates and artificial turf deodorizers address urine accumulation in kennel runs and patio installations where drainage and substrate porosity create distinct degradation challenges.
- Car:Compact format enzymatic sprays and seat-cover compatible wipes target ride-share drivers and traveling pet owners with space-constrained storage and rapid turnaround cleaning needs.
- Travel:TSA-compliant sizes and collapsible litter solutions serve airline cabin transport and extended road trip scenarios where regulatory compliance and portability constrain product architecture.
Indoor maintains the installed base; travel formats gain share through mobility-oriented lifestyle positioning.
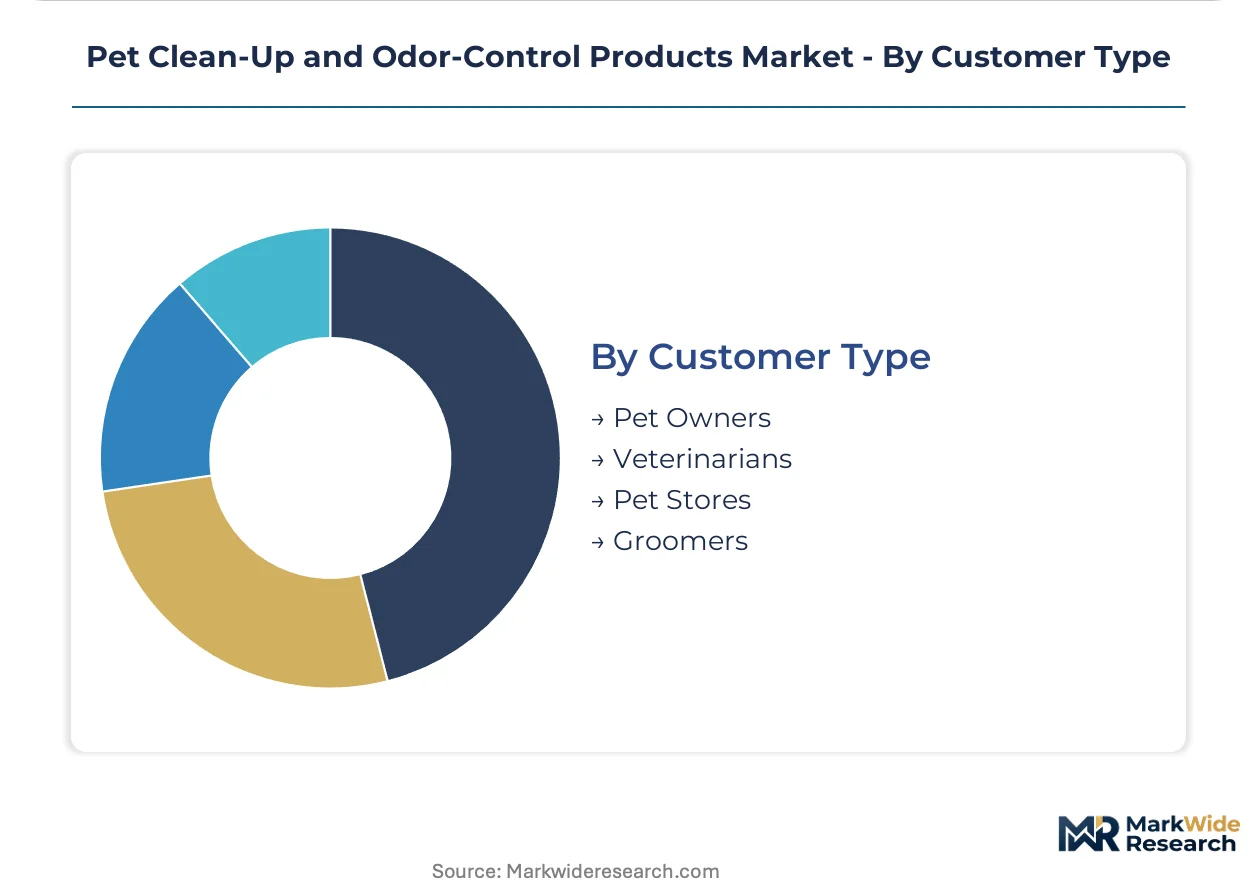
Customer Type:
Professional channels concentrate purchasing volume and specification influence, while pet owner direct purchasing fragments across price tiers and channel preferences.
- Pet Owners:Residential end-users drive SKU proliferation through segmented needs across single-pet, multi-pet, and mixed-species households with varying surface portfolios and odor sensitivity thresholds.
- Veterinarians:Clinic and hospital procurement specifications prioritize disinfectant compatibility, enzymatic efficacy validation, and bulk dispensing economics for high-turnover examination and kennel environments.
- Pet Stores:Independent and chain retail operators curate assortment breadth to capture basket expansion through cross-merchandising with food, toys, and grooming categories.
- Groomers:Salon operators demand rapid-action formulations compatible with hydrobath systems and high-velocity dryers where residual product interference with coat finish creates quality control risks.
Pet owners retain volume leadership; veterinary channels hold the steepest expansion curve through professional endorsement leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for enzymatic biocatalysts tilts trade balances toward Southeast Asian fermentation clusters, while domestic formulation and packaging capacity concentrates in coastal metropolitan zones with stringent organic waste diversion mandates.
United States
Multi-pet household density in suburban Texas and Florida drives concentrated demand for odor-neutralization formulations. EPA Safer Choice certification requirements under the Federal Insecticide, Fungicide, and Rodenticide Act shape permissible ingredient panels for household chemical products. California's CARB VOC regulations in Los Angeles and San Francisco metropolitan areas accelerate reformulation investments toward zero-emission enzymatic alternatives.
Germany
REACH substance restriction expansions force reformulation of stain-resistant coatings and moisture barriers in pet accessory textiles. ECHA candidate list updates for per- and polyfluoroalkyl substances create compliance timelines that favor centralized formulation platforms with regional variant production. Industrial chemical clusters in North Rhine-Westphalia host contract manufacturers serving dual EU-USDA BioPreferred certification pathways.
China
Domestic pet ownership growth in tier-one cities generates demand for premium positioning products previously export-oriented. SAMR national standards for household cleaning products tighten labeling requirements and biocide registration protocols. Yangtze River Delta chemical parks near Shanghai concentrate contract fermentation capacity for bulk enzyme production serving global formulation customers.
Japan
Compact living spaces in Tokyo and Osaka metropolitan areas drive demand for space-constrained litter solutions and rapid-action odor control. METI chemical substance regulations under the Act on the Evaluation of Chemical Substances impose pre-market notification requirements on enzymatic formulations. Kansai industrial corridors host specialty chemical producers with heritage expertise in biocatalytic processes.
United Kingdom
Post-EU regulatory divergence creates dual compliance burdens for formulations serving both UK and continental European markets. Environment Agency extended producer responsibility frameworks for pet waste packaging mandate recycled content minimums and end-of-life recovery infrastructure. Southeast England logistics clusters concentrate direct-to-consumer fulfillment capacity for subscription replenishment models.
Pet Clean-Up and Odor-Control Products Market Competitive Landscape
Concentration sits with diversified household products conglomerates leveraging infrastructure scale against enzymatic formulation specialists capturing premium positioning through channel control. Three archetypes define competitive structure: mass-market incumbents with national distribution density, natural-formulation specialists with direct-to-consumer reach, and contract manufacturers serving private-label programs. Strategic moves center on portfolio diversification into enzymatic alternatives and geographic expansion through e-commerce platform partnerships.
Within the diversified conglomerate tier, The Procter & Gamble Company and Church & Dwight Co., Inc. exemplify scale-driven positioning anchored by household brand recognition and retail shelf space dominance. Rocco & Roxie Supply Co. occupies a specialist position representing the enzymatic formulation archetype with concentrated direct-to-consumer channel control. These three entities collectively illustrate the bifurcation between thin-margin mass distribution and premium natural-positioned returns.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| Spectrum Brands, Inc. |
| Church & Dwight Co., Inc. |
| The Clorox Company |
| Rocco & Roxie Supply Co. |
| BISSELL Inc. |
| Ecolab Inc. |
| SC Johnson |
| Betco |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for bulk enzymatic biocatalysts lock in supply access and price visibility for formulation specialists serving California's CARB-regulated markets, insulating against spot-market volatility in Southeast Asian fermentation capacity while compressing margins for buyers without scale.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with enzymatic concentrates commanding certification premiums over surfactant baselines. Price differentiation rests on EPA Safer Choice verification and cold-chain logistics requirements. Cost compression in economy tiers is intensifying because private-label entrants replicate basic enzymatic formulations. Veterinary clinics demonstrate the lowest price sensitivity due to professional endorsement requirements, while mass-market retailers squeeze suppliers hardest on unit economics.
Supply Chain Analysis
Port congestion on the Shanghai–Long Beach trade lane elevates inbound logistics costs for temperature-sensitive enzyme shipments requiring refrigerated containers. Bulk biocatalyst production clusters in Thailand, Indonesia, and China's Yangtze River Delta, creating single-source vulnerability for North American formulators. Raw material dependencies span proteolytic enzymes, bacterial culture substrates, and compostable polymer resins. Distribution runs through Chewy's fulfillment network and Petco's shelf-space allocation systems, with direct-to-consumer channels capturing expanding margin pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized enzymologist talent pools remain shallow relative to formulation demand, creating a capability bottleneck that constrains product development velocity and favors incumbents with captive R&D assets.
For Market Incumbents: Compound brand equity in odor-neutralization chemistry through Arm & Hammer-style ingredient transparency while acquiring small enzymatic specialists to fill formulation gaps. Cold-chain infrastructure investments in Texas and Florida distribution nodes defend against private-label encroachment in multi-pet household strongholds. For New Entrants and Emerging Players: Veterinary clinic dispensing systems represent an underdeveloped service layer where professional endorsement protocols remain unstandardized. Target suburban veterinary partnerships in Dallas-Fort Worth and Tampa metropolitan zones with bulk enzymatic concentrate programs, leveraging USDA BioPreferred procurement tailwinds in military housing installations. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors enzymatic formulation specialists with verified biodegradable supply chains and direct-to-consumer channel control. Acquisition targets should demonstrate CARB-compliant product lines and Chewy auto-ship penetration above category averages. Monitor FTC Green Guides revision timing as an inflection indicator for claim substantiation cost reallocations.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Formulation R&D Expansion | CARB compliance investments displace legacy surfactant capacity in California retail channels. |
| Cold-Chain Logistics Infrastructure | Temperature-controlled distribution networks reduce spoilage rates for bacterial culture products. |
| Direct-to-Consumer Channel Buildout | Chewy auto-ship programs capture recurring revenue pools from subscription replenishment models. |
| USDA BioPreferred Certification | Federal procurement mandates open institutional demand in military and government facilities. |
| Compostable Substrate Innovation | ASTM D6400-certified waste bags satisfy municipal organic waste diversion mandates in Portland and Seattle. |
Research Methodology
Cross-validation between EPA Safer Choice certification databases and state-level VOC regulatory filings anchors the qualitative findings on formulation compliance trajectories. Primary interviews with enzymatic formulation chemists, Petco category buyers, veterinary procurement managers, and compostable packaging suppliers combine with secondary analysis of CARB regulatory dockets, USDA BioPreferred product directories, and municipal organic waste ordinance databases. Bottom-up SKU velocity data from Chewy and Amazon Subscribe & Save programs triangulates against top-down market sizing from household chemical trade associations.
Sensitivity analysis across enzyme stability assumptions and subscription renewal rate scenarios informs the projection framework. Segmentation dimensions span product type, form factor, application environment, and customer channel, with enzymatic concentration levels and certification status as industry-specific modeling variables. CAGRs derive from regression analysis against multi-pet household formation rates and regulatory compliance cost curves, incorporating cold-chain logistics cost indices and municipal composting infrastructure deployment timelines as forecast inputs.
Forecasts assume regulatory continuity in EPA Safer Choice and California CARB regimes; material policy shifts would require re-modeling of permissible ingredient panels and labeling requirements. Enzyme production concentration in Southeast Asian fermentation facilities and pending FTC environmental marketing standard revisions constitute specific risk factors that could revise trajectory assumptions. Recalibration cycles align with material shifts in municipal organic waste diversion mandates and enzymatic biocatalyst supply contract renegotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Raincoats Market
Pet Care Products
Dog Seat Covers Market
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
Pet Pens Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Dog Pillow Market
Pet Care Products
Cat Collar Market
Pet Care Products
Pet Apparel Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
US Pet Boarding Market
Pet Care Products
Pet Water Fountain Market
Pet Care Products
Pet Clothing Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
Cannabidiol CBD Pet Market
Pet Care Products
Dog Seat Belt Market