
 Pet Rugs Market | 2026-2036
Pet Rugs Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Rugs Market Analytics
Subscription-based replacement programs for washable pet rug liners is rebalancing how manufacturers capture recurring revenue from pet owners. Mohawk Industries leverages its broad distribution network to sustain volume leadership across mass retail channels. Ruggable differentiates through machine-washable modular systems that reduce replacement frequency. Milliken & Company anchors its position with advanced stain-resistant chemistry developed for commercial-grade durability.
Pet rugs are textile floor coverings engineered with absorbent cores, non-skid backings, and odor-resistant treatments designed to protect interior surfaces from pet waste, shedding, and scratching. Manufacturing typically involves bonded polyurethane foam bases topped with solution-dyed synthetic face fibers rated for repeated washing cycles. Indoor rugs dominate current volume due to year-round climate-controlled placement, while anti-slip variants represent the fastest-expanding category as safety concerns intensify among aging pet populations. Synthetic fiber materials command the largest margin pools because petrochemical supply chains enable cost-efficient scale and consistent performance grading.
The EPA regulates volatile organic compound emissions from synthetic fiber manufacturing, while the Consumer Product Safety Commission governs flammability standards for residential textiles. California's Proposition 65 disclosure requirements further constrain formulation choices for products sold into the largest U.S. state economy. Stakeholders must monitor evolving state-level chemical restrictions and pet owner willingness to pay for certified non-toxic construction as these forces determine which product architectures survive channel consolidation.
Market Dynamics
The EPA's low-VOC mandates for synthetic fiber production are compressing formulation choices while California's Proposition 65 disclosure rules constrain material sourcing for manufacturers serving the largest U.S. state economy. Multi-pet household expansion is simultaneously fragmenting demand toward specialized SKUs that resist commoditization.
Growth Catalysts
- REACH chemical registration protocols:European manufacturers advancing non-toxic chemistry gain preferential access to premium retail channels seeking certified-safe inventory.
- Machine-washable modular construction:Pet owners in urban apartments prioritize space-efficient maintenance systems that reduce replacement frequency and storage burden.
- Aging pet demographic concentration:Anti-slip backing demand accelerates as veterinary geriatric care expands and owners invest in mobility-supporting home modifications.
Market Restraints
- Petrochemical feedstock volatility:Solution-dyed synthetic fiber margins compress when crude oil derivatives experience supply disruption.
- Concentrated polyurethane foam supply:Three domestic chemical producers control bonded base material availability, creating bottleneck risk for mid-tier rug assemblers.
- Technical limitation in natural fiber alternatives:Cotton and jute constructions fail odor-resistance standards for repeated soiling cycles, restricting premium positioning.
Strategic Opportunities
- Underpenetrated senior pet care segment:Incontinence-specific absorbent cores with medical-grade wicking layers address the veterinary-assisted living transition market.
- Regulatory tailwind from IRA clean manufacturing credits:Domestic producers retrofitting facilities for low-emission synthetic fiber output qualify for federal incentive structures.
- Subscription liner replacement channels:Direct-to-consumer replenishment programs bypass retail margin extraction and capture lifetime value from repeat purchasers.
Industry Challenges
- Specialized textile chemist scarcity:Formulation expertise combining stain-resistance, odor-neutralization, and wash-durability resides with a narrow cohort of commercial carpet veterans.
- Proposition 65 compliance timeline compression:Reformulation cycles must accelerate to meet California's evolving warning-label requirements without inventory obsolescence.
- Legacy ERP integration friction:Subscription-based liner programs require real-time inventory orchestration that conflicts with batch-oriented manufacturing software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Rugs Market |
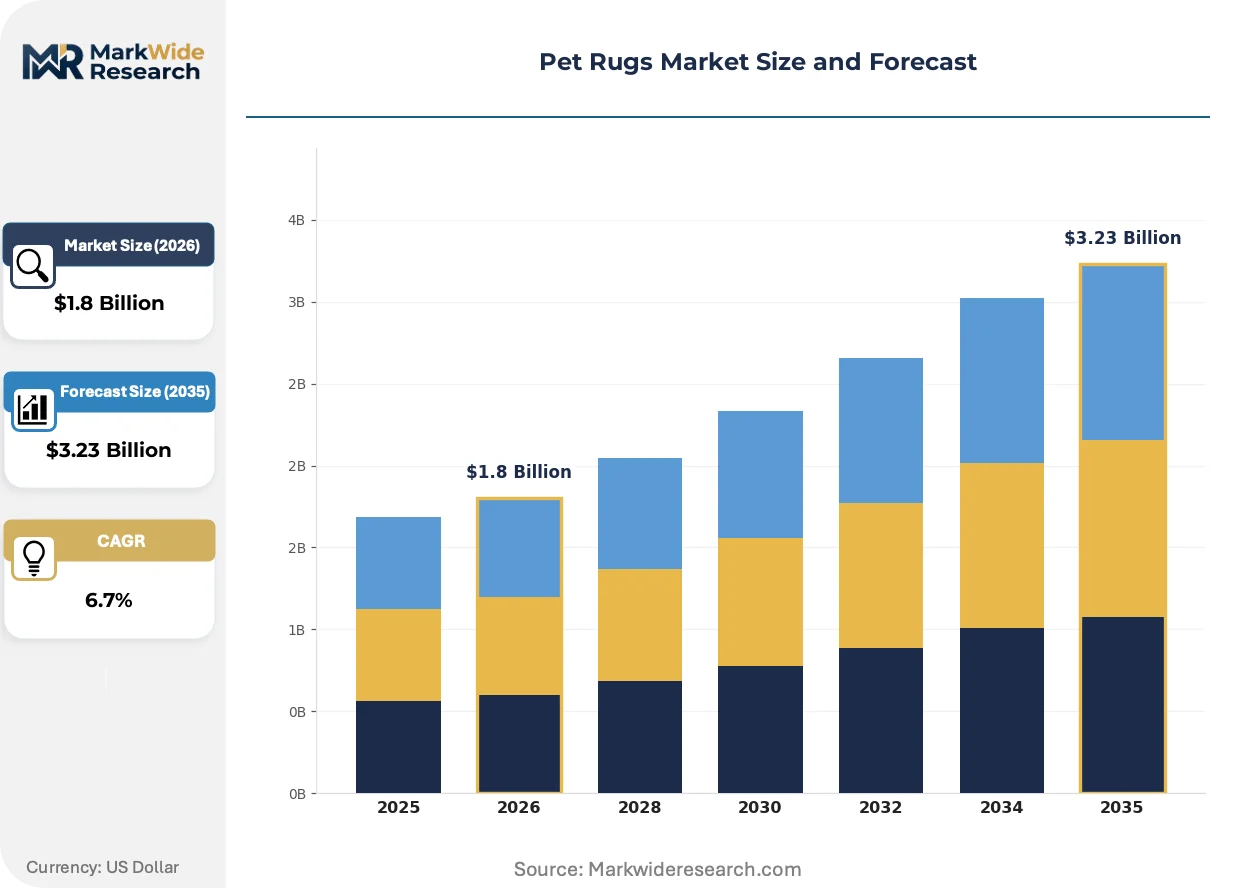
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Rugs, Outdoor Rugs, Anti-Slip Rugs, Designer Rugs Material: Cotton, Synthetic Fiber, Wool, Velvet Size: Small, Medium, Large, Extra Large End User: Pet Owners, Pet Shops, Veterinarians, Animal Shelters |
| Companies Covered | Beaulieu International Group, Tarkett, Mohawk Industries, Godfrey Hirst, Milliken & Company, Shaw Industries Group, Interface, The Rug Company, Ruggable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Rugs Market Evolving Landscape
Material science convergence and regulatory chemistry mandates are restructuring how pet rugs achieve performance certification. Manufacturers must now engineer simultaneously for wash durability, emissions compliance, and modular serviceability.
Solution-dyed PET fiber technology with embedded antimicrobial silver ions is unifying stain resistance, odor control, and colorfastness into single-yarn constructions. Veterinary clinic procurement teams specify these systems for kennel environments requiring hospital-grade hygiene protocols. The technology is unifying previously separate treatment steps, compressing manufacturing cost structures for mid-volume producers.
California's Proposition 65 enforcement expansion against phthalate-containing vinyl backings is forcing rapid substitution with TPU and bio-based alternatives. Domestic compounders are retooling extrusion lines to serve rug manufacturers previously dependent on Asian vinyl supply. Small-batch producers in the Pacific Northwest are capturing shelf space by leading disclosure transparency.
Multi-pet households are consolidating purchases through veterinary-affiliated retail portals rather than mass-market channels. Clinic recommendation programs direct owners toward certified non-toxic constructions with documented wash-cycle performance. This behavioral shift concentrates brand discovery in professional settings rather than big-box aisles, privileging manufacturers with veterinary trade relationships.
Pet Rugs Market Segmentation
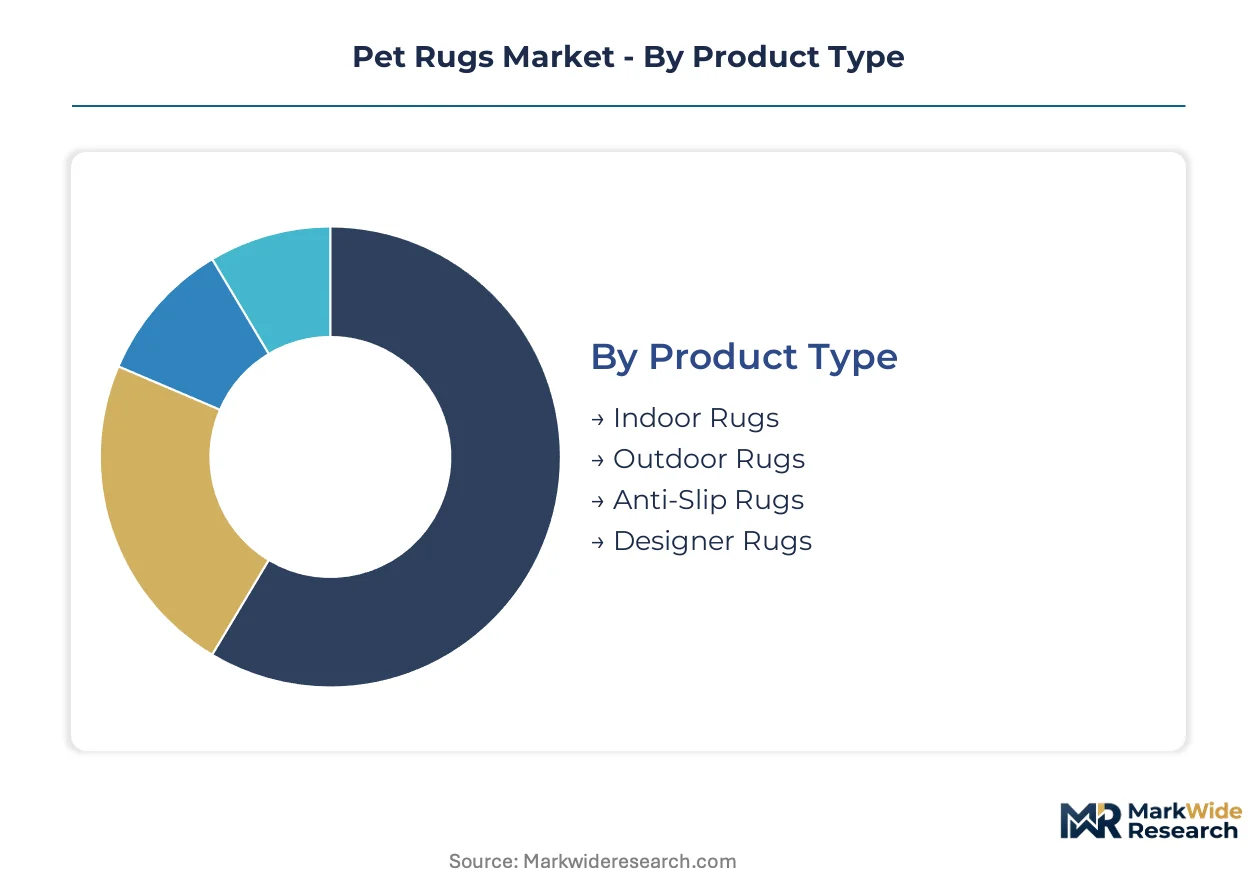
Pet rug segmentation reflects divergent compliance burdens across material chemistry and placement environments. Manufacturers must align formulation investments with the specific certification requirements each segment triggers.
Product Type:
Certification intensity varies sharply by placement environment, with outdoor and anti-slip variants facing distinct regulatory exposure.
- Indoor Rugs:Bonded polyurethane foam bases with solution-dyed synthetic face fibers must meet EPA low-VOC emission standards for residential textiles. Concentrated demand in United States multi-pet households drives volume, though California Proposition 65 disclosure rules constrain backing material choices for products entering the largest state economy.
- Anti-Slip Rugs:TPU and bio-based backing alternatives replace phthalate-containing vinyl constructions under expanded California enforcement. Veterinary geriatric care expansion concentrates purchases among aging pet owners seeking mobility-supporting home modifications.
- Outdoor Rugs:UV-stabilized constructions face weathering durability standards without indoor air quality constraints.
- Designer Rugs:Aesthetic-focused SKUs prioritize wash-cycle performance certification over emissions compliance.
Indoor Rugs sits at the top of the volume ranking, with Anti-Slip Rugs climbing the fastest.
Material:
Cost tier stratification separates petrochemical-dependent synthetics from premium natural fiber alternatives with inferior odor resistance.
- Synthetic Fiber:Solution-dyed PET with embedded antimicrobial silver ions unifies stain resistance, odor control, and colorfastness. Petrochemical supply chains enable cost-efficient scale, though crude oil derivative volatility compresses margins during supply disruption.
- Cotton:Absorbent natural fiber constructions fail repeated soiling cycle standards, restricting positioning to budget-tier replacement-frequency models.
- Wool:Premium natural alternative with inherent stain resistance requires specialized cleaning protocols that limit veterinary channel penetration.
- Velvet:Plush face constructions target designer aesthetic segments with limited wash durability certification.
Synthetic Fiber commands the dominant share of manufacturing output, while Wool captures the highest margin per unit.
Size:
Application scope determines dimensional requirements, with veterinary and shelter procurement driving non-standard specifications.
- Large:Multi-pet household coverage requirements standardize around dimensions accommodating simultaneous feeding and resting zones. United States mass retail channels concentrate inventory investment here.
- Medium:Urban apartment space constraints prioritize modular systems with replacement liner compatibility.
- Small:Single-pet portability specifications for travel and crate placement.
- Extra Large:Kennel environment and veterinary clinic procurement with institutional durability requirements.
Large size formats generate the highest absolute revenue contribution, with Medium formats expanding most quickly in urban coastal markets.
End User:
Customer type segmentation channels distinct margin extraction models, from direct-to-consumer subscription programs to institutional procurement.
- Pet Owners:Subscription-based liner replacement programs capture lifetime value through recurring revenue. Machine-washable modular systems reduce replacement frequency for urban apartment dwellers with storage constraints.
- Veterinarians:Clinic recommendation programs concentrate brand discovery in professional settings, privileging manufacturers with veterinary trade relationships and documented wash-cycle performance.
- Pet Shops:Mass retail channel placement requires inventory breadth across price tiers with compressed margin structures.
- Animal Shelters:Volume procurement prioritizes cost-per-wash-cycle metrics over premium feature sets.
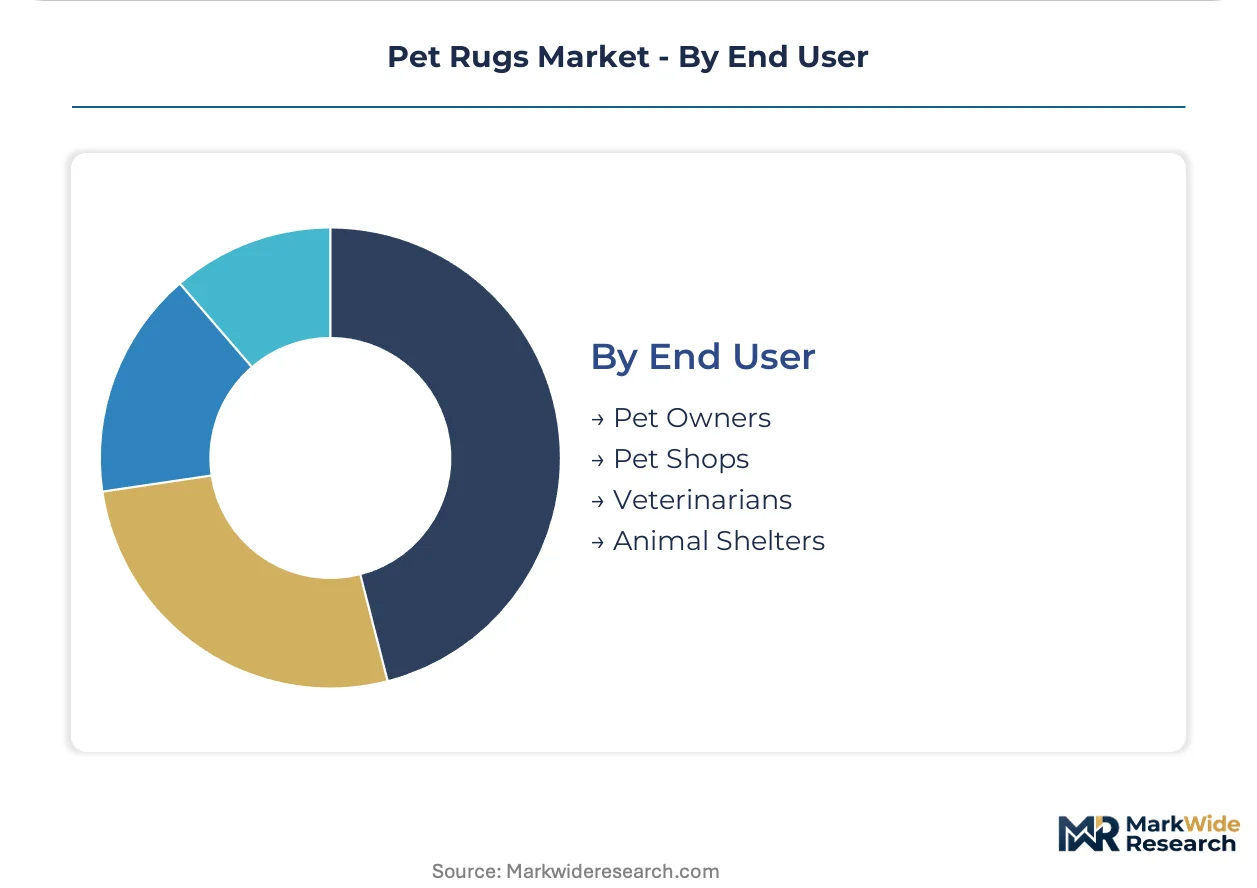
Pet Owners represent the largest addressable population, with Veterinarians delivering the steepest expansion trajectory through affiliated retail portals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pet owners outspend German consumers on premium accessories by a wide margin, while Chinese manufacturing clusters now supply the majority of synthetic fiber base materials. Regulatory divergence between California's chemical disclosure rules and federal EPA standards creates compliance complexity for cross-border suppliers.
United States
Multi-pet household expansion in Texas and Florida drives specialized SKU demand for absorbent cores with odor-resistant treatments. EPA low-VOC mandates for residential textiles constrain formulation choices for manufacturers serving mass retail channels. The Los Angeles basin hosts a concentration of small-batch producers leading disclosure transparency for Proposition 65 compliance.
Germany
REACH chemical registration protocols elevate non-toxic chemistry producers into premium veterinary supply chains across Bavaria and North Rhine-Westphalia. ECHA enforcement of SVHC candidate list updates accelerates reformulation cycles for synthetic fiber imports. The Stuttgart industrial corridor anchors testing and certification services for EU-bound pet textile exports.
China
Petrochemical supply chain scale in Zhejiang and Jiangsu provinces enables cost-efficient solution-dyed PET fiber production for export markets. MEE emissions standards for chemical manufacturing tighten compliance burdens for bonded polyurethane foam base producers. The Yangtze River Delta concentration of textile machinery fabricators supplies automated cutting and bonding equipment to mid-tier rug assemblers globally.
United Kingdom
Veterinary clinic recommendation programs in Greater London and the Southeast concentrate brand discovery for certified non-toxic constructions. UKCA marking requirements post-Brexit create parallel certification tracks alongside retained EU regulations. The Midlands manufacturing belt hosts contract finishing operations for European brands seeking near-shore production flexibility.
Canada
Urban apartment density in Toronto and Vancouver accelerates demand for machine-washable modular systems with replacement liner compatibility. Health Canada and PMRA oversight of antimicrobial claims in textile treatments constrains silver ion marketing language. Montreal-area textile chemists supply formulation expertise for North American brands navigating dual US-Canada regulatory frameworks.
Pet Rugs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with mass retail channels favoring volume-scale suppliers while veterinary portals privilege certified-construction specialists. The vendor base organizes into three tiers: integrated petrochemical-to-finished-goods producers, modular-system innovators, and regional private-label fabricators. Competitive positioning hardens around M&A activity consolidating chemical formulation expertise and strategic partnerships locking veterinary distribution channels.
Within the integrated manufacturing tier, Mohawk Industries and Milliken & Company represent scale-driven archetypes with captive supply chain control over synthetic fiber production. Ruggable occupies a distinct position exemplifying the modular-system innovation vector. Shaw Industries Group and Interface sit within the commercial-grade durability segment, translating carpet industry expertise into pet-specific constructions. Beaulieu International Group and Tarkett exemplify European-based competitors navigating REACH compliance as a competitive differentiator.
| Leading Market Players |
|---|
| Beaulieu International Group |
| Tarkett |
| Mohawk Industries |
| Godfrey Hirst |
| Milliken & Company |
| Shaw Industries Group |
| Interface |
| The Rug Company |
| Ruggable |
| Others |
Value Network & Pricing Analysis
Crude oil derivative indices for solution-dyed PET feedstocks cascade directly into tiered pricing structures across the pet rug market, compressing margins for synthetic fiber assemblers when petrochemical volatility spikes while rewarding bonded polyurethane foam producers with captive supply arrangements.
Pricing Analysis
Capacity additions in Zhejiang province are reshaping price floors for solution-dyed PET fiber exports, forcing mid-tier assemblers toward three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on wash-cycle certification grade and EPA low-VOC compliance tier, with California-bound SKUs commanding premiums for Proposition 65 disclosure transparency. Cost compression in economy-tier cotton constructions is intensifying because natural fiber alternatives fail odor-resistance standards. Animal shelters exhibit highest price sensitivity due to volume procurement metrics, while veterinary clinic channels show lowest sensitivity where certified non-toxic construction drives specification.
Supply Chain Analysis
Skilled textile chemist availability constrains expansion in the Carolinas manufacturing corridor and Pacific Northwest finishing operations, limiting formulation capacity for stain-resistant antimicrobial treatments. Geographic supply concentrates in China for solution-dyed PET fiber, the United States for bonded polyurethane foam bases, and Belgium for TPU backing alternatives. Raw material dependencies draw from petrochemical derivatives, silver ion antimicrobial additives, and bio-based polymer feedstocks. Single-source vulnerability in concentrated domestic polyurethane foam supply creates bottleneck exposure for mid-tier rug assemblers. Distribution runs through mass retail channels, veterinary-affiliated portals, and direct-to-consumer subscription programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pet rugs rests on the shift toward subscription-based liner replacement programs, which capture recurring revenue while reducing customer acquisition costs through veterinary channel endorsement.
For Market Incumbents: Lock in formulation expertise through targeted acquisition of commercial carpet veterans possessing combined stain-resistance, odor-neutralization, and wash-durability capabilities. Secure backward integration into solution-dyed PET fiber production to offset petrochemical feedstock volatility. Defend against modular-system innovators by accelerating proprietary machine-washable platform development before channel consolidation hardens. For New Entrants and Emerging Players: Begin with the underpenetrated senior pet care segment, where incontinence-specific absorbent cores with medical-grade wicking layers address veterinary-assisted living transitions. Target Pacific Northwest small-batch producers leading Proposition 65 disclosure transparency as acquisition or partnership candidates. Pursue direct-to-consumer entry through subscription liner replacement channels that bypass retail margin extraction. For Investors and Strategic Acquirers: Asymmetric upside sits with modular-system innovators possessing real-time inventory orchestration capabilities compatible with subscription-based replenishment programs. Long-term viability favors manufacturers bridging EPA low-VOC compliance with veterinary channel certification requirements. Monitor California Proposition 65 enforcement expansion against phthalate-containing backings as inflection indicator for TPU and bio-based alternative adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solution-Dyed PET Production | Captive fiber supply insulates margin from crude oil derivative volatility in Zhejiang export markets. |
| Veterinary Channel Partnership Lock-In | Clinic recommendation programs concentrate brand discovery away from mass retail price competition. |
| Subscription Liner Replacement Platform Launch | Direct-to-consumer replenishment captures lifetime value while bypassing retail margin extraction. |
| Proposition 65-Compliant Backing Reformulation | TPU and bio-based alternatives replace phthalate vinyl before California enforcement expansion. |
| Senior Pet Care Product Line Extension | Incontinence-specific cores address veterinary-assisted living transitions with medical-grade absorbency. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with textile chemists, veterinary procurement managers, mass retail category buyers, and subscription platform operators with secondary validation from EPA emission standard filings, California Proposition 65 enforcement databases, customs trade records for synthetic fiber imports, and petrochemical derivative price indices. Bottom-up SKU-level demand modeling and top-down macroeconomic factor weighting were triangulated against channel shipment data.
Segment-weighting approaches distributed value and volume across product type, material chemistry, size format, and end-user channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical shipment trajectories adjusted for regulatory compliance cost step-changes and petrochemical input price elasticity. Industry-specific inputs included veterinary clinic expansion rates, multi-pet household formation trends, and EPA low-VOC mandate implementation timelines.
Several conditions sit outside the modeled scope, including abrupt California Proposition 65 chemical list revisions, coordinated OPEC+ production decisions affecting petrochemical feedstock costs, and breakthrough natural fiber treatments achieving odor-resistance parity with synthetics. Forecasts assume stable trade policy frameworks between major manufacturing and consumption geographies. Practitioners should monitor silver ion antimicrobial regulatory scrutiny from Health Canada and ECHA, veterinary clinic consolidation into corporate practice groups, and machine-washable modular patent litigation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Pet Relaxants Market
Pet Care Products
Smart Connected Pet Collar Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Dog Supplement Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Dog Clippers Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
Dog Life Jacket Market
Pet Care Products
Spain Pet Food Market
Pet Care Products
Dog Biscuit Market
Pet Care Products
DTC Pet Food Market
Pet Care Products
Pet Dental Health Market
Pet Care Products
Pet Transporting Service Market