
 Pet Apparel Market | 2026-2036
Pet Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Apparel Market Outlook
Multi-source fabric procurement is shifting toward vertically integrated mills in Southeast Asia as brands seek margin protection against cotton and synthetic volatility. Hurtta leverages its Finnish design heritage to sustain premium positioning in technical dog outerwear. Maxbone anchors its growth through direct-to-consumer channel control and influencer-driven brand equity. Petmate Holdings Co. competes across mass retail with scale manufacturing and private-label partnerships.
Pet apparel encompasses functional and aesthetic garments engineered for domestic animals, typically constructed from woven or knit textiles with specifications for water resistance measured in millimeters of hydrostatic head and breathability rated by moisture vapor transmission rate; its primary commercial purpose is thermoregulation, injury protection, and owner-driven aesthetic expression. Coats and sweaters dominate value pools as staple seasonal purchases with repeat-buy potential, while costumes capture concentrated margin spikes around Halloween and holiday events. Accessories represent the fastest-expanding segment as leashes, boots, and bandanas attach to existing apparel purchases with lower decision friction.
The US Consumer Product Safety Commission monitors flammability standards for pet textiles, while the EU REACH regulation restricts azo dyes and phthalates in imported garments, and China's GB 18401 national textile safety standard governs exports from dominant manufacturing provinces. These frameworks elevate compliance costs for smaller importers while creating certification barriers that favor established players with dedicated quality teams. Stakeholders must monitor evolving chemical restriction lists and traceability mandates as sustainability disclosure requirements tighten across major import jurisdictions.
Market Dynamics
Social media-fueled pet humanization is compressing purchase cycles and elevating aesthetic specifications for functional outerwear, forcing brands to merge technical performance with visual shareability.
Growth Catalysts
- REACH chemical compliance:EU ECHA's expanding restricted substance list is accelerating certified material adoption among import-dependent brands seeking European market access.
- Millennial cohort expansion:This demographic's willingness to allocate discretionary spending toward thermoregulating garments for companion animals sustains premium price realization.
- Technical textile advancement:Moisture vapor transmission rate optimization and hydrostatic head ratings above 10,000mm are extending functional use cases into extreme weather applications.
Market Restraints
- Cotton price volatility:Input cost swings for natural fibers compress margin buffers for mid-tier manufacturers lacking forward contracting capabilities.
- Guangdong-Zhejiang supply concentration:Dominance of export-oriented textile clusters in these Chinese provinces exposes brands to single-country logistics disruption risk.
- Flammability testing burden:US CPSC 16 CFR Part 1610 compliance requirements impose fixed costs that disproportionately burden small-batch importers.
Strategic Opportunities
- India domestic market penetration:Underdeveloped organized retail for companion animal goods in urban centers like Mumbai and Bengaluru offers first-mover positioning for technical outerwear.
- Veterinary rehabilitation integration:Post-surgical recovery garments represent an adjacent clinical channel with prescription-driven demand and reduced price sensitivity.
- Direct-to-consumer platform scaling:Proprietary e-commerce infrastructure enables margin capture currently surrendered to mass retail intermediaries.
Industry Challenges
- Technical pattern-making talent scarcity:Apparel engineers capable of translating human grading rules to variable canine anatomies remain concentrated in heritage outdoor wear regions.
- Multi-jurisdiction certification sequencing:Concurrent GB 18401, REACH, and CPSC compliance timelines delay product launches by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Apparel Market |
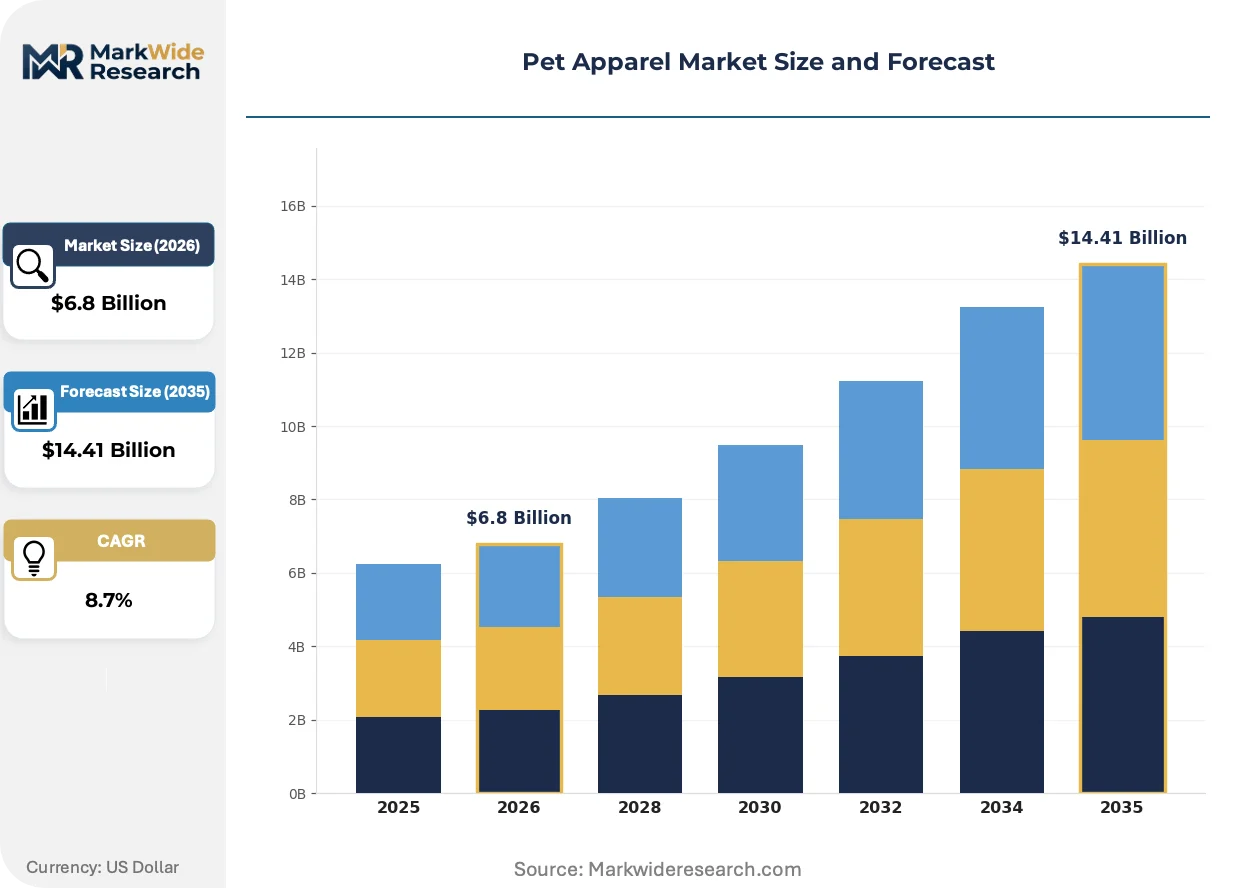
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coats, Sweaters, Costumes, Accessories Material: Cotton, Polyester, Fleece, Nylon Size: Small, Medium, Large, Extra Large End User: Dog Owners, Cat Owners, Pet Stores, Online Retailers |
| Companies Covered | PetRageous Designs, Maxbone, Petmate Holdings Co., RC Pet Products, Hurtta, Ruffwear, Medical Pet Shirts, Blueberry Pet, Canada Pooch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Apparel Market Strategic Shifts
Material science convergence with digital commerce infrastructure is redefining how technical specifications are communicated and validated before purchase.
Recycled ocean plastic filament is expanding into mid-layer insulation and shell fabrics for canine outerwear. Premium pet owners in coastal US metropolitan areas are adopting these garments at rates exceeding conventional synthetic alternatives. This material shift is compressing virgin polymer demand while forcing suppliers to establish traceability documentation chains.
EU REACH SVHC candidate list expansion is tightening azo dye and phthalate restrictions for textile articles imported into European Economic Area member states. Brands with established chemical management systems are capturing shelf space as distributors reduce supplier counts to limit compliance exposure. Technical dog coat manufacturers serving Nordic markets are reformulating water-repellent finishes to exclude perfluorinated compounds ahead of anticipated restrictions.
Subscription-based seasonal wardrobe replenishment is displacing episodic costume and outerwear purchases among high-frequency buyers. Direct-to-consumer channels with fit-prediction algorithms are capturing repeat purchase loyalty previously retained by brick-and-mortar specialty retailers. This behavioral shift is most pronounced in US metropolitan markets with elevated pet density and same-day delivery infrastructure.
Pet Apparel Market Segmentation
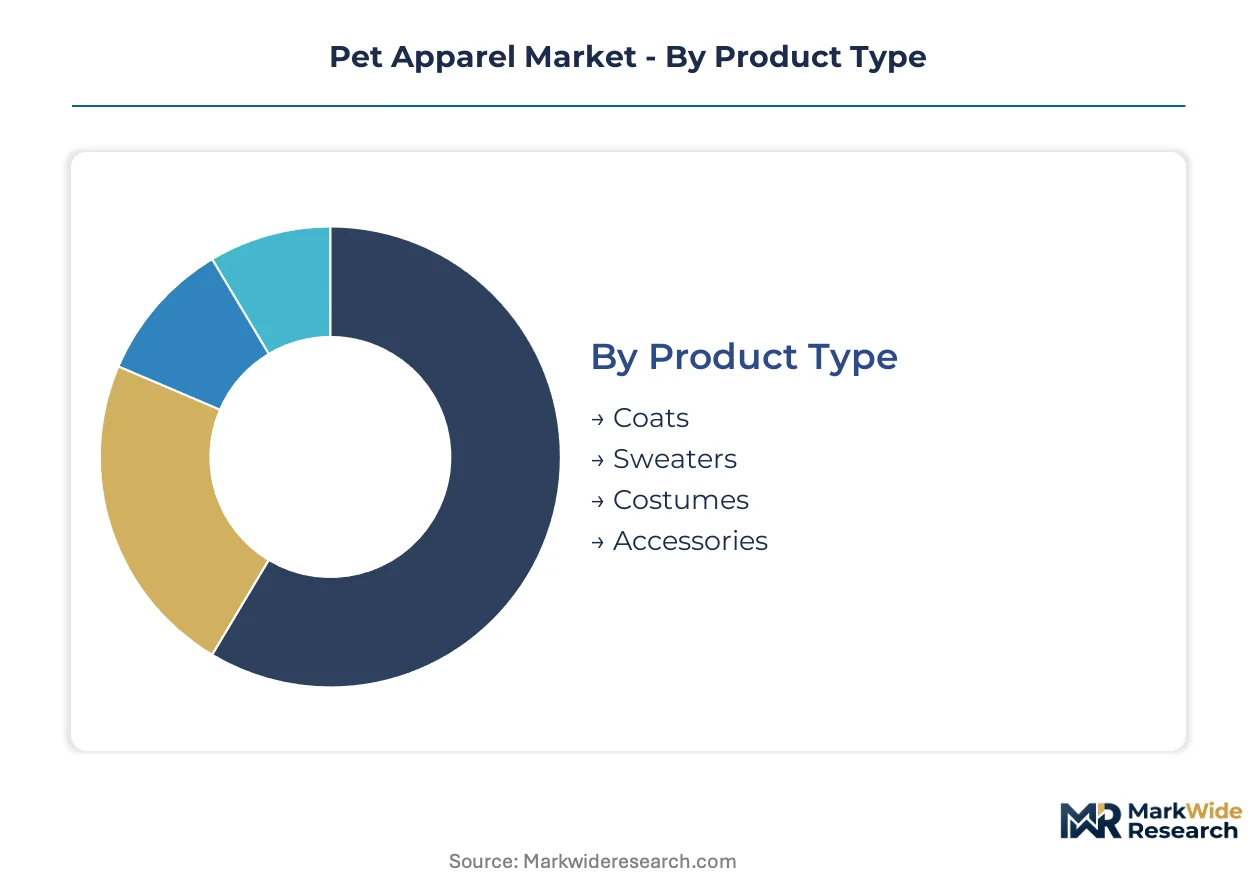
Pet apparel segmentation reveals how supply chain configuration shapes competitive positioning across product tiers. Manufacturers calibrate material specifications and sizing granularity to capture distinct willingness-to-pay thresholds among companion animal owners.
Product Type:
Vertically integrated mills in Southeast Asia dominate outerwear production while specialized subcontractors retain costume manufacturing due to volatile demand patterns.
- Coats:Engineered with hydrostatic head ratings exceeding 10,000mm and moisture vapor transmission optimization for thermoregulation in extreme weather. Demand concentrates in Nordic countries and the northern United States where functional performance commands premium pricing from owners of working and sporting breeds.
- Sweaters:Knit constructions using wool blends or acrylic yarns for indoor warmth and transitional outdoor layering. Urban dog owners in metropolitan markets like New York and London drive repeat purchase cycles through seasonal color refreshes and social media visibility.
- Costumes:Seasonal garments capturing concentrated margin spikes around Halloween and holiday events with limited reuse potential.
- Accessories:Leashes, boots, and bandanas attaching to existing apparel purchases with lower decision friction and fastest expansion trajectory among all product types.
Today's leader: Coats. Tomorrow's challenger: Accessories.
Material:
Raw material cost tiers separate premium positioning from mass-market penetration, with fiber selection determining compliance pathways for EU REACH and US CPSC standards.
- Cotton:Natural fiber preferred for breathability and skin-contact comfort in base-layer garments. Price volatility in cotton futures compresses margin buffers for mid-tier manufacturers lacking forward contracting capabilities with spinning mills.
- Polyester:Dominant synthetic for durability and moisture-wicking performance in active-use outerwear. Recycled ocean plastic filament variants are gaining adoption among coastal US metropolitan consumers demanding traceability documentation.
- Fleece:Synthetic pile fabrics providing warmth-to-weight efficiency for mid-layer insulation in technical dog coats.
- Nylon:High-tenacity filament for abrasion-resistant shell applications and reinforced high-wear zones.
Cotton and polyester split volume leadership. Recycled synthetics represent the steepest expansion trajectory.
Size:
Pattern-making complexity escalates with dimensional range, concentrating technical talent in heritage outdoor wear regions with established grading expertise.
- Small:Garments for toy breeds and cats requiring precision fit to prevent escape and ensure thermoregulation efficiency.
- Medium:Highest volume tier serving the modal dog weight distribution in developed markets.
- Large:Technical outerwear for working breeds with elevated material consumption and reinforced construction requirements.
- Extra Large:Specialized patterns for giant breeds with limited supplier competition due to low order frequency and custom grading demands.
Medium sizes anchor current revenue. Extra Large presents untapped margin expansion for brands with pattern-making depth.
End User:
Channel control separates direct-to-consumer margin capture from wholesale surrender, with veterinary and clinical channels emerging as adjacent demand pools.
- Dog Owners:Primary demand source with highest average transaction values and subscription-based seasonal wardrobe replenishment adoption.
- Cat Owners:Smaller addressable market with distinct fit challenges and lower outerwear acceptance due to behavioral resistance.
- Pet Stores:Brick-and-mortar intermediaries facing displacement by same-day delivery infrastructure in dense metropolitan markets.
- Online Retailers:Platform-dependent sellers capturing traffic through algorithmic fit-prediction tools and influencer-driven discovery.
Dog owners dominate value capture. Veterinary rehabilitation channels represent the next expansion frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong-Zhejiang textile clusters anchor global pet apparel manufacturing, exporting functional outerwear and seasonal garments to North American and European consumer bases. Demand fragmentation across developed markets creates distinct regulatory and channel requirements for import-dependent brands.
United States
Millennial and Gen Z dog owners in metropolitan markets like New York and Los Angeles drive premium outerwear adoption through social media-fueled purchasing. The US Consumer Product Safety Commission enforces 16 CFR Part 1610 flammability standards for imported pet textiles. Same-day delivery infrastructure in dense urban corridors is displacing brick-and-mortar specialty retailers for subscription-based seasonal replenishment.
Germany
Nordic-influenced technical dog coat specifications command premium pricing from owners of working and sporting breeds in Bavaria and North Rhine-Westphalia. ECHA's REACH SVHC candidate list expansion restricts azo dyes and phthalates in textile imports. Berlin-based distributors are consolidating supplier counts to limit compliance exposure from multi-jurisdiction certification requirements.
China
Export-oriented manufacturing concentrates in Guangdong and Zhejiang provinces, supplying woven and knit textiles with GB 18401 national safety standard compliance. The Ministry of Ecology and Environment's dual carbon goals are pressuring textile mills to establish traceability documentation for recycled ocean plastic filament variants. Domestic pet humanization trends in Shanghai and Beijing are creating parallel demand for premium functional garments.
United Kingdom
Urban dog owners in London and Manchester sustain repeat purchase cycles for knit sweaters through seasonal color refreshes and social media visibility. The UK's post-Brexit regulatory alignment with EU REACH restrictions maintains chemical compliance barriers for imported garments. Midlands-based logistics hubs are optimizing cross-border fulfillment for direct-to-consumer channels serving European Economic Area markets.
India
Underdeveloped organized retail for companion animal goods in Mumbai and Bengaluru offers first-mover positioning for technical outerwear brands. The Bureau of Indian Standards monitors textile safety for imported pet garments while domestic production scales under PLI scheme incentives. Chennai and Delhi-NCR textile subcontractors are capturing overflow orders from brands diversifying beyond Chinese supply concentration.
Pet Apparel Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer platform control and influencer-driven brand equity. The vendor base spans heritage outdoor wear specialists, mass retail scale manufacturers, and digitally native vertical brands. Three archetypes dominate: technical performance specialists leveraging Nordic design heritage, mass-market players with private-label partnerships, and DTC-native brands with proprietary e-commerce infrastructure. Competitive moves concentrate on backward integration into Southeast Asian mills and geographic expansion into underpenetrated clinical channels.
Among Nordic-based technical specialists, Hurtta exemplifies premium positioning through functional outerwear engineering. Maxbone and Canada Pooch occupy distinct positions within the DTC-native tier, with the former anchoring influencer-driven discovery and the latter representing North American market specialization. Petmate Holdings Co. sits within the mass-market archetype, competing through scale manufacturing and retail channel density. These three companies illustrate how geographic origin and channel strategy separate premium realization from volume capture.
| Leading Market Players |
|---|
| PetRageous Designs |
| Maxbone |
| Petmate Holdings Co. |
| RC Pet Products |
| Hurtta |
| Ruffwear |
| Medical Pet Shirts |
| Blueberry Pet |
| Canada Pooch |
| Others |
Value Chain & Pricing Dynamics
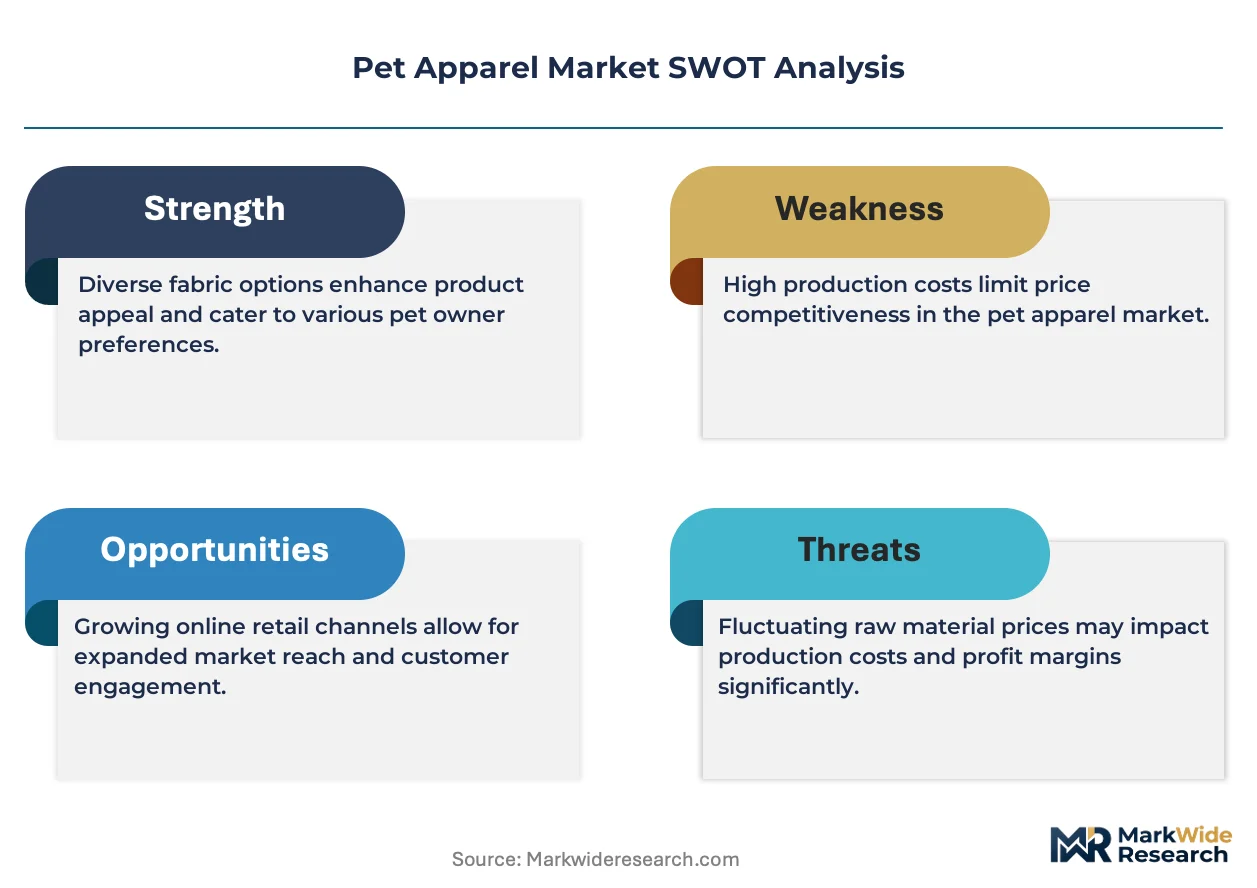
REACH SVHC candidate list expansion in the European Economic Area is forcing import-dependent brands to absorb certified material premiums or surrender shelf space, compressing margin buffers for mid-tier manufacturers while rewarding established players with dedicated quality infrastructure. This regulatory pressure cascades through cotton futures volatility and synthetic fiber traceability costs, reshaping how suppliers calibrate pricing across premium functional outerwear and mass-market seasonal garments.
Pricing Analysis
Input-cost pass-through from cotton futures and recycled ocean plastic filament traceability documentation is intensifying margin pressure across mid-tier manufacturers lacking forward contracting capabilities with Southeast Asian spinning mills. Three-tier pricing structure across premium, standard, and economy levels separates Nordic technical specialists with hydrostatic head certification from private-label mass retailers and direct-to-consumer challengers. Price differentiation hinges on REACH compliance tier and moisture vapor transmission rate performance specifications. Price erosion runs through the standard tier as Guangdong-Zhejiang supply concentration enables volume buyers to extract procurement concessions.
Supply Chain Analysis
Technical textile supply rests on Guangdong and Zhejiang province export clusters for woven shell fabrics, Vietnamese knit mills for sweater constructions, and Finnish design houses for pattern-making talent in canine anatomical grading. Raw material flows draw from cotton futures markets, recycled ocean plastic filament processors, and perfluorinated compound-free water-repellent finish suppliers. Single-country logistics disruption risk concentrates in Chinese export-oriented textile clusters exposed to dual carbon goals enforcement and shipping chokepoint vulnerability. Distribution runs through direct-to-consumer platforms with fit-prediction algorithms, mass retail intermediaries facing displacement, and veterinary rehabilitation channels with prescription-driven demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU ECHA's expanding restricted substance list accelerates certified material adoption and consolidates shelf space among compliant suppliers, creating structural advantage for quality-infrastructure investments.
For Market Incumbents: Deploy backward integration into Southeast Asian spinning mills to secure cotton and recycled synthetic supply against futures volatility and traceability documentation requirements. Capture channel control through proprietary direct-to-consumer platforms with fit-prediction algorithms, defending margin position against algorithmic discovery challengers like Maxbone. Invest in multi-jurisdiction certification sequencing capabilities to compress GB 18401, REACH, and CPSC compliance timelines that currently delay launches. For New Entrants and Emerging Players: Begin with veterinary rehabilitation channel penetration in Mumbai and Bengaluru where organized retail for companion animal goods remains underdeveloped and prescription-driven demand reduces price sensitivity. Target post-surgical recovery garments as a white-space application with clinical credibility requirements that favor technical pattern-making depth over brand equity. Launch through influencer-driven discovery on social media platforms where Millennial and Gen Z dog owners compress purchase cycles through aesthetic shareability. For Investors and Strategic Acquirers: Asymmetric upside sits with direct-to-consumer-native brands with proprietary e-commerce infrastructure and seasonal subscription replenishment models capturing repeat purchase loyalty. Long-term viability favors archetypes with captive supply relationships in Vietnamese or Indian textile subcontractors, insulating against Guangdong-Zhejiang concentration risk. Watch for ECHA perfluorinated compound restriction announcements as inflection indicators that will force reformulation investments and consolidate supplier counts among distributors.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification Investment | ECHA SVHC list expansion rewards early movers with shelf space consolidation in European Economic Area distribution. |
| Direct-to-Consumer Platform Scaling | Proprietary e-commerce with fit-prediction algorithms captures margin surrendered to mass retail intermediaries. |
| Backward Integration into Southeast Asian Mills | Captive supply of cotton and recycled synthetics insulates against futures volatility and traceability documentation costs. |
| Veterinary Rehabilitation Channel Development | Post-surgical recovery garments unlock prescription-driven demand with reduced price sensitivity in clinical settings. |
| Perfluorinated Compound-Free Finish Reformulation | Anticipated ECHA restrictions on water-repellent chemistry force technical adaptation ahead of regulatory enforcement. |
Study Parameters
Direct dialogue with brand managers at heritage outdoor wear specialists, category buyers at mass retail intermediaries, supply planners at Southeast Asian textile mills, and veterinary rehabilitation channel distributors grounded qualitative findings in operational reality. Secondary validation drew from EU ECHA restricted substance list updates, US CPSC 16 CFR Part 1610 flammability standard filings, Chinese customs export data for GB 18401-compliant textiles, and Nielsen retail audit data for companion animal goods. Bottom-up sizing of product type, material, and end-user segments triangulated against top-down macroeconomic indicators across the analysis window.
Segment-level projections across coats, sweaters, costumes, and accessories incorporated hydrostatic head performance tier, moisture vapor transmission rate specifications, and channel control variables throughout the forecast period. CAGRs were derived from elasticity modeling of Millennial discretionary spending allocation and social media-fueled purchase cycle compression. Industry-specific inputs included cotton futures volatility indices, REACH compliance cost curves, and same-day delivery infrastructure penetration in US metropolitan markets.
Several conditions sit outside the modeled scope, including acute cotton commodity price spikes beyond historical volatility bands, abrupt logistics disruption in Guangdong-Zhejiang clusters, and accelerated perfluorinated compound restriction timelines. Forecasts reflect assumptions about regulatory enforcement consistency and consumer willingness-to-pay stability for premium functional outerwear. A small set of named triggers warrants ongoing watch: ECHA SVHC candidate list expansion pace, India PLI scheme textile incentive disbursement, and veterinary channel prescription formulary adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Clothes Market
Pet Care Products
Asia-Pacific Pet Food Market
Pet Care Products
Pet Perfume Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Pet Supplement Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
Natural Dog Treat Market
Pet Care Products
Pet Oral Care Products Market
Pet Care Products
Pet Care Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Pet Grooming Supplies Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
Germany Pet Food Market