
 Germany Pet Food Market | 2026-2036
Germany Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Pet Food Market Analysis
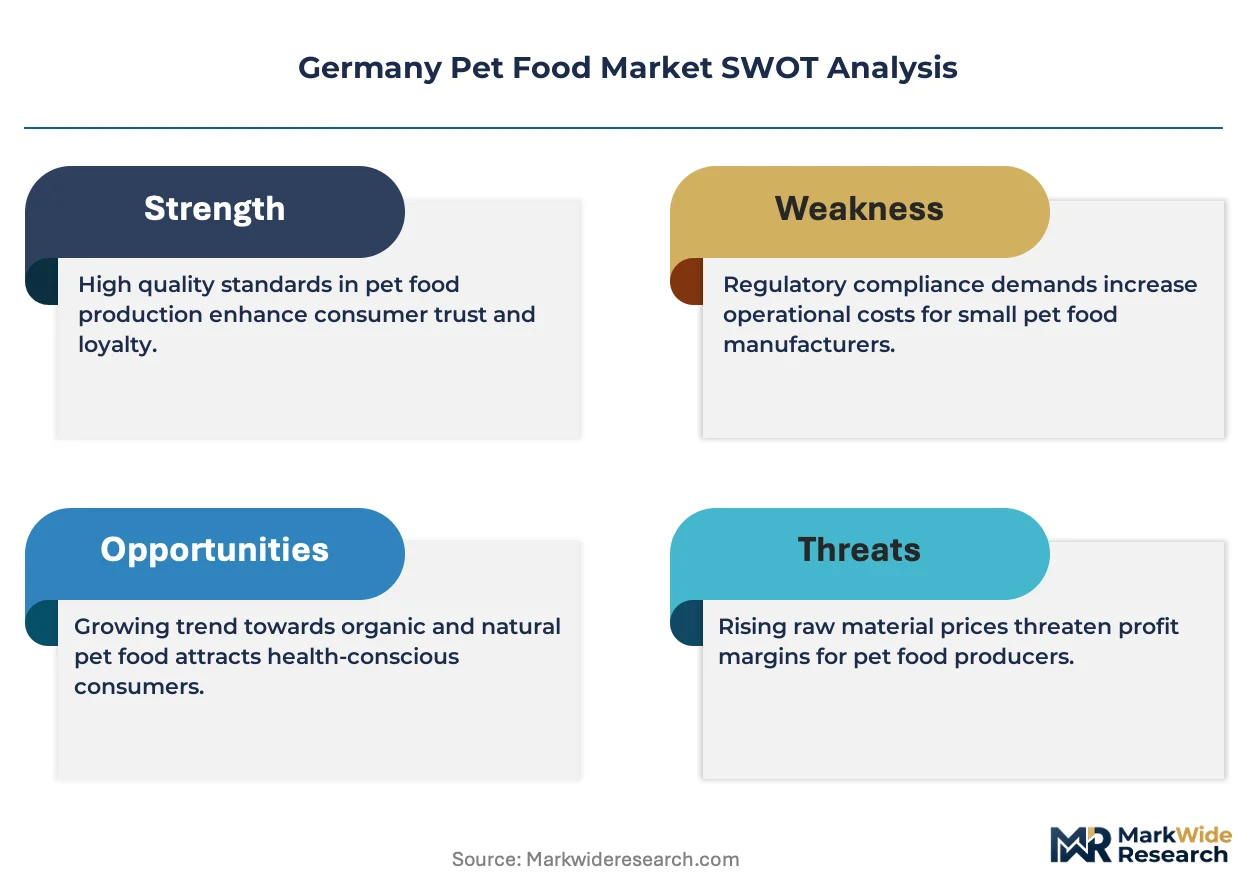
The EU Green Deal is consolidating demand around recyclable packaging and lower-carbon supply chains across German pet food manufacturing. Mars Holding GmbH leverages its integrated European production network to secure raw material traceability. Nestlé Deutschland AG sustains competitive pressure through Purina's specialized veterinary and therapeutic diet lines. Fressnapf Holding SE anchors the specialty retail channel with its captive Maxi Zoo network and private-label manufacturing depth.
Germany pet food encompasses nutritionally formulated products manufactured to species-specific dietary requirements, with dry kibble typically containing 6-10% moisture and wet formulations ranging 75-85% moisture to support hydration and palatability. Premium wet food for dogs commands disproportionate margin pools as owners trade up from mass-market dry alternatives. Online retail competes aggressively with veterinary channels for subscription-based repeat purchases of therapeutic and senior-animal formulations. Organic options remain structurally constrained by limited domestic certified ingredient supply and price premiums that filter out budget-tier buyers.
KBA guidelines on commercial transport logistics intersect with REACH chemical safety standards and EU Green Deal packaging mandates to elevate compliance costs for imported formulations and non-recyclable multi-layer films. The Federal Ministry of Food and Agriculture enforces strict labeling under the German Feed Regulation, requiring precise nutritional declarations that favor transparent, domestically produced brands. Stakeholders must monitor how the EU AI Act's forthcoming transparency requirements affect automated pet health diagnostics and personalized feeding recommendation platforms.
Market Dynamics
The EU Green Deal's packaging sustainability mandates are compressing supplier margins while accelerating consolidation around recyclable mono-material films and regional raw material sourcing across German pet food manufacturing.
Growth Catalysts
- Urban dog ownership density:Apartment-dwelling households in Munich and Hamburg drive disproportionate wet food consumption due to space constraints and odor management priorities.
- REACH chemical safety standards:Stricter contaminant thresholds for imported proteins elevate domestic production premiums and filter out low-cost Eastern European suppliers.
- Veterinary channel expansion:Specialized therapeutic diets distributed through clinic networks capture recurring revenue streams from aging pet populations in North Rhine-Westphalia.
Market Restraints
- Organic ingredient scarcity:Limited certified domestic supply of organic meat and grain inputs constrains production scale and inflates finished-product premiums beyond mass-market reach.
- Multi-layer film dependency:Wet food's shelf-stability requirements currently lock manufacturers into non-recyclable packaging structures facing EU Green Deal phase-out timelines.
- Import logistics friction:KBA commercial transport guidelines intersect with customs documentation burdens, elevating landed costs for non-EU protein sources.
Strategic Opportunities
- Bavaria premiumization:Munich's high disposable-income households sustain price elasticity for functional nutrition claims including joint health and cognitive support formulations.
- Subscription platform integration:Direct-to-consumer auto-replenishment models bypass retail margin extraction while capturing proprietary consumption data for personalized feeding algorithms.
- EU AI Act transparency requirements:Early compliance with automated diagnostic disclosure standards positions domestic brands ahead of imported competitors in veterinary recommendation engines.
Industry Challenges
- Packaging engineering talent scarcity:Food-grade mono-material barrier development requires polymer scientists and shelf-life modelers in short supply within German technical universities.
- Legacy ERP integration friction:Traceability mandates under the German Feed Regulation force mid-tier manufacturers to replace batch-tracking systems without disrupting just-in-time raw material flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Pet Food Market |
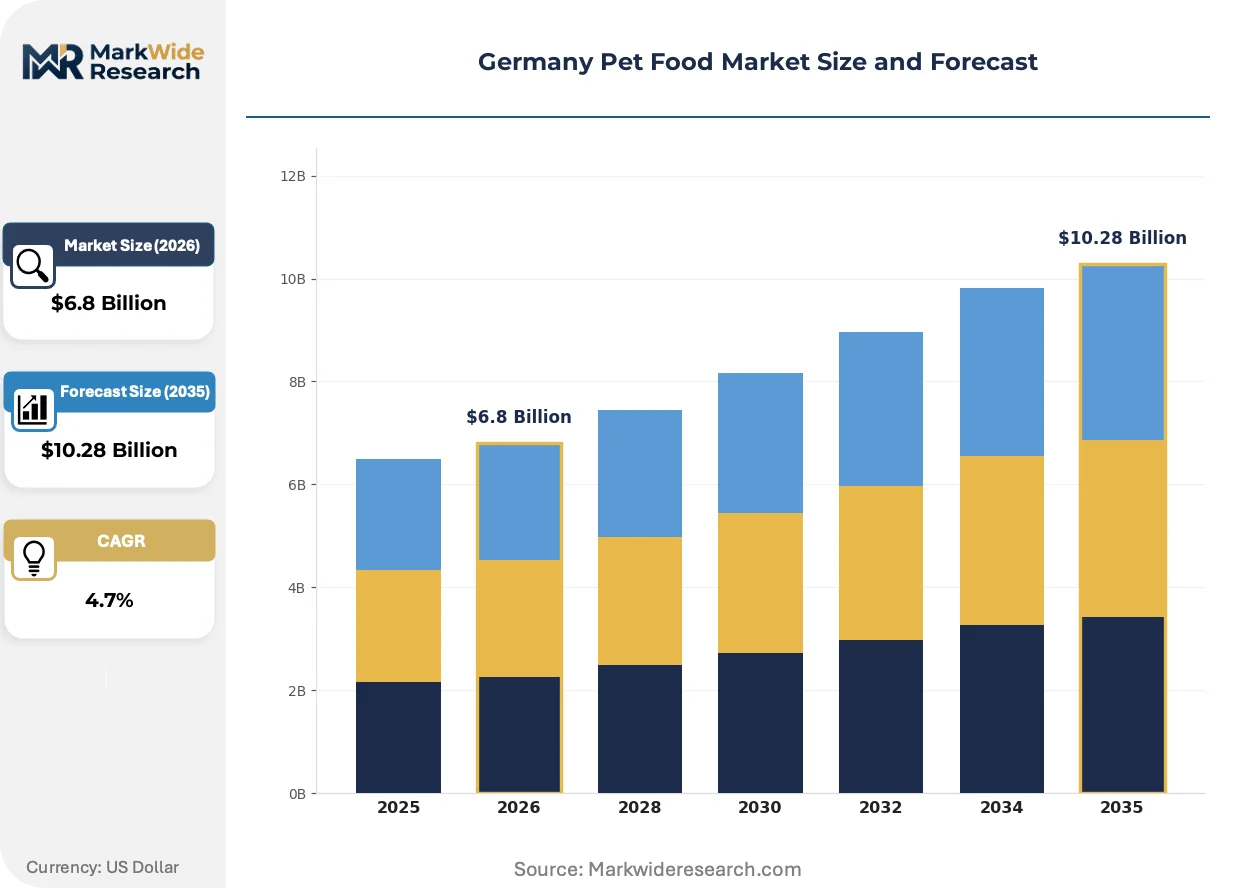
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Organic Options Animal Type: Dogs, Cats, Birds, Small Pets Distribution Channel: Supermarkets, Pet Stores, Online Retail, Veterinarians Price Tier: Premium, Mid-Range, Budget, Economy |
| Companies Covered | Colgate-Palmolive Company (Hill's Pet Nutrition), Fressnapf Holding SE, Mars Holding GmbH, General Mills (Edgard & Cooper), Zooplus AG, Nestlé Deutschland AG, Schell & Kampeter, Inc., Bayer HealthCare AG, Heristo Holding GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Pet Food Market Emerging Trajectories
Digital personalization engines and material science breakthroughs are compressing traditional category boundaries between mass-market and veterinary-grade nutrition across German pet food retail channels.
High-moisture fresh-frozen formats preserved through gentle pasteurization are overtaking conventional retorted cans in urban distribution networks. Berlin and Hamburg households with refrigerator capacity prioritize palatability and ingredient transparency over shelf-stable convenience. This shift is overtaking the historical dominance of mass-market dry kibble in metropolitan household penetration rates.
The EU Green Deal's packaging recyclability targets force reformulation of barrier layers and adhesive systems by 2030. German manufacturers must validate mono-material structures through accelerated shelf-life testing while maintaining oxygen and moisture protection for lipid-rich formulations. Wet food producers in Bavaria face the steepest compliance curves given their reliance on multi-layer retort pouches.
Veterinary clinics are unbundling diagnostic services from product sales, creating independent prescription fulfillment pathways. Pet owners in North Rhine-Westphalia increasingly price-shop therapeutic diets across online pharmacies after receiving veterinary consultations. This disintermediation pressures clinic-exclusive distribution margins while expanding third-party logistics volumes for temperature-controlled shipments.
Germany Pet Food Market Segmentation
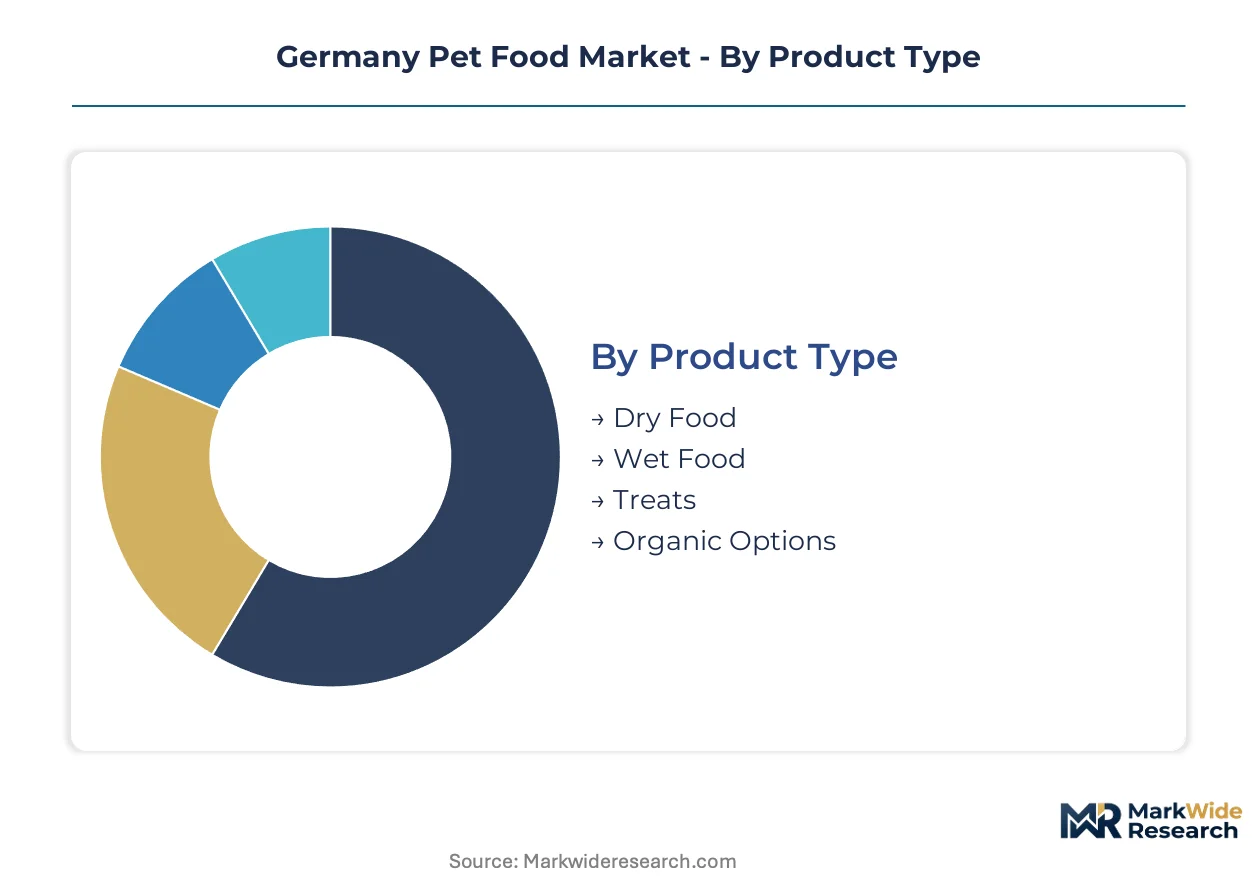
Segmentation in Germany's pet food market exposes divergent margin structures and channel strategies. Product moisture content and species-specific formulation requirements create fundamentally different supply chain economics. Price tier stratification concentrates purchasing power in southern German metropolitan zones.
Product Type:
Dry formulations dominate tonnage throughput while wet alternatives command absolute margin premiums across German retail channels.
- Dry Food:Kibble formulations with 6-10% moisture content enable extended ambient shelf stability and efficient logistics. Bavarian warehouse clubs and North Rhine-Westphalia discounters move the highest volumes through centralized distribution centers serving apartment-dwelling households seeking odor-minimized feeding solutions.
- Wet Food:Retort-pouched or tray-sealed products carrying 75-85% moisture support hydration and palatability for aging animals. Urban dog owners in Munich and Hamburg sustain disproportionate adoption rates despite EU Green Deal packaging compliance pressures on multi-layer film structures.
- Treats:Functional and reward-based formulations with targeted nutritional additives.
- Organic Options:Certified ingredient products constrained by limited domestic supply and price premiums filtering mass-market penetration.
Today's leader: Dry Food. Tomorrow's challenger: Wet Food.
Animal Type:
Species-specific metabolic requirements dictate formulation complexity and veterinary channel penetration depth.
- Dogs:Omnivore-optimized formulations spanning maintenance, performance, and therapeutic life-stage requirements. North Rhine-Westphalia's aging canine population drives therapeutic diet volumes through clinic networks.
- Cats:Obligate carnivore nutrition with taurine and arachidonic acid fortification mandates. Premium wet adoption concentrates in Berlin and Hamburg single-cat households prioritizing hydration management.
- Birds:Seed, pellet, and nectar formulations for avian species with species-specific beak morphology requirements.
- Small Pets:Rodent, rabbit, and ferret diets with hay-based fiber and controlled calcium specifications.
Canine nutrition anchors current revenue. Feline therapeutic segments are expanding most quickly.
Distribution Channel:
Channel selection determines margin extraction rates and customer data ownership structures.
- Supermarkets:Mass-market dry kibble and mid-range wet formats with high-visibility placement. Edeka and REWE chains in Bavaria concentrate volume through centralized procurement.
- Pet Stores:Specialty retailers with private-label depth and captive loyalty programs. Fressnapf's Maxi Zoo network dominates this channel with in-house manufacturing integration.
- Online Retail:Subscription-based auto-replenishment platforms capturing recurring therapeutic and senior-animal purchases. Temperature-controlled logistics investments enable fresh-frozen format penetration.
- Veterinarians:Prescription-only therapeutic diets with clinic-exclusive distribution margins. North Rhine-Westphalia practices face disintermediation pressure as owners price-shop across online pharmacies post-consultation.
Physical retail currently controls volume. Digital subscription models are gaining share fastest.
Price Tier:
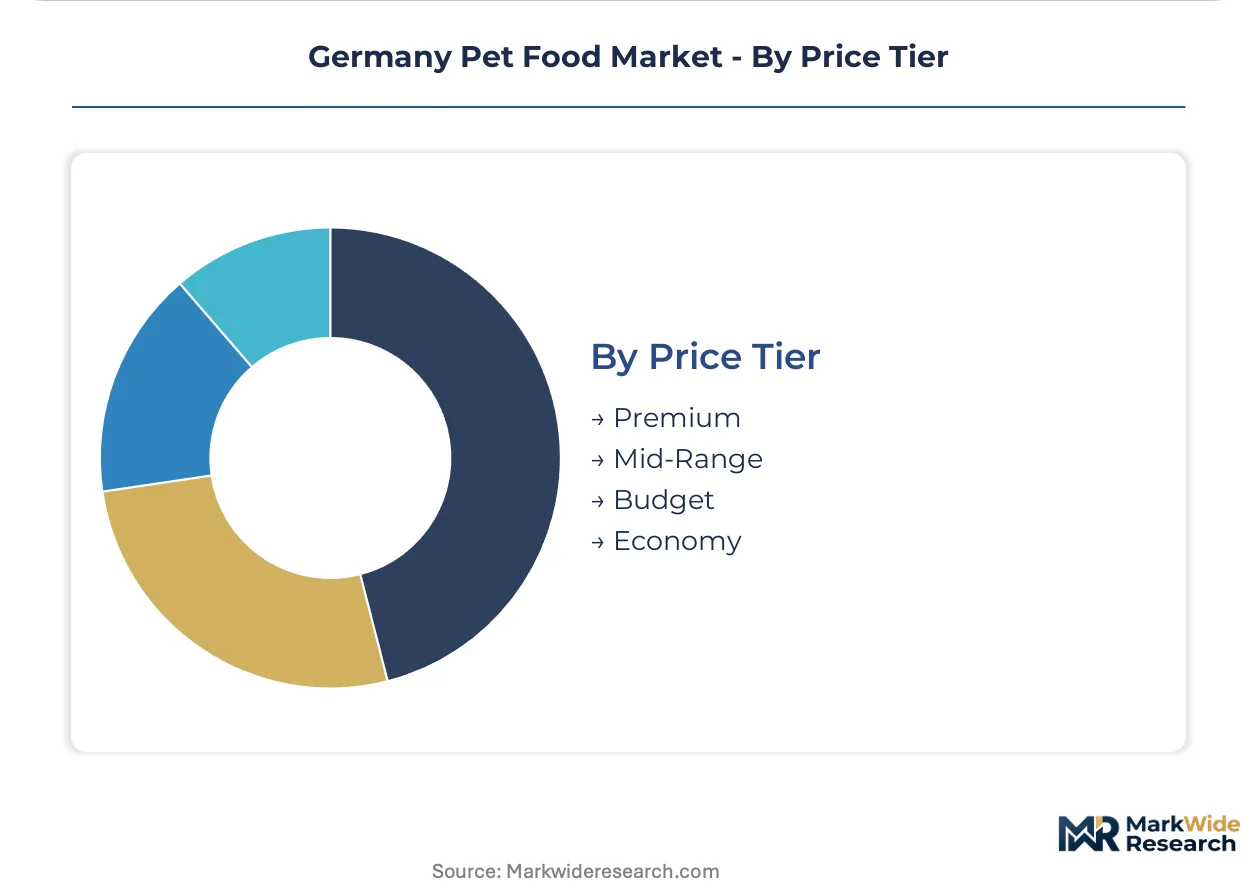
Pricing stratification across premium, standard, and economy levels reflects ingredient sourcing transparency and functional claim substantiation.
- Premium:Human-grade protein sourcing, novel carbohydrate bases, and substantiated functional claims. Munich households sustain price elasticity for joint health and cognitive support formulations.
- Mid-Range:Balanced nutrition with conventional protein sources and limited functional additives. Hamburg families trade up selectively for life-stage transitions.
- Budget:Commodity protein meals meeting minimum nutritional adequacy standards. Discounter channels in eastern Germany concentrate this tier.
- Economy:Price-point-driven formulations with minimal marketing investment and basic compliance labeling.
Premium tier leads absolute margin generation. Mid-Range products face steepest competitive pressure from private-label substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pet food manufacturing traces its modern lineage to post-war industrialization in Bavaria and the Rhineland, where meat-processing byproducts first supplied standardized animal nutrition at scale.
Bavaria
Munich's affluent households sustain premium wet food demand through functional nutrition claims targeting joint health and cognitive support. The German Feed Regulation enforces strict nutritional labeling transparency that favors established domestic brands over imports. Manufacturing clusters around Nuremberg and Augsburg concentrate production of therapeutic formulations for aging canine populations.
North Rhine-Westphalia
Dense urban dog ownership in Cologne and Düsseldorf drives disproportionate consumption of odor-minimized wet formats suited to apartment living. REACH chemical safety standards elevate compliance costs for imported proteins, filtering Eastern European suppliers from premium supply chains. The Ruhr industrial corridor hosts specialized logistics infrastructure for temperature-controlled distribution of fresh-frozen pet nutrition.
Baden-Württemberg
Stuttgart's automotive-affluent households exhibit strong price elasticity for subscription-based pet food delivery models. KBA commercial transport guidelines intersect with EU Green Deal packaging mandates to reshape supplier procurement specifications. The Upper Rhine Valley clusters organic ingredient suppliers constrained by limited certified domestic meat and grain availability.
Hamburg
Single-cat households in this northern port city prioritize hydration-focused wet nutrition with high palatability scores. EU AI Act transparency requirements are pressuring automated feeding recommendation platforms to disclose algorithmic decision criteria. The metropolitan area's cold-chain infrastructure enables fresh-frozen format penetration ahead of national averages.
Berlin-Brandenburg
Younger pet owners in the capital trade up from mass-market dry kibble to gently pasteurized fresh formats requiring refrigeration. The Federal Ministry of Food and Agriculture enforces contaminant thresholds that exceed EU baselines for domestic production. Brandenburg's agricultural hinterland supplies conventional grain inputs while organic certification lags regional demand.
Germany Pet Food Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and veterinary channel access, creating a tiered structure where therapeutic diet specialists command recurring revenue streams. The vendor base spans multinational CPG conglomerates with integrated European production networks, captive specialty retail chains with private-label manufacturing depth, and digital-native subscription platforms. Three archetypes dominate: vertically integrated nutrition science leaders, multi-channel retail operators with captive loyalty ecosystems, and direct-to-consumer challengers leveraging consumption data for personalization. Competitive intensity concentrates on M&A activity targeting therapeutic formulation capabilities and strategic partnerships securing mono-material packaging engineering talent.
Among diversified CPG conglomerates, Mars Holding GmbH and Nestlé Deutschland AG occupy positions anchored by Purina's specialized veterinary lines and integrated raw material traceability systems. Fressnapf Holding SE exemplifies the captive retail-manufacturing archetype through its Maxi Zoo network and in-house production depth. These three entities represent distinct competitive vectors: multinational scale advantages, specialty channel control, and private-label margin extraction respectively.
| Leading Market Players |
|---|
| Colgate-Palmolive Company (Hill's Pet Nutrition) |
| Fressnapf Holding SE |
| Mars Holding GmbH |
| General Mills (Edgard & Cooper) |
| Zooplus AG |
| Nestlé Deutschland AG |
| Schell & Kampeter, Inc. |
| Bayer HealthCare AG |
| Heristo Holding GmbH |
| Others |
Supply Flow & Price Mechanics
Mono-material packaging migration simultaneously compresses wet food production economics and concentrates supplier bargaining power among polymer engineering specialists. REACH chemical safety standards and EU Green Deal mandates elevate compliance costs disproportionately for imported proteins, reshaping cost structures across Bavarian and North Rhine-Westphalian manufacturing clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes by functional claim intensity and ingredient transparency demands. Certification grade under EU organic standards and domestic provenance claims drive price differentiation between Munich households and eastern German discounter channels. Cost compression in mid-range tiers intensifies as private-label substitution accelerates through Fressnapf's captive manufacturing depth. Budget-tier buyers exhibit highest price sensitivity, while premium segment purchasers in Stuttgart and Hamburg sustain elasticity for joint health and cognitive support formulations.
Supply Chain Analysis
Dual-sourcing requirements for wet food barrier films mandate multi-supplier qualification as EU Green Deal phase-out timelines approach. Manufacturing concentrates in Germany, Poland, and the Netherlands, with raw material dependencies spanning Brazilian poultry meal, Ukrainian grain, and Scandinavian fish protein. Single-source vulnerability in mono-material polymer science talent elevates risk for Bavarian retort pouch producers. Distribution runs through temperature-controlled logistics networks anchored by Ruhr corridor cold-chain infrastructure and veterinary clinic fulfillment pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Germany's pet food market rests on packaging compliance cost-down curves and premium wet food adoption in metropolitan households. Mono-material engineering breakthroughs and subscription platform data monetization reshape profitability trajectories.
For Market Incumbents: Deepen backward integration into certified organic protein sourcing to offset supply scarcity constraints in Brandenburg and Upper Rhine Valley clusters. Expand captive mono-material film production capabilities ahead of EU Green Deal enforcement timelines. Digital-native subscription challengers threaten clinic-exclusive distribution margins through price-transparent therapeutic diet fulfillment. For New Entrants and Emerging Players: Capture fresh-frozen format white space in Berlin-Brandenburg and Hamburg single-pet households with refrigerator capacity and palatability priorities. Veterinary channel disintermediation creates entry pathways for temperature-controlled direct-to-consumer platforms. Target subscription auto-replenishment with algorithmic personalization as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers with legacy ERP systems requiring German Feed Regulation traceability upgrades. Long-term viability favors therapeutic formulation specialists with clinic network access and captive raw material traceability. Watch EU AI Act transparency enforcement as the inflection signal for automated diagnostic platform compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Packaging Transition | EU Green Deal compliance secures shelf-life validation for lipid-rich wet formulations through accelerated barrier testing. |
| Subscription Platform Integration | Direct-to-consumer auto-replenishment captures proprietary consumption data for personalized feeding algorithms in urban households. |
| Therapeutic Diet Pipeline Expansion | Veterinary clinic networks in North Rhine-Westphalia generate recurring revenue from aging canine populations. |
| Organic Ingredient Supply Security | Backward integration into certified domestic protein sourcing mitigates production scale constraints in premium tiers. |
| AI Transparency Compliance | Early adherence to EU AI Act disclosure standards positions domestic brands ahead of imported competitors in recommendation engines. |
Methodological Framework
Coverage spans Bavaria, North Rhine-Westphalia, Baden-Württemberg, Hamburg, and Berlin-Brandenburg, with primary inputs from each manufacturing cluster and consumption center. The analysis combines structured interviews with pet food brand managers, veterinary clinic procurement leads, Maxi Zoo category buyers, polymer packaging engineers, and Federal Ministry of Food and Agriculture regulatory specialists with secondary validation from EU Green Deal implementation documents, German Feed Regulation enforcement records, KBA commercial transport guidelines, and REACH chemical safety compliance databases. Bottom-up production capacity modeling and top-down household expenditure triangulation anchor volume and value estimates.
Granularity-level modeling disaggregates projections across product moisture content tiers, species-specific formulation requirements, distribution channel economics, and regional metropolitan consumption patterns. CAGRs derive from segment-level growth rate blending with macroeconomic elasticity assumptions. Industry-specific forecast inputs include urban dog ownership density trajectories in Munich and Hamburg, veterinary channel prescription volumes in North Rhine-Westphalia, and mono-material packaging adoption curves across Bavarian manufacturing facilities.
EU Green Deal enforcement acceleration, REACH chemical safety threshold revisions, and organic ingredient supply disruptions are the dominant revision risks to the outlook. Deviation in mono-material packaging engineering timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
United Kingdom Pet Food Market
Pet Care Products
Spain Pet Food Market
Pet Care Products
Cat Massage Comb Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
Pet Jerky Treat Market
Pet Care Products
Pet Food Bowl Market
Pet Care Products
Canada Pet Boarding Market
Pet Care Products
Bird Toy Market
Pet Care Products
Toy Dog Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
South America Pet Diet Market
Pet Care Products
Mobile Pet Care Market
Pet Care Products
Pet Pens Market