
 Pet Perfume Market | 2026-2036
Pet Perfume Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Perfume Market Outlook
The capital-intensity gap between artisan formulators and mass-market producers is collapsing as contract manufacturing and white-label platforms democratize scent development. TropiClean leverages its established grooming supply infrastructure to secure shelf placement across big-box pet retailers. Isle of Dogs anchors its positioning through breed-specific fragrance lines and professional groomer channel relationships. Pawfume competes via direct-to-consumer subscription models that reduce customer acquisition costs over repeat purchase cycles.
Pet perfume comprises alcohol-based or water-based formulations incorporating essential oils, synthetic fragrance compounds, and conditioning agents designed to neutralize pet odor while leaving a residual scent on coat and skin. Manufacturing typically involves cold-blending processes with pH balancing to maintain dermatological safety for canine and feline physiology, followed by stability testing for shelf-life validation. Spray formats dominate volume sales through convenience positioning, while oil-based variants command margin premiums among buyers seeking extended fragrance longevity. The fragrance family dimension shows citrus profiles leading in puppy and young-dog applications, with woody notes gaining traction among owners of large-breed dogs where masking stronger natural odors becomes a functional priority.
The EPA regulates volatile organic compound emissions in aerosol pet products, while state-level consumer protection offices in California enforce Proposition 65 labeling for trace contaminants. The FDA Center for Veterinary Medicine maintains oversight of products making therapeutic claims, creating compliance boundaries that separate cosmetic fragrance from medicated odor-control formulations. Stakeholders must monitor pending state legislation around fragrance ingredient disclosure that could replicate California's Cleaning Product Right to Know Act across pet care categories.
Market Dynamics
Humanization of pet ownership is compressing the innovation cycle for cosmetic-grade formulations, as urban households demand dermatologically tested products that mirror personal fragrance standards. This force is pulling contract manufacturers into scent development while fragmenting buyer loyalty across subscription and specialty retail channels.
Growth Catalysts
- EU REACH framework:Mandatory ingredient disclosure is elevating formulation transparency as a competitive differentiator, pushing brands to invest in clean-label chemistry and third-party safety certifications.
- Urban household density:Apartment-dwelling pet owners face amplified odor concerns from confined spaces, creating sustained pull for daily-use spray formats and portable application designs.
- Essential oil microencapsulation:Extended-release technology is extending fragrance longevity from hours to days, reducing reapplication frequency and improving cost-per-use metrics for premium buyers.
Market Restraints
- Synthetic fragrance concentrate volatility:Petrochemical feedstock fluctuations compress margins for alcohol-based formulations, forcing price adjustments that alienate mid-tier buyers.
- California Proposition 65 enforcement:Trace contaminant labeling requirements create compliance friction for imported products, delaying market entry for non-US formulators.
- Water-based substitute threat:Alcohol-free variants from grooming and hygiene adjacent categories capture safety-conscious buyers seeking dermatological claims without fragrance specialization.
Strategic Opportunities
- Feline-specific underpenetration:Canine-dominated product portfolios leave cat owners underserved, with pH-adjusted formulations and stress-reducing scent profiles representing untapped white space.
- Veterinary clinic channel expansion:Professional endorsement through white-coat retail builds credibility for therapeutic-positioned odor control, bypassing crowded mass-market shelf competition.
- Biodegradable carrier solvents:Convergence of green chemistry and performance requirements creates first-mover advantage for brands achieving EU Ecolabel certification ahead of mandate expansion.
Industry Challenges
- Fragrance chemist talent scarcity:Cross-species dermatological safety expertise sits concentrated with legacy personal care formulators, inflating recruitment costs for emerging brands.
- Stability testing capex intensity:Shelf-life validation for oil-in-water emulsions requires climate-controlled aging facilities that strain bootstrap capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Perfume Market |
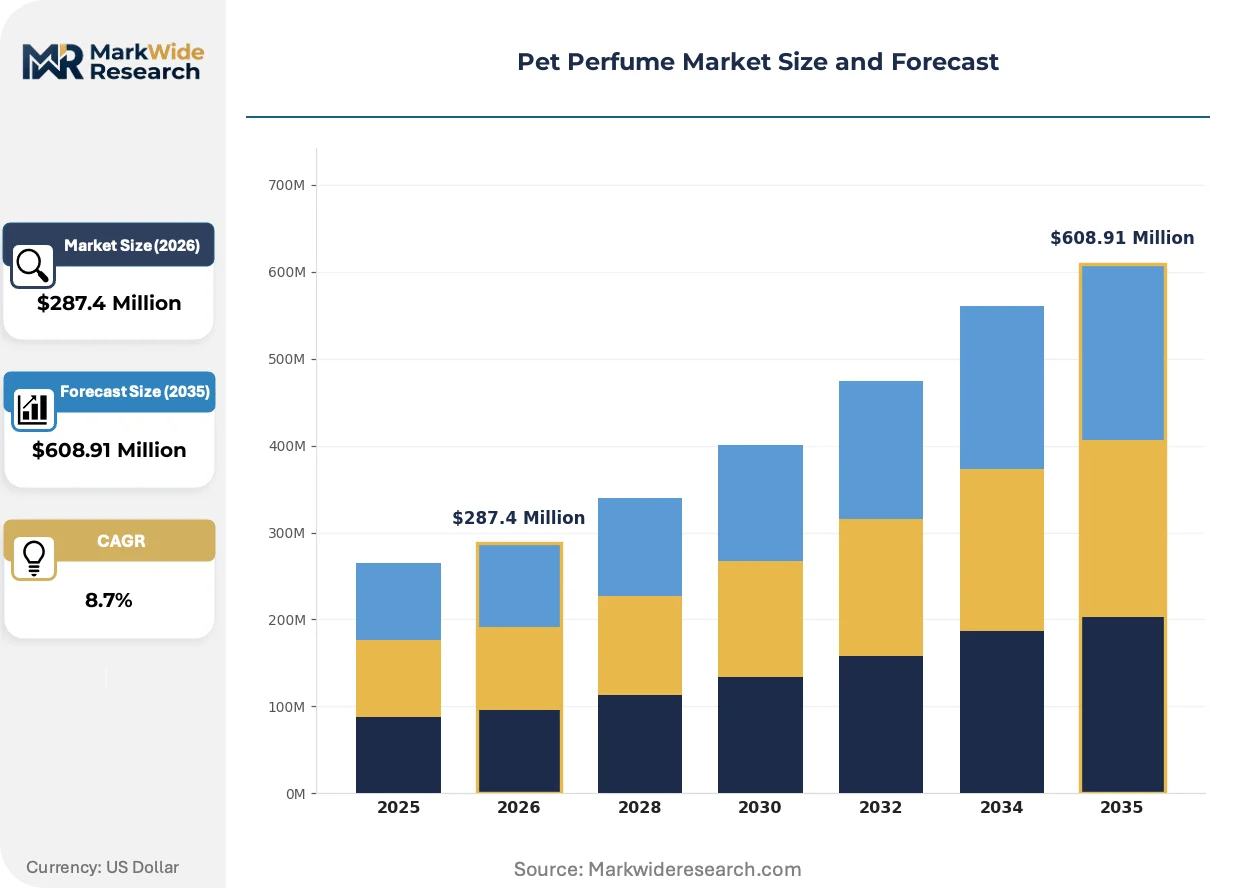
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $608.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray, Oil, Gel, Roll-on Customer Type: Pet Owners, Retailers, Groomers, Veterinary Clinics Fragrance Family: Citrus, Floral, Woody, Spicy Packaging Type: Glass Bottle, Plastic Bottle, Eco-friendly, Sample Size |
| Companies Covered | Pawfume, Isle of Dogs, TropiClean, Animology, Bodhi Dog, Earthbath, Pet Head, Captain Zack, Lambert Kay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Perfume Market Strategic Shifts
Formulation chemistry and distribution architecture are diverging simultaneously, as biotechnology-enabled scent delivery collides with direct-to-consumer channel maturation. These forces are rewriting how products reach buyers and how long they retain them.
Biotechnology-derived fragrance precursors are bifurcating the ingredient supply base between synthetic petrochemical routes and enzymatic biosynthesis pathways. Premium-positioned brands are adopting yeast-fermented aromatic compounds to secure clean-label positioning, while mass-market producers defend cost structures through conventional chemistry. This split is compressing mid-tier players into margin pressure as they straddle incompatible cost and positioning architectures.
REACH authorization requirements for fragrance allergens are tightening disclosure obligations across EU member states, forcing reformulation of legacy compound libraries. Manufacturers must now submit full safety dossiers for previously grandfathered ingredients, extending product development timelines by twelve to eighteen months. Professional groomer channels are responding fastest, as their liability exposure drives preference for pre-certified formulations.
Subscription replenishment models are displacing episodic retail purchasing among urban millennial and Gen Z pet owners, locking in predictable revenue streams. Specialty e-commerce platforms capture these buyers through algorithmic scent matching and auto-ship flexibility, while big-box retailers struggle to replicate the data intimacy. This shift concentrates most visibly in United States coastal metro areas where pet insurance penetration and premium care spending already run above national averages.
Pet Perfume Market Segmentation
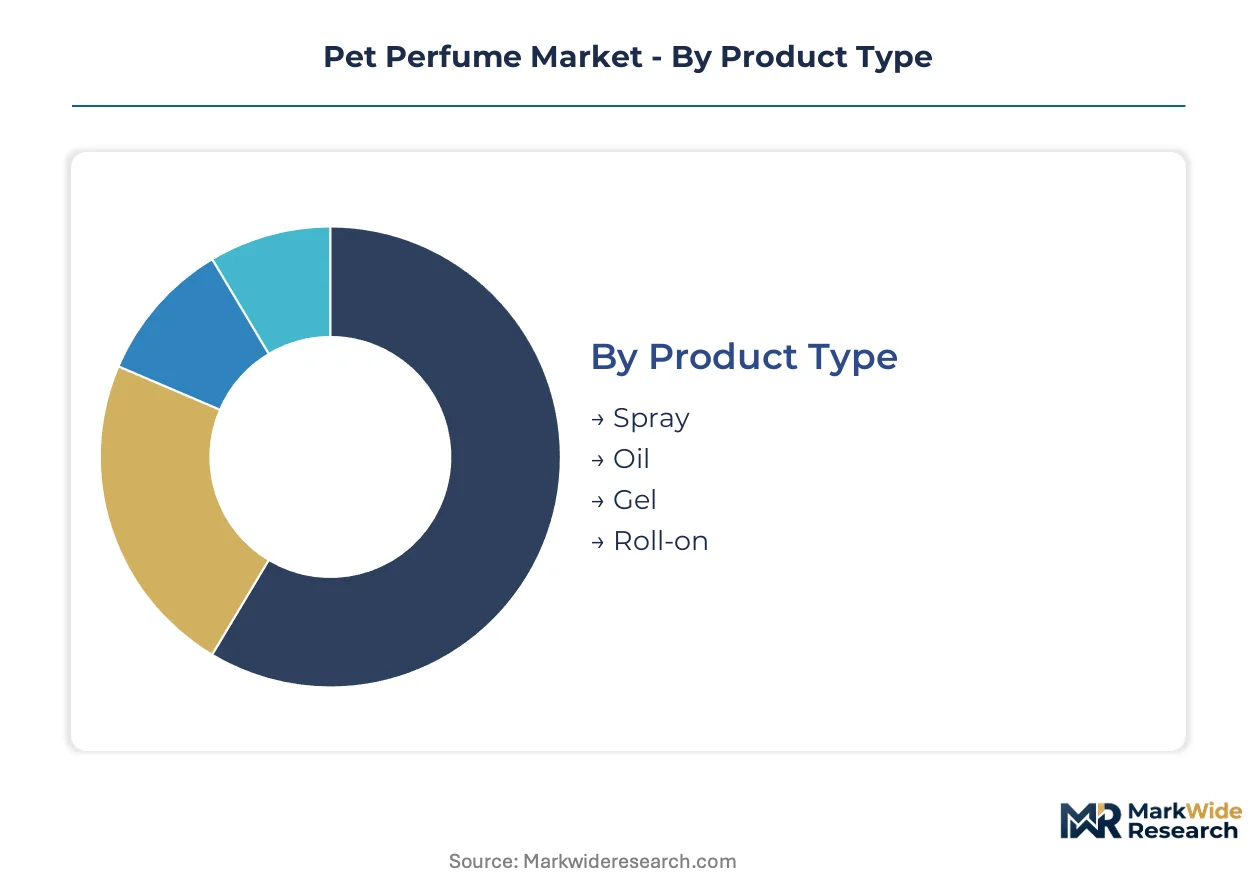
Pet perfume segmentation reveals divergent substitution threats across formulation chemistry and channel access. Each dimension carries distinct competitive exposure to adjacent grooming categories and private-label alternatives.
Product Type:
Alcohol-free water-based substitutes from general pet hygiene lines exert the strongest substitution pressure on spray formats, while oil and gel variants maintain defensive positioning through longevity claims.
- Spray:Water or alcohol-based formulations dispensed through aerosol or pump mechanisms for even coat coverage. Apartment-dwelling urban owners in the United States drive repeat purchase frequency for daily-use convenience formats. Spray retains volume leadership; oil holds the steepest expansion curve.
- Oil:Concentrated lipid-soluble fragrance compounds with extended skin adherence and reduced evaporation rates. Premium buyers seeking multi-day longevity accept per-application cost premiums that sustain margin structures.
- Gel:Viscous polymer-thickened formulations enabling targeted application to paws and coat sections. Professional groomers favor controlled-dispense formats for breed-specific styling protocols.
- Roll-on:Ball-applicator designs limiting overspray in confined vehicle or apartment environments. Travel-oriented packaging sizes capture mobile pet owner segments.
Spray dominates absolute unit movement; oil climbs fastest on premium positioning.
Customer Type:
Channel concentration shapes margin capture, with veterinary and groomer segments commanding price premiums through professional endorsement that mass retail cannot replicate.
- Pet Owners:Direct purchasers motivated by odor control efficacy and humanization-aligned cosmetic positioning. Subscription models lock coastal United States millennials into predictable replenishment cycles.
- Retailers:Specialty pet chains and big-box distributors negotiating slotting fees and promotional allowances. Shelf placement competition intensifies as white-label platforms expand formulation access.
- Groomers:Professional service providers integrating fragrance into bathing and finishing protocols. Breed-specific product lines cement loyalty through technical training relationships.
- Veterinary Clinics:White-coat retail channels validating therapeutic-positioned odor control with clinical credibility. EU REACH pre-certified formulations reduce liability exposure for clinic operators.
Pet owners generate the highest absolute transaction volume; veterinary clinics expand most quickly on professional endorsement premiums.
Fragrance Family:
Citrus profiles face the greatest competitive encroachment from human fragrance crossovers, while woody and spicy territories remain defensible through species-specific formulation requirements.
- Citrus:Limonene and terpene-based fresh profiles dominating puppy and young-dog applications. Sensitive-skin positioning aligns with clean-label chemistry investments.
- Floral:Synthetic and natural rose, jasmine, and lavender compounds appealing to owner aesthetic preferences over pet olfactory sensitivity. Gendered marketing conventions persist in premium positioning.
- Woody:Sandalwood, cedar, and vetiver bases masking stronger natural odors in large-breed applications. Functional performance claims sustain pricing power against substitutes.
- Spicy:Cinnamon, clove, and ginger notes requiring careful concentration limits to avoid feline toxicity. Underdeveloped cat-specific portfolios create expansion headroom.
Citrus leads absolute formulation count; woody gains share fastest on large-breed functional positioning.
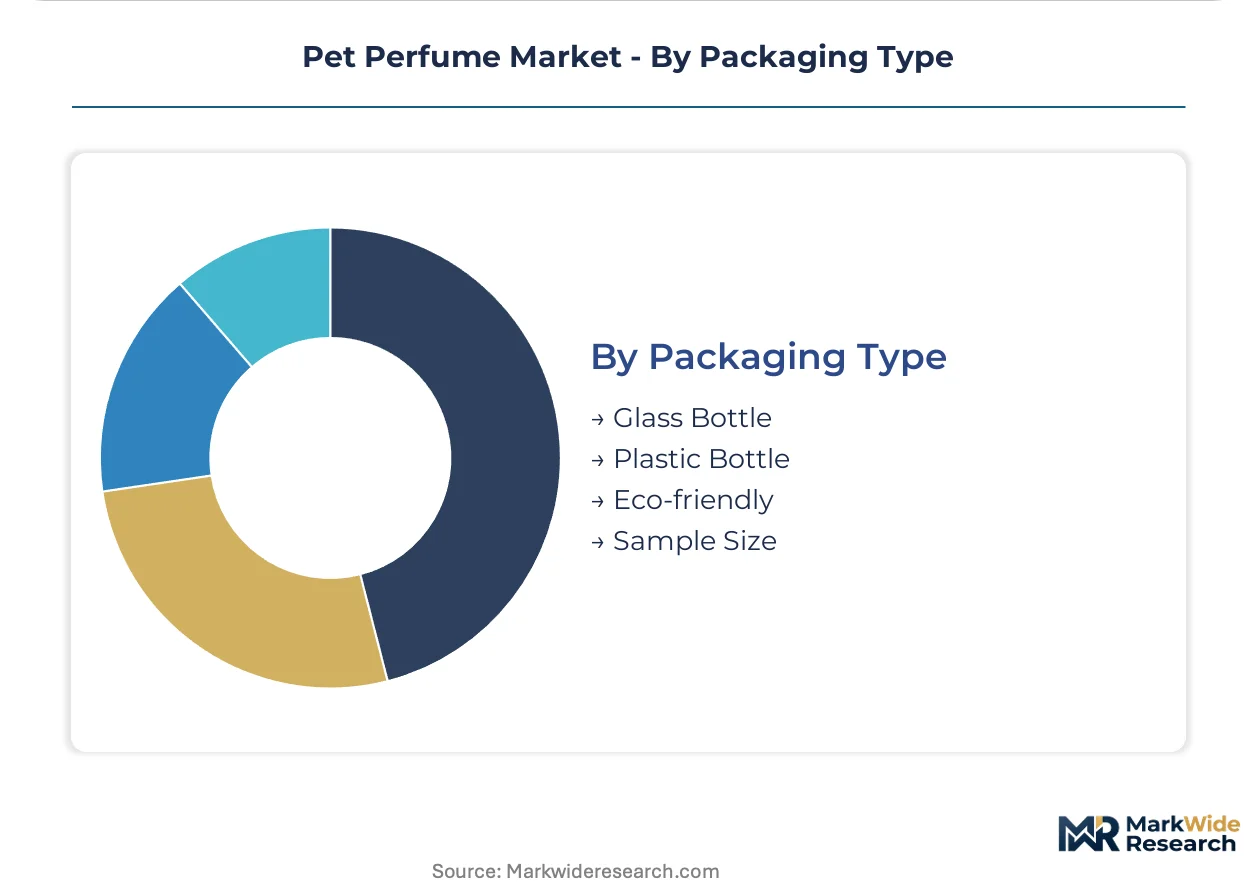
Packaging Type:
Eco-friendly alternatives command sourcing premiums that mass-market producers struggle to absorb, fragmenting competitive position between sustainability leaders and cost defenders.
- Glass Bottle:Premium-positioned containers supporting aesthetic shelf presence and refill program integration. Weight and breakage constraints limit travel-format applicability.
- Plastic Bottle:Lightweight, shatter-resistant PET and HDPE formats dominating volume production and retail distribution economics. Recyclability claims face rising regulatory scrutiny under extended producer responsibility frameworks.
- Eco-friendly:Post-consumer recycled content, biodegradable polymers, and refillable systems aligning with EU Ecolabel trajectory. California Proposition 65 compliance requirements complicate imported sustainable packaging qualification.
- Sample Size:Trial formats reducing purchase risk for fragrance-averse pet owners and enabling subscription box inclusion. Unit economics challenge profitability without conversion to full-size purchase.
Plastic bottle retains absolute volume dominance; eco-friendly packaging expands most rapidly on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in United States coastal metros while European markets absorb compliance cost premiums through REACH-mandated reformulation cycles. This asymmetry reshapes capital allocation across manufacturing footprints.
United States
Urban apartment density in New York and Los Angeles sustains daily-use spray frequency among millennial pet owners. The EPA regulates volatile organic compound emissions in aerosol formats, creating compliance layering for imported formulations. California's Proposition 65 enforcement through the state Office of Environmental Health Hazard Assessment delays market entry for trace contaminant-heavy products.
Germany
Professional groomer channel density in North Rhine-Westphalia supports breed-specific fragrance adoption. ECHA administers REACH authorization requirements for fragrance allergens, extending product development timelines by twelve to eighteen months. Cologne's contract manufacturing cluster attracts white-label platforms seeking EU Ecolabel certification pathways.
United Kingdom
Subscription model penetration in Greater London locks coastal millennials into auto-replenishment cycles. The UK's post-Brexit regulatory alignment with EU REACH creates transitional disclosure obligations for legacy compound libraries. Manchester's specialty pet retail corridor concentrates independent brand distribution.
France
Luxury fragrance crossover demand in Paris elevates aesthetic positioning over functional odor control. ANSM oversees cosmetic-style safety dossiers for pet fragrance products under converging personal care standards. Lyon's biotechnology research cluster enables enzymatic biosynthesis pathways for clean-label aromatic compounds.
Japan
Compact living spaces in Tokyo amplify odor sensitivity among small-breed owners. METI guidelines on volatile organic compound labeling create disclosure requirements distinct from EU and US frameworks. Osaka's grooming supply distribution network anchors professional channel access for premium oil-based formats.
Pet Perfume Market Competitive Environment
Concentration sits with mass-market grooming suppliers leveraging existing retail infrastructure. The vendor base spans three tiers: multinational pet care conglomerates with slotting fee leverage, mid-cap specialists in breed-specific formulations, and direct-to-consumer startups capturing subscription economics. Strategic moves center on white-label platform partnerships and veterinary clinic channel expansion.
Among established grooming supply fabricators, TropiClean and Isle of Dogs occupy positions defined by infrastructure scale and professional channel relationships respectively. Pawfume exemplifies the direct-to-consumer archetype through subscription model execution. These three represent the strategic spectrum: mass retail penetration, professional endorsement leverage, and digital-native customer acquisition.
| Leading Market Players |
|---|
| Pawfume |
| Isle of Dogs |
| TropiClean |
| Animology |
| Bodhi Dog |
| Earthbath |
| Pet Head |
| Captain Zack |
| Lambert Kay |
| Others |
Value Chain & Pricing Dynamics
Essential oil microencapsulation technology displacing conventional alcohol-based carriers is simultaneously redrawing raw material procurement geography toward biotechnology clusters and compressing margin structures for legacy petrochemical-dependent formulators. This substitution dynamic forces mid-tier brands to straddle incompatible cost architectures while premium players capture pricing power through extended-release performance claims.
Pricing Analysis
The customization-premium spread separates breed-specific formulations with professional groomer training integration from mass-market spray variants. Three-tier pricing structure across premium, standard, and economy levels stratifies by fragrance longevity certification and dermatological testing depth. Pricing pressure stems from water-based substitute encroachment from adjacent grooming categories. Mass-market retail buyers exhibit highest price sensitivity; veterinary clinic channels maintain lowest sensitivity through professional endorsement premiums.
Supply Chain Analysis
Fragrance chemist talent concentration in Cologne, Paris, and Lyon contract manufacturing clusters creates chokepoint vulnerability for emerging brands seeking REACH-compliant formulation. Raw material flows draw from enzymatic biosynthesis facilities in France, synthetic petrochemical feedstocks in Germany, and essential oil cultivation in Mediterranean agricultural zones. Single-source vulnerability sits with yeast-fermented aromatic compound suppliers. Distribution runs through specialty pet retail chains, veterinary clinic white-coat networks, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as subscription platforms aggregate urban millennial demand, fragmenting incumbent retail relationships and compressing slotting fee leverage across mass-market channels.
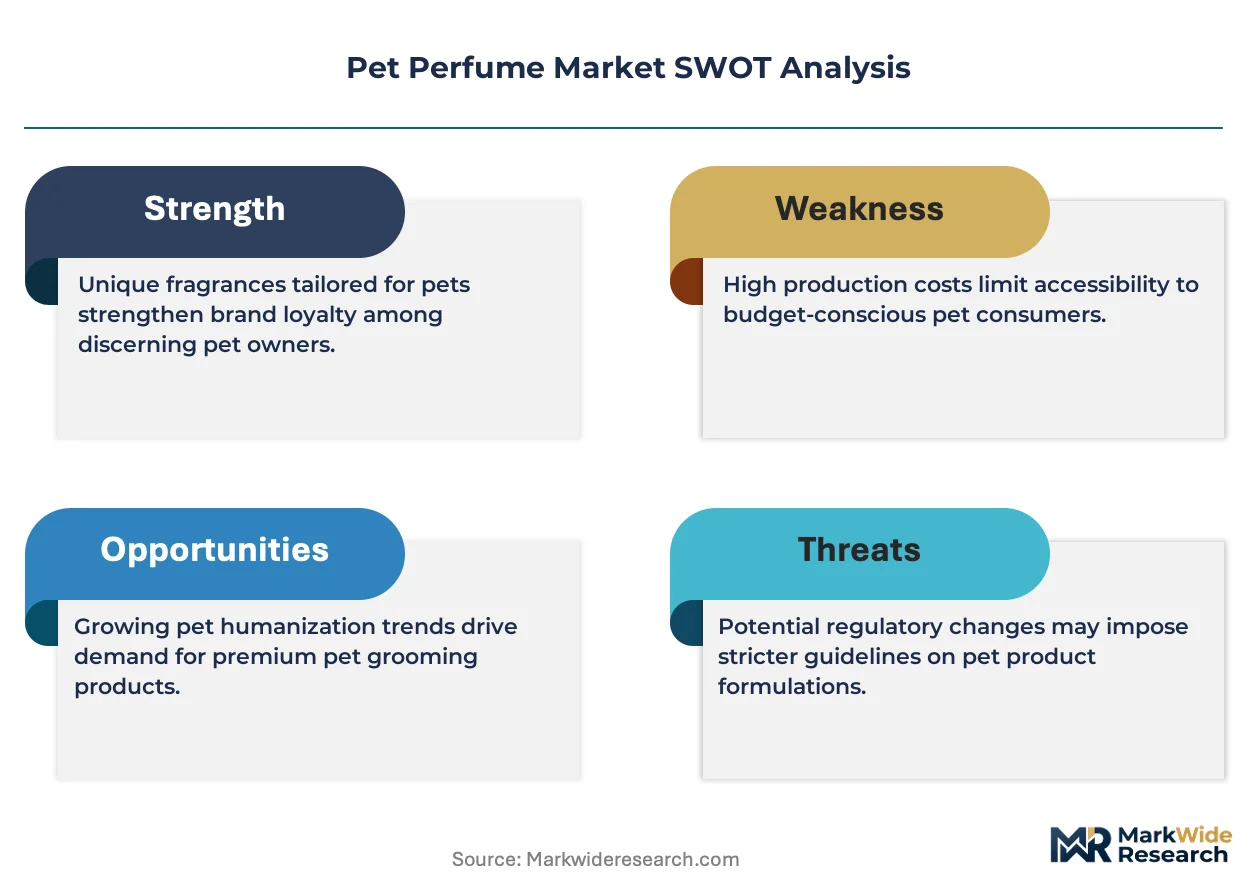
For Market Incumbents: Compound defensive positioning through backward integration into contract manufacturing capabilities in North Rhine-Westphalia and EU Ecolabel certification pre-emption ahead of mandate expansion. Threat substitution from water-based grooming substitutes demands channel control reinforcement through veterinary clinic exclusive distribution partnerships. R&D investment in feline-specific pH-adjusted formulations addresses underpenetrated white space. For New Entrants and Emerging Players: Differentiate on enzymatic biosynthesis clean-label chemistry to bypass REACH authorization timeline disadvantages facing legacy synthetic portfolios. Most penetrable segment sits with cat owners underserved by canine-dominated product architectures. Go-to-market angle targets coastal United States metro subscription platforms with algorithmic scent matching and auto-ship flexibility. For Investors and Strategic Acquirers: The market sits at a formulation-technology-transition phase that favors biotechnology-enabled scent delivery platforms over conventional petrochemical-dependent assets. Long-term viability favors targets with captive essential oil microencapsulation IP and veterinary clinic channel contracts. Signal to watch is EU Ecolabel certification achievement rate as regulatory mandate expansion indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Channel Expansion | Professional endorsement through white-coat retail bypasses crowded mass-market shelf competition. |
| EU Ecolabel Certification Investment | First-mover advantage in biodegradable carrier solvents aligns with regulatory trajectory. |
| Feline-Specific Formulation Development | pH-adjusted products address underpenetrated cat owner segment with stress-reducing scent profiles. |
| Subscription Platform Partnership | Algorithmic scent matching locks urban millennials into predictable revenue streams. |
| Backward Integration into Manufacturing | Captive production in Cologne cluster secures REACH compliance and margin control. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with formulation chemists, professional groomer network managers, veterinary clinic procurement officers, and specialty pet retail category buyers; and secondary validation through EU ECHA REACH authorization databases, EPA volatile organic compound emission filings, customs trade records for fragrance compound imports, and Nielsen retail audit data. Bottom-up demand modeling triangulated against top-down market sizing across product type, customer channel, and fragrance family dimensions.
Across the analysis window, the analytical framework projected value expansion through segmentation-level growth rate derivation incorporating urban household density trends, humanization spending elasticity, and regulatory compliance cost absorption capacity. Modeled dimensions span formulation chemistry, distribution channel, fragrance family, and packaging sustainability tier. CAGR derivation rested on historical trajectory analysis adjusted for technology substitution effects and channel migration patterns. Industry-specific inputs included essential oil microencapsulation adoption curves and subscription platform penetration rates in coastal United States metros.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity, petrochemical feedstock stability, and millennial pet ownership retention would require recalibration. Forecasts embed assumptions regarding regulatory timeline adherence and biotechnology cost parity achievement. Revision becomes warranted when water-based substitute performance crosses functional equivalence thresholds or EU Ecolabel mandate expansion accelerates beyond modeled trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
DTC Pet Food Market
Pet Care Products
Cat Calming Treats Market
Pet Care Products
Italy Pet Food Market
Pet Care Products
Pet Waste Removal Services Market
Pet Care Products
Dog Nail Clippers Market
Pet Care Products
Pet Sitting Market
Pet Care Products
Pet Dental Health Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Dog Clippers Market
Pet Care Products
Canned Wet Cat Food Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Dog Safety Leash Market
Pet Care Products
Europe Cat Food Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Pet Feeder Market
Pet Care Products
Dog Float Market