
 Pet Transport Cage Market | 2026-2036
Pet Transport Cage Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Transport Cage Market Insights
Veterinary clinic procurement consolidation is realigning how manufacturers secure recurring volume contracts. Sherpa™ leverages its brand recognition in soft carriers to sustain direct-to-clinic distribution channels. Taizhou Kuxin Pet Products Co.,Ltd. anchors its competitive stance through manufacturing scale in molded plastic enclosures. Richell USA, Inc. differentiates via specialized metal crate designs that meet institutional durability requirements.
Pet transport cages are rigid or semi-rigid enclosures engineered to restrain and protect companion animals during vehicular, aerial, or manual transit, typically incorporating ventilation apertures, secure latching mechanisms, and structural walls rated for impact resistance. Hard-shell plastic variants dominate commercial aviation compliance due to their stackability and ease of sanitization, while soft carriers command premium positioning among urban pet owners prioritizing portability. Fabric-based backpacks represent the fastest-growing configuration, though margin pools remain concentrated in extra-large metal crates purchased by airlines and veterinary chains.
IATA Live Animals Regulations govern international air transport dimensions and material safety, while the USDA enforces welfare standards for ground transit of regulated species. The FAA mandates cargo hold restraint specifications for commercial carriers, creating compliance barriers for uncertified imports. Stakeholders must monitor evolving carrier-specific size restrictions and antimicrobial material mandates to align product development with procurement criteria.
Market Dynamics
Commercial aviation procurement consolidation is compressing supplier margins while IATA Live Animals Regulations raise dimensional and ventilation compliance thresholds, forcing manufacturers to retool hard-shell production lines or exit airline cargo channels entirely.
Growth Catalysts
- IATA Live Animals Regulations:Updated dimensional standards for hold transport are mandating reinforced ventilation apertures and impact-rated latching mechanisms, driving replacement cycles across airline cargo divisions.
- Veterinary clinic consolidation:Multi-site practice chains in the United States are standardizing on premium hard-shell crates for patient transport, creating recurring volume contracts with direct-to-clinic distributors.
- Fabric-based backpack carriers:Urban pet owners prioritizing manual transit portability are pulling soft carrier innovation toward lightweight, airline-compatible configurations with integrated tether systems.
Market Restraints
- Petrochemical input volatility:Virgin polypropylene and ABS resin prices fluctuate with crude oil benchmarks, compressing margin pools for molded plastic enclosure manufacturers locked into annual airline contracts.
- Guangdong manufacturing concentration:Hard-shell crate assembly clusters in southern China create single-point vulnerability for North American and European aviation procurement channels facing tariff or logistics disruptions.
- Soft carrier durability ceiling:Fabric-based enclosures face structural load limits below 15 kilograms, excluding large-breed applications from premium positioning in veterinary and airline segments.
Strategic Opportunities
- Antimicrobial material mandates:Veterinary procurement specifications in Germany and France are beginning to require silver-ion or copper-infused plastics, creating first-mover advantage for compliant suppliers.
- India domestic aviation expansion:IndiGo and Air India cargo divisions are launching companion animal programs without established supplier relationships, opening white-space for IATA-certified entrants.
- Smart crate integration:Convergence of IoT temperature sensors and GPS tracking is enabling real-time cargo hold monitoring, with airlines in the United Arab Emirates piloting connected enclosures for high-value pet transit.
Industry Challenges
- IATA certification timeline compression:Laboratory testing for impact resistance and ventilation flow rates now extends 14-18 months, delaying product launches and freezing R&D budgets.
- Multi-material welding complexity:Hybrid crates combining aluminum framing with polymer panels require specialized friction-stir welding expertise scarce in traditional pet product manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Transport Cage Market |
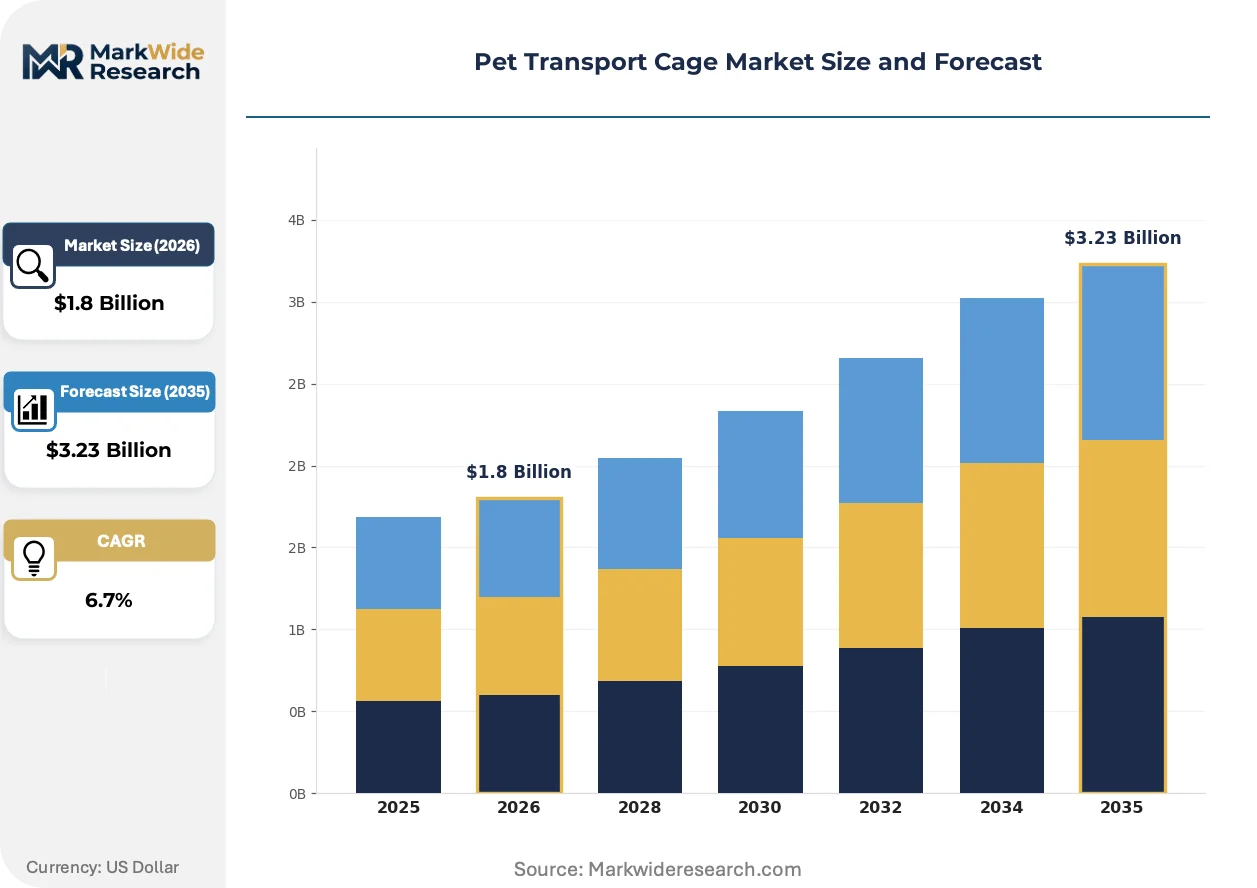
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Shell, Soft Carrier, Crate, Backpack Material: Plastic, Metal, Fabric, Wood Size: Small, Medium, Large, Extra Large End User: Pet Owners, Veterinary Clinics, Airlines, Pet Shops |
| Companies Covered | Quality Cage Crafters, Richell USA, Inc., Knapp Manufacturing, Inc., Pet Palace Limited, Kritta-Krates, Sherpa™, Taizhou Kuxin Pet Products Co.,Ltd., Suzhou Inspirer Pet Products Co.,Ltd., Nantong Yuanyang Leisure Products Co.,Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Transport Cage Market Trends and Innovations
Material science advances and regulatory digitization are fragmenting traditional product categories while reshaping how manufacturers validate compliance and access procurement channels.
Modular polymer framing systems are replacing fixed-dimension hard-shell designs, allowing carriers to collapse for urban storage and expand for aviation compliance. Airlines including Lufthansa Cargo and American Airlines are piloting these configurations for frequent-flyer pet programs. The technology is modularizing supplier relationships, as carriers source frame extrusions, panel fabrics, and latching hardware from separate specialists rather than single-source enclosure manufacturers.
REACH substance restrictions on phthalates and heavy metals in polymer formulations are forcing reformulation of legacy ABS and polycarbonate blends used in stackable aviation crates. European manufacturers face 18-month transition timelines to secure ECHA-compliant material certifications. Veterinary chains in France and Germany are accelerating procurement shifts toward REACH-verified suppliers, creating compliance-driven supplier turnover.
Direct-to-consumer configuration tools are displacing traditional distributor-led specification processes, with urban pet owners designing custom dimensions through manufacturer portals. This channel compression bypasses veterinary and retail intermediaries that historically controlled product visibility. The pattern concentrates in United States coastal metropolitan markets where same-day delivery logistics support made-to-order production workflows.
Pet Transport Cage Market Segmentation
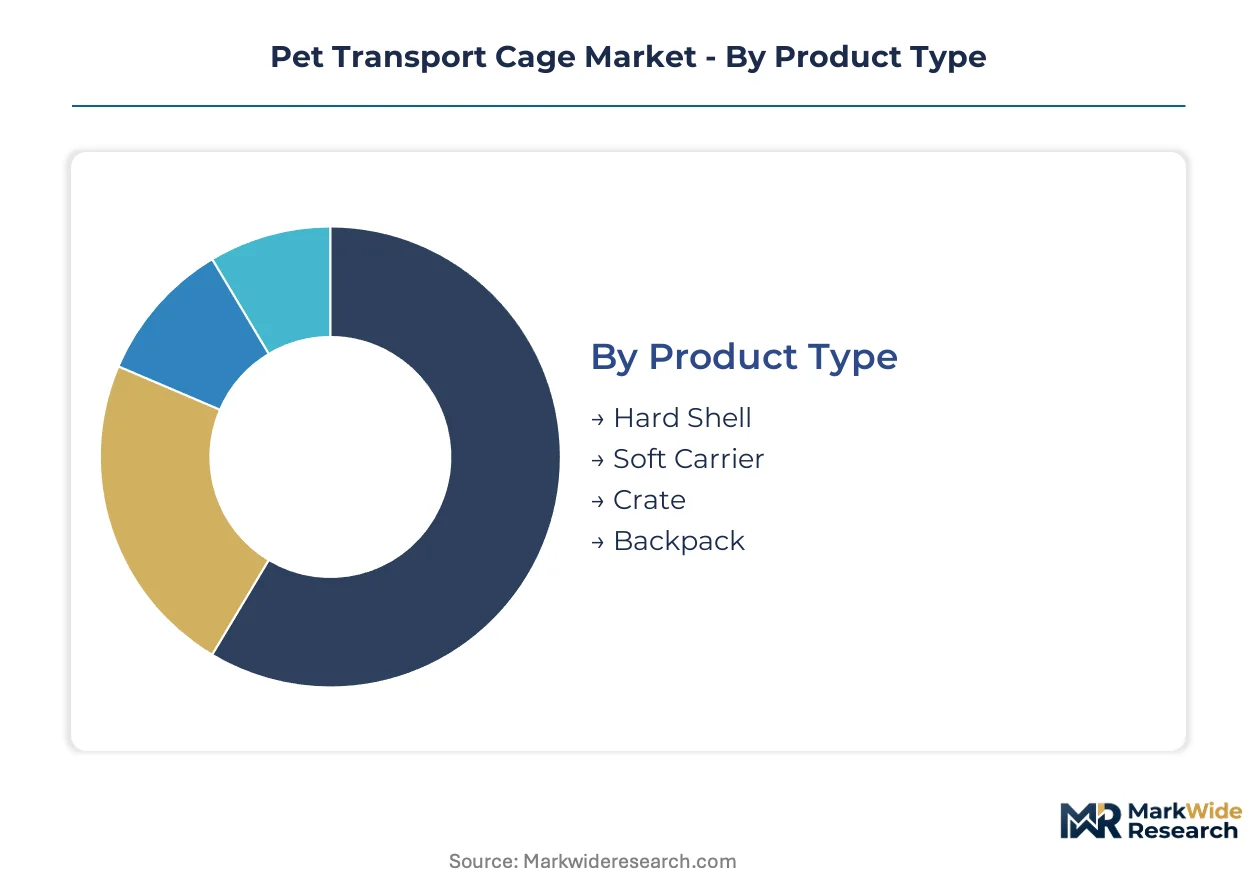
Pet transport cage procurement channels diverge sharply across use cases, with aviation compliance requirements, veterinary sterilization protocols, and urban portability needs each dictating distinct product specifications. Manufacturers must align R&D investments with the replacement cycles and margin structures of their target segments.
Product Type:
Upgrade cycles vary dramatically across enclosure formats, with IATA certification mandates forcing airline-facing categories into compressed retooling timelines while consumer segments follow discretionary replacement patterns.
- Hard Shell:Molded polymer or ABS enclosures rated for cargo hold stackability and impact resistance. Airlines in the United States and Germany concentrate procurement here for checked baggage programs, with ventilation aperture redesigns now mandatory under updated IATA Live Animals Regulations.
- Soft Carrier:Fabric-walled enclosures with integrated tether points and collapsible frames. Urban pet owners in coastal metropolitan markets pull demand toward airline-compatible dimensions below 18 inches, though structural load limits exclude large-breed applications.
- Crate:Rigid metal or polymer enclosures designed for veterinary transport and extended confinement. Multi-site practice chains standardize on premium variants with antimicrobial coatings, creating recurring volume contracts.
- Backpack:Dual-strap fabric configurations with mesh ventilation panels and integrated hydration access. Manual transit portability drives fastest adoption among apartment-dwelling pet owners in dense Japanese and South Korean cities.
Hard Shell sits at the top of the volume ranking, with Backpack climbing the fastest.
Material:
Cost tier differentiation separates aviation-certified suppliers from commodity producers, with regulatory compliance costs creating moats around premium material grades.
- Plastic:Virgin polypropylene and ABS resin formulations dominate stackable aviation crates. REACH substance restrictions in Europe and tariff exposure on Guangdong-sourced assemblies compress margin pools for manufacturers locked into annual airline contracts.
- Metal:Aluminum or steel framing with polymer infill panels. Veterinary chains and commercial kennel operators prioritize institutional durability, with specialized welding expertise scarce outside established industrial bases.
- Fabric:Nylon or polyester composites with reinforced stitching. Urban portability applications favor lightweight configurations, though 15-kilogram structural ceilings limit addressable market scope.
- Wood:Plywood or bamboo laminates with metal hardware. Boutique positioning in residential and aesthetic-conscious segments, with moisture resistance limitations excluding aviation and clinical use cases.
Plastic commands the dominant revenue share, while Metal gains traction fastest in institutional procurement channels.
Size:
Customer type stratification maps directly onto dimensional requirements, with airlines and veterinary networks anchoring demand at scale extremes while individual owners cluster in mid-range portability formats.
- Small:Enclosures under 18 inches designed for cats and toy breeds. In-cabin aviation compliance and urban apartment storage constraints concentrate demand in United States and Japanese metropolitan markets.
- Medium:18-to-24-inch configurations balancing portability with species range. Retail channel volume leader, though margin compression from direct-to-consumer configuration tools is accelerating.
- Large:24-to-32-inch enclosures for medium breeds and multi-pet transport. Veterinary clinic consolidation in the United States standardizes procurement here for patient intake workflows.
- Extra Large:32-plus inch crates for large breeds and commercial cargo. Airlines and institutional breeders generate concentrated demand, with IATA dimensional standards forcing compliance-driven supplier turnover.
Medium generates the highest unit volumes, with Extra Large expanding most quickly as aviation cargo programs scale.
End User:
Application-specific requirements fragment procurement criteria, with certification mandates, sterilization protocols, and aesthetic preferences each shaping distinct vendor relationships.
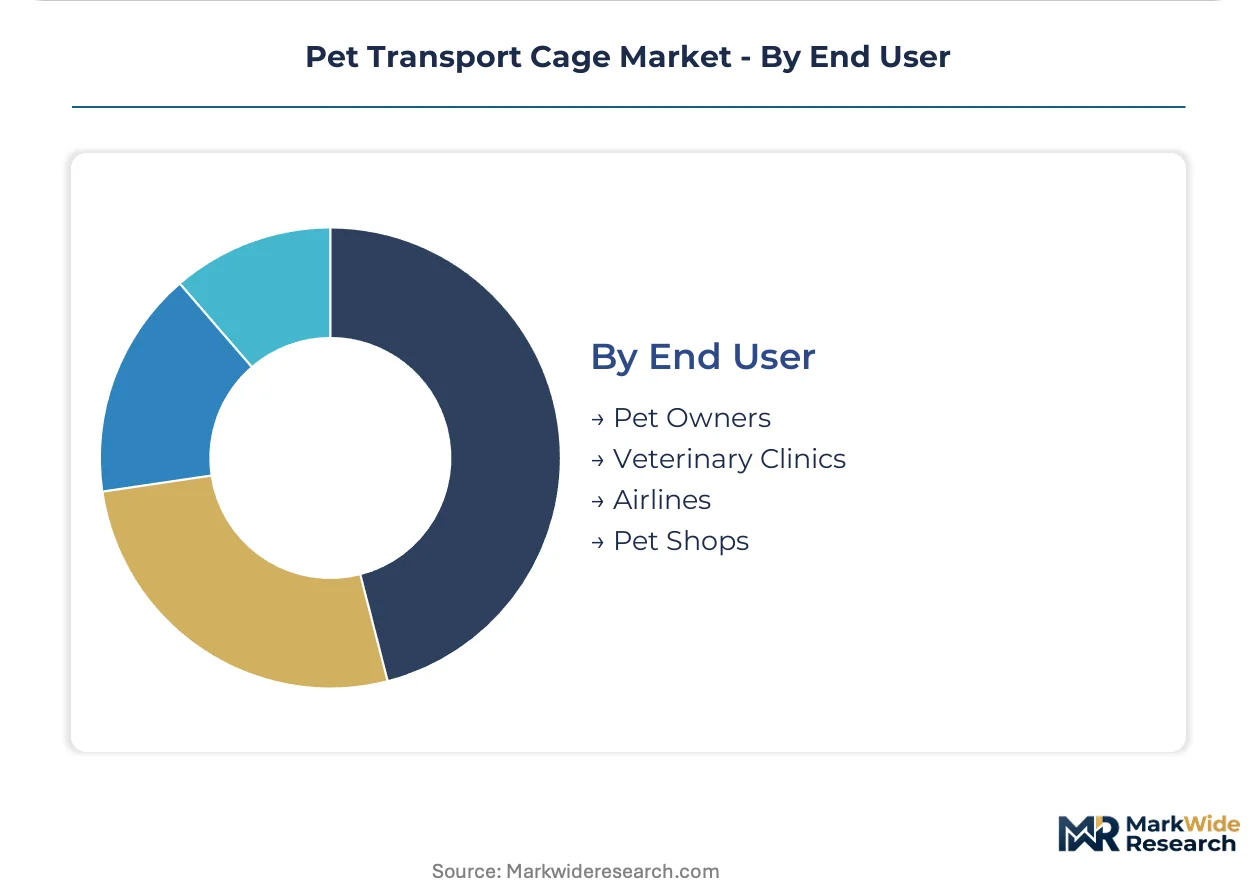
- Pet Owners:Individual consumers purchasing through retail or direct-to-manufacturer channels. Configuration tools and same-day delivery logistics in United States coastal markets are displacing traditional distributor intermediaries.
- Veterinary Clinics:Multi-site practice chains and independent operators requiring sterilizable, durable transport solutions. Antimicrobial material mandates in France and Germany are accelerating procurement shifts toward compliant suppliers.
- Airlines:Commercial cargo divisions and frequent-flyer pet programs with IATA-certified specifications. Procurement consolidation is compressing supplier margins while raising compliance barriers for uncertified imports.
- Pet Shops:Retail intermediaries stocking consumer-facing soft carriers and entry-level hard shells. Channel compression from manufacturer direct sales is eroding historical positioning in specification influence.
Pet Owners represent the broadest addressable base, with Airlines driving the steepest specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States aviation cargo programs outpace German procurement volumes, while Chinese manufacturing clusters supply both markets through divergent certification pathways.
United States
FAA cargo hold restraint specifications and USDA welfare standards govern ground transit protocols. Multi-site veterinary chains in Texas and Florida standardize on premium hard-shell crates, compressing supplier margins through consolidated procurement. Taizhou Kuxin Pet Products Co.,Ltd. anchors supply relationships with North American distributors from its Zhejiang manufacturing base.
Germany
REACH substance restrictions on phthalates and heavy metals force 18-month reformulation timelines for ABS and polycarbonate blends. ECHA-compliant material certifications now determine supplier eligibility for veterinary chains in Bavaria and North Rhine-Westphalia. Lufthansa Cargo pilots modular polymer framing systems for frequent-flyer pet programs.
China
Guangdong hard-shell crate assembly clusters face tariff exposure and logistics disruptions for North American aviation procurement channels. MIIT industrial standards for polymer formulations create domestic compliance layers parallel to IATA requirements. Suzhou and Nantong manufacturers supply fabric-based enclosures to Japanese and South Korean urban markets.
India
IndiGo and Air India cargo divisions launch companion animal programs without established supplier relationships, opening white-space for IATA-certified entrants. BIS quality certification requirements for imported pet products create procedural barriers for uncertified Chinese assemblies. Maharashtra veterinary networks drive demand for sterilizable metal crate configurations.
Japan
METI consumer safety standards and JIS specifications for pet product durability shape domestic procurement criteria. Backpack carriers dominate manual transit in Tokyo and Osaka apartment markets, pulling soft carrier innovation toward sub-15-kilogram configurations. Kansai-based distributors source fabric enclosures from Zhejiang and Jiangsu manufacturing clusters.
Pet Transport Cage Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply channels. The vendor base stratifies between aviation-certified hard-shell manufacturers, veterinary-durable metal crate fabricators, and urban-portability soft carrier designers. Three archetypes dominate: Guangdong-centered plastic molders serving airline contracts, Japanese precision metalworkers targeting institutional durability specifications, and brand-recognized soft goods specialists leveraging direct-to-clinic distribution. Competitive moves concentrate on IATA certification acquisition and antimicrobial material compliance rather than price-based displacement.
Within the aviation-certified tier, Taizhou Kuxin Pet Products Co.,Ltd. and Suzhou Inspirer Pet Products Co.,Ltd. represent Zhejiang and Jiangsu manufacturing scale archetypes, while Sherpa™ occupies a position exemplifying brand-anchored direct distribution. Richell USA, Inc. sits within the institutional durability specialist category. Quality Cage Crafters and Nantong Yuanyang Leisure Products Co.,Ltd. anchor regional manufacturing concentrations in the United States and Jiangsu province respectively.
| Leading Market Players |
|---|
| Quality Cage Crafters |
| Richell USA, Inc. |
| Knapp Manufacturing, Inc. |
| Pet Palace Limited |
| Kritta-Krates |
| Sherpa™ |
| Taizhou Kuxin Pet Products Co.,Ltd. |
| Suzhou Inspirer Pet Products Co.,Ltd. |
| Nantong Yuanyang Leisure Products Co.,Ltd. |
| Others |
Pricing and Supply Chain Analysis
Virgin polypropylene and ABS resin feedstock costs transmit directly from Guangdong petrochemical complexes through three pricing tiers: IATA-certified aviation crates, antimicrobial-coated veterinary enclosures, and entry-level retail soft carriers. Airlines lock annual contracts at fixed resin baselines, while spot-market volatility squeezes mid-tier manufacturers without backward integration into polymer compounding.
Pricing Analysis
Capacity additions in Zhejiang and Jiangsu provinces are reshaping price floors for molded plastic enclosures. Three-tier pricing structure across IATA-certified, REACH-compliant, and standard retail levels separates aviation procurement at premium fixed-contract rates from veterinary antimicrobial grades and commoditized soft carriers. Cost compression in mid-tier hard-shell segments intensifies because veterinary chains demand silver-ion formulations without volume scale to amortize R&D. Airlines exhibit lowest price sensitivity due to regulatory non-substitutability, while urban pet owners buying fabric backpacks show highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from Lufthansa Cargo and American Airlines mandate qualified suppliers in both Guangdong and Zhejiang manufacturing clusters. Raw material dependencies center on Saudi-sourced virgin polypropylene, Korean ABS resin, and Taiwanese precision latching hardware. Single-source vulnerability concentrates in friction-stir welding expertise for aluminum-polymer hybrid frames, scarce outside Osaka industrial corridors. Distribution runs through veterinary GPOs in Texas and Florida, airline procurement divisions, and direct-to-consumer portals in coastal United States metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where IATA Live Animals Regulations mandate 14-18 month certification cycles that freeze out uncapitalized competitors and sustain pricing power for compliant incumbents.
For Market Incumbents: Anchor certification pipelines against timeline compression by securing dedicated laboratory partnerships for impact resistance and ventilation flow testing. Defensive consolidation moves include captive supply of antimicrobial polymer formulations and exclusive frame extrusion contracts with Suzhou specialists. Threat from modular polymer framing systems piloted by Lufthansa Cargo demands rapid co-development partnerships with component specialists rather than single-source enclosure manufacturing.
For New Entrants and Emerging Players: Begin with white-space targeting of India domestic aviation expansion where IndiGo and Air India cargo divisions lack established IATA-certified supplier relationships. Most penetrable segment sits in sub-15-kilogram fabric backpack carriers for Japanese and South Korean urban markets, bypassing hard-shell certification barriers entirely. Go-to-market angle leverages direct-to-consumer configuration tools with same-day delivery logistics in United States coastal metropolitan markets.
For Investors and Strategic Acquirers: Consolidation pressure builds where veterinary clinic procurement standardization concentrates volume among fewer suppliers capable of antimicrobial material compliance. Long-term viability over the projection horizon favors manufacturers with dual IATA and REACH certification moats and backward integration into polymer compounding. Acquisition target archetype: Zhejiang-based molders with aviation contracts but lacking European material compliance. Signal to watch: BIS quality certification enforcement in India that would disqualify uncertified Chinese assemblies and redirect procurement toward compliant entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| IATA Certification Investment | 14-18 month laboratory testing cycles create regulatory barriers against commodity imports. |
| Antimicrobial Material Integration | Silver-ion and copper-infused formulations unlock veterinary procurement in Germany and France. |
| Modular Frame System Development | Collapsible polymer configurations align with Lufthansa Cargo frequent-flyer pet program pilots. |
| India Market Entry | IndiGo and Air India cargo divisions launch companion animal programs without incumbent supplier lock-in. |
| Direct-to-Consumer Channel Buildout | Configuration tools bypass veterinary and retail intermediaries in United States coastal metros. |
Research Methodology
Coverage spans United States, Germany, China, India, and Japan, with primary inputs from each regional cluster combining structured interviews with airline cargo procurement officers, veterinary clinic chain purchasing managers, polymer compounder technical directors, and IATA certification laboratory supervisors. Secondary validation draws from FAA cargo hold restraint specifications, ECHA REACH substance restriction databases, USDA welfare standard filings, and MIIT industrial polymer formulation standards. Bottom-up volume modeling triangulates against top-down value projections across enclosure format categories.
Rate-of-change decomposition separates volume growth from price mix effects across the analysis window. Segmentation dimensions modeled include product type (hard shell, soft carrier, crate, backpack), material grade (aviation-certified polymer, antimicrobial metal, standard fabric), size tier, and end-user procurement channel. CAGRs derive from replacement cycle analysis tied to IATA regulatory revision timelines and veterinary clinic consolidation patterns. Industry-specific forecast inputs incorporate petrochemical input cost trajectories and carrier-specific dimensional restriction changes.
Several conditions sit outside the modeled scope, including abrupt tariff reclassification of Guangdong-sourced assemblies, force majeure disruptions to Saudi polypropylene supply, and unilateral carrier size restriction changes outside IATA coordination. Forecasts reflect documented assumptions about certification timeline stability and antimicrobial mandate geographic diffusion. Deviation in IATA Live Animals Regulations revision frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Smart Pet Collar Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
USA Bird Food Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Weight Management Dog Food Market
Pet Care Products
Cat Litter Market
Pet Care Products
South America Pet Diet Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Pet Feeder Market
Pet Care Products
Dog Clothing and Accessories Market
Pet Care Products
Pet Treats Market
Pet Care Products
Pet Beds Market
Pet Care Products
Netherlands Pet Boarding Market