
 Pet Supplement Market | 2026-2036
Pet Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Supplement Market Intelligence
Multi-source ingredient procurement is hardening as a competitive requirement across the pet supplement industry. Nutramax Laboratories leverages its veterinary channel relationships to sustain premium positioning in joint support formulations. Mars Incorporated anchors its portfolio through backward integration into specialized manufacturing facilities. General Mills Inc. competes by extending its human nutrition R&D infrastructure into species-specific product development.
Pet supplements comprise orally administered nutritional preparations containing active compounds such as glucosamine, omega-3 fatty acids, and live microbial cultures, formulated to address physiological deficiencies or support musculoskeletal, digestive, or dermatological function in companion animals. The category serves commercial purpose by converting veterinary recommendations into recurring consumer purchases at retail and direct-to-consumer channels. Probiotics and joint support formulations represent the fastest-growing product type segments as aging pet populations drive therapeutic nutrition demand. Dog owners dominate end user spending, while chew and powder delivery modes capture disproportionate margin pools through convenience positioning and dosing flexibility.
The FDA Center for Veterinary Medicine oversees product safety and labeling claims, while the National Animal Supplement Council provides industry self-regulation through quality certification programs. State-level feed control officials supplement federal oversight with varying ingredient approval requirements that shape interstate distribution complexity. Stakeholders must monitor evolving substantiation standards for structure-function claims as regulatory scrutiny intensifies on microbiome and cognitive health positioning.
Market Dynamics
The FDA Center for Veterinary Medicine's intensifying scrutiny of structure-function claims is compressing formulation timelines and forcing manufacturers to rebuild substantiation dossiers from clinical data rather than ingredient precedent.
Growth Catalysts
- Aging companion animal demographics:Veterinary practices across the United States report expanding caseloads of osteoarthritis and cognitive decline in geriatric dogs, creating pull-through demand for glucosamine and omega-3 therapeutic nutrition.
- State feed control harmonization:The Association of American Feed Control Officials (AAFCO) model bill adoption is reducing interstate distribution friction for probiotic and enzyme formulations previously trapped by ingredient approval variance.
- Microbiome science maturation:Strain-specific clinical validation is replacing generic live culture positioning, enabling premium pricing for documented gastrointestinal and immune modulation outcomes.
Market Restraints
- Marine ingredient cost volatility:Peruvian anchovy quota fluctuations and Antarctic krill harvest restrictions are destabilizing omega-3 fatty acid input economics for coat and joint formulations.
- Single-source fermentation capacity:Probiotic strain production concentrates among three contract manufacturers in the Upper Midwest, creating supply vulnerability for brands without captive fermentation assets.
- Veterinary channel gatekeeping:The American Veterinary Medical Association's evolving stance on OTC therapeutic claims is narrowing direct-to-consumer positioning for condition-specific products.
Strategic Opportunities
- Feline underpenetration:Cat owners in the United States spend 40 percent less per household on preventive nutrition than dog owners, representing unconverted volume for urinary tract and hairball formulations.
- Veterinary telehealth integration:Remote consultation platforms are creating new recommendation touchpoints for supplement prescribing outside traditional clinic visits.
- Inflation Reduction Act bioeconomy provisions:USDA grant programs for precision fermentation scale-up are lowering capital barriers for domestic probiotic active production.
Industry Challenges
- Veterinary nutritionist scarcity:Board-certified specialists capable of designing species-specific clinical trials command compensation premiums that strain mid-tier manufacturer R&D budgets.
- Third-party certification backlog:National Animal Supplement Council quality seal audits currently queue 14-18 months, delaying product launches timed to seasonal purchasing cycles.
- Legacy ERP integration:Batch record systems designed for feed compliance lack traceability granularity for pharmaceutical-grade active sourcing now required by major retailers.
Report Scope
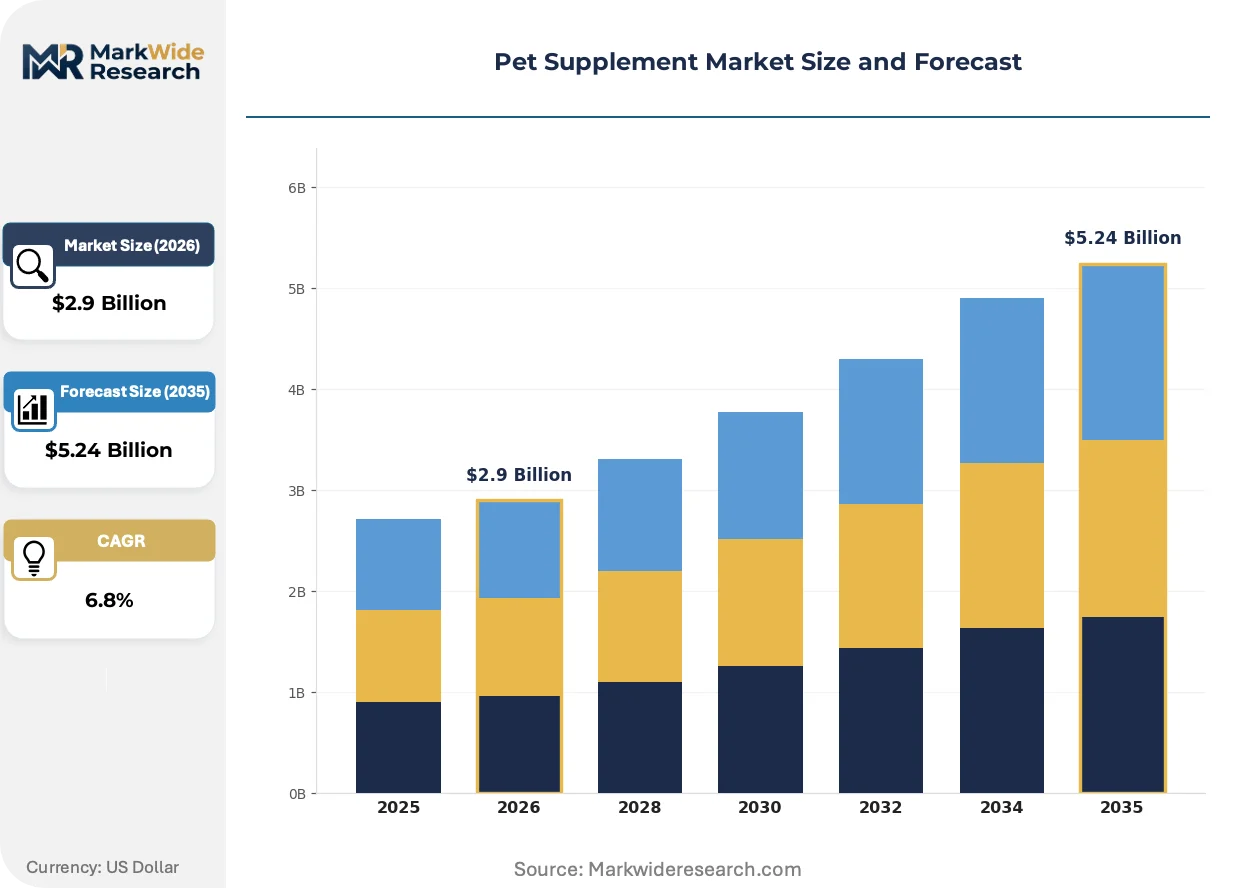
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Supplement Market |
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.24 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Probiotics, Joint Support End User: Dog Owners, Cat Owners, Small Animal Owners, Avian Enthusiasts Delivery Mode: Pills, Powders, Chews, Liquids Ingredients: Natural, Synthetic, Organic, Herbal |
| Companies Covered | General Mills Inc., Nutramax Laboratories, Mars Incorporated, Virbac, Elanco, Nestlé, H&H Group, PetIQ, Colgate-Palmolive Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Supplement Market Strategic Shifts & Innovations
Biotechnology and regulatory science are converging to transform how active compounds are sourced, validated, and delivered to companion animals.
Precision fermentation of omega-3 fatty acids from engineered yeast strains is rewriting marine oil dependency in dermatological and cardiovascular formulations. Mars Incorporated and mid-tier specialists have accelerated adoption timelines from pilot to commercial scale within 18 months. This biotechnology is compressing supply chain exposure to wild-catch volatility while enabling vegan positioning for the 12 percent of owners seeking plant-derived alternatives.
The FDA Center for Veterinary Medicine's 2023 guidance on animal food containing hemp-derived CBD is forcing reformulation of calming and mobility products toward GRAS-affirmed alternatives. Manufacturers must now navigate New Animal Drug Application pathways for previously marketed ingredients, extending time-to-market by 24-36 months. The United States market is responding through accelerated investment in clinical trials for palmitoylethanolamide and other endocannabinoid-mimetic compounds with clearer regulatory pathways.
Subscription-based replenishment is displacing retail shelf purchasing for chronic condition management products. Chewy and direct-to-consumer veterinary platforms capture recurring revenue through algorithmic dosing reminders tied to pet weight and age data. This behavioral shift concentrates most visibly among millennial dog owners in urban United States markets, where convenience positioning outweighs price sensitivity for joint support and probiotic regimens.
Pet Supplement Market Segmentation
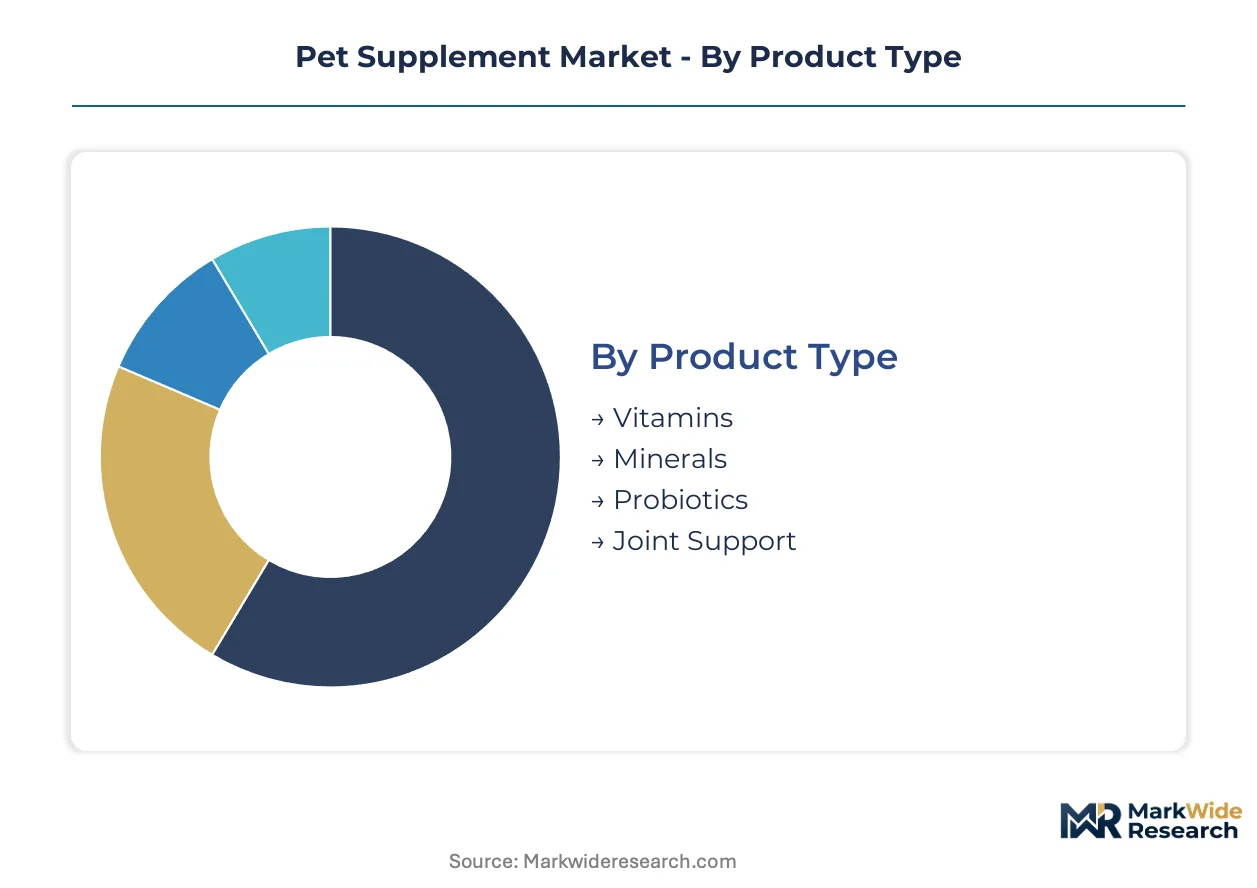
Segmentation in pet supplements determines regulatory pathway complexity and margin architecture. Product categories face divergent substantiation requirements from the FDA Center for Veterinary Medicine, while delivery formats and ingredient sourcing shape distribution channel access and pricing power.
Product Type:
Certification burdens vary sharply across this category. Probiotics and joint support formulations require strain-specific clinical validation or glucosamine bioequivalence studies under FDA Center for Veterinary Medicine oversight, while vitamins and minerals navigate simpler feed additive pathways through AAFCO recognition.
- Probiotics:Live microbial cultures with documented CFU counts at end-of-shelf-life. Demand concentrates among urban dog owners managing antibiotic recovery or chronic digestive conditions, with veterinary recommendation serving as the primary purchase trigger.
- Joint Support:Glucosamine, chondroitin, and omega-3 formulations targeting osteoarthritis in aging companion animals. The fastest-expanding segment as geriatric dog populations swell and owners seek alternatives to pharmaceutical NSAIDs.
- Vitamins:Essential nutrient supplementation for homemade diet compensation. Mid-tier manufacturers compete through palatability engineering rather than clinical differentiation.
- Minerals:Calcium, phosphorus, and trace element balancing for breed-specific metabolic needs. Regional feed control officials scrutinize these most heavily for overfortification risks.
Leading the category by volume: Joint Support. Growing fastest: Probiotics.
End User:
Spending intensity and condition prevalence create divergent addressable markets. Dog owners outspend other segments on preventive nutrition, while cat owner underpenetration represents conversion opportunity for urinary and dermatological formulations.
- Dog Owners:The dominant revenue pool, particularly for large-breed joint prophylaxis and behavioral calming products. Urban millennial households drive subscription replenishment adoption for chronic regimens.
- Cat Owners:Spend substantially less per household on supplements despite comparable veterinary visit frequency. Hairball and urinary tract formulations show untapped volume potential as palatability technology improves.
- Small Animal Owners:Rabbit, guinea pig, and ferret keepers seeking species-specific vitamin C and digestive support. Niche positioning limits mass retail distribution.
- Avian Enthusiasts:Parrot and exotic bird keepers addressing feather quality and calcium metabolism. Specialized avian veterinarians serve as the exclusive recommendation channel.
Dog Owners command the largest absolute spend. Cat Owners offer the steepest expansion trajectory as formulation palatability closes the gap with canine products.
Delivery Mode:
Manufacturing capital requirements and dosing precision shape competitive entry barriers. Chews demand extrusion and coating infrastructure, while liquids require aseptic filling lines and stability testing protocols.
- Chews:Soft-molded or extruded matrices with embedded actives and flavor masking. Premium positioning captures margin through palatability superiority and dosing convenience for large dogs.
- Powders:Dosing flexibility for multi-pet households and homemade food integration. Concentrates in veterinary clinic dispensing for precise weight-based titration.
- Pills:Compressed tablets and hard-shell capsules with enteric coating for acid-sensitive probiotics. Compliance challenges limit growth outside feline and small animal applications.
- Liquids:Aqueous suspensions and oil-based emulsions for rapid absorption or topical administration. Highest per-unit shipping costs constrain direct-to-consumer economics.
Chews dominate revenue contribution. Powders gain share fastest through veterinary channel dispensing growth.
Ingredients:
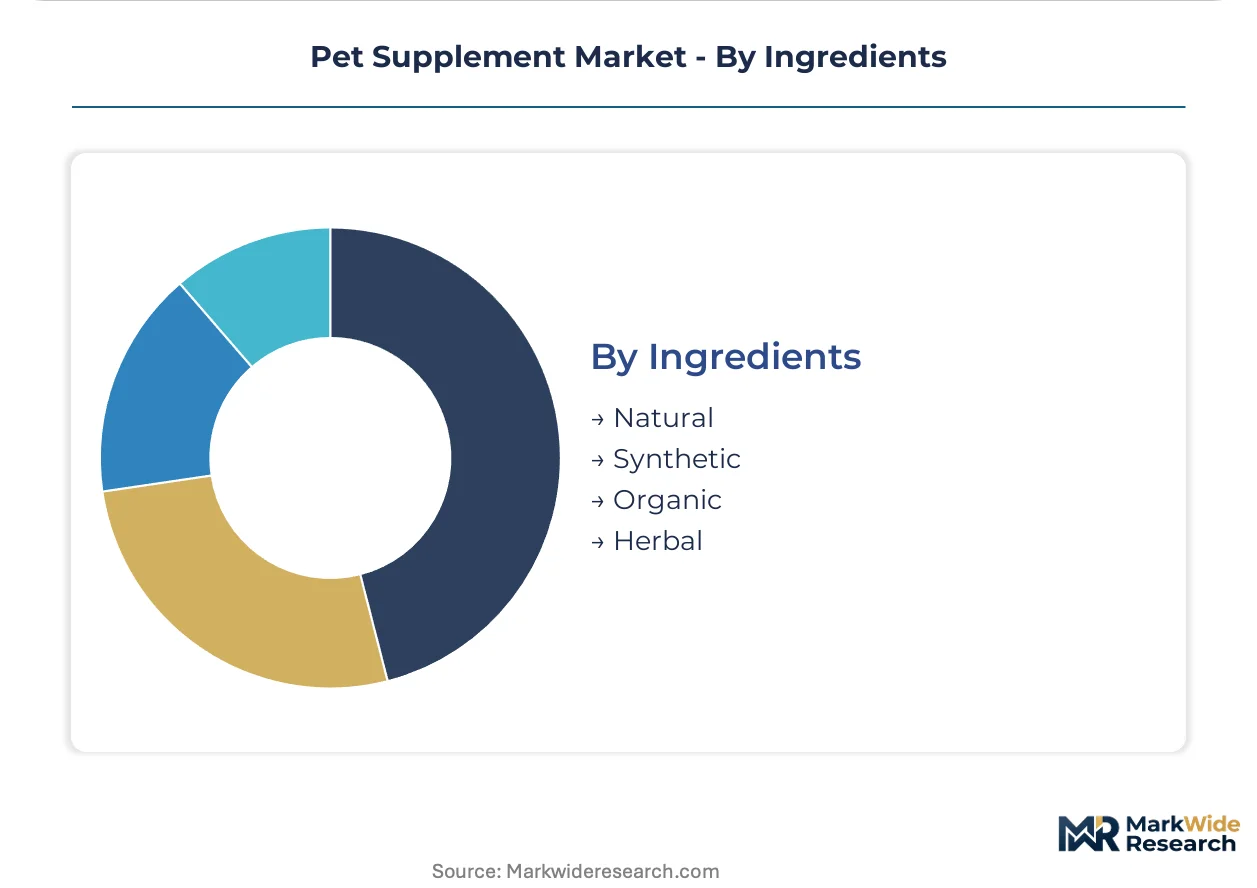
Supply chain provenance and certification status determine retail access and price realization. Organic and natural positioning command shelf space premiums at specialty retailers, while synthetic inputs enable cost-competitive mass market entry.
- Natural:Marine-derived omega-3s, botanical extracts, and fermentation-sourced glucosamine. Peruvian anchovy supply volatility and Antarctic krill harvest restrictions create input cost pressure.
- Synthetic:Chemically identical molecules produced through industrial processes. Consistent supply and lower input costs support private label and value-tier positioning.
- Organic:USDA-certified ingredients meeting livestock feed-grade standards. Limited domestic sourcing concentrates supply among certified organic fermentation facilities.
- Herbal:Ashwagandha, turmeric, and hemp-derived compounds for calming and mobility applications. FDA Center for Veterinary Medicine scrutiny of structure-function claims constrains marketing language.
Natural ingredients lead by volume. Organic certification is climbing fastest as specialty retail gatekeeping intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peruvian anchovy fisheries and Antarctic krill harvest zones anchor raw material flows for omega-3 formulations, concentrating manufacturing investment near coastal processing infrastructure in North America and Europe.
United States
Urban millennial dog owners drive subscription replenishment adoption for joint support and probiotic regimens. The FDA Center for Veterinary Medicine intensifies scrutiny of structure-function claims, forcing manufacturers to rebuild substantiation dossiers from clinical data. Wisconsin and Minnesota host concentrated fermentation capacity for probiotic strain production, creating supply vulnerability for brands without captive assets.
Germany
Geriatric large-breed dog populations expand veterinary caseloads for osteoarthritis management, pulling demand for glucosamine alternatives to pharmaceutical NSAIDs. EFSA guidelines on animal feed additives shape formulation standards for cross-border distribution within the EU. Bavaria's specialized manufacturing corridor anchors premium private-label production for European retail chains.
United Kingdom
Pet humanization trends accelerate premiumization of preventive nutrition among urban households. The Veterinary Medicines Directorate coordinates with FSA on borderline product classifications, creating regulatory uncertainty for CBD-containing calming formulations. Greater London concentrates direct-to-consumer platform headquarters and veterinary telehealth operations.
Japan
Aging companion animal demographics mirror human population trends, expanding therapeutic nutrition demand for cognitive and mobility support. METI's bioeconomy initiatives subsidize precision fermentation scale-up for domestic omega-3 active production. Osaka-Kobe industrial corridor hosts specialized coating and palatability engineering facilities for chew-format supplements.
Australia
High pet ownership rates and veterinary channel density support above-average per-household supplement spending. The TGA's parallel oversight of animal health products creates dual compliance requirements for imported formulations. Sydney and Melbourne anchor distribution networks serving Pacific Rim export markets.
Pet Supplement Market Key Industry Players
Backward integration into specialized manufacturing dominates the current competitive landscape. The vendor base concentrates among three structural tiers: multinational consumer goods conglomerates with veterinary pharmaceutical divisions, mid-tier specialists with captive fermentation or extrusion assets, and private-label contractors serving retail chains. Veterinary channel relationships and quality certification status serve as primary differentiation vectors. M&A activity and capacity expansion in precision fermentation represent the dominant competitive moves.
Within the multinational tier, Mars Incorporated, Nestlé, and Colgate-Palmolive occupy positions anchored by human nutrition R&D infrastructure extended into species-specific development. Among dedicated animal health specialists, Nutramax Laboratories and Virbac exemplify veterinary channel-dependent positioning. Elanco represents the pharmaceutical-origin archetype with regulatory affairs capabilities spanning drug and supplement pathways.
| Leading Market Players |
|---|
| General Mills Inc. |
| Nutramax Laboratories |
| Mars Incorporated |
| Virbac |
| Elanco |
| Nestlé |
| H&H Group |
| PetIQ |
| Colgate-Palmolive Company |
| Others |
Cost & Logistics Intelligence
Urban millennial dog owners concentrated in United States metropolitan markets anchor the dominant subscription-replenishment pricing model, converting veterinary recommendations into recurring revenue streams through algorithmic dosing platforms. This buyer concentration compresses price transparency across direct-to-consumer channels while elevating convenience premiums over transactional retail formats.
Pricing Analysis
Warranty-backed quality certification from the National Animal Supplement Council separates bundled premium offerings from unbundled standard tiers lacking third-party validation. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient provenance and clinical substantiation depth, with organic-certified and precision-fermented inputs commanding shelf-space premiums. Pricing pressure stems from marine ingredient cost volatility affecting omega-3 formulations, while veterinary clinic dispensing channels exhibit lowest price sensitivity due to recommendation-driven purchase behavior.
Supply Chain Analysis
Regional distribution centers in Wisconsin and Minnesota anchor hub-and-spoke patterns for probiotic strain logistics, with coastal processing infrastructure near Peruvian anchovy landing zones serving omega-3 raw material flows. The supply chain draws from United States fermentation capacity, Peruvian marine fisheries, and Antarctic krill harvest zones for critical actives. Single-source concentration among three Upper Midwest contract manufacturers creates supply vulnerability for brands lacking captive production assets. Distribution runs through veterinary clinics, specialty retailers, and direct-to-consumer platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where fermentation capacity and clinical validation infrastructure determine competitive survival. Players are pursuing upstream control over probiotic strain production to escape supply bottlenecks.
For Market Incumbents: To counter single-source fermentation vulnerability, acquire captive production assets in Wisconsin or Minnesota corridors while accelerating National Animal Supplement Council certification investment to compress audit queue delays. Prioritize backward integration into precision fermentation capacity before USDA grant programs lower capital barriers for mid-tier competitors. For New Entrants and Emerging Players: Cat owners in United States urban households represent an underserved buyer archetype with 40 percent lower per-household spending than dog owners despite comparable veterinary visit frequency. Target urinary tract and hairball formulations with improved palatability engineering, entering through veterinary telehealth platforms that bypass traditional clinic gatekeeping. For Investors and Strategic Acquirers: The window for entry favors mid-tier specialists with captive extrusion or fermentation assets and established veterinary channel relationships. Long-term viability hinges on regulatory affairs capabilities spanning FDA Center for Veterinary Medicine and state feed control pathways. Monitor FDA guidance evolution on structure-function claims as the primary inflection indicator for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | USDA grant programs lower capital barriers for domestic omega-3 active production from engineered yeast strains. |
| Veterinary Telehealth Integration | Remote consultation platforms create new recommendation touchpoints for supplement prescribing outside clinic visits. |
| Third-Party Certification Investment | National Animal Supplement Council quality seal reduces retail gatekeeping friction for premium positioning. |
| Feline Formulation Development | Palatability engineering advances unlock underpenetrated cat owner spending on urinary and dermatological products. |
| Backward Integration into Probiotic Production | Captive fermentation assets eliminate supply vulnerability to Upper Midwest contract manufacturer concentration. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across veterinary nutritionists, FDA Center for Veterinary Medicine officials, retail category buyers, and contract manufacturing executives. Secondary sources included Association of American Feed Control Officials model bill documentation, National Animal Supplement Council certification databases, and United States import records for marine-derived ingredients. Bottom-up volume modeling and top-down value triangulation validated segment-level outputs.
Granularity-level modeling operated at product type, end user species, delivery mode, and ingredient certification tier dimensions across the analysis window. CAGRs derived from regression analysis against demographic drivers and veterinary service utilization trends. Industry-specific inputs incorporated geriatric companion animal population projections and state-level feed control harmonization adoption patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA substantiation standard evolution and marine fishery quota restrictions. Forecasts reflect documented assumptions around regulatory pathway stability and ingredient supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
US Pet Food Market
Pet Care Products
Natural Dog Treat Market
Pet Care Products
Organic Dog Food Market
Pet Care Products
Cat Food Toppers Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
Cat Collar Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
Japan Dog Food Market
Pet Care Products
Pet Lodging Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Cat Bed Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Aquarium Market
Pet Care Products
Natural Pet Food Market
Pet Care Products
UK Pet Grooming Market