
 Asia-Pacific Pet Food Market | 2026-2036
Asia-Pacific Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pet Food Market Analysis
Asset-light contract manufacturing and third-party leasing of production lines is rewriting competitive entry dynamics in the Asia-Pacific pet food sector. Mars Incorporated leverages captive supply chains across Thailand and Australia to sustain cost advantages in dry food production. Unicharm Corporation anchors its position through specialized feline nutrition research facilities in Japan. IB Group competes aggressively on grain-free formulations for price-sensitive Indian households.
Asia-Pacific pet food comprises commercially manufactured nutritional products formulated to meet species-specific dietary requirements, typically processed through extrusion, retorting, or freeze-drying to achieve target moisture content, protein density, and shelf stability for companion animal consumption. Dry food dominates volume flows due to logistics efficiency and extended storage life, while treats and supplements represent the fastest-expanding margin pool as owners seek functional benefits beyond basic nutrition. Wet food maintains structural importance in Japan and South Korea, where palatability preferences support premium positioning.
Japan's Ministry of Agriculture, Forestry and Fisheries enforces strict labeling standards for pet food ingredients, while Australia's Pet Food Industry Association operates a voluntary accreditation scheme that increasingly shapes retail access decisions. China's National Feed Standard GB/T mandates contaminant thresholds that foreign manufacturers must navigate for import clearance. Stakeholders should monitor evolving feed-grade versus food-grade classification debates, as regulatory reclassification would force reformulation investments across multiple production networks.
Market Dynamics
Urban pet humanization across China's tier-one cities is compressing product lifecycles and forcing manufacturers to accelerate functional formulation pipelines, while regulatory divergence between Japan's food-grade standards and Australia's feed-grade frameworks fragments compliance architectures.
Growth Catalysts
- Japan's MAFF Labeling Standards:Mandatory ingredient disclosure rules elevate transparency premiums, compelling domestic manufacturers to reformulate toward cleaner label architectures that command retail shelf preference.
- Freeze-drying Technology:Nutrient retention capabilities in raw and fresh segments unlock premium positioning for functional treats targeting senior companion animals with specific dietary requirements.
- Shanghai and Beijing:Concentrated high-income pet owner populations generate disproportionate demand for imported nutrition-dense formulations, sustaining cross-border e-commerce volume growth.
Market Restraints
- Animal Protein Input Volatility:Fishmeal and poultry meal price swings strain margin structures for mid-tier dry food producers dependent on commodity sourcing.
- Thailand-Australia Production Concentration:Captive supply chain dominance by integrated multinationals limits contract manufacturing access for emerging regional brands.
- China's GB/T Contaminant Thresholds:Stringent heavy metal and mycotoxin limits for import clearance create technical barriers that delay foreign product registration timelines.
Strategic Opportunities
- India's Tier-Two Cities:Underpenetrated households with rising disposable incomes present whitespace for grain-free and single-protein formulations at accessible price points.
- Veterinary Prescription Channels:Therapeutic nutrition distribution through clinic networks remains nascent outside Japan, offering margin expansion for condition-specific diets.
- South Korea's MFDS Functional Claims Pathway:Regulatory clarity on digestive health and coat quality assertions enables differentiated positioning against generic premium competitors.
Industry Challenges
- Pet Food Technologist Talent Scarcity:Formulation science expertise lags demand growth across Southeast Asian manufacturing hubs, constraining R&D pipeline velocity.
- Dual Certification Complexity:Simultaneous compliance with Australia's PFIA voluntary scheme and export-market food-grade standards duplicates testing expenditure for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pet Food Market |
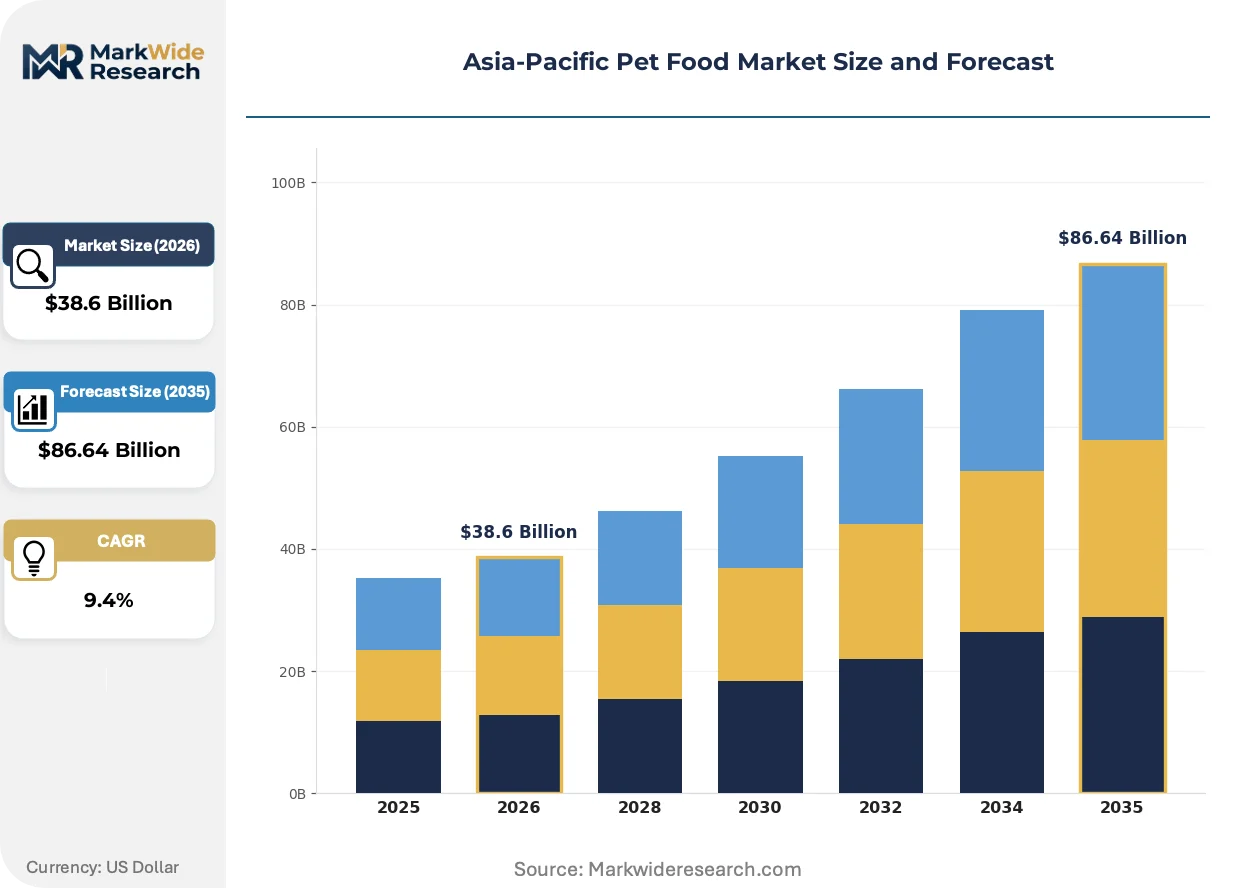
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Customer Type: Pet Owners, Pet Retailers, Veterinary Clinics, E-commerce Platforms Ingredient Source: Natural, Organic, Grain-Free, Premium Pet Type: Dogs, Cats, Birds, Small Mammals |
| Companies Covered | Mars Incorporated, Nestle (Purina), Colgate-Palmolive Company (Hill's Pet Nutrition Inc.), General Mills Inc., Unicharm Corporation, Perfect Companion Group Co., Archer Daniels Midland (ADM), i-Tail Corporation, IB Group (Drools Pet Food Pvt. Ltd.), Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pet Food Market Emerging Trajectories
Formulation science and distribution infrastructure are undergoing parallel transformation as digital traceability systems intersect with shifting retail access patterns across metropolitan Asia-Pacific markets.
Blockchain-enabled supply chain verification is digitizing ingredient provenance documentation for premium raw and fresh segments. Japanese specialty retailers and direct-to-consumer platforms are adopting batch-level tracking at the fastest clip. This transparency architecture is digitizing quality assurance workflows and compressing supplier audit cycles from quarterly to real-time monitoring.
Australia's Pet Food Industry Association is tightening its voluntary accreditation scheme to mirror food-grade safety protocols, with third-party audit requirements expanding from manufacturing to ingredient sourcing. The industrial consequence is capital reallocation toward HACCP-compliant facility upgrades. Wet food and refrigerated fresh categories face the steepest compliance cost escalation, prompting consolidation among regional processors.
Subscription-based replenishment models are displacing traditional retail stocking patterns among urban millennial pet owners. South Korean and Chinese metropolitan markets show the deepest channel shift, with automated delivery scheduling replacing supermarket bulk purchasing. Veterinary clinics in Japan are responding by integrating own-label therapeutic diets into recurring patient management protocols, capturing lifetime value through adherence monitoring.
Asia-Pacific Pet Food Market Segmentation
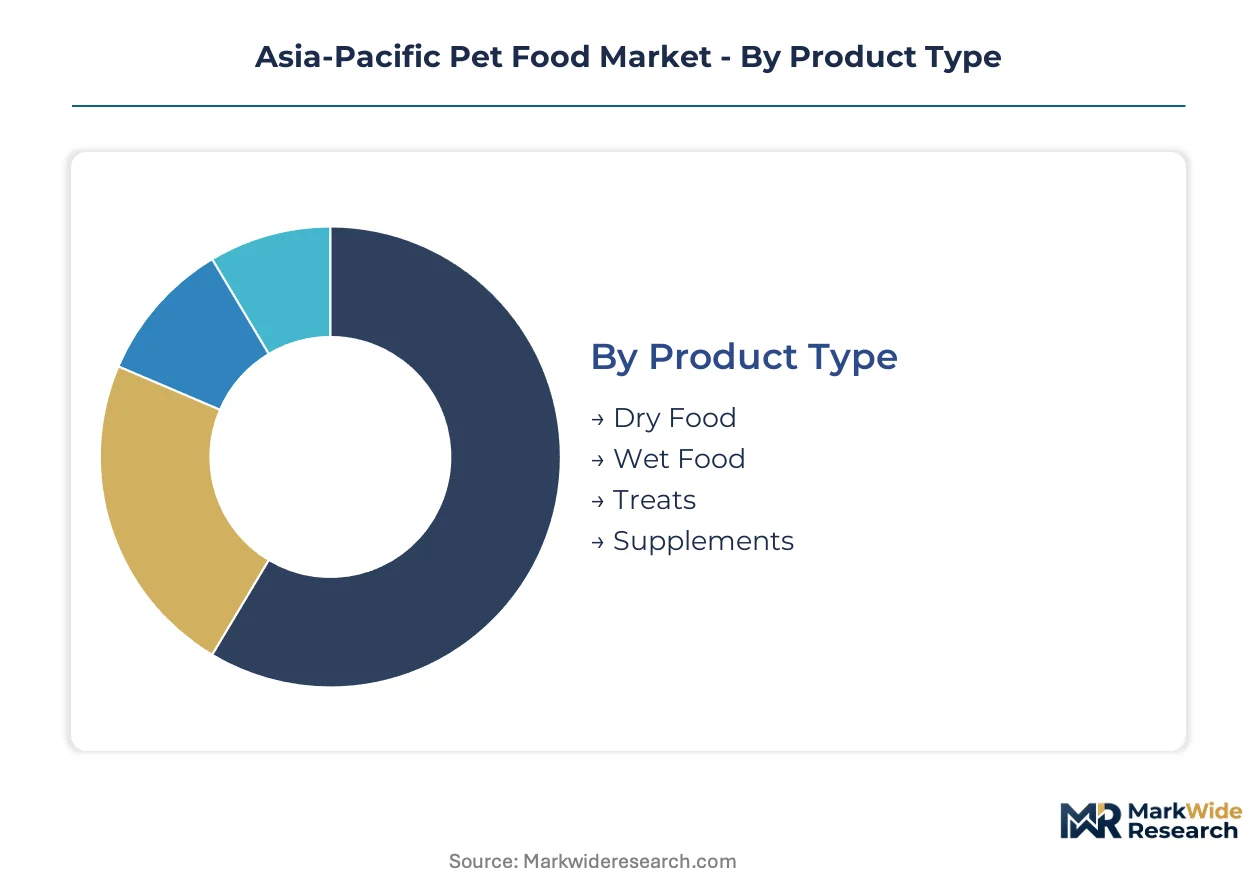
Asia-Pacific pet food segmentation reveals divergent margin architectures across product formats, with shelf-stable categories sustaining logistics economies while functional segments capture premium pricing. Customer channel fragmentation and ingredient sourcing complexity create distinct competitive battlegrounds requiring tailored formulation and distribution strategies.
Product Type:
Dry food turns inventory slowest due to extended shelf life and bulk purchasing patterns, while treats and supplements cycle fastest as impulse-driven replenishment accelerates in urban markets.
- Dry Food:Extruded kibble formulations achieve moisture content below 10% through high-temperature processing, enabling ambient storage and cost-efficient containerized shipping. Mars Incorporated's Thailand-Australia production network leverages this stability for regional distribution, though commodity protein input volatility compresses margins for non-integrated producers.
- Treats:Functional formulations targeting dental health, training reinforcement, and behavioral conditioning command price multiples over base nutrition. Shanghai and Beijing pet owners drive disproportionate demand for imported freeze-dried variants with species-specific protein sourcing.
- Wet Food:Retorted cans and pouches maintain structural importance in Japan and South Korea where palatability preferences support premium positioning.
- Supplements:Nutraceutical add-ons addressing joint health, digestive function, and coat quality expand margin pools beyond core feeding regimens.
Dry food dominates installed base. Treats and supplements are where expansion concentrates.
Customer Type:
Channel economics stratify sharply, with veterinary and direct-to-consumer routes capturing value through clinical credibility and subscription retention versus price-transparent retail competition.
- Pet Owners:Direct purchasing decisions increasingly route through mobile-enabled platforms with automated replenishment scheduling, displacing traditional supermarket bulk buying among South Korean and Chinese metropolitan households.
- Veterinary Clinics:Prescription diet distribution through clinic networks remains nascent outside Japan, offering margin expansion for condition-specific therapeutic formulations with adherence monitoring protocols.
- Pet Retailers:Specialty stores in Japan adopt blockchain-enabled batch-level tracking at the fastest clip, digitizing quality assurance workflows.
- E-commerce Platforms:Cross-border channels sustain volume growth for imported nutrition-dense formulations targeting China's tier-one cities.
Pet retailers and e-commerce platforms dominate installed base. Veterinary clinics are where expansion concentrates.
Ingredient Source:
Certification tier determines price realization, with organic and natural classifications requiring audit-intensive supply chains that smaller regional processors struggle to maintain.
- Natural:Minimally processed ingredient declarations without artificial additives or synthetic preservatives. Australia's PFIA voluntary accreditation scheme increasingly shapes retail access decisions for natural-positioned products.
- Grain-Free:Formulations excluding wheat, corn, and rice address digestive sensitivity concerns and ancestral diet positioning. IB Group competes aggressively on this architecture for price-sensitive Indian households.
- Organic:Certified cultivation and processing standards with full traceability documentation command substantial premiums in Japanese specialty retail.
- Premium:Human-grade ingredient specifications with elevated protein density and limited processing, subject to Japan's MAFF food-grade labeling standards.
Natural and grain-free dominate installed base. Organic and premium tiers are where expansion concentrates.
Pet Type:
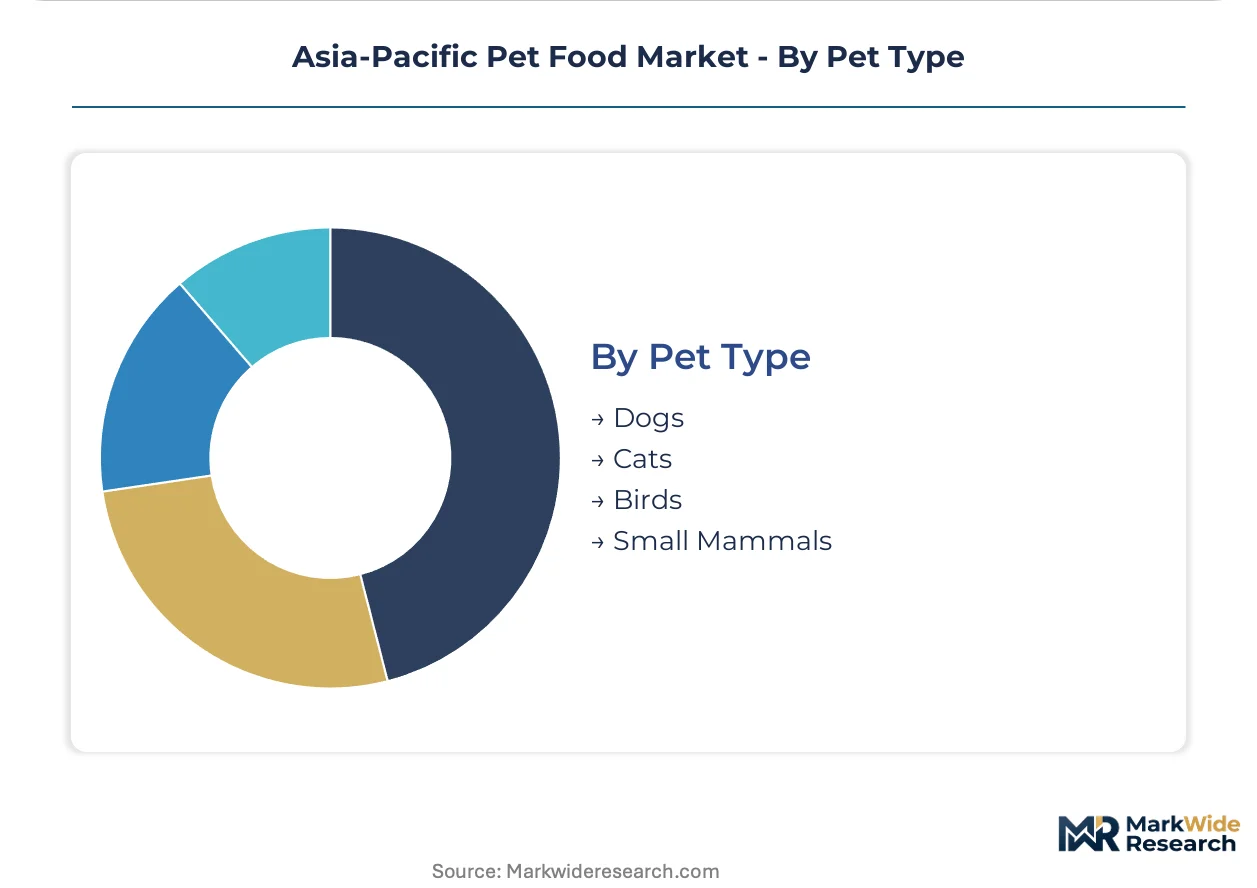
Species-specific formulation requirements create divergent R&D intensity, with feline nutrition demanding precise amino acid profiles that constrain outsourcing options.
- Cats:Obligate carnivore physiology mandates taurine supplementation and specific protein bioavailability standards. Unicharm Corporation anchors competitive position through specialized feline nutrition research facilities in Japan.
- Dogs:Omnivore tolerance enables broader ingredient flexibility, supporting volume scale across dry food production networks in Thailand and Australia.
- Birds:Seed and pellet formulations with species-specific micronutrient profiles serve concentrated hobbyist populations in Australian and Japanese markets.
- Small Mammals:Niche rodent and rabbit nutrition represents limited volume with high margin potential through specialty retail channels.
Dog food dominates installed base. Cat food is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Ministry of Agriculture, Forestry and Fisheries enforces food-grade labeling standards that elevate compliance costs for import-dependent markets. Australia's Pet Food Industry Association accreditation scheme increasingly determines retail access across the region. China's National Feed Standard GB/T mandates contaminant thresholds that reshape sourcing networks for foreign manufacturers.
China
Tier-one cities Shanghai and Beijing concentrate high-income pet owner populations driving imported nutrition-dense formulations. The National Feed Standard GB/T establishes heavy metal and mycotoxin limits that delay foreign product registration timelines. Cross-border e-commerce channels sustain volume growth for premium brands targeting metropolitan households with humanization-driven treat and supplement purchases.
Japan
Specialty retailers adopt blockchain-enabled batch-level tracking at the fastest clip across Asia-Pacific markets. The Ministry of Agriculture, Forestry and Fisheries mandates strict ingredient disclosure rules that compel domestic manufacturers toward cleaner label architectures. Unicharm Corporation anchors competitive positioning through specialized feline nutrition research facilities in Tokyo and Osaka industrial corridors.
Australia
Pet Food Industry Association voluntary accreditation schemes shape retail access decisions with expanding third-party audit requirements. The country's HACCP-compliant facility standards prompt capital reallocation toward wet food and refrigerated fresh category upgrades. Mars Incorporated leverages captive supply chains across Queensland and New South Wales production networks for regional dry food distribution.
South Korea
Metropolitan millennial pet owners displace traditional supermarket bulk purchasing through subscription-based replenishment models. The Ministry of Food and Drug Safety provides regulatory clarity on digestive health and coat quality functional claims. Seoul-based direct-to-consumer platforms automate delivery scheduling for imported freeze-dried treat variants with species-specific protein sourcing.
India
Tier-two cities present whitespace for grain-free and single-protein formulations at accessible price points for rising disposable income households. The Food Safety and Standards Authority of India oversees evolving feed-grade versus food-grade classification debates that would force reformulation investments. IB Group competes aggressively on grain-free architectures from manufacturing positions serving Maharashtra and Gujarat industrial clusters.
Asia-Pacific Pet Food Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Integrated multinationals with captive Thailand-Australia production networks dominate dry food volume flows. Three archetypes define competitive positioning: scale-driven extrusion specialists, feline nutrition research anchors, and grain-free formulation challengers. M&A activity concentrates on therapeutic nutrition distribution capabilities, while strategic partnerships target blockchain-enabled supply chain verification.
Within the scale-driven tier, Mars Incorporated and Nestle occupy positions anchored by regional production network control. Among Asia-Pacific-based specialists, Unicharm Corporation exemplifies feline nutrition research intensity. IB Group represents the price-accessible grain-free challenger archetype for emerging market penetration.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestle (Purina) |
| Colgate-Palmolive Company (Hill's Pet Nutrition Inc.) |
| General Mills Inc. |
| Unicharm Corporation |
| Perfect Companion Group Co. |
| Archer Daniels Midland (ADM) |
| i-Tail Corporation |
| IB Group (Drools Pet Food Pvt. Ltd.) |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Thailand's extrusion facilities is forcing mid-tier dry food producers toward spot-market protein sourcing, compressing margins while integrated multinationals exploit captive supply chains to sustain pricing power across Southeast Asian distribution networks.
Pricing Analysis
Certification level under Japan's MAFF food-grade standards creates the primary spread between import-positioned premiums and domestic feed-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient disclosure depth and contaminant testing rigor. Pricing pressure stems from commodity protein input volatility straining non-integrated producers. Price-sensitive Indian tier-two households drive volume in grain-free economy tiers, while Japanese specialty retailers absorb premium markups for blockchain-verified batch tracking.
Supply Chain Analysis
Export-control scrutiny over freeze-drying technology transfers is constraining equipment access for Southeast Asian processors seeking premium treat production capabilities. Geographic supply concentrates in Thailand, Australia, and China's Shandong province for extruded kibble manufacturing. Raw material dependencies center on Vietnamese fishmeal, Australian poultry meal, and New Zealand lamb derivatives. Single-source vulnerability runs through Thailand's integrated multinational production networks. Distribution runs through veterinary clinic networks in Japan, direct-to-consumer platforms in South Korea, and cross-border e-commerce channels targeting China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment platforms are reconstituting customer lock-in mechanics around automated adherence protocols, shifting value capture from transactional retail toward recurring-revenue ecosystems anchored in Japan's veterinary clinic integrations and South Korea's direct-to-consumer infrastructure.
For Market Incumbents: Insulate margin architecture through backward integration into protein rendering facilities across Queensland and New South Wales production corridors. Accelerate HACCP-compliant facility upgrades ahead of Australia's PFIA accreditation tightening. Defensive priority rests on securing freeze-drying equipment allocations before export-control restrictions harden.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-two cities with single-protein formulations priced below Mars Incorporated's economy-tier positioning. Target Maharashtra and Gujarat industrial clusters for contract manufacturing partnerships. Go-to-market leverage runs through veterinary clinic education programs demonstrating digestive health outcomes.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among therapeutic nutrition distributors with clinic-network integration and adherence-monitoring protocols. Five-to-ten-year viability favors acquisition targets possessing feline nutrition research capabilities or blockchain-enabled supply chain verification infrastructure. Signal to monitor: regulatory reclassification of feed-grade to food-grade standards forcing reformulation capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Nutrient retention capabilities unlock premium positioning for functional senior pet treats in Japan's specialty retail. |
| Blockchain Supply Chain Integration | Batch-level tracking digitizes quality assurance workflows and compresses supplier audit cycles for Japanese retailers. |
| Veterinary Clinic Network Partnership | Prescription diet distribution captures lifetime value through adherence monitoring protocols outside Japan's mature market. |
| Grain-Free Formulation R&D | Single-protein architectures address digestive sensitivity concerns among India's rising disposable income households. |
| HACCP Facility Certification | Third-party audit compliance under Australia's PFIA scheme determines retail access for wet food and refrigerated fresh categories. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs import records, MAFF registration filings, and PFIA accreditation databases. Primary interviews engaged pet food formulation technologists, veterinary clinic procurement managers, specialty retail category buyers, and contract manufacturing facility operators. Secondary validation drew from National Feed Standard GB/T compliance documentation, cross-border e-commerce trade flow data, and ingredient supplier customs declarations. Bottom-up demand modeling triangulated against top-down production capacity assessments across Thailand-Australia manufacturing networks.
Forecast inputs span product format segmentation, ingredient certification tiers, distribution channel economics, and regional regulatory divergence. The analytical framework projects volume and value trajectories across dry food, wet food, treats, and supplements through the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating urban pet ownership penetration, disposable income trajectories, and humanization-driven category mix shifts. Industry-specific inputs include freeze-drying technology adoption rates and blockchain traceability implementation timelines.
Stress conditions across protein input price volatility, regulatory reclassification timelines, and veterinary channel consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MAFF labeling enforcement intensity and PFIA accreditation scheme expansion. Material shifts in China's GB/T contaminant threshold stringency or Australia's feed-grade to food-grade reclassification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Dog Safety Leash Market
Pet Care Products
Pet Food Market
Pet Care Products
Pet GPS Tracker Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
Japan Pet Boarding Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Fresh and Frozen Dog Food Market
Pet Care Products
Bird Toy Market
Pet Care Products
Pet Oral Care Products Market
Pet Care Products
Cat Furniture and Scratchers Market
Pet Care Products
Cat Litter Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Dog Pen Market