
 Sustainable Logistics Market | 2026-2036
Sustainable Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Logistics Market Insights
Market Context
European freight corridors is hardening as shippers lock in low-emission capacity ahead of tightening carbon border rules. Deutsche Post DHL Group leverages its StreetScooter electric fleet manufacturing to control last-mile asset supply. FedEx Corporation anchors its network around sustainable aviation fuel offtake agreements with regional biorefinery partners. A.P. Moller - Maersk dominates transoceanic green methanol vessel procurement, locking in dual-fuel engine capacity through shipyard partnerships.
Technical Definition and Structural Segments
Sustainable logistics encompasses the planning, execution, and optimization of freight movement using energy-efficient vehicles, renewable fuels, and emissions-tracking infrastructure to minimize greenhouse gas output across supply chains. Route optimization algorithms reduce empty miles by integrating real-time traffic, weather, and delivery density data into dispatch decisions. Freight Services captures the largest revenue pool as shippers outsource decarbonization liability to asset-based carriers, while Last Mile Delivery registers the fastest structural expansion driven by urban zero-emission zone mandates. Warehousing margins concentrate in facilities with on-site solar generation and battery storage, where energy cost arbitrage differentiates operators from grid-dependent competitors.
Regulatory Framework
The EU Green Deal and its Fit for 55 package enforce emissions trading on road freight above 3.5 tonnes, compelling fleet operators to document carbon intensity per ton-kilometer or purchase offset credits. The EPA's Clean Trucks Plan and California Air Resources Board's Advanced Clean Fleets rule together mandate zero-emission vehicle sales quotas and phase out diesel tractor purchases in the United States. Stakeholders must monitor whether battery-electric range and charging infrastructure density match regulatory timelines for corridor compliance.
Market Dynamics
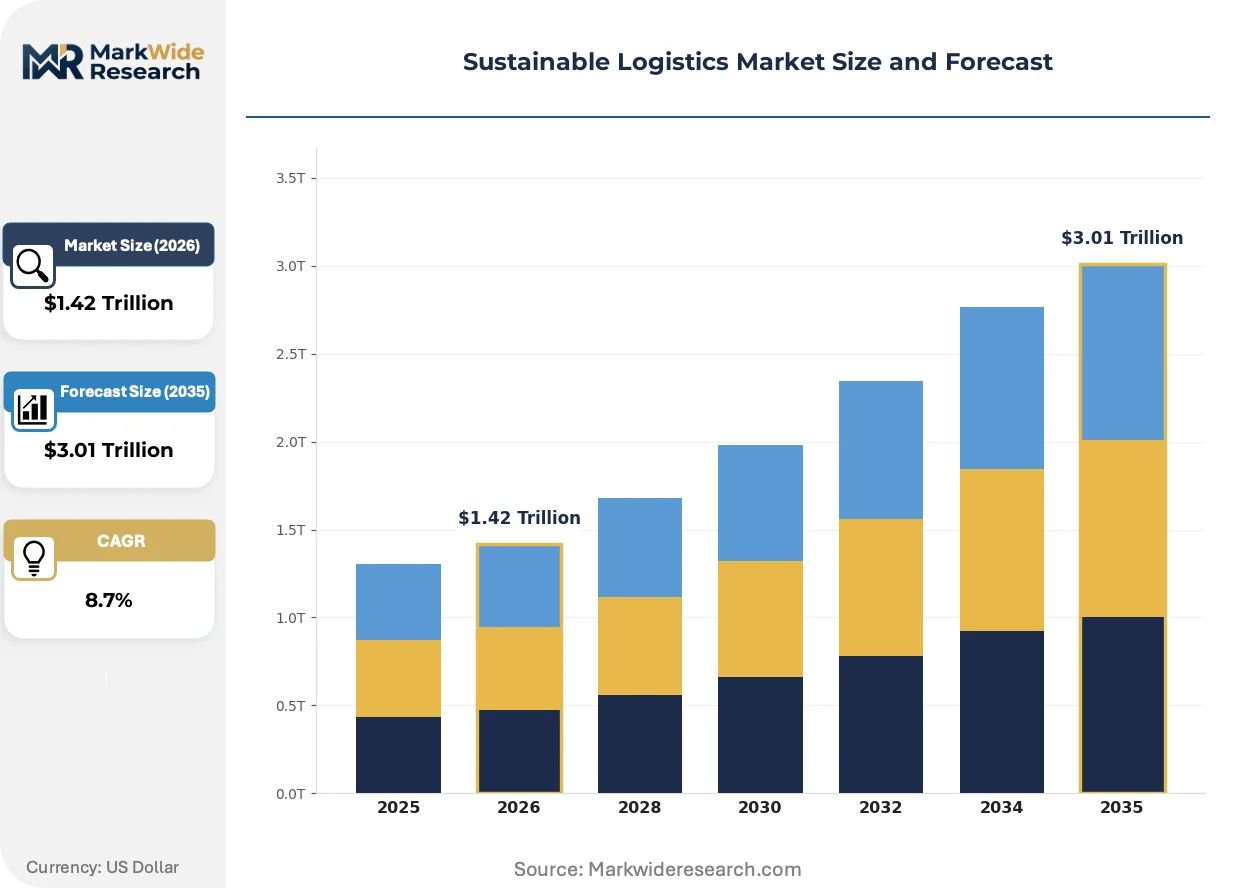
EU Green Deal emissions trading rules are compressing diesel fleet economics while battery-electric vehicle procurement accelerates across German and California freight corridors.
Growth Catalysts
- EU Green Deal Fit for 55:Mandatory emissions documentation per ton-kilometer forces fleet operators to electrify or purchase offset credits, accelerating zero-emission vehicle deployment.
- Urban zero-emission zones:Municipal mandates in Amsterdam, London, and Paris prohibit diesel last-mile delivery, concentrating electric van demand in metropolitan fulfillment networks.
- Dual-fuel engine technology:Green methanol and ammonia-compatible marine engines enable transoceanic carriers to lock in future fuel flexibility ahead of port carbon intensity rules.
Market Restraints
- Lithium-ion cell supply:Cathode precursor concentration in Indonesian nickel processing and Chilean lithium brine creates input cost volatility for battery-electric truck manufacturing.
- Charging infrastructure density:Highway corridor fast-charging gaps exceed 300 kilometers across the US Interstate 10 freight spine, limiting electric long-haul feasibility.
- Renewable fuel certification:EU Renewable Energy Directive sustainability criteria create compliance friction for imported biogas and synthetic e-fuel procurement.
Strategic Opportunities
- Indian freight electrification:PLI scheme subsidies for commercial electric vehicle manufacturing create localized production capacity for last-mile logistics operators.
- Warehouse energy arbitrage:On-site solar-plus-battery installations enable cold storage facilities to monetize grid services and reduce Scope 2 emissions intensity.
- Blockchain emissions tracking:Integration of distributed ledger verification with IoT telematics creates auditable carbon accounting for shipper ESG reporting.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance networks lack certified electricians for 800-volt battery pack diagnostics and repair, extending vehicle downtime.
- Intermodal system integration:Rail-yard drayage electrification requires synchronized charging scheduling with ocean vessel berthing windows, complicating operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Logistics Market |
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $3.01 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Services, Transportation Management, Warehousing, Last Mile Delivery Technology: Route Optimization, Fleet Management Systems, IoT Solutions, Automation Industry Vertical: Retail, Manufacturing, Food & Beverage, Automotive Delivery Mode: Air, Sea, Rail, Road |
| Companies Covered | Deutsche Post DHL Group, United Parcel Service, FedEx Corporation, GEODIS, DSV, XPO Logistics, A.P. Moller - Maersk, DB Schenker, Kuehne + Nagel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Logistics Market Trends and Innovations
Artificial intelligence dispatch systems and alternative fuel infrastructure are compressing the cost gap between sustainable and conventional freight movement across dense logistics corridors.
Autonomous yard tractors are automating container repositioning at port terminals. Terminal operators in Los Angeles and Rotterdam are deploying battery-electric autonomous guided vehicles for 24-hour gate-to-stack operations. This technology is automating labor-intensive chassis management while reducing diesel particulate exposure in adjacent communities.
California Air Resources Board's Advanced Clean Fleets rule mandates zero-emission vehicle sales quotas for drayage operators serving Los Angeles and Long Beach ports. Fleet operators must phase out diesel tractor purchases by 2036 or face registration restrictions. Heavy-duty battery-electric truck deployment concentrates in this corridor where charging infrastructure investment matches regulatory timelines.
Shippers are unbundling carbon accounting from transportation procurement, creating standalone emissions verification contracts with third-party logistics providers. Retail and consumer goods verticals in Germany and the Netherlands lead this separation, demanding ISO 14064-aligned footprint disclosure separate from freight rate negotiations. This bifurcation pressures asset-light brokers to acquire verification capabilities or lose enterprise accounts.
Sustainable Logistics Market Segmentation
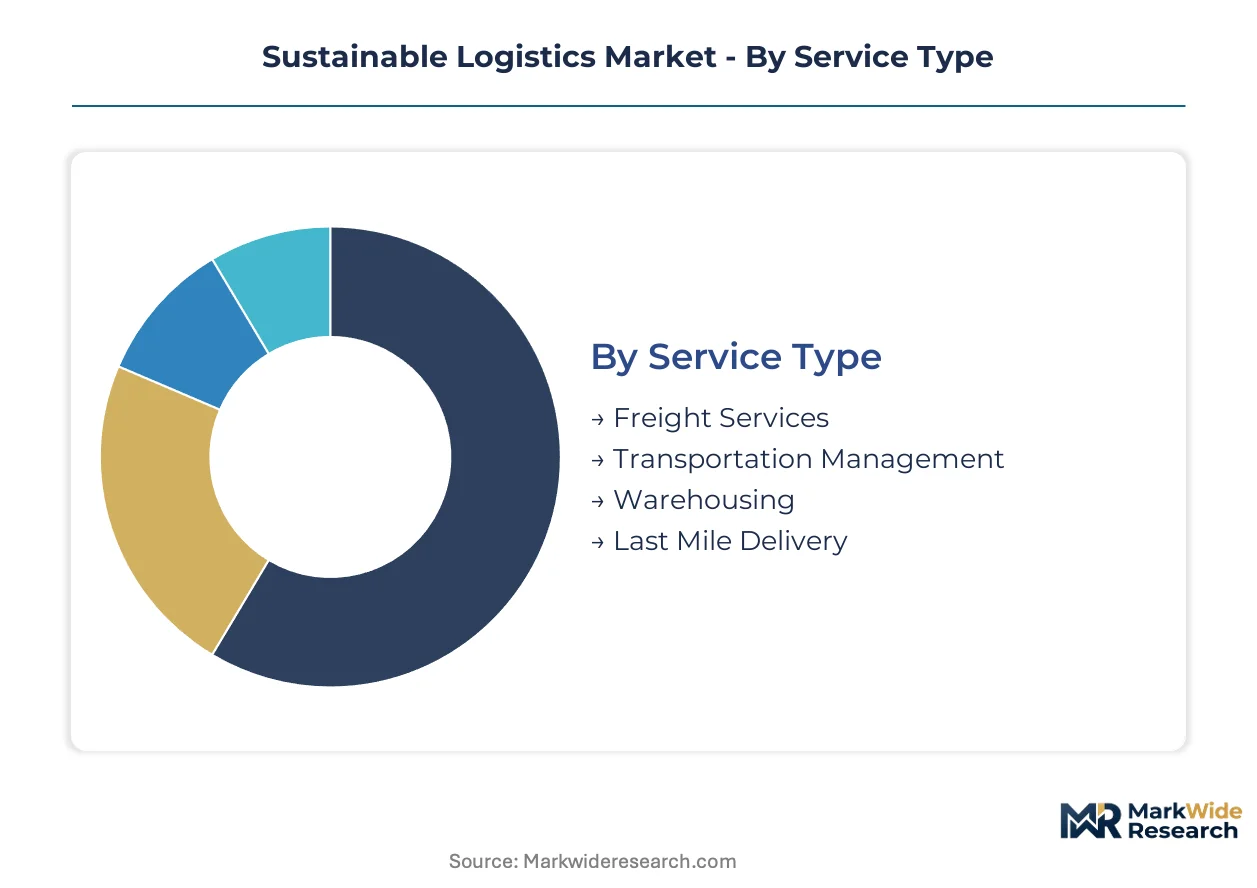
Sustainable logistics segmentation reveals where decarbonization investments concentrate versus where compliance costs accumulate. Service type and delivery mode determine emissions liability exposure, while technology and industry vertical shape procurement priorities for tracking and reduction infrastructure.
Service Type:
Standalone outsourcing services carry full carbon accounting burden, while embedded logistics functions spread liability across shipper operations.
- Freight Services:Asset-based carriers deploy battery-electric tractors and renewable fuel contracts to absorb shipper Scope 3 obligations. Demand concentrates in German port corridors and California's I-10 spine where EU Green Deal and CARB rules enforce documentation per ton-kilometer.
- Last Mile Delivery:Electric van fleets operate under Amsterdam, London, and Paris zero-emission zone mandates. Metro fulfillment networks face the tightest regulatory timelines, compressing diesel economics and accelerating depot charging infrastructure deployment.
- Transportation Management:Software platforms integrate carrier emissions data into shipper procurement decisions.
- Warehousing:Facilities with on-site solar and battery storage arbitrage energy costs against grid-dependent competitors.
Freight Services leads volumes today; Last Mile Delivery is gaining share fastest.
Technology:
Cost tier separates enterprise-grade integrated suites from point solutions serving mid-market shippers.
- Route Optimization:Algorithms reduce empty miles by ingesting real-time traffic, weather, and delivery density data. Retail verticals in Germany and the Netherlands deploy these systems to meet ISO 14064-aligned footprint disclosure requirements separate from rate negotiations.
- Fleet Management Systems:Telematics platforms track fuel consumption, idling time, and maintenance intervals across mixed diesel-electric fleets. California drayage operators use these tools to document compliance with Advanced Clean Fleets phase-out timelines.
- IoT Solutions:Sensor networks monitor refrigerated cargo temperature and location integrity.
- Automation:Autonomous yard tractors reposition containers at Los Angeles and Rotterdam terminals.
Route Optimization leads volumes today; Fleet Management Systems show the steepest expansion trajectory.
Industry Vertical:
Application criticality determines sustainability spend intensity, with temperature-controlled and just-in-time supply chains commanding premium tracking investment.
- Retail:Omnichannel fulfillment networks face consumer-facing emissions disclosure pressure. German and Dutch retailers unbundle carbon accounting from transportation procurement, creating standalone verification contracts with third-party logistics providers.
- Food & Beverage:Cold chain integrity requirements intersect with refrigerant phase-down regulations under EU F-Gas rules. Warehouse energy arbitrage through solar-plus-battery installations enables Scope 2 reduction while monetizing grid services.
- Automotive:Inbound parts logistics tracks component-level carbon intensity for EU carbon border adjustment documentation.
- Manufacturing:Heavy freight corridors concentrate procurement of green methanol and ammonia-compatible marine engines.
Retail leads volumes today; Food & Beverage is climbing the fastest.
Delivery Mode:
Geography determines fuel pathway viability, with coastal corridors accessing marine alternative fuels and inland networks constrained by charging infrastructure density.
- Road:Battery-electric truck deployment concentrates where highway fast-charging gaps fall below 300 kilometers. German freight corridors and California's port drayage networks lead procurement as EU emissions trading and CARB quotas harden diesel economics.
- Sea:Dual-fuel engine retrofits enable green methanol and ammonia flexibility ahead of port carbon intensity rules. Transoceanic carriers lock in shipyard partnerships for vessel procurement.
- Air:Sustainable aviation fuel offtake agreements anchor network decarbonization where electrification remains non-viable.
- Rail:Yard electrification requires synchronized charging with ocean vessel berthing windows.
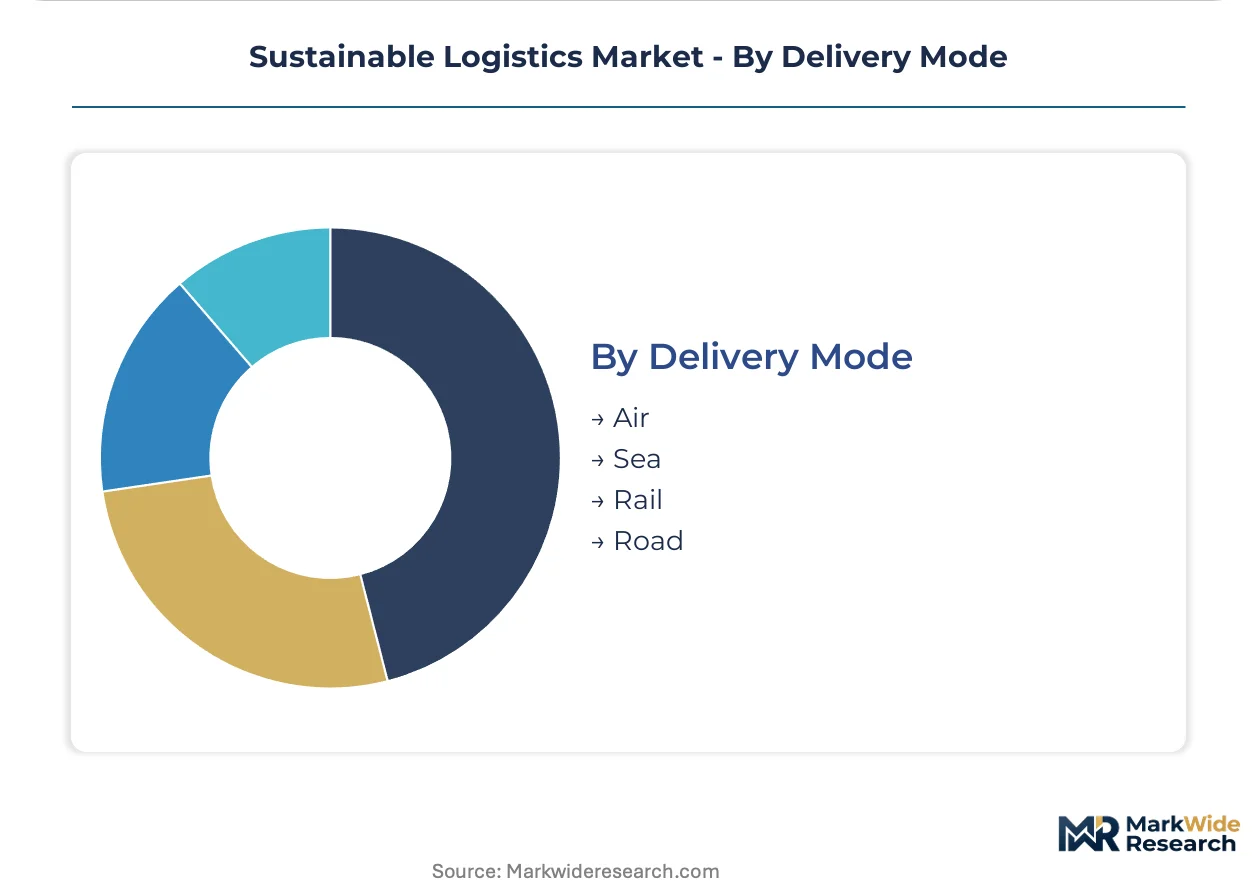
Road leads volumes today; Sea is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's freight corridors electrify faster than India's logistics networks, though both face tightening emissions documentation requirements that reshape fleet procurement priorities across their respective industrial belts.
United States
California's port drayage operators deploy battery-electric tractors along the Los Angeles-Long Beach corridor to meet CARB Advanced Clean Fleets phase-out timelines. The EPA Clean Trucks Plan reinforces these mandates with federal zero-emission vehicle sales quotas. Heavy-duty charging infrastructure concentrates in the I-10 freight spine connecting the ports to inland distribution centers.
Germany
Deutsche Post DHL Group controls last-mile asset supply through captive StreetScooter electric van manufacturing for metropolitan fulfillment networks. The EU Green Deal Fit for 55 package enforces emissions trading on road freight above 3.5 tonnes, compelling carbon intensity documentation per ton-kilometer. Freight corridors through North Rhine-Westphalia harden as shippers lock in low-emission capacity ahead of tightening carbon border rules.
Netherlands
Amsterdam's zero-emission zone prohibits diesel last-mile delivery, compressing electric van demand into Randstad metro fulfillment networks. Retail and consumer goods verticals unbundle carbon accounting from transportation procurement, demanding ISO 14064-aligned footprint disclosure. Rotterdam terminal operators deploy battery-electric autonomous guided vehicles for gate-to-stack container repositioning.
China
Domestic battery-electric truck manufacturing scales through MIIT production quotas for commercial vehicle electrification. The country's dual carbon goals pressure logistics operators to document supply chain emissions intensity for export compliance. Yangtze River Delta industrial clusters anchor green methanol and ammonia-compatible marine engine procurement for transoceanic vessel retrofits.
India
PLI scheme subsidies for commercial electric vehicle manufacturing create localized production capacity for last-mile logistics operators in Maharashtra and Gujarat. Cold storage facilities in these states arbitrage energy costs through on-site solar-plus-battery installations. National freight corridors face charging infrastructure density gaps that constrain electric long-haul feasibility despite regulatory pressure.
Sustainable Logistics Market Competitive Landscape
German producers anchor the integrated logistics tier; American specialists hold the express parcel segment through sustainable aviation fuel offtake structures. The vendor base organizes around three strategic archetypes: asset-heavy integrators controlling captive electric fleet manufacturing, asset-light brokers acquiring emissions verification capabilities, and ocean carriers locking in dual-fuel vessel capacity. Competitive moves concentrate on vertical integration into battery-electric asset supply and strategic partnerships with regional biorefinery operators for renewable fuel security.
Within the integrated logistics tier, Deutsche Post DHL Group and FedEx Corporation exemplify divergent fuel pathway strategies. Deutsche Post DHL Group's StreetScooter manufacturing operation represents captive production of last-mile electric assets. FedEx Corporation anchors its network architecture around sustainable aviation fuel offtake agreements with biorefinery partners. A.P. Moller - Maersk occupies a distinct position among ocean carriers through green methanol vessel procurement and shipyard partnerships for dual-fuel engine capacity.
| Leading Market Players |
|---|
| Deutsche Post DHL Group |
| United Parcel Service |
| FedEx Corporation |
| GEODIS |
| DSV |
| XPO Logistics |
| A.P. Moller - Maersk |
| DB Schenker |
| Kuehne + Nagel |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed infrastructure funds and private-equity-rolled-up fleet operators now dominate asset ownership across European and North American freight corridors, compressing pricing discipline through scale procurement of battery-electric tractors and renewable fuel offtake contracts while locking in long-term shipper relationships that insulate against spot market volatility.
Pricing Analysis
Capacity additions in Germany and California are reshaping price floors for sustainable freight services as Deutsche Post DHL Group and FedEx Corporation deploy captive electric fleets at scale. Contract-based long-term offtake agreements anchor pricing, with differentiation driven by ISO 14064-aligned carbon certification tier and geographic delivery density. Pricing pressure stems from lithium-ion cell input volatility concentrated in Indonesian nickel processing and Chilean lithium brine. Mid-market shippers exhibit highest price sensitivity, while enterprise retailers with Scope 3 disclosure mandates absorb premium tiers for verified emissions tracking.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Germany anchor hub-and-spoke patterns for electric last-mile fulfillment, with satellite depots positioned within Amsterdam and Paris zero-emission zone perimeters. Manufacturing concentrates in China for battery-electric commercial vehicles, Germany for autonomous yard tractor systems, and South Korea for cathode precursor chemicals. The supply chain draws from lithium brine, nickel laterite, and rare earth magnet inputs. Single-source vulnerability runs through Indonesian nickel processing. Distribution runs through Rotterdam and Hamburg port terminals with synchronized rail-yard drayage scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sustainable logistics functions as a stable compounder, with regulatory emissions documentation requirements across the EU Green Deal and CARB mandates ensuring steady demand for low-emission freight capacity.
For Market Incumbents: Acquire captive charging infrastructure assets along the I-10 freight spine and German port corridors to lock in depot access before real estate scarcity intensifies. Secure backward integration into battery-electric vehicle supply through shipyard partnerships for dual-fuel marine engines. Defend against asset-light brokers acquiring emissions verification capabilities by embedding ISO 14064-aligned carbon accounting into standard service contracts. For New Entrants and Emerging Players: The mid-market price-point gap between premium certified services and economy diesel-reliant operators creates entry space for hybrid fleet operators serving Indian PLI scheme-subsidized manufacturing clusters. Target Maharashtra and Gujarat cold storage facilities with solar-plus-battery energy arbitrage solutions. Penetrate through blockchain emissions tracking integration with IoT telematics for mid-tier retail shippers lacking in-house ESG verification. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light logistics brokers facing pressure to acquire emissions verification capabilities or lose enterprise accounts. The five-to-ten year viability window favors integrated operators with captive electric asset manufacturing and renewable fuel security. Monitor green methanol and ammonia-compatible marine engine procurement announcements from transoceanic carriers as inflection signals for dual-fuel technology maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Electric Fleet Manufacturing | Deutsche Post DHL Group's StreetScooter operation insulates last-mile asset supply from lithium-ion cell volatility. |
| Renewable Fuel Offtake Agreements | FedEx Corporation's biorefinery partnerships anchor sustainable aviation fuel security for express network decarbonization. |
| Dual-Fuel Vessel Procurement | A.P. Moller - Maersk's green methanol shipyard partnerships lock in transoceanic compliance ahead of port carbon intensity rules. |
| Blockchain Emissions Tracking Integration | Distributed ledger verification with IoT telematics creates auditable carbon accounting for German retailer ESG reporting. |
| Warehouse Energy Arbitrage Buildout | On-site solar-plus-battery installations enable cold storage operators to monetize grid services and reduce Scope 2 intensity. |
Research Methodology
Bottom-up fleet operator modeling reconciled against top-down emissions regulation tracking forms the analytical core of this study. Primary interviews with fleet procurement directors, sustainability officers at retail shippers, terminal operations managers, and biorefinery project developers combined with secondary validation from EU ETS transaction databases, CARB regulatory filings, EPA Clean Trucks Plan documentation, and customs trade data for battery-electric commercial vehicle imports. Triangulation across stakeholder inputs and documentary sources ensures coverage of both operational deployment timelines and compliance documentation requirements.
Input-output matrices model capacity deployment across service type, technology tier, delivery mode, and industry vertical dimensions over the projection horizon. CAGRs derive from segment-level fleet electrification trajectories, renewable fuel production scaling curves, and regulatory phase-in schedules. Industry-specific forecast inputs include highway fast-charging infrastructure gap closure rates and shipyard orderbook data for dual-fuel vessel construction.
Caveats apply where lithium-ion cell supply disruptions, charging infrastructure deployment delays, or renewable fuel certification friction under EU Renewable Energy Directive criteria could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Iraq Air Freight Transport Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Food Delivery Logistic Market
Logistics and Shipping
Sweden Freight and Logistics Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
US Express Delivery Market