
 Southeast Asia Construction Chemicals Market | 2026-2036
Southeast Asia Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Construction Chemicals Market Analytics
Modular product bundling is shifting how contractors procure construction chemicals across Southeast Asia. Sika AG leverages integrated waterproofing-admixture systems to anchor its position in Indonesia's infrastructure pipeline. BASF SE competes through high-performance concrete additives that extend its technical reach into Vietnam's bridge and tunnel projects. MAPEI S.p.A. specializes in tile-setting and flooring systems that dominate Thailand's commercial building segment.
Construction chemicals encompass admixtures, sealants, waterproofing membranes, and repair compounds formulated to modify concrete rheology, protect structural integrity, or restore deteriorated substrates; these formulations typically incorporate polymers, surfactants, and cementitious binders engineered for tropical humidity, saline exposure, and seismic loading conditions. Admixtures command the largest product-type position due to their penetration across every concrete pour, while waterproofing registers the fastest structural expansion as flood-resilient design becomes mandatory in low-lying Indonesian and Vietnamese developments. Application demand tilts toward infrastructure over residential projects, reflecting state-backed toll roads, rail corridors, and port modernization that concentrate volume and specification intensity.
Singapore's Building and Construction Authority enforces Green Mark standards that restrict VOC content in sealants and mandate durability testing for waterproofing systems, while Indonesia's Ministry of Public Works and Housing imposes national compulsory standards on concrete additives for public infrastructure. Vietnam's Directorate for Standards, Metrology and Quality aligns cementitious repair compound specifications with ASEAN harmonized frameworks, creating cross-border compliance complexity for suppliers. Stakeholders must monitor diverging national certification timelines and pre-qualification requirements that determine project eligibility across the region's fragmented procurement landscape.
Market Dynamics
Modular product bundling is compressing procurement cycles across Indonesia, Vietnam, and the Philippines as state contractors consolidate admixture-waterproofing-sealant specifications into single-source packages, forcing suppliers to restructure technical service teams around integrated system validation rather than individual product sales.
Growth Catalysts
- Transit-oriented development mandates:Indonesia's Ministry of Public Works and Housing prioritizes flood-resilient concrete specifications for Greater Jakarta MRT extensions, pulling high-performance admixtures into every station and viaduct pour.
- Green Mark certification expansion:Singapore's Building and Construction Authority tightens VOC thresholds for sealants in commercial towers, creating specification premiums for low-emission formulations that contractors must meet to secure public leases.
- Polymer-modified binders:Bridge and tunnel projects across Vietnam's North-South Expressway corridor absorb cementitious repair compounds engineered for saline intrusion resistance, extending asset design lives beyond conventional concrete rehabilitation cycles.
Market Restraints
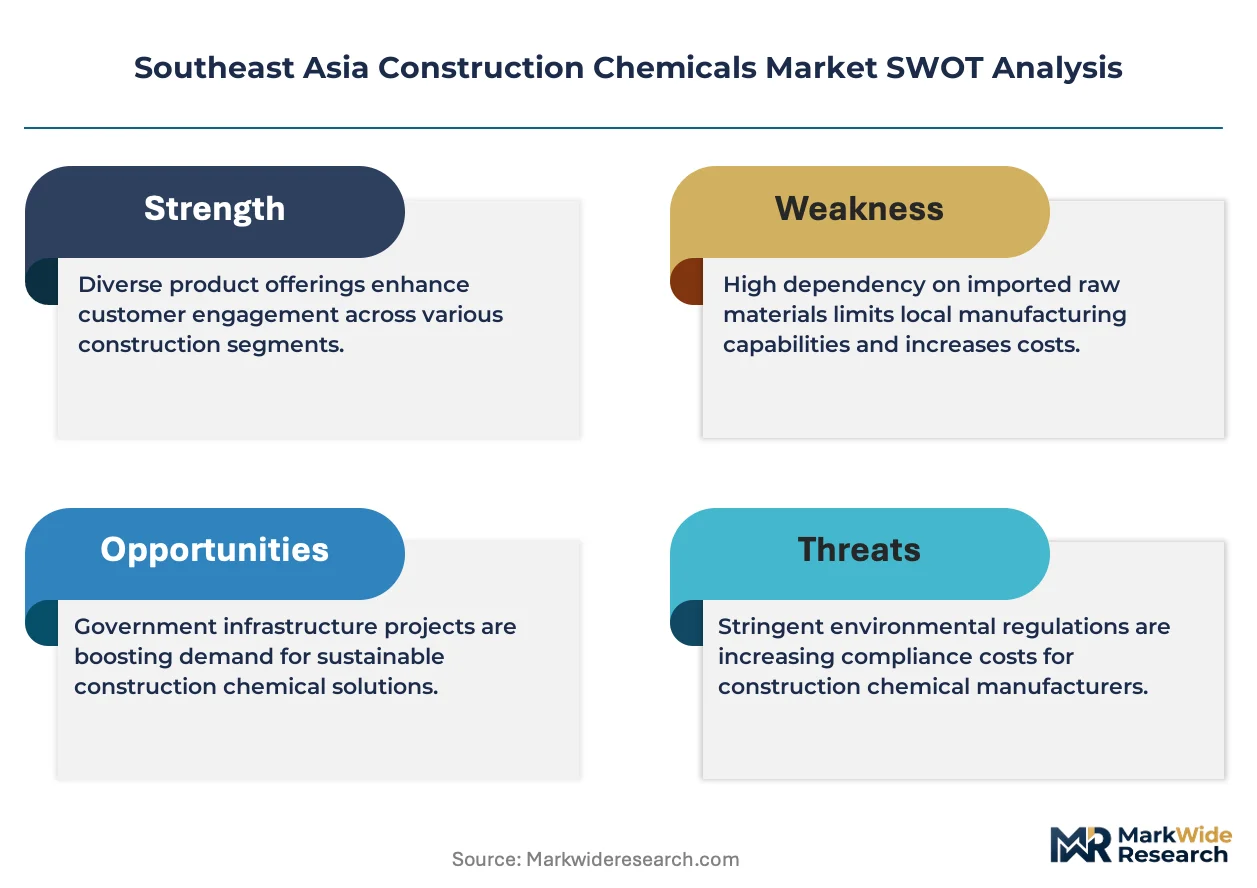
- Petrochemical feedstock volatility:Acrylic and epoxy resin prices fluctuate with regional naphtha cracking margins, compressing formulation margins for waterproofing membrane producers serving Indonesian infrastructure tenders.
- Import dependency concentration:Specialty surfactants and redispersible polymer powders concentrate through Singaporean and Thai distributors, exposing Vietnamese contractors to currency-adjusted cost spikes during project execution phases.
- Performance standard fragmentation:Divergent national compulsory standards between Indonesia's SNI and Vietnam's TCVN frameworks force suppliers to maintain parallel certification inventories, inflating compliance overhead for cross-border project participation.
Strategic Opportunities
- Philippine secondary city penetration:Cebu and Davao infrastructure pipelines lack established construction chemical distribution networks, opening first-mover positioning for localized blending facilities serving Visayas and Mindanao port modernization.
- Carbon-capture concrete additives:Emerging mineralization technologies that embed CO2 into cement hydration products align with Singapore's Green Mark 2025 carbon intensity benchmarks, creating premium positioning for early formulation adopters.
- Direct contractor engagement platforms:Digital specification tools that bypass traditional distributor layers are capturing volume from mid-sized Indonesian contractors managing multiple simultaneous public housing projects.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in tropical humidity stabilization and seismic load rheology remains concentrated in Singapore and Bangkok, constraining technical service expansion for suppliers targeting Vietnamese provincial markets.
- Pre-qualification timeline compression:Indonesia's state-owned enterprise procurement windows now demand six-month certification cycles for new admixture suppliers, shortening viable entry pathways for specialized product lines.
- Legacy specification inertia:Established contractor relationships with incumbent waterproofing membrane brands in Thailand's commercial building segment delay specification switches to newer polymer-modified alternatives despite superior performance data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Construction Chemicals Market |
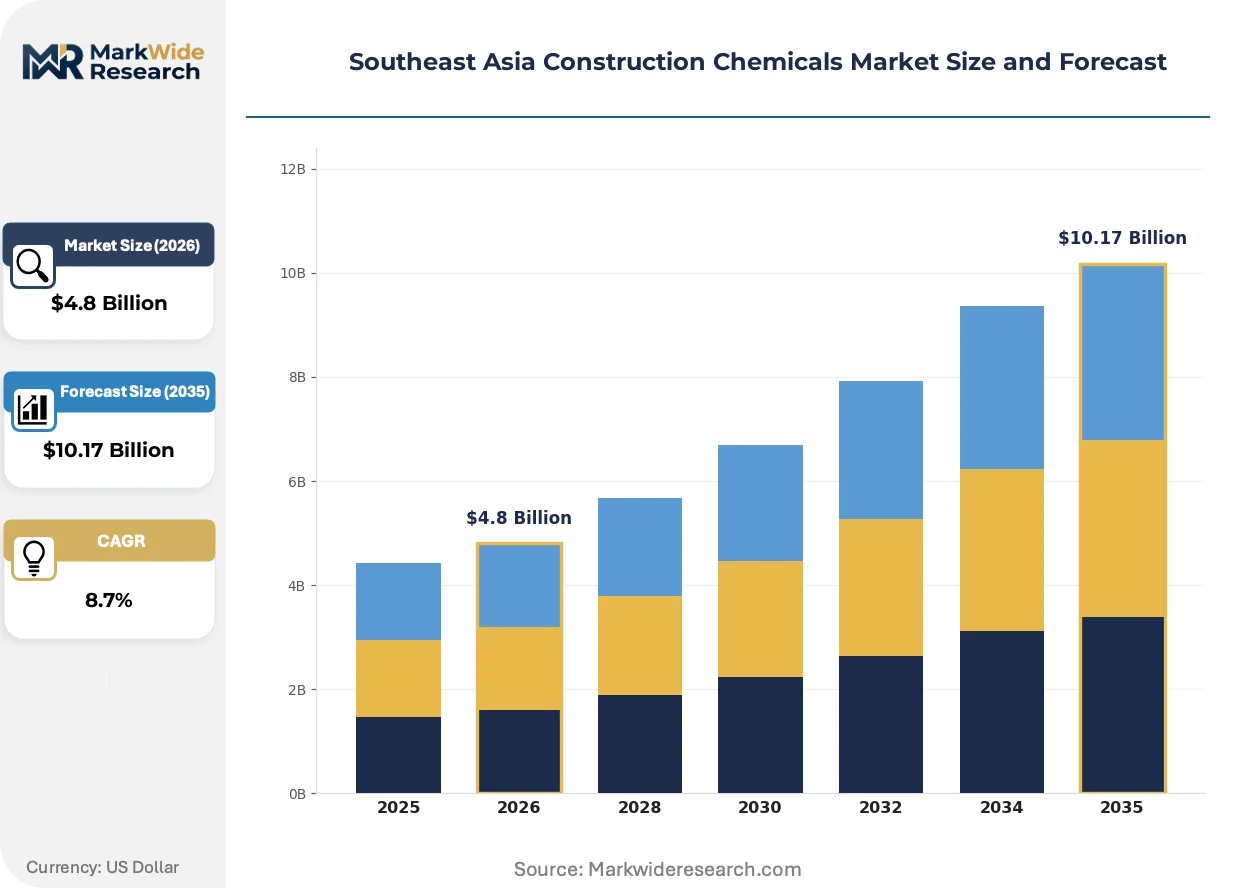
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Waterproofing, Repair Compounds Application: Commercial Buildings, Infrastructure, Residential Projects, Industrial Facilities End User: Contractors, Builders, Architects, Engineers Distribution Channel: Direct Sales, Retail, Online Platforms, Wholesale |
| Companies Covered | MAPEI S.p.A., Holcim, BASF SE, Dow Inc., Henkel AG and Co. KGaA, Sika AG, Saint Gobain, Fosroc International Ltd., Akzo Nobel NV, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Construction Chemicals Market Evolving Landscape
Digital specification platforms and bio-based polymer research are restructuring how construction chemicals move from laboratory to jobsite across Southeast Asia, compressing traditional distributor hierarchies while opening formulation differentiation paths.
Self-healing concrete admixtures containing encapsulated bacterial spores or mineral precursors are overtaking conventional crack-injection repair methods in Indonesia's coastal infrastructure pipeline. State contractors for the Patimban Deep Sea Port specify these formulations for quay walls and container yards where access for post-construction maintenance remains restricted. The technology is compressing lifecycle cost calculations for asset owners who previously budgeted for periodic epoxy injection campaigns.
Singapore's Green Mark 2025 revision tightens embodied carbon thresholds for structural materials, forcing waterproofing and sealant suppliers to submit Environmental Product Declarations verified against ISO 14025. Commercial tower developers now pre-qualify formulation partners based on cradle-to-gate carbon footprints before technical performance evaluation. Thai and Malaysian suppliers without established lifecycle assessment capabilities are losing specification access to Singapore's core central business district pipeline.
Contractor procurement teams across Vietnam's bridge construction sector now bundle admixture, waterproofing, and repair compound specifications into single-source technical service agreements. State project managers for the Ninh Binh–Thanh Hoa expressway segment consolidate supplier accountability for concrete durability outcomes rather than discrete product performance. This compression is marginalizing distributors who lack in-house application engineering capabilities.
Southeast Asia Construction Chemicals Market Segmentation
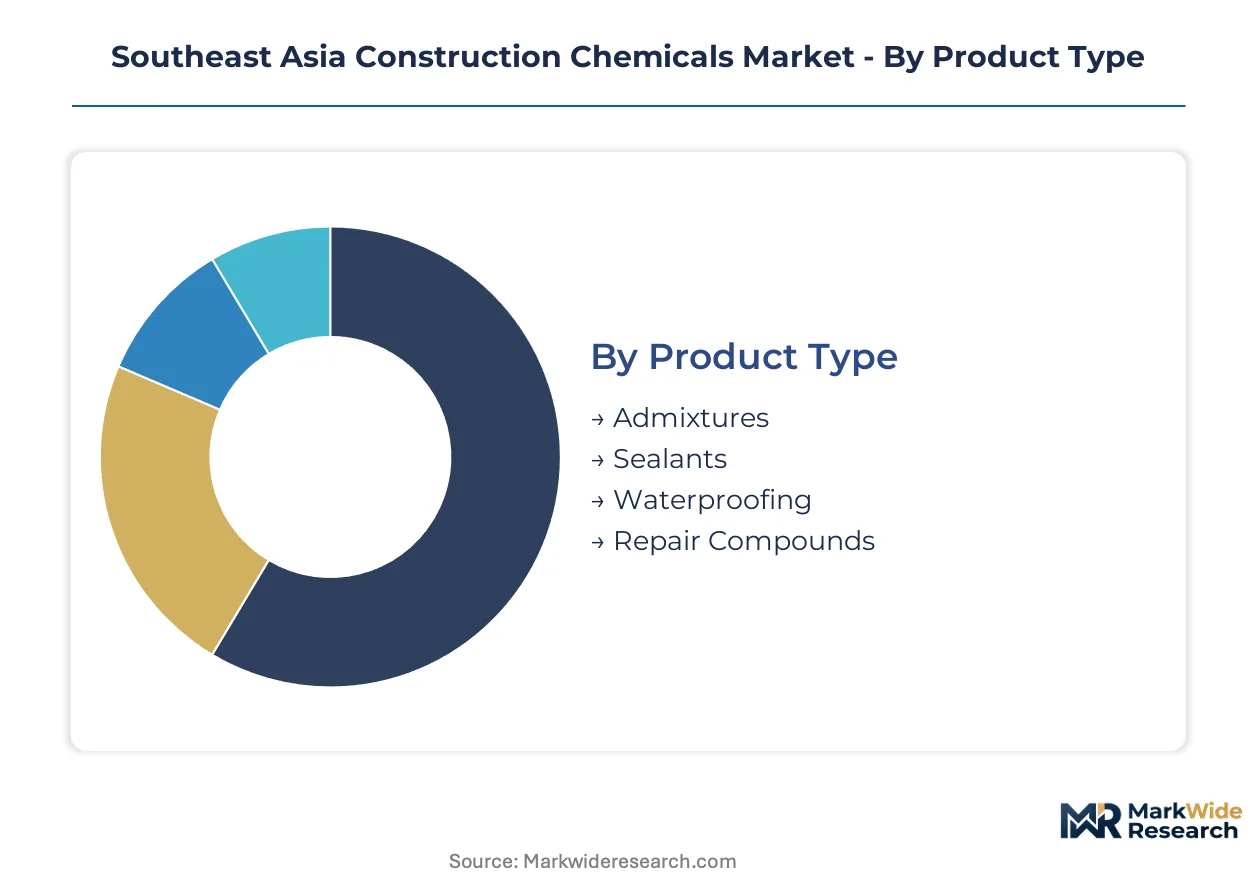
Construction chemicals in Southeast Asia fragment across product chemistry, project scale, and procurement authority. Specification power concentrates with state contractors in Indonesia and Vietnam, while private developers in Singapore and Thailand drive premium formulation demand through green certification mandates.
Product Type:
Volume concentrates in commodity-grade formulations for mass concrete pours. Premium margins attach to specialty systems delivering extended durability warranties.
- Admixtures:These formulations modify concrete rheology through plasticizers, retarders, and accelerators engineered for tropical humidity cycles. Demand concentrates in Indonesia's Greater Jakarta transit corridor where MRT viaduct specifications mandate high-range water reducers for pumpability across seismic zones.
- Waterproofing:Polymer-modified membranes and crystalline coatings protect substructures from saline intrusion and seasonal flooding. Newer deployment concentrates in Vietnamese coastal industrial zones where port modernization projects specify multi-layer systems with 20-year performance guarantees.
- Sealants:Polyurethane and silicone formulations accommodate structural movement while blocking moisture ingress. Singapore's Green Mark standards restrict VOC content below 50g/L for commercial tower applications.
- Repair Compounds:Cementitious grouts and epoxy injection systems restore deteriorated concrete substrates. Philippine contractors deploy these for retrofitting aging infrastructure in Cebu and Davao.
Mature deployment sits with Admixtures. Newer deployment is concentrated in Waterproofing.
Application:
Infrastructure projects absorb the highest specification intensity per cubic meter of concrete. Commercial buildings generate recurring demand through maintenance cycles and tenant improvement work.
- Infrastructure:Bridge, tunnel, and port construction specifications demand performance-grade admixtures and waterproofing systems validated for seismic loading. Indonesia's Patimban Deep Sea Port and Vietnam's North-South Expressway anchor regional volume.
- Commercial Buildings:High-rise towers in Singapore's central business district require low-VOC sealants and carbon-accounted waterproofing to meet Green Mark 2025 benchmarks.
- Residential Projects:Mass housing developments across Greater Jakarta and Ho Chi Minh City absorb commodity waterproofing for podium slabs and basement structures.
- Industrial Facilities:Manufacturing plants and logistics centers in Thai eastern seaboard zones specify chemical-resistant flooring systems and joint sealants.
Specification complexity peaks in Infrastructure. Volume scale concentrates in Residential Projects.
End User:
Procurement authority determines formulation tier. State-owned enterprises consolidate specifications across multi-project portfolios, while private developers optimize for first-cost constraints.
- Contractors:Execution-focused firms managing Indonesian public housing and Vietnamese expressway segments bundle admixture-waterproofing-repair specifications into single-source technical service agreements.
- Builders:Commercial tower developers in Singapore and Bangkok pre-qualify suppliers based on Environmental Product Declarations before technical evaluation.
- Architects:Design professionals specify aesthetic and performance requirements for sealants and exposed concrete finishes in premium commercial projects.
- Engineers:Structural and geotechnical consultants mandate durability testing protocols for waterproofing systems in flood-resilient designs.
Consolidated procurement authority sits with Contractors. Fragmented specification influence characterizes Architects.
Distribution Channel:
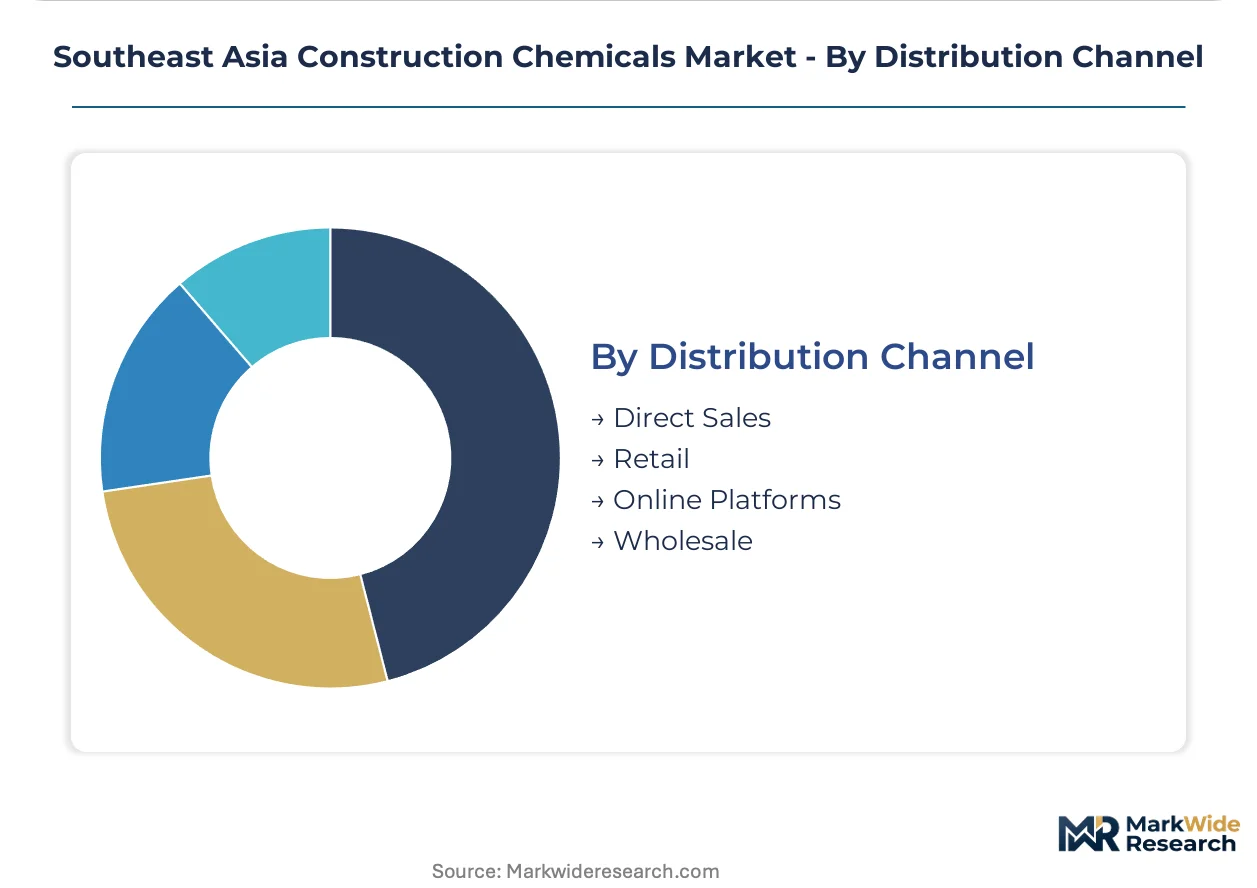
Channel selection tracks project scale and technical service requirements. Large infrastructure mandates direct supplier engagement, while smaller commercial work flows through intermediaries.
- Direct Sales:Supplier technical teams embed with Indonesian state contractors and Vietnamese bridge project managers for integrated system validation and pour-side support.
- Wholesale:Regional distributors in Bangkok and Singapore inventory commodity admixtures and waterproofing membranes for mid-tier contractors across secondary cities.
- Retail:Hardware-focused channels serve Thai and Philippine residential repair markets with tile adhesives and small-format sealant cartridges.
- Online Platforms:Digital specification tools capture volume from Indonesian contractors managing simultaneous public housing projects, compressing traditional distributor layers.
High-touch deployment concentrates in Direct Sales. Self-service procurement is expanding fastest through Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Singapore and Thailand, while consumption gravity pulls toward Indonesia and Vietnam where mega-infrastructure deployment outpaces domestic formulation capabilities. This structural gap forces regional suppliers to coordinate cross-border technical service teams.
Indonesia
Greater Jakarta's transit-oriented development absorbs high-performance admixtures for MRT viaducts and flood-resilient station foundations. The Ministry of Public Works and Housing imposes national compulsory standards on concrete additives for public infrastructure tenders. State-owned contractors in the Patimban Deep Sea Port corridor specify self-healing concrete formulations for quay walls where maintenance access is restricted.
Vietnam
The North-South Expressway corridor drives demand for polymer-modified repair compounds engineered against saline intrusion in coastal bridge segments. The Directorate for Standards, Metrology and Quality aligns cementitious specifications with ASEAN harmonized frameworks. Contractors in the Ninh Binh–Thanh Hoa expressway segment bundle admixture-waterproofing-repair specifications into single-source technical service agreements.
Singapore
Commercial tower developers in the central business district pre-qualify suppliers based on Environmental Product Declarations before technical evaluation. The Building and Construction Authority enforces Green Mark standards that restrict VOC content in sealants below 50g/L. Premium formulation demand concentrates in Marina Bay and Jurong Lake District projects where embodied carbon thresholds tighten specification access.
Thailand
The Eastern Economic Corridor absorbs chemical-resistant flooring systems and joint sealants for manufacturing plants and logistics centers. National industrial estate authorities coordinate with the Thai Industrial Standards Institute on performance benchmarks for construction chemicals. Rayong and Chonburi industrial zones anchor regional distribution networks serving mid-tier contractors across secondary cities.
Philippines
Cebu and Davao infrastructure pipelines lack established construction chemical distribution networks, opening positioning for localized blending facilities. The Department of Public Works and Highways prioritizes repair compound deployment for retrofitting aging structures in Visayas and Mindanao. Port modernization in secondary cities pulls waterproofing specifications away from Metro Manila-centric supply chains.
Southeast Asia Construction Chemicals Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Southeast Asia's construction chemicals sector. The vendor base fragments across three tiers: integrated multinational suppliers with regional technical service networks, mid-scale regional blenders serving national infrastructure pipelines, and niche specialists concentrated in single product categories. Strategic archetypes include system integrators bundling waterproofing-admixture-sealant packages, carbon-accounted formulation leaders capturing Singapore Green Mark premiums, and digital-native distributors compressing traditional channel layers. Dominant competitive moves encompass direct contractor engagement platforms bypassing wholesale intermediaries, and backward integration into specialty polymer production to hedge petrochemical feedstock volatility.
Within the multinational integrated tier, Sika AG, BASF SE, and MAPEI S.p.A. occupy anchor positions. Sika AG exemplifies system-level bundling through integrated waterproofing-admixture specifications. BASF SE represents high-performance concrete additive capabilities extending into bridge and tunnel projects. MAPEI S.p.A. anchors tile-setting and flooring specialization for commercial building segments. These three entities collectively illustrate the competitive spectrum from full-system integration to category-specific depth.
| Leading Market Players |
|---|
| MAPEI S.p.A. |
| Holcim |
| BASF SE |
| Dow Inc. |
| Henkel AG and Co. KGaA |
| Sika AG |
| Saint Gobain |
| Fosroc International Ltd. |
| Akzo Nobel NV |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock costs for acrylic and epoxy resins cascade through formulation margins as Singaporean and Thai distributors apply currency-adjusted markups before Vietnamese contractors absorb final project pricing. This input-cost transmission concentrates pricing power with integrated suppliers controlling captive polymer production, while fragmented Indonesian contractors face compressed margins on public infrastructure tenders.
Pricing Analysis
Margin tightening in commodity admixtures reflects naphtha cracking volatility and Indonesian state tender pricing protocols that prioritize lowest-compliant bids. Three-tier pricing structure across performance-grade, standard, and economy levels separates Green Mark-certified sealants for Singapore towers from generic waterproofing for Jakarta mass housing. Cost-down pressure on Vietnamese bridge project specifications accelerates as contractors bundle admixture-waterproofing-repair packages into single-source accountability. State-owned enterprises exhibit lowest price sensitivity due to durability warranty requirements, while mid-tier Indonesian residential developers negotiate hardest on per-kilogram admixture rates.
Supply Chain Analysis
Freight costs from Singaporean specialty chemical hubs to Vietnamese project sites inflate landed costs for redispersible polymer powders and surfactant intermediates. Supply concentrates in Thailand and Singapore for formulation blending, while Indonesia and Vietnam function as demand sinks with limited domestic production. Raw material dependencies center on Malaysian palm-oil-derived emulsifiers, South Korean acrylic acid shipments, and Chinese epoxy resin bulk supply. Single-source vulnerability sits with Singaporean distributors controlling ASEAN-wide inventory positioning for crystalline waterproofing additives. Distribution runs through direct technical service teams for Indonesian infrastructure megaprojects and wholesale networks for Thai commercial building maintenance cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemist scarcity across Vietnamese provincial markets props pricing premiums for suppliers maintaining Singapore-based technical service capabilities. Capacity constraints in localized blending infrastructure concentrate margin capture with established multinationals.
For Market Incumbents: Acquire regional distribution networks in Cebu and Davao to preempt Philippine secondary city infrastructure deployment. Secure backward integration into redispersible polymer powder production to hedge petrochemical feedstock volatility eroding waterproofing membrane margins. Counter emerging digital-native distributors through embedded pour-side technical validation teams that Indonesian state contractors now mandate for MRT project qualification. For New Entrants and Emerging Players: Mid-sized Indonesian contractors managing simultaneous public housing projects represent the most penetrable buyer archetype for digital specification platforms bypassing traditional wholesale layers. Target Vietnamese provincial bridge segments lacking established technical service coverage. Lead with carbon-capture concrete additive formulations aligned with Singapore Green Mark 2025 embodied carbon thresholds to secure central business district tower pre-qualification. For Investors and Strategic Acquirers: Indonesian state-owned enterprise procurement windows compressing supplier certification cycles to six months is the leading indicator that technical service capabilities will consolidate toward incumbent control. Five-to-ten-year viability favors suppliers with integrated waterproofing-admixture-sealant bundling capacity and established Environmental Product Declaration verification. Watch for Philippine Department of Public Works and Highways repair compound tender volumes in Visayas and Mindanao as inflection signal for localized blending facility ROI.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive acrylic resin supply hedges naphtha margin volatility for Indonesian waterproofing tenders. |
| Carbon-Capture Additive Formulation Launch | Mineralization technology secures Green Mark 2025 pre-qualification for Singapore commercial towers. |
| Direct Contractor Digital Platform Deployment | Bypasses Bangkok distributor layers to capture Indonesian public housing project volume. |
| Localized Blending Facility Establishment | Cebu and Davao positioning captures Philippine secondary city port modernization specifications. |
| Integrated System Technical Service Expansion | Single-source accountability bundles meet Vietnamese North-South Expressway contractor procurement protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at Indonesian admixture blending facilities, procurement leads at Vietnamese state contractors, distribution channel partners in Bangkok, and technical R&D directors at Singapore formulation centers combined with Indonesian Ministry of Public Works and Housing tender databases, ASEAN customs harmonization records, and Singapore Building and Construction Authority Green Mark certification lists. Bottom-up project pipeline assessments and top-down chemical consumption estimates triangulated volume figures.
Granularity-level modeling disaggregated demand across product chemistry tiers, application scale from infrastructure megaprojects to residential maintenance, and procurement authority concentration from state-owned enterprises to fragmented private developers. CAGRs derived from weighted project commissioning schedules and specification intensity curves across the analysis window. Industry-specific inputs included Indonesian MRT viaduct concrete pour schedules, Vietnamese expressway segment completion timelines, and Singapore commercial tower embodied carbon threshold phase-in protocols.
Revisions become necessary when Indonesian compulsory standard certification timelines accelerate, Vietnamese Dong volatility disrupts import cost structures, or Singapore Green Mark carbon intensity benchmarks tighten ahead of scheduled review cycles. Forecasts reflect documented assumptions about infrastructure budget execution rates and petrochemical feedstock price band stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Naturally Derived Fatty Alcohol Market
Chemicals
Chromium Trioxide Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Fatty Alcohol Market
Chemicals
Sodium Azide Market
Chemicals
Scouring Agents Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Potassium Alum Market
Chemicals
3-Dimethylacrylic Acid Methyl Ester Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Potassium Iodide Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
Welding Chemicals Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Triethylaluminum Market