
 Self-Supervised Learning Market | 2026-2036
Self-Supervised Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Supervised Learning Market Intelligence
Foundation model pre-training is reconfiguring how AI capabilities are developed and commercialized. Google LLC leverages massive unlabeled corpus access to sustain its position in large language model development. Meta Platforms, Inc. anchors its open-source strategy on publicly released self-supervised checkpoints that reduce downstream training costs. NVIDIA dominates the silicon layer, controlling GPU supply chains that determine which labs can execute billion-parameter pre-training runs.
Self-supervised learning denotes machine learning paradigms where models derive supervisory signals from the intrinsic structure of raw data rather than human-annotated labels, typically employing contrastive objectives, masked prediction, or autoregressive density estimation across billions of unlabeled examples to produce generalizable representations for downstream fine-tuning. Natural language processing represents the most mature application segment, with transformer-based masked language modeling now standard across commercial search and generation products. Edge computing deployment is gaining traction as compressed self-supervised encoders enable on-device inference without cloud dependency, though cloud-based training remains where capital concentrates.
The EU AI Act imposes documentation and risk-classification obligations on general-purpose AI models, directly affecting how self-supervised foundation models enter European markets. The FDA has begun issuing guidance on adaptive AI systems in healthcare, creating compliance pathways that favor self-supervised approaches with robust validation frameworks. Stakeholders must monitor whether emerging compute-export controls fragment pre-training infrastructure across jurisdictional boundaries.
Market Dynamics
Compute scarcity is concentrating pre-training capacity among cloud hyperscalers and venture-backed labs with secured GPU allocations, fundamentally reshaping how self-supervised foundation models enter commercial circulation.
Growth Catalysts
- FDA adaptive AI guidance:The FDA's emerging framework for continuously learning diagnostic systems creates compliance pathways favoring self-supervised approaches with built-in validation protocols in radiology and pathology workflows.
- Edge deployment compression:Distilled self-supervised encoders enable on-device inference for autonomous vehicles and industrial inspection without cloud dependency, opening manufacturing and automotive verticals previously blocked by latency constraints.
- EU AI Act transparency mandates:Documentation requirements for general-purpose AI models are accelerating investment in interpretability tools for self-supervised architectures, creating competitive differentiation for providers with robust provenance systems.
Market Restraints
- NVIDIA GPU supply concentration:Single-source dependency for H100 and successor silicon creates allocation bottlenecks that determine which research organizations can execute billion-parameter training runs.
- Energy cost volatility:Pre-training runs consume tens of megawatt-hours per model iteration, exposing capital-intensive labs to electricity price swings in data center clusters across Texas, Virginia, and Singapore.
- Data licensing friction:Copyright ambiguity surrounding web-scale training corpora generates legal exposure that chilled dataset construction for commercial foundation model development in 2023-2024.
Strategic Opportunities
- Scientific computing convergence:Self-supervised protein folding models trained on genomic sequences are hybridizing with small-molecule simulation, creating pharmaceutical discovery platforms that bypass traditional structure-based drug design timelines.
- India's digital public infrastructure:The country's language diversity and digitized governance records present untapped corpus potential for Indic language foundation models serving 1.4 billion citizens.
- Climate modeling acceleration:Physics-informed neural networks trained through masked prediction on satellite and sensor data are compressing weather forecasting horizons previously requiring supercomputer allocation.
Industry Challenges
- Distributed systems engineering talent:The specialized skill set for orchestrating thousand-GPU training clusters across multiple data centers commands compensation premiums that exclude mid-scale research organizations from frontier model development.
- Evaluation standardization gaps:Absence of agreed benchmarks for emergent capabilities in large language models forces buyers to rely on vendor claims rather than reproducible performance metrics during procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Supervised Learning Market |
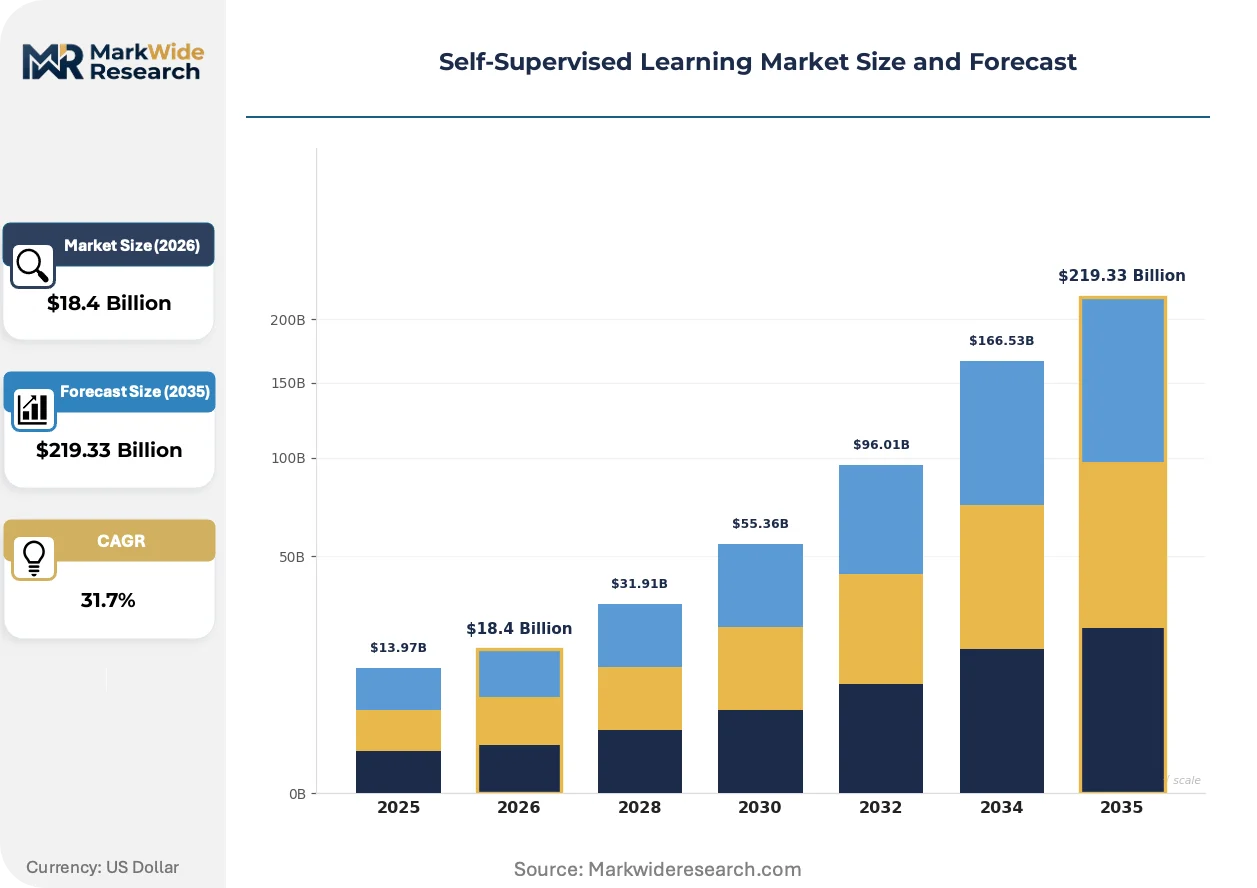
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $219.33 Billion |
| CAGR (2026 – 2036) | 31.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Natural Language Processing, Computer Vision, Audio Analysis, Recommendation Systems Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Healthcare, Finance, Retail, Manufacturing Technology: Neural Networks, Transformers, Graph-Based Learning, Generative Models |
| Companies Covered | Google LLC, Microsoft, Amazon Web Services, Inc., IBM Corporation, Meta Platforms, Inc., OpenAI, Inc., NVIDIA, Apple Inc., Databricks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Supervised Learning Market Strategic Shifts & Innovations
Foundation model development is fragmenting across training paradigms, with contrastive learning, masked prediction, and autoregressive methods each carving distinct application territories based on data modality and downstream task requirements.
Multimodal self-supervised architectures are hybridizing vision and language representations into unified embedding spaces. Automotive perception teams at Tier-1 suppliers are deploying these fused encoders for end-to-end autonomous navigation systems. The convergence is compressing sensor fusion pipelines that previously required separate training stages for camera, lidar, and radar inputs.
The EU AI Act's risk-tier classification system is forcing documentation investments across general-purpose model providers. Developers must now maintain technical files detailing training data provenance and capability evaluations before market entry. Healthcare AI vendors targeting European hospitals are restructuring compliance teams to satisfy conformity assessment procedures for high-risk diagnostic applications.
Enterprise buyers are unbundling model licensing from inference infrastructure commitments. Financial services firms in New York and London are negotiating direct checkpoint access for self-supervised foundation models, then deploying on private cloud or on-premise clusters to satisfy data residency requirements. This procurement pattern is fragmenting the integrated SaaS model that dominated early commercialization.
Self-Supervised Learning Market Segmentation
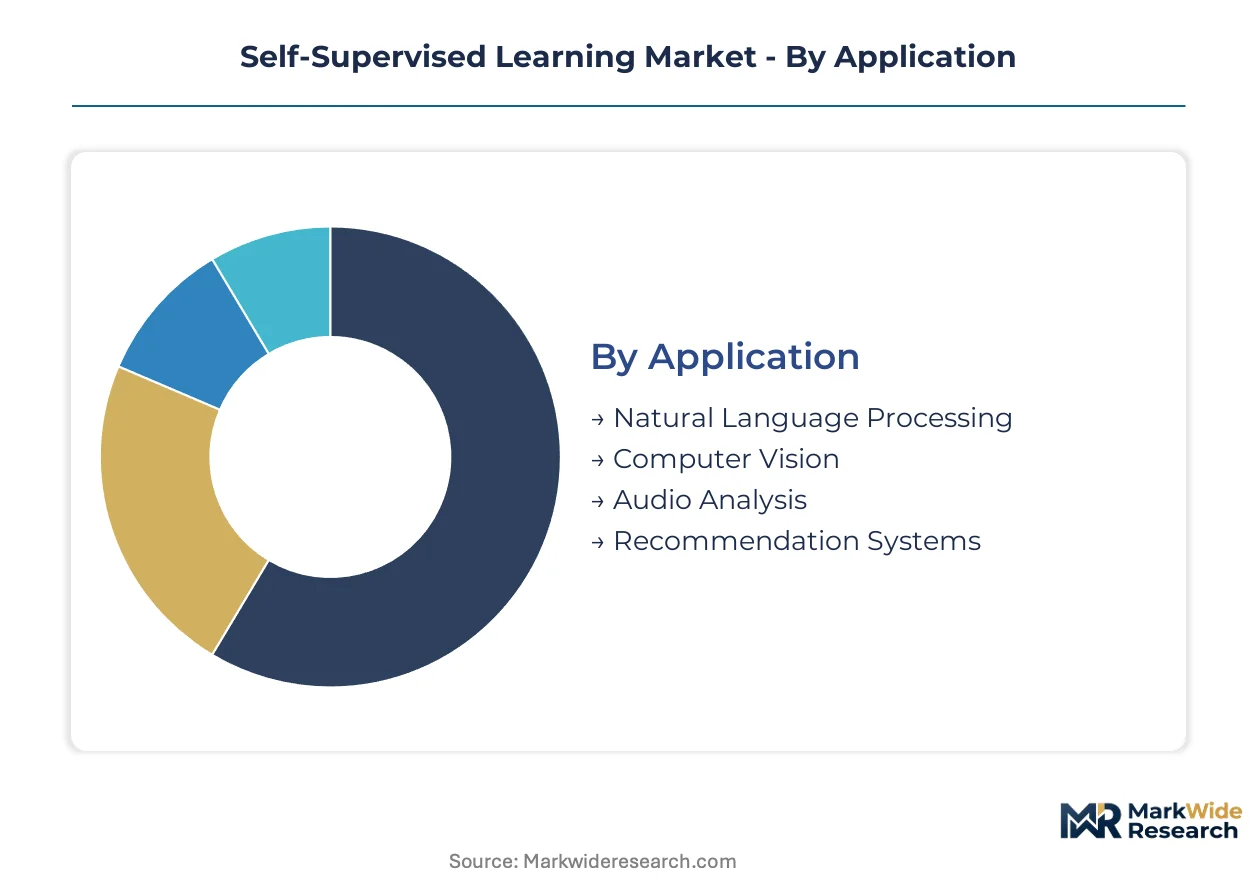
Segmentation in self-supervised learning reveals how capital, talent, and data assets distribute across divergent technical requirements. Application-level differences drive infrastructure choices more sharply than in supervised paradigms, where labeled dataset construction once unified workflows.
Application:
Cycle times vary dramatically: NLP models iterate monthly on fresh web corpus while computer vision architectures stabilize over multi-year horizons on static image benchmarks.
- Natural Language Processing:Transformer-based masked language modeling consumes the largest training budgets, with autoregressive and bidirectional architectures demanding continuous data pipeline engineering. Financial services firms in New York deploy these systems for document understanding and generation workflows.
- Computer Vision:Contrastive pre-training on unlabeled image collections produces encoders for defect detection and medical imaging. Automotive perception teams at Tier-1 suppliers integrate these models into end-to-end navigation stacks.
- Audio Analysis:Self-supervised speech representations enable voice biometric systems without speaker-labeled training data.
- Recommendation Systems:Sequential masked prediction captures user behavior patterns from raw interaction logs.
Natural Language Processing anchors the volume base while Computer Vision gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates capital-intensive pre-training from inference-optimized delivery mechanisms.
- Cloud-Based:Hyperscaler GPU clusters execute billion-parameter training runs requiring tens of megawatt-hours per iteration. This tier captures foundation model development spend concentrated in Northern Virginia, Texas, and Singapore data center corridors.
- Edge Computing:Distilled encoders enable on-device inference for autonomous vehicles and industrial inspection without cloud dependency. Manufacturing verticals previously blocked by latency constraints now access self-supervised capabilities.
- On-Premise:Private clusters satisfy data residency requirements for healthcare and financial services.
- Hybrid:Split architectures train in cloud environments while inference executes on regulated infrastructure.
Cloud-Based deployment commands the capital intensity while Edge Computing expands most quickly as compression techniques mature.
End User:
Customer type determines compliance burden and procurement timeline, with regulated industries imposing extended validation cycles.
- Healthcare:FDA adaptive AI guidance creates compliance pathways for continuously learning diagnostic systems in radiology and pathology. Self-supervised approaches with built-in validation protocols satisfy emerging regulatory expectations.
- Finance:Model interpretability requirements under SEC and EU AI Act obligations drive investment in provenance documentation. Firms negotiate direct checkpoint access for private deployment.
- Retail:Recommendation and search systems leverage sequential self-supervised training on transaction and browsing data.
- Manufacturing:Visual inspection systems deploy compressed encoders for quality control on production lines.
Healthcare dominates compliance-driven R&D spend while Finance shows the steepest procurement acceleration.
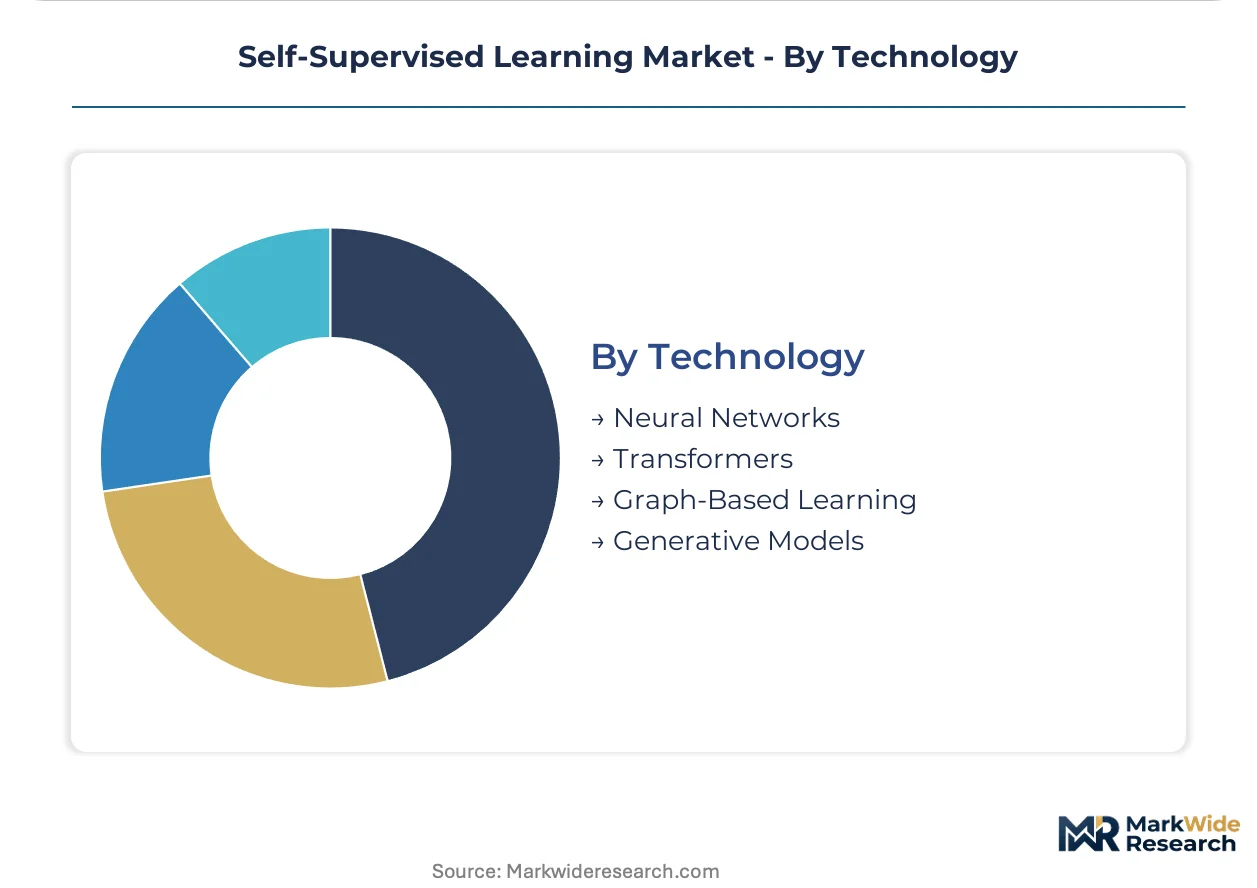
Technology:
Supply concentration in GPU allocation shapes which architectural families advance, with transformer scaling laws favoring well-capitalized labs.
- Transformers:Attention-based architectures scale predictably with compute and data, concentrating frontier development among organizations with secured H100 allocations. Masked language and autoregressive objectives dominate commercial applications.
- Neural Networks:Convolutional and recurrent architectures persist in resource-constrained deployment scenarios where transformer inference costs prove prohibitive.
- Generative Models:Diffusion and flow-based objectives enable synthetic data generation and content creation pipelines.
- Graph-Based Learning:Relational inductive biases suit molecular and social network applications where structured reasoning matters.
Transformers anchor the research investment base while Generative Models climb the fastest as multimodal capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud hyperscalers and venture-backed AI labs concentrate pre-training infrastructure in jurisdictions with favorable energy pricing and GPU supply chain access. Buyer archetypes span healthcare systems seeking FDA-compliant diagnostic tools, financial institutions navigating SEC and EU AI Act obligations, and automotive manufacturers deploying edge-compressed encoders.
United States
Financial services firms in New York and technology companies in Northern Virginia drive cloud-based foundation model procurement. The SEC's emerging guidance on AI-driven investment systems imposes documentation requirements that favor self-supervised architectures with built-in validation protocols. Texas data center corridors host billion-parameter training runs consuming tens of megawatt-hours per iteration.
China
Domestic cloud providers and state-affiliated research institutes advance multimodal self-supervised architectures for industrial inspection and smart city deployment. MIIT standards for algorithmic recommendation systems create compliance frameworks that shape training data provenance documentation. The Yangtze River Delta concentration anchors computer vision pre-training for manufacturing quality control.
Germany
Automotive Tier-1 suppliers in Bavaria and Baden-Württemberg integrate contrastive vision encoders into end-to-end autonomous navigation stacks. The EU AI Act's risk-tier classification mandates technical file documentation before market entry for general-purpose AI models. Berlin-based research labs specialize in interpretability tools for transformer architectures facing transparency obligations.
United Kingdom
London financial institutions negotiate direct checkpoint access for private cloud deployment to satisfy data residency requirements. The Information Commissioner's Office guidance on automated decision-making shapes validation frameworks for self-supervised diagnostic systems. Cambridge and Oxford research clusters advance protein folding models trained on genomic sequences for pharmaceutical discovery.
India
The country's language diversity and digitized governance records present corpus potential for Indic language foundation models serving 1.4 billion citizens. BIS standards for AI system safety create emerging compliance pathways for healthcare and financial applications. Bengaluru and Hyderabad technology corridors concentrate edge deployment engineering for compressed encoders in mobile and IoT contexts.
Self-Supervised Learning Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure concentrated among cloud hyperscalers with secured GPU allocations and venture-backed research labs with exclusive data access. Three archetypes dominate: vertically integrated cloud providers controlling training infrastructure, open-source checkpoint distributors reducing downstream costs, and silicon layer suppliers determining which organizations can execute frontier model development. Competitive moves center on strategic partnerships for corpus access and geographic expansion of inference infrastructure to satisfy data residency requirements.
Within the cloud-provider archetype, Google LLC and Amazon Web Services, Inc. anchor positions through massive unlabeled corpus access and hyperscaler GPU cluster control. Meta Platforms, Inc. exemplifies the open-source checkpoint distribution model, publicly releasing self-supervised encoders that compress downstream training costs for enterprise buyers. NVIDIA occupies the silicon-layer position, with supply chain control over H100 and successor GPU allocations determining which labs can execute billion-parameter pre-training runs. Microsoft and IBM Corporation represent diversified technology conglomerates spanning cloud infrastructure, enterprise software integration, and regulated industry compliance tooling.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft |
| Amazon Web Services, Inc. |
| IBM Corporation |
| Meta Platforms, Inc. |
| OpenAI, Inc. |
| NVIDIA |
| Apple Inc. |
| Databricks |
| Others |
Cost & Logistics Intelligence
Trans-Pacific fiber corridors connecting Northern Virginia to Singapore data centers carry bandwidth costs that concentrate pre-training capacity among cloud hyperscalers, translating GPU scarcity into tiered access pricing that separates venture-backed labs from mid-scale research organizations.
Pricing Analysis
Cost-plus contracts indexed to spot electricity rates in Texas and Singapore data center clusters dominate foundation model training services. Pricing stratifies across premium reserved-capacity tiers for billion-parameter runs, standard on-demand allocations, and economy spot-interruptible instances. Cost compression in economy tiers intensifies as distillation techniques reduce per-inference energy draw. Healthcare systems exhibit lowest price sensitivity due to FDA compliance requirements, while retail recommendation engine buyers negotiate aggressively on per-token rates.
Supply Chain Analysis
Export controls on H100 and successor GPU architectures limit flows from Taiwan and South Korea into Chinese research institutes, fragmenting pre-training infrastructure across jurisdictional boundaries. The supply chain draws from TSMC fabrication in Taiwan, HBM memory from South Korean suppliers, and substrate packaging in Malaysia. Single-source vulnerability at the silicon layer creates allocation bottlenecks determining which labs execute frontier runs. Distribution runs through cloud hyperscaler marketplaces and direct enterprise licensing for checkpoint access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation model commercialization fragments across deployment models as enterprise buyers unbundle inference infrastructure from training commitments, creating niche opportunities for specialized compliance tooling and edge-compressed encoders.
For Market Incumbents: Build data-provenance moats through technical file documentation systems satisfying EU AI Act transparency mandates. Incumbents should secure exclusive corpus licensing agreements with academic publishers and code repositories to block challenger training data access. GPU allocation guarantees through multi-year NVIDIA supply contracts represent the critical defensive lever against venture-backed labs threatening frontier model capabilities. For New Entrants and Emerging Players: Indic-language foundation models serving India's digitized governance and healthcare records represent the most penetrable entry point given limited existing checkpoint coverage. Edge deployment engineering for compressed vision encoders in automotive Tier-1 supplier pipelines offers second white-space targeting. Go-to-market should emphasize direct checkpoint licensing bypassing cloud marketplace fees to capture price-sensitive manufacturing verticals. For Investors and Strategic Acquirers: Carve-out targets emerge from hyperscaler AI research divisions spinning out specialized vertical applications. Long-term viability hinges on distinguishing training-data rights from model weights in acquisition structures. Watch for FDA adaptive AI guidance finalization as inflection signal triggering healthcare procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Technical File Documentation Investment | EU AI Act compliance creates competitive differentiation for European hospital system contracts. |
| GPU Allocation Securement | Multi-year NVIDIA supply contracts determine which labs execute billion-parameter training runs. |
| Edge Encoder Distillation | Compressed architectures unlock automotive and manufacturing verticals blocked by latency constraints. |
| Direct Checkpoint Licensing | Financial services firms in New York and London negotiate private deployment satisfying data residency. |
| Indic Language Corpus Development | India's digitized governance records enable foundation models serving 1.4 billion citizens. |
Research Approach
Operator-level perspectives from foundation model engineering leads, healthcare AI procurement officers, cloud hyperscaler solution architects, and regulatory compliance specialists anchored the qualitative base. Secondary validation drew from FDA guidance documents, EU AI Act implementing acts, hyperscaler capex disclosures, and academic pre-training cost analyses. Bottom-up segment sizing triangulated against top-down infrastructure spend estimates across data center corridors.
Scenario-bracketing around GPU supply constraints and energy price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, application vertical, end-user industry, and regional regulatory cluster. CAGRs derived from infrastructure capacity buildout curves and enterprise adoption pattern analysis. Industry-specific inputs encompassed training run energy consumption benchmarks and checkpoint licensing transaction values.
Practitioners should monitor export control expansion and FDA adaptive AI guidance finalization for early signals requiring forecast revision. Forecasts reflect documented assumptions on GPU supply normalization and electricity cost stabilization. Material shifts in compute-export control scope or foundation model liability rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Text-To-Speech (TTS) Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Radiology Market
Artificial Intelligence (AI)
Embedded AI Market