
 Multimodal AI Market | 2026-2036
Multimodal AI Market Size, Share, and Industry Trends Forecast 2026-2036
Multimodal AI Market Insights
The EU AI Act is restructuring the cost-of-entry calculus for multimodal AI vendors by imposing conformity assessments and risk-classification obligations on systems processing biometric, health, and judicial data. Google LLC leverages its vertically integrated tensor processing infrastructure to sustain inference cost advantages across vision-language tasks. Microsoft Corporation anchors enterprise distribution through Azure OpenAI Service, which competes with Amazon Web Services on government cloud contracts requiring FedRAMP authorization.
Multimodal AI refers to artificial intelligence systems that simultaneously process and correlate heterogeneous data types—text, image, audio, video, and sensor streams—through shared embedding spaces and cross-attention architectures, typically operating at inference latencies below 500 milliseconds for real-time applications. These systems serve industrial and commercial purposes ranging from automated quality inspection in manufacturing to clinical decision support requiring synchronized radiology reports and imaging analysis. Natural Language Processing and Image Recognition occupy the largest share of current deployment value, while Speech Recognition integrated with computer vision represents the fastest-expanding margin pool as contact centers and automotive cabin monitoring converge. Cloud-Based deployment dominates revenue today, though Edge Computing configurations are gaining traction in healthcare and retail chains where data residency and sub-100-millisecond response requirements override centralized processing economics.
The US Food and Drug Administration and the European Medicines Agency are tightening software-as-a-medical-device pathways for diagnostic multimodal systems, forcing vendors to document training data provenance and performance drift monitoring. China's National Medical Products Administration and the Cyberspace Administration of China impose parallel algorithmic registration and security assessment requirements that fragment product development roadmaps. Stakeholders must monitor divergence between Brussels' risk-based classifications and Washington's sector-specific agency mandates to avoid compliance architectures that satisfy neither jurisdiction.
Market Dynamics
Cross-attention architectures are compressing inference latency thresholds below 500 milliseconds, enabling real-time multimodal processing in surgical robotics and autonomous vehicle cabins where synchronized audio-visual reasoning determines safety outcomes.
Growth Catalysts
- FDA software-as-a-medical-device pathways:The US Food and Drug Administration's streamlined premarket review for diagnostic imaging AI is accelerating hospital procurement cycles for radiology-integrated systems.
- Automotive cabin monitoring convergence:Driver drowsiness detection combining computer vision with speech emotion recognition is mandating multimodal sensor fusion in European and Japanese vehicle platforms.
- Cloud tensor processing infrastructure:Hyperscale data centers in the United States are deploying specialized inference accelerators that reduce per-query costs for vision-language tasks.
Market Restraints
- EU AI Act conformity assessments:High-risk system classification for biometric and health data processing is imposing documentation burdens that extend vendor commercialization timelines by 12-18 months.
- Training data provenance requirements:The European Medicines Agency and FDA are mandating auditable sourcing for medical imaging datasets, constraining model development for rare disease applications.
- Edge hardware cost structures:Sub-100-millisecond response requirements in retail and healthcare are forcing capital expenditure on localized GPU clusters that undermine centralized cloud economics.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor and sensor assembly are attracting multimodal hardware vendors to establish captive edge device production.
- Contact center emotion analytics:Speech-vision fusion for customer sentiment scoring represents an underpenetrated application as banks and insurers modernize legacy interactive voice response systems.
- China's algorithmic registration framework:The Cyberspace Administration of China's security assessment requirements are creating compliance service opportunities for vendors with documented training data governance.
Industry Challenges
- Cross-modal embedding expertise scarcity:The shortage of engineers proficient in transformer architectures for heterogeneous data fusion is inflating compensation premiums and delaying product roadmaps.
- FedRAMP authorization timelines:Federal cloud procurement mandates in the United States are creating 9-14 month certification backlogs that disadvantage smaller vendors competing for defense and intelligence contracts.
- Legacy electronic health record integration:Hospital information systems built on 1990s data standards require expensive middleware development to enable real-time radiology report and imaging synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multimodal AI Market |
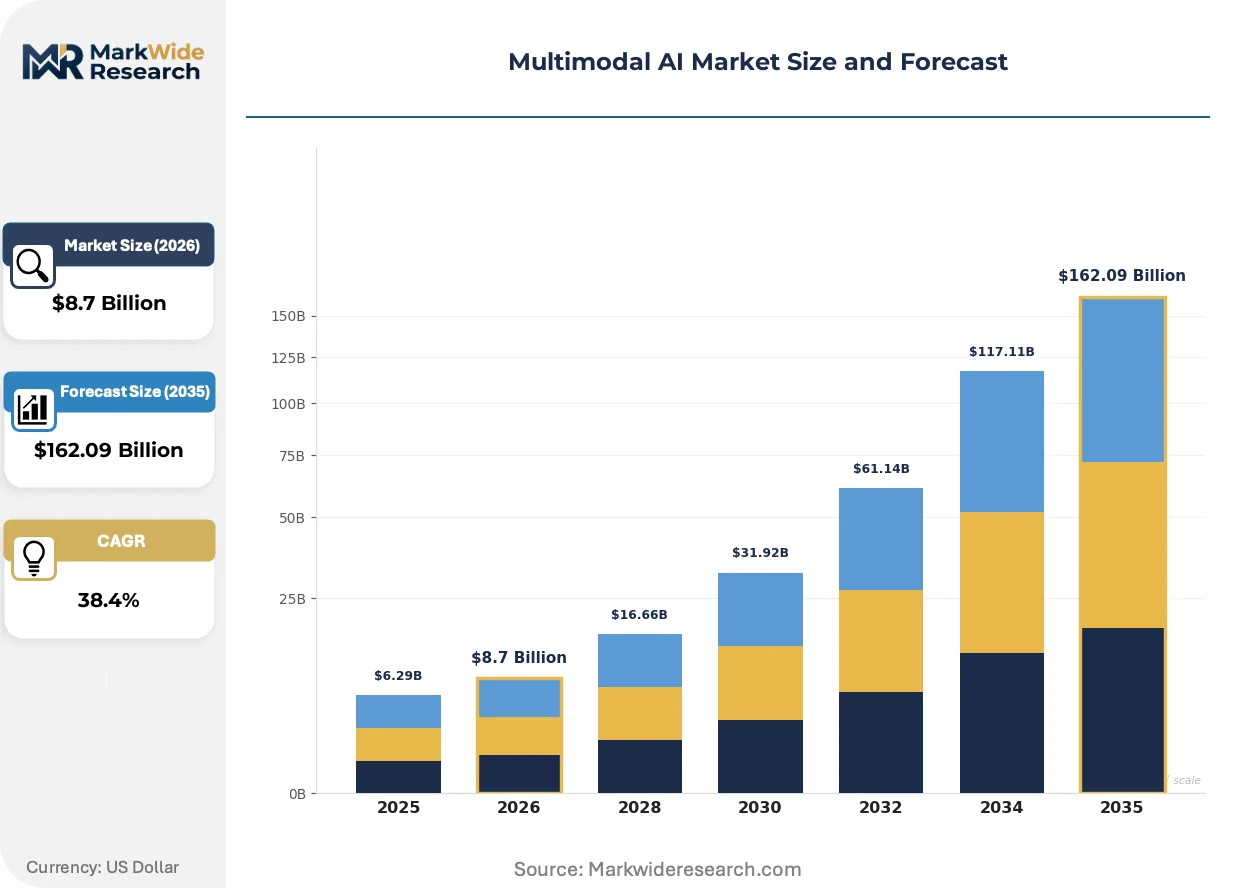
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $162.09 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Natural Language Processing, Image Recognition, Speech Recognition, Data Analytics End User: Healthcare Providers, Financial Institutions, Retail Chains, Educational Institutions Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing Technology: Machine Learning, Computer Vision, Neural Networks, Deep Learning |
| Companies Covered | Google LLC, Microsoft Corporation, OpenAI, L.L.C., Meta Platforms, Inc., Amazon Web Services, Inc., IBM Corporation, Twelve Labs Inc., NVIDIA Corporation, Uniphore Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multimodal AI Market Trends and Innovations
Foundation model architectures are collapsing previously separate AI pipelines into unified inference endpoints, reshaping how enterprises procure and deploy cognitive automation across document processing, quality inspection, and clinical workflows.
Mixture-of-experts routing for multimodal inputs is rewriting cost-performance tradeoffs in large-scale deployment. Manufacturing quality engineers at automotive and semiconductor fabs are adopting sparse activation patterns that route vision and text tokens through specialized sub-networks, reducing per-inference compute by 40-60% compared to dense architectures while maintaining accuracy on defect classification tasks.
The EU AI Act's risk-classification framework is restructuring vendor product strategies across biometric identification and health diagnostic categories. Systems processing judicial or medical data now face mandatory conformity assessments and CE marking obligations that favor established players with dedicated regulatory affairs functions, compressing market access for emerging challengers in European public sector procurement.
Hospital procurement committees are unbundling AI diagnostics from radiology equipment leases and negotiating direct SaaS contracts with algorithm vendors. This disintermediation of original equipment manufacturers is most visible in United States academic medical centers, where chief information officers are establishing separate vendor evaluation workflows for imaging AI that bypass traditional capital equipment committees and compress deployment timelines from 18 months to 90 days.
Multimodal AI Market Segmentation
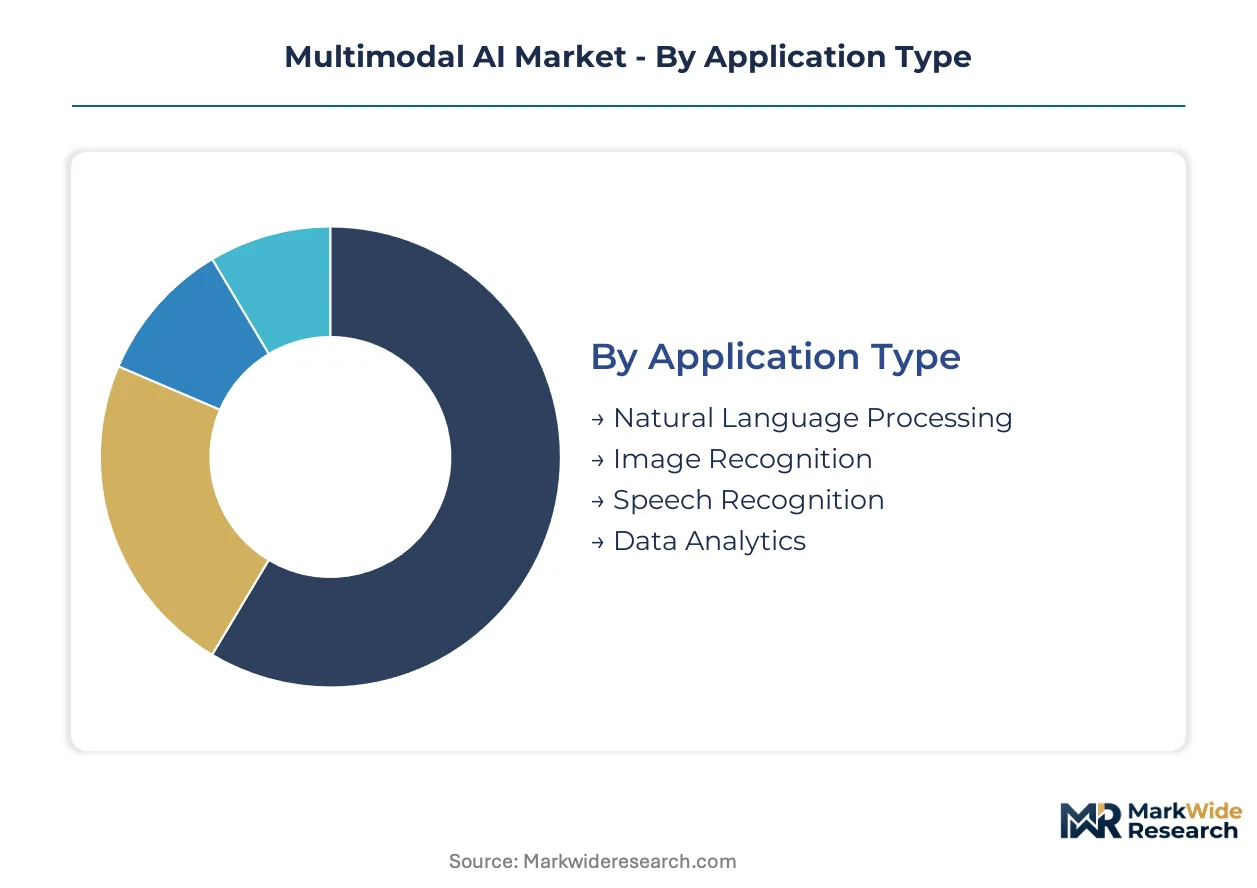
Multimodal AI architectures diverge sharply across deployment environments and data fusion requirements. Hospital procurement committees evaluate diagnostic systems against fundamentally different latency and residency constraints than retail chains assessing customer sentiment pipelines. The four segmentation dimensions below capture where standardization yields to vertical-specific engineering.
Application Type:
Standardization dominates vision-language tasks where transformer architectures transfer across domains, while health and judicial applications demand customized conformity documentation under EU AI Act risk classifications.
- Natural Language Processing:Cross-attention mechanisms fuse text embeddings with visual tokens in clinical documentation systems. Demand concentrates in United States academic medical centers where FDA software-as-a-medical-device pathways compress procurement cycles from 18 months to 90 days.
- Image Recognition:Convolutional backbones process radiology DICOM stacks alongside pathology reports through shared embedding spaces. United States hospital networks are unbundling AI diagnostics from equipment leases and negotiating direct SaaS contracts that bypass traditional capital committees.
- Speech Recognition:Automotive cabin monitoring in European and Japanese vehicle platforms mandates synchronized audio-visual emotion detection for drowsiness intervention.
- Data Analytics:Manufacturing quality engineers at semiconductor fabs adopt sparse activation patterns routing heterogeneous sensor streams through specialized sub-networks.
Most installed capacity flows through Natural Language Processing. Expansion is steepest in Speech Recognition as contact centers modernize legacy interactive voice response systems.
End User:
Procurement sophistication varies from federal cloud mandates requiring FedRAMP authorization to retail chains prioritizing sub-100-millisecond edge response over centralized economics.
- Healthcare Providers:Diagnostic imaging systems require synchronized radiology report and imaging analysis with inference below 500 milliseconds. United States academic medical centers are establishing separate vendor evaluation workflows that disintermediate original equipment manufacturers.
- Financial Institutions:Document processing pipelines for Know Your Customer compliance fuse ID imagery with textual extraction through unified inference endpoints. Cloud tensor processing infrastructure in United States hyperscale data centers reduces per-query costs for these vision-language tasks.
- Retail Chains:In-store customer tracking demands localized GPU clusters that undermine centralized cloud economics due to data residency requirements.
- Educational Institutions:Proctoring systems combine facial recognition with audio anomaly detection for remote examination integrity.
Healthcare Providers command the highest compliance premiums. Financial Institutions are expanding fastest as legacy Know Your Customer workflows collapse into multimodal automation.
Deployment Model:
Latency thresholds and data sovereignty requirements fragment deployment economics across centralized hyperscale and distributed edge configurations.
- Cloud-Based:Hyperscale inference endpoints serve vision-language tasks through specialized tensor processing accelerators. United States federal procurement directives are accelerating enterprise deployment across defense contractors requiring FedRAMP authorization.
- Edge Computing:Sub-100-millisecond response requirements in healthcare and retail force capital expenditure on localized GPU clusters. India's PLI scheme for electronics manufacturing is attracting hardware vendors to establish captive edge device production.
- On-Premise:Financial institutions in jurisdictions with strict data localization mandates maintain sovereign infrastructure for biometric processing.
- Hybrid:Manufacturing quality inspection splits model training to cloud while retaining inference at facility edge for defect classification latency.
Cloud-Based deployment hosts the majority of inference volume. Edge Computing is gaining share fastest where real-time surgical robotics and autonomous vehicle cabins demand synchronized audio-visual reasoning.
Technology:
Foundation model architectures are collapsing previously separate pipelines, though regulatory documentation requirements favor established players with dedicated conformity assessment functions.
- Machine Learning:Classical ensemble methods persist in financial risk scoring where model interpretability requirements override neural network performance.
- Computer Vision:Vision transformers process manufacturing defect imagery alongside textual work order descriptions through cross-modal attention layers.
- Neural Networks:Dense architectures face displacement by mixture-of-experts routing that reduces per-inference compute by 40-60% on multimodal classification tasks.
- Deep Learning:End-to-end training of unified encoders for text, image, and audio requires auditable training data provenance under FDA and EMA mandates.
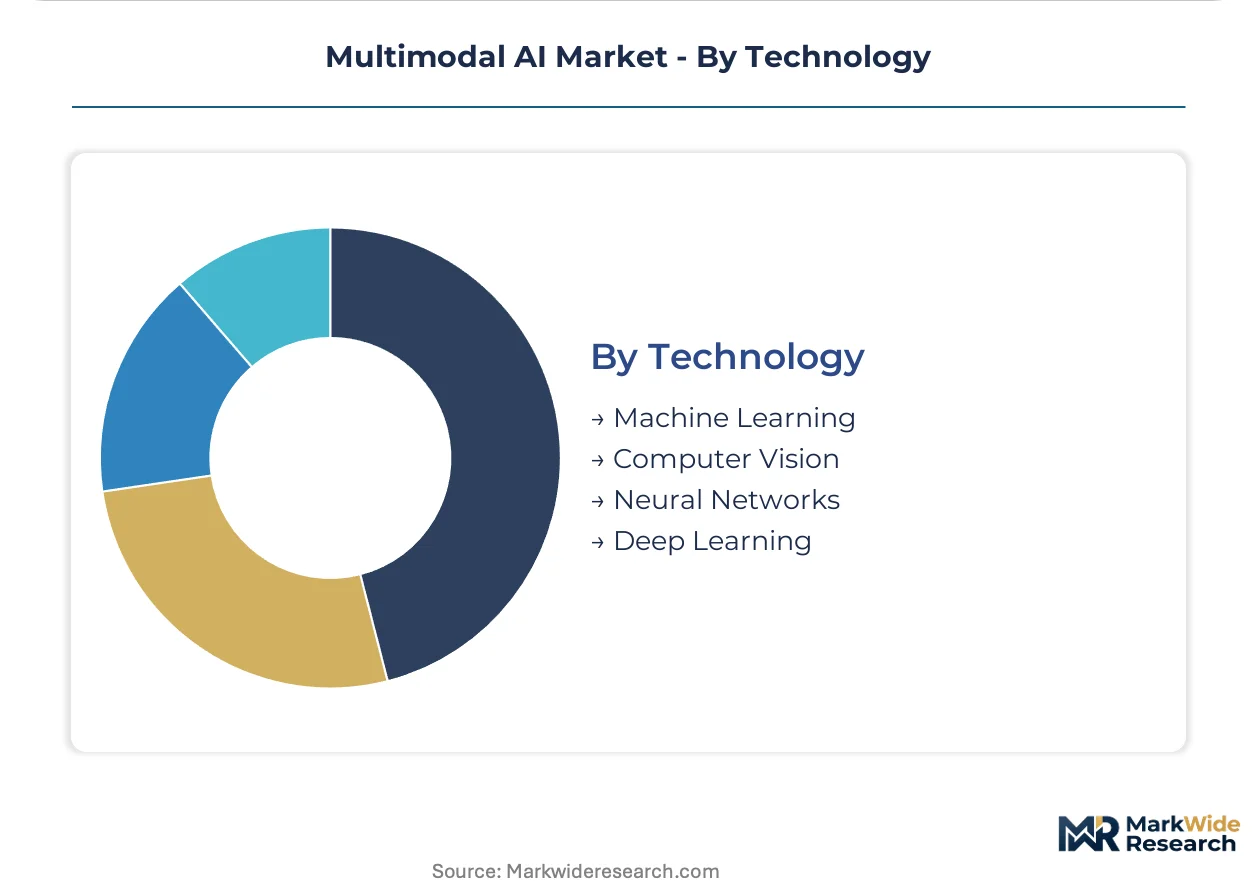
Deep Learning absorbs the largest research investment. Computer Vision is climbing fastest as automotive and medical imaging applications converge on shared transformer backbones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep learning talent pools in the San Francisco Bay Area, Beijing, and Bangalore anchor multimodal AI development. National AI procurement directives and divergent regulatory frameworks are fragmenting deployment strategies across jurisdictions.
United States
Federal cloud procurement mandates and FedRAMP authorization requirements are accelerating enterprise deployment across defense contractors and financial institutions. The FDA's software-as-a-medical-device pathways compress hospital procurement cycles for diagnostic imaging systems. Academic medical centers in Boston and the San Francisco Bay Area are establishing separate vendor evaluation workflows that disintermediate original equipment manufacturers.
China
Algorithmic registration requirements under the Cyberspace Administration of China and dual carbon goals are restructuring vendor compliance investments. The National Medical Products Administration imposes parallel security assessment mandates that fragment product development roadmaps. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta are adopting sparse activation patterns for quality inspection pipelines.
Germany
Automotive cabin monitoring convergence mandates from KBA are driving multimodal sensor fusion investments across vehicle platforms. The EU AI Act's high-risk system classification imposes conformity assessment obligations on biometric and health data processing. Industrial automation hubs in Bavaria and Baden-Württemberg are deploying vision-language systems for defect classification.
India
Production-linked incentives for semiconductor and sensor assembly under the PLI scheme are attracting hardware vendors to establish captive edge device production. The country's national IT regulator imposes data localization requirements that favor sovereign cloud infrastructure. Technology corridors in Karnataka and Telangana are concentrating engineering talent for transformer architecture development.
United Kingdom
Financial services modernization programs are collapsing legacy Know Your Customer workflows into multimodal automation pipelines. GDPR and emerging AI governance frameworks impose documentation burdens on biometric processing systems. London's fintech cluster is pioneering document processing pipelines that fuse ID imagery with textual extraction.
Multimodal AI Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across cloud infrastructure, foundation model development, and vertical application layers. Hyperscale technology groups anchor the infrastructure tier through vertically integrated tensor processing and distribution networks. Mid-tier specialists concentrate on regulatory compliance services and edge hardware optimization. Dominant competitive moves include strategic partnerships with hospital procurement committees and capacity expansion in India under electronics manufacturing incentives.
Within the hyperscale infrastructure tier, Google LLC and Microsoft Corporation exemplify vertically integrated players with dedicated regulatory affairs functions. NVIDIA Corporation anchors the specialized hardware vector through inference accelerator deployment. These entities represent divergent strategic postures: cloud-native service expansion versus silicon-software co-design optimization.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| OpenAI, L.L.C. |
| Meta Platforms, Inc. |
| Amazon Web Services, Inc. |
| IBM Corporation |
| Twelve Labs Inc. |
| NVIDIA Corporation |
| Uniphore Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
United States academic medical centers and defense contractors anchor demand concentration for multimodal AI, shaping a subscription-based SaaS pricing model that stratifies across FedRAMP-authorized premium tiers, standard enterprise licenses, and economy-grade API access for emerging developers. Procurement committees at these hyperscale buyers negotiate multi-year contracts with volume-based scaling, compressing margins for vendors lacking dedicated regulatory affairs infrastructure.
Pricing Analysis
Bundled hardware-software packages from original equipment manufacturers are losing ground to unbundled SaaS diagnostics contracts that hospital CIOs negotiate directly with algorithm vendors. Price differentiation hinges on FDA software-as-a-medical-device certification tier and FedRAMP authorization status, with authorized vendors commanding substantial premiums over uncertified competitors. Pricing pressure stems from India's PLI scheme attracting captive edge device production that undercuts hyperscale cloud inference economics. Financial institutions show least price sensitivity due to compliance-driven procurement mandates, while retail chains and educational institutions exhibit highest sensitivity as they weigh localized GPU cluster capital expenditure against centralized cloud subscriptions.
Supply Chain Analysis
Direct-to-enterprise channels serve hyperscale buyers including defense contractors and academic medical centers, while cloud marketplaces distribute to mid-tier financial institutions and retail chains. Geographic supply concentration centers on Taiwan for advanced GPU foundry capacity, South Korea for high-bandwidth memory, and the United States for specialized tensor processing accelerator design. The chain rests on rare earth element feedstock from China, photolithography equipment from the Netherlands, and advanced packaging substrates from Japan. Single-source vulnerability in EUV lithography systems creates chokepoint exposure. Distribution runs through hyperscale cloud providers' integrated marketplaces, direct enterprise sales forces, and emerging channel partners for edge hardware deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multimodal AI has entered a late-cycle quality phase where procurement committees prioritize FDA-authorized and FedRAMP-certified systems over uncertified alternatives, shifting demand toward premium-tier offerings with documented training data provenance and conformity assessment documentation.
For Market Incumbents: Lock in regulatory moats by accelerating FDA software-as-a-medical-device submissions and FedRAMP authorization timelines before compliance backlogs extend further. Incumbents should deepen backward integration into specialized inference accelerator supply through partnerships with Taiwan foundries, defending against emerging challengers lacking dedicated regulatory affairs functions. Channel control through direct hospital procurement committee relationships represents the critical lever for margin defense. For New Entrants and Emerging Players: Sparse mixture-of-experts architectures offer a technology-first wedge for cost-disruptive entry into manufacturing quality inspection and contact center emotion analytics. The most penetrable white-space sits in India's PLI scheme beneficiary ecosystem for captive edge device production, where domestic data localization requirements favor sovereign infrastructure vendors. A go-to-market angle anchored to documented training data governance for China's algorithmic registration framework unlocks compliance service revenue streams. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, targeting specialist firms with vertical regulatory expertise and edge hardware optimization capabilities. Long-term viability over the next decade hinges on sustained differentiation in conformity assessment documentation and cross-modal embedding engineering talent retention. The signal to watch is divergence between Brussels' risk-based classifications and Washington's sector-specific agency mandates, which would force expensive dual-compliance architectures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Compresses hospital procurement cycles from 18 months to 90 days for radiology-integrated systems. |
| FedRAMP Authorization Pathway | Unlocks federal cloud contracts with defense contractors and intelligence agencies requiring sovereign infrastructure. |
| Strategic Partnership with Hospital Procurement Committees | Disintermediates original equipment manufacturers from diagnostic imaging AI contracts. |
| Acquisition of Regulatory Compliance Specialist | Accelerates EU AI Act conformity assessment documentation for high-risk biometric and health data processing. |
| Geographic Expansion under India's PLI Scheme | Establishes captive edge device production for sub-100-millisecond response requirements in retail and healthcare. |
Research Methodology
Multiple input streams — primary interviews with AI platform engineers, hospital CIOs, and regulatory affairs leads; secondary validation through FDA 510(k) filings, EMA software-as-a-medical-device guidance documents, and hyperscaler capex disclosures; plus customs data on GPU and accelerator trade flows — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement committee decision criteria at United States academic medical centers and defense contractor technology offices. Secondary sources included EU AI Act implementation guidance, China's algorithmic registration framework publications, and India PLI scheme beneficiary disclosures.
Data-stream reconciliation across deployment model, application type, end-user vertical, and regional regulatory cluster informed the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed cloud versus edge versus on-premise infrastructure, natural language processing versus image recognition versus speech recognition applications, and healthcare provider versus financial institution versus retail chain end-user categories. CAGRs were derived from installed base expansion rates and average revenue per user trajectories, with cross-modal embedding expertise scarcity and FedRAMP authorization timeline backlogs serving as key forecast inputs.
The model holds under stable regulatory enforcement intensity and sustained hyperscale cloud infrastructure investment; deviation in EU AI Act conformity assessment timeline extensions or export control tightening on advanced accelerators would shift trajectory. Forecasts reflect documented base assumptions regarding hospital procurement cycle compression and automotive cabin monitoring mandate adoption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Automotive Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Artificial Neural Network Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Global Call Center AI Market
Artificial Intelligence (AI)
Global Computer Assisted Coding Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Global Conversational AI Platform Software Market
Artificial Intelligence (AI)
Smart Virtual Personal Assistants Market
Artificial Intelligence (AI)
AI Virtual Assistants Market