
 Chemical Detection Equipment Market | 2026-2036
Chemical Detection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Detection Equipment Market Analysis
Aftermarket service revenue is narrowing as original equipment manufacturers bundle predictive maintenance into platform licensing agreements. Thermo Fisher Scientific leverages its diagnostic installed base to extend recurring revenue streams. Smiths Detection anchors its position through airport and border security channel control. Bruker differentiates by specializing in high-resolution mass spectrometry for research laboratories.
Chemical detection equipment comprises instruments that identify and quantify hazardous substances through spectroscopic, electrochemical, or chromatographic methods, typically achieving detection thresholds in parts per billion for toxic industrial chemicals and chemical warfare agents. These systems serve critical functions in protecting personnel, ensuring regulatory compliance, and enabling environmental surveillance across industrial and security applications. Gas detectors occupy the largest product category as petrochemical facilities mandate fixed-point monitoring networks. Mass spectrometry commands premium pricing in military applications where false-positive tolerance approaches zero. Multi-gas monitors represent the fastest-expanding segment as mining and confined-space operations adopt wearable form factors.
EPA workplace exposure limits and OSHA permissible exposure standards dictate sensor calibration frequencies and detection threshold requirements across United States industrial facilities. The Department of Homeland Security's SAFETY Act certification shapes procurement eligibility for counter-terrorism detection deployments. European REACH compliance and CE marking requirements under the EU AI Act increasingly govern connected sensor data governance. Stakeholders must monitor convergence between chemical detection algorithms and artificial intelligence regulatory frameworks to anticipate product certification roadmaps.
Market Dynamics
Portable detection platforms are compressing replacement cycles across industrial and defense procurement channels as EPA and OSHA tighten permissible exposure standards for toxic industrial chemicals.
Growth Catalysts
- EPA workplace exposure limits:Tightening permissible exposure standards for benzene, formaldehyde, and hydrogen sulfide are forcing petrochemical facilities to upgrade fixed-point monitoring networks with higher-sensitivity sensors.
- SAFETY Act certification:The Department of Homeland Security's counter-terrorism procurement framework is expanding eligibility requirements for chemical warfare agent detection systems deployed at critical infrastructure sites.
- Wearable multi-gas monitors:Mining operations and confined-space construction sites are adopting palm-sized electrochemical sensors with real-time cloud connectivity to replace handheld spot-check devices.
Market Restraints
- Sensor calibration costs:Electrochemical and photoionization detectors require 90-day recalibration cycles under OSHA standards, creating recurring operational burdens that slow adoption among small and mid-sized industrial facilities.
- High-purity rare earth supply:Neodymium and dysprosium concentrates for infrared source components face sourcing concentration from Chinese processing facilities, exposing detector manufacturers to input volatility.
- Mass spectrometry complexity:Field-deployable high-resolution systems require vacuum pumps and precision ion optics that limit battery life and increase unit weight, constraining portable military applications.
Strategic Opportunities
- India industrial safety mandate:The country's national factory inspectorate is expanding compulsory gas monitoring to small-scale chemical processing units currently exempt from continuous detection requirements.
- EU AI Act convergence:Connected sensor networks with embedded machine learning for false-positive suppression must achieve CE marking under emerging algorithmic governance frameworks, creating first-mover certification advantages.
- Drone-mounted detection:Unmanned aerial platforms carrying lightweight infrared spectrometers are opening perimeter monitoring contracts at pipeline corridors and petrochemical storage terminals previously served by fixed towers.
Industry Challenges
- Spectroscopy talent scarcity:Universities are producing insufficient graduates with combined expertise in analytical chemistry and firmware engineering to support product development pipelines.
- Legacy system integration:SCADA networks in mature chemical plants operate on proprietary protocols that resist seamless incorporation of IP-enabled smart sensors without expensive gateway infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Detection Equipment Market |
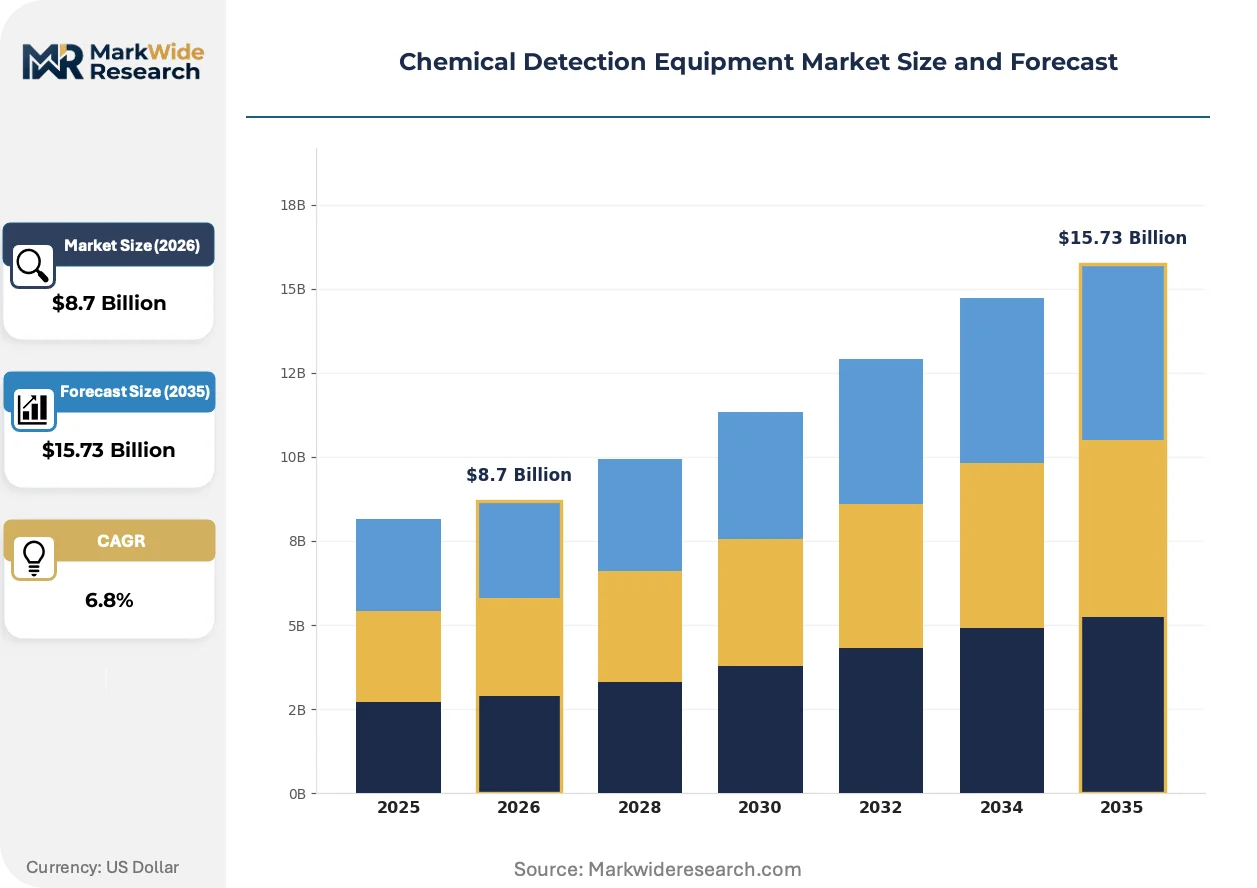
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Detectors, Liquid Analyzers, Multi-Gas Monitors, Chemical Sensors Technology: Infrared Spectroscopy, Colorimetric Methods, Mass Spectrometry, Electrochemical Sensors End User: Manufacturing Plants, Environmental Agencies, Laboratories, Military Application: Hazardous Material Management, Ambient Air Monitoring, Industrial Safety, Research and Development |
| Companies Covered | Thermo Fisher Scientific Inc., Smiths Detection Group Ltd., Bruker Corporation, Agilent Technologies, Inc., Honeywell International Inc., FLIR Systems, Inc., MSA Safety, Drägerwerk AG & Co. KGaA, PerkinElmer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Detection Equipment Market Emerging Trajectories
Artificial intelligence is embedding directly into sensor firmware to reduce false-positive rates and enable predictive maintenance without cloud dependency, reshaping hardware-software value distribution.
Photoacoustic spectroscopy is digitizing detection workflows by replacing extractive sampling with non-contact laser absorption measurement. Semiconductor fabrication facilities are adopting these solid-state systems to monitor arsine and phosphine at parts-per-billion thresholds without consumable media. The technology is digitizing maintenance scheduling through embedded self-diagnostic algorithms that eliminate manual calibration verification.
REACH compliance under the EU Green Deal is mandating substance-by-substance registration for detection reagents and calibration gases, extending procurement timelines for European industrial buyers. Chemical processors must now document full supply chain provenance for reference standards used in regulatory reporting. Gas detector manufacturers serving German automotive and pharmaceutical clusters are responding by vertically integrating reagent production to control certification documentation.
Defense and homeland security agencies are consolidating vendor relationships through multi-year platform licensing agreements that bundle hardware, predictive maintenance software, and training into single procurement vehicles. This unbundles traditional after-sales service revenue streams into recurring subscription structures. The United States represents the most visible geography for this shift, with DHS and Department of Defense contracts increasingly specifying total-cost-of-ownership evaluation criteria over unit acquisition price.
Chemical Detection Equipment Market Segmentation
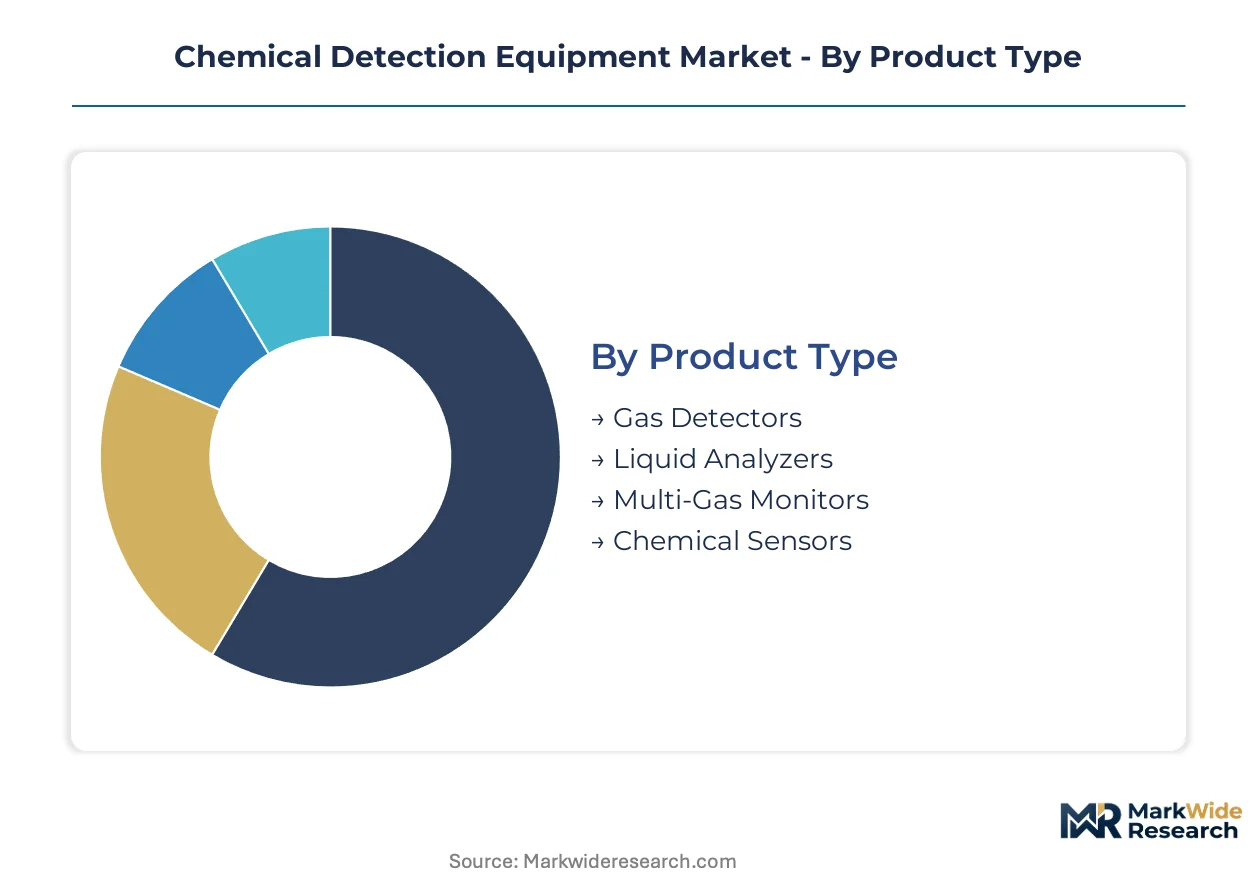
Chemical detection equipment serves divergent operational requirements across fixed industrial infrastructure, mobile field deployment, and precision laboratory environments. Segmentation reveals how replacement cycles, certification burdens, and connectivity requirements reshape procurement patterns across product categories and end-use verticals.
Product Type:
Replacement cycles vary dramatically—fixed networks operate on decade-long depreciation schedules while wearable units face 18-36 month obsolescence from battery degradation and sensor drift.
- Gas Detectors:Fixed-point and portable electrochemical or catalytic bead sensors designed for continuous ambient monitoring of combustible and toxic gases. Petrochemical facilities along the US Gulf Coast and Germany's Rhine-Ruhr chemical cluster mandate dense deployment networks for benzene and hydrogen sulfide compliance. Tightening OSHA permissible exposure limits force sensor refresh cycles faster than mechanical depreciation schedules allow.
- Multi-Gas Monitors:Palm-sized wearable devices combining electrochemical, photoionization, and infrared sensors for simultaneous multi-species detection. Mining operations in Western Australia's Pilbara region and confined-space construction crews in Saudi Arabia's NEOM development are standardizing on cloud-connected units that stream real-time exposure data to safety operations centers.
- Liquid Analyzers:Chromatographic and spectroscopic systems for process stream and wastewater monitoring. Pharmaceutical manufacturers in Switzerland and Singapore deploy these for active pharmaceutical ingredient containment verification.
- Chemical Sensors:Discrete sensing elements—metal oxide semiconductors, polymer composites, optical fibers—sold as components for OEM integration into larger safety systems. Semiconductor fabrication equipment suppliers in South Korea represent concentrated demand.
Gas detectors dominate installed base. Multi-gas monitors are where expansion concentrates.
Technology:
Cost tiers separate field-deployable simplicity from laboratory-grade precision, with military specifications commanding 10-20x price multiples over industrial equivalents.
- Mass Spectrometry:High-resolution ion detection systems achieving parts-per-trillion sensitivity through magnetic sector or time-of-flight architectures. The US Department of Defense and UK Ministry of Defence specify these for chemical warfare agent identification where false-positive tolerance approaches zero. Vacuum pump requirements and precision ion optics constrain battery life and field portability.
- Infrared Spectroscopy:Non-dispersive and Fourier-transform systems exploiting molecular absorption signatures in the mid-infrared range. Pipeline operators in Canada and petrochemical storage terminals in the Netherlands are adopting drone-mounted open-path configurations for perimeter monitoring of fugitive emissions.
- Electrochemical Sensors:Amperometric cells with gas-permeable membranes generating current proportional to target species concentration. The lowest-cost technology for routine industrial safety applications, though 90-day calibration cycles under OSHA standards create recurring operational burdens.
- Colorimetric Methods:Chemical reagent tubes and badges producing visible color change upon exposure. Emergency response teams in Japan maintain these as battery-independent backup detection for earthquake and industrial disaster scenarios.
Mass spectrometry anchors premium pricing. Infrared spectroscopy is climbing the fastest on drone and open-path deployment.
End User:
Customer type determines procurement channel—defense integrators, industrial distributors, and academic supply houses operate with incompatible contract vehicles and technical support expectations.
- Manufacturing Plants:Petrochemical, pharmaceutical, and semiconductor fabrication facilities requiring continuous monitoring for process safety and regulatory compliance. German automotive suppliers face REACH-mandated documentation of detection reagent provenance.
- Military:Armed forces and homeland security agencies procuring through multi-year platform licensing agreements. The US Department of Homeland Security's SAFETY Act certification shapes eligibility for counter-terrorism deployments at critical infrastructure sites.
- Environmental Agencies:Federal and state regulators conducting ambient air quality surveillance and enforcement monitoring. The US EPA and state environmental departments operate reference-grade monitoring networks.
- Laboratories:Research institutions and analytical service providers requiring trace-level quantification for method development and forensic analysis. University chemistry departments in the UK and Netherlands drive demand for high-resolution mass spectrometry.
Manufacturing plants represent the deepest installed base. Military procurement is where subscription revenue models are displacing traditional hardware sales.
Application:
Maturity gradients separate regulated compliance mandates from discretionary research spending, with industrial safety applications showing recession-resistant demand characteristics.
- Industrial Safety:Personnel protection through continuous or periodic monitoring of toxic and combustible gas exposure. Mining operations in India and confined-space construction in the UAE are expanding wearable monitor deployment.
- Hazardous Material Management:Detection and identification of chemical warfare agents, toxic industrial chemicals, and illicit substances at borders, airports, and critical infrastructure. Smiths Detection anchors this segment through airport and border security channel control.
- Ambient Air Monitoring:Regulatory compliance and public health surveillance of outdoor and indoor air quality. The EU Green Deal is extending monitoring requirements to smaller industrial facilities previously exempt from continuous detection.
- Research and Development:Method development, forensic analysis, and fundamental spectroscopic research. Bruker differentiates by specializing in high-resolution mass spectrometry configurations for university and government laboratories.
Industrial safety dominates recurring revenue. Hazardous material management is gaining share fastest on homeland security procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detector assembly concentrates in Germany, the United States, and Japan where precision optics and vacuum component ecosystems anchor manufacturing. Procurement patterns diverge sharply between defense-driven North American demand and process-safety mandates across European chemical corridors.
United States
Defense and homeland security agencies are expanding multi-year platform licensing for portable chemical warfare agent detection systems. The Department of Homeland Security's SAFETY Act certification shapes eligibility for counter-terrorism deployments at critical infrastructure sites. Gulf Coast petrochemical clusters in Texas and Louisiana are upgrading fixed-point monitoring networks as OSHA tightens permissible exposure standards for benzene and hydrogen sulfide.
Germany
Industrial safety regulations mandate continuous gas monitoring across chemical processing facilities in the Rhine-Ruhr corridor and Bavaria. REACH compliance under the EU Green Deal requires substance-by-substance registration for detection reagents, extending procurement timelines. Automotive suppliers in Baden-Württemberg face documentation requirements for full supply chain provenance of reference standards used in regulatory reporting.
China
Semiconductor fabrication equipment suppliers are driving concentrated demand for discrete chemical sensing elements. The country's national factory inspectorate is expanding compulsory gas monitoring requirements to previously exempt small-scale chemical processing units. Yangtze River Delta manufacturing hubs are adopting wearable multi-gas monitors with real-time cloud connectivity for confined-space operations.
India
Mining operations in the country's western and eastern mineral belts are standardizing on palm-sized electrochemical sensors to replace handheld spot-check devices. The national factory inspectorate is extending compulsory gas monitoring mandates to small-scale chemical processing units. Construction crews at the Gujarat and Maharashtra industrial corridors are deploying cloud-connected units that stream real-time exposure data to safety operations centers.
United Kingdom
University chemistry departments are driving demand for high-resolution mass spectrometry configurations for forensic and research applications. The UK Ministry of Defence specifies premium detection systems for chemical warfare agent identification where false-positive tolerance approaches zero. Research institutions in the Cambridge-Oxford-London triangle are expanding analytical service capabilities for trace-level quantification.
Chemical Detection Equipment Market Vendor Landscape
Integrated conglomerates and specialized analytical instrument makers split the market into distinct capability tiers. Consolidation pressure concentrates among mid-scale players lacking captive distribution channels or diagnostic installed bases. Three archetypes dominate: diversified life science conglomerates with recurring revenue platforms, defense-focused detection specialists with homeland security channel control, and precision instrument pure-plays with university laboratory relationships. Competitive moves center on predictive maintenance software bundling and multi-year platform licensing agreements that displace traditional hardware sales.
Among diversified conglomerates, Thermo Fisher Scientific exemplifies the diagnostic-installed-base archetype extending recurring revenue streams through service integration. Smiths Detection occupies a position representing defense and security channel specialists anchoring market presence through airport and border procurement relationships. Bruker sits within the precision instrument tier specializing in high-resolution configurations for research laboratory end users. These three players illustrate how strategic positioning around customer type—industrial, security, or academic—shapes sustainable competitive differentiation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Smiths Detection Group Ltd. |
| Bruker Corporation |
| Agilent Technologies, Inc. |
| Honeywell International Inc. |
| FLIR Systems, Inc. |
| MSA Safety |
| Drägerwerk AG & Co. KGaA |
| PerkinElmer, Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in precision vacuum component manufacturing across Japan and Germany is compressing lead times for mass spectrometry subassemblies, granting incumbent suppliers pricing power while forcing detector OEMs into long-term offtake commitments to secure allocation.
Pricing Analysis
EPA and OSHA permissible exposure standards dictate the pricing tier structure across portable and fixed-point detection systems. Three-tier pricing separates SAFETY Act-certified military platforms from industrial safety equipment and economy-grade spot-check devices. Price differentiation centers on calibration frequency guarantees and predictive maintenance software bundling, with subscription-based licensing commanding premiums over transactional hardware sales. Cost compression in the economy tier is intensifying as Chinese sensor manufacturers expand electrochemical cell capacity. Small and mid-sized industrial facilities show highest price sensitivity, while defense integrators prioritize total-cost-of-ownership evaluation over unit acquisition price.
Supply Chain Analysis
Neodymium and dysprosium concentrates for infrared source components draw from Chinese rare earth processing facilities, with germanium substrates for optical elements sourced from Belgium and the United States. Electrochemical sensor membranes rely on fluoropolymer films from Japanese chemical manufacturers, while precision ion optics for mass spectrometry rest on Swiss and German machining expertise. Single-source vulnerability concentrates in rare earth separation capacity, exposing detector manufacturers to export restriction risk. Distribution runs through defense integrators for military procurement, industrial distributors for plant safety applications, and academic supply houses for research laboratory sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical detection equipment sits at an inflection point where AI-embedded firmware is displacing cloud-dependent architectures, reshaping hardware-software value capture and opening asymmetric opportunities for agile entrants.
For Market Incumbents: Harden predictive maintenance software platforms against edge-computing challengers by embedding self-diagnostic algorithms directly into sensor firmware. Secure rare earth supply through backward integration into neodymium processing or long-term offtake agreements with Australian concentrate producers. Channel control through DHS SAFETY Act certification investment remains the priority defensive lever against emerging portable detection specialists.
For New Entrants and Emerging Players: Build out drone-mounted open-path infrared capabilities for pipeline perimeter monitoring contracts at North American and Middle Eastern petrochemical storage terminals. India's small-scale chemical processing units represent the most penetrable geography as compulsory gas monitoring mandates expand. A go-to-market angle through cloud-connected wearable multi-gas monitors with real-time streaming to safety operations centers bypasses incumbent fixed-network installed bases.
For Investors and Strategic Acquirers: Capital is best deployed toward precision instrument pure-plays with university laboratory relationships and captive mass spectrometry IP, where subscription revenue models are displacing transactional hardware sales. Long-term viability across the analysis window favors players with diagnostic installed bases capable of extending recurring service streams. The signal to watch is convergence between chemical detection algorithms and EU AI Act certification timelines, which will determine first-mover positioning in connected sensor governance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Captive neodymium supply insulates infrared source production from Chinese export volatility. |
| SAFETY Act Certification Investment | DHS eligibility unlocks multi-year platform licensing at critical infrastructure deployment sites. |
| Edge AI Firmware Development | On-sensor false-positive suppression reduces cloud dependency and enables predictive maintenance. |
| Drone-Mounted Spectrometer Partnership | Open-path infrared deployment opens perimeter monitoring contracts at pipeline corridors. |
| Predictive Maintenance Platform Launch | Subscription bundling displaces traditional after-sales service revenue into recurring structures. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with plant safety managers, defense procurement officers, university laboratory directors, and aftermarket service heads; and secondary validation through EPA enforcement databases, OSHA compliance records, DHS SAFETY Act certifications, and EU REACH registration filings. Bottom-up triangulation across product category shipment data and top-down reconciliation against end-use industry capital expenditure patterns anchored volume estimates.
Forecast inputs span technology type, end-user vertical, application maturity, and regional regulatory cluster intensity across the projection horizon. CAGRs derive from segment-level replacement cycle analysis and procurement elasticity modeling. Specific forecast inputs include sensor calibration frequency mandates under evolving OSHA permissible exposure standards and SAFETY Act certification pipeline velocity for counter-terrorism deployments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by edge-AI sensor startups or rare earth supply nationalization would shift outcomes. Cross-checking against DHS procurement award databases and EU AI Act implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
Piping Hydro Testing Market
Testing Equipment
Micro Carbon Residue Tester Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market
Testing Equipment
Global Lab Automation in Analytical Chemistry Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Digital Shore Durometer Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
Process Analytical Technology Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Stack Emissions Real-Time Speciation and Compliance Test Systems Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
Membrane Osmometer Market