
 Pediatric Supplements Market | 2026-2036
Pediatric Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Supplements Market Analytics
Asset-light contract manufacturing and white-label financing is tilting competitive dynamics toward brands that outsource production while concentrating capital on marketing and formulation science. Nestlé S.A. leverages its pediatric nutrition heritage to sustain shelf dominance in pharmacies across Western Europe. Abbott Laboratories anchors its position through science-backed clinical validation and hospital channel relationships. Haleon competes on consumer health brand recognition, while Pfizer Inc. differentiates via prescription-adjacent distribution networks that physicians trust.
Pediatric supplements comprise age-appropriate micronutrient, probiotic, and essential fatty acid formulations delivered in palatable, child-safe formats designed to bridge dietary gaps during critical developmental windows. Manufacturing employs microencapsulation and taste-masking technologies to achieve stability, bioavailability, and compliance in young consumers. Vitamins and probiotics occupy the largest revenue pools due to established pediatrician recommendation patterns and parental familiarity. Gummies and liquid formats are expanding fastest as they overcome swallowing limitations in infants and toddlers, while online retail captures disproportionate growth through subscription models and direct-to-parent marketing efficiency.
The FDA exercises post-market surveillance authority over dietary supplement adverse events, while the EMA and national EU regulators enforce novel food and health claim substantiation standards that constrain label messaging. China's NMPA imposes registration requirements on imported pediatric formulations, creating a bifurcation between domestic and foreign brand access. Stakeholders must monitor evolving probiotic strain-specific approval pathways and emerging clean-label certification demands as the primary determinants of competitive defensibility and market entry feasibility.
Market Dynamics
Asset-light contract manufacturing is redistributing capital toward brand-building and direct-to-parent digital channels, compressing traditional vertically integrated supply structures while elevating formulation science as the primary competitive moat.
Growth Catalysts
- Early childhood nutrition protocols:Pediatrician associations in the United States and Germany now issue micronutrient screening guidelines that normalize supplementation for toddlers, expanding addressable demand through clinical credibility transfer.
- Microencapsulation advances:Lipid-shell stabilization technologies are extending probiotic viability in ambient storage, unlocking pharmacy distribution without cold-chain dependency and reducing spoilage rates in tropical climates.
- China's third-child policy:Demographic incentives and provincial birth subsidies in Sichuan and Guangdong are expanding the 0-6 year population base, concentrating demand for age-appropriate nutritional formats.
Market Restraints
- Fish oil input volatility:Omega-3 raw material costs fluctuate with Peruvian anchovy harvest quotas and marine ecosystem disruptions, squeezing margin on essential fatty acid formulations.
- Novel food substantiation requirements:EFSA's health claim validation process for probiotic strains demands 18-36 month clinical timelines, freezing label messaging and delaying European product launches.
- Algal DHA substitution pressure:Plant-derived omega-3 alternatives are capturing vegan-parent segments, threatening traditional marine-source positioning in premium positioning tiers.
Strategic Opportunities
- Subscription commerce infrastructure:Direct-to-parent auto-replenishment models bypass pharmacy margin extraction and capture behavioral loyalty through pediatric milestone-based dosing algorithms.
- India's FSSAI streamlining:Consolidated import licensing for dietary supplements is reducing registration timelines from 24 to 12 months, opening organized retail penetration in Mumbai and Bangalore metro clusters.
- Clean-label certification convergence:Dual pursuit of USDA Organic and Non-GMO Project verification is commanding 15-25% shelf price premiums in Whole Foods and Sprouts channels.
Industry Challenges
- Pediatric formulation toxicology expertise:Qualified safety pharmacologists capable of designing age-appropriate excipient profiles remain concentrated in Basel and Boston, constraining R&D expansion.
- Legacy ERP integration:Contract manufacturers struggle to synchronize batch-level traceability data with brand-owner demand-planning systems, delaying lot-release documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Supplements Market |
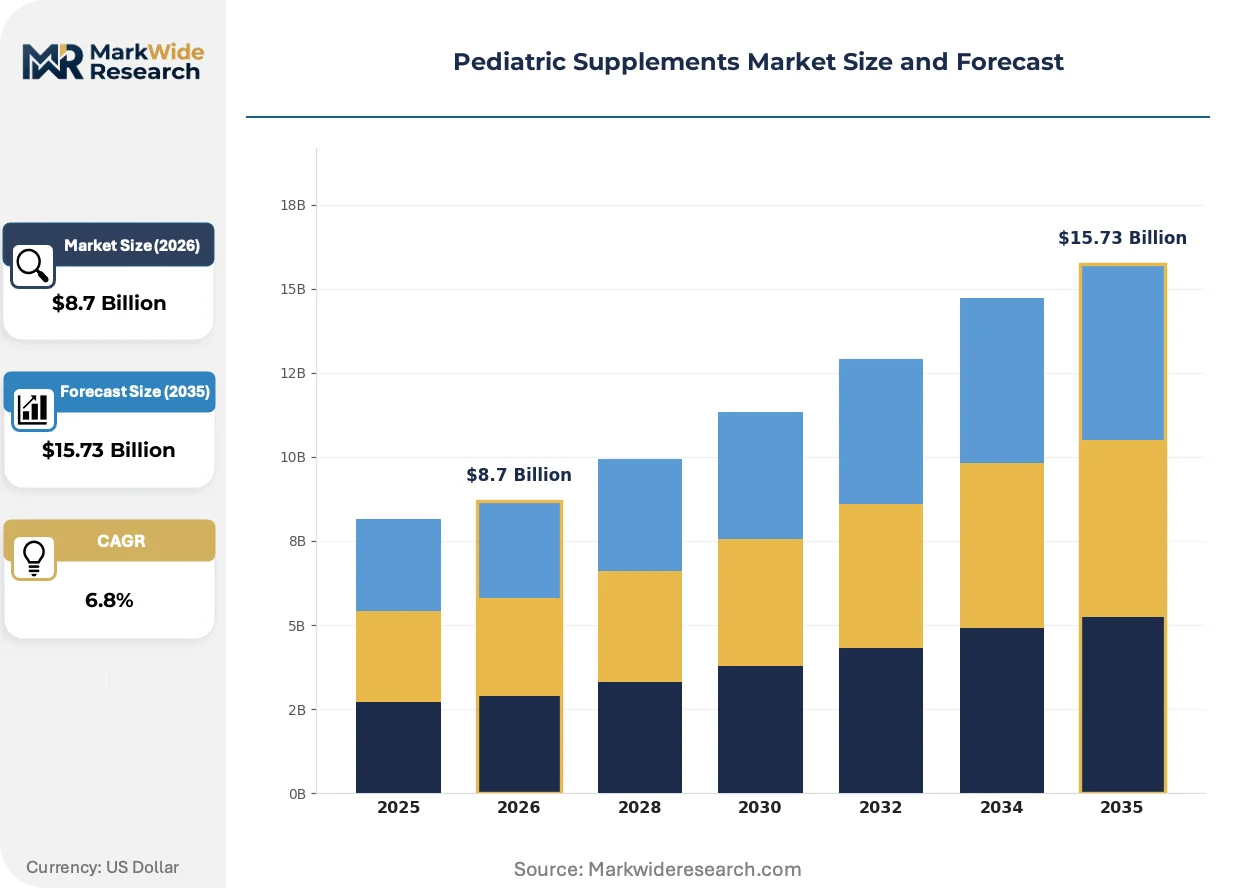
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Probiotics, Omega-3 Fatty Acids Form: Chewable Tablets, Liquid, Gummies, Powder Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores Target Age Group: Infants, Toddlers, Preschoolers, School-Aged Children |
| Companies Covered | Bayer AG, Reckitt Benckiser Group plc, Nestlé S.A., Johnson & Johnson, Danone S.A., Abbott Laboratories, Sanofi S.A., Haleon, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Supplements Market Evolving Landscape
Palatability engineering and precision dosing formats are dismantling historical compliance barriers in young children, while regulatory digitization and channel disintermediation compress go-to-market timelines.
Microencapsulation is collapsing the stability-performance tradeoff that previously forced manufacturers to choose between bioavailability and shelf life. Lipid-in-lipid shell structures now protect heat-sensitive probiotic strains through pasteurization and ambient distribution. Pharmacy chains in Germany and the United States are accelerating adoption of these stabilized formats, eliminating cold-chain capital requirements that previously excluded smaller retail accounts.
REACH-aligned substance restrictions are tightening excipient approval pathways for colorants and flavoring agents used in children's products. ECHA's candidate list expansions for endocrine-disrupting compounds are forcing reformulation of legacy gummy bases and coating systems. European manufacturers are responding by accelerating natural colorant sourcing from spirulina and beetroot concentrates, though these substitutions complicate taste-masking protocols.
Subscription-based replenishment is consolidating purchase decisions into algorithm-driven dosing schedules tied to developmental milestones. Direct-to-parent platforms disassemble the pharmacy intermediary, capturing recurring revenue and first-party consumption data. This behavioral shift concentrates in United States coastal metro areas where digital-native millennial parents dominate household purchasing authority.
Pediatric Supplements Market Segmentation
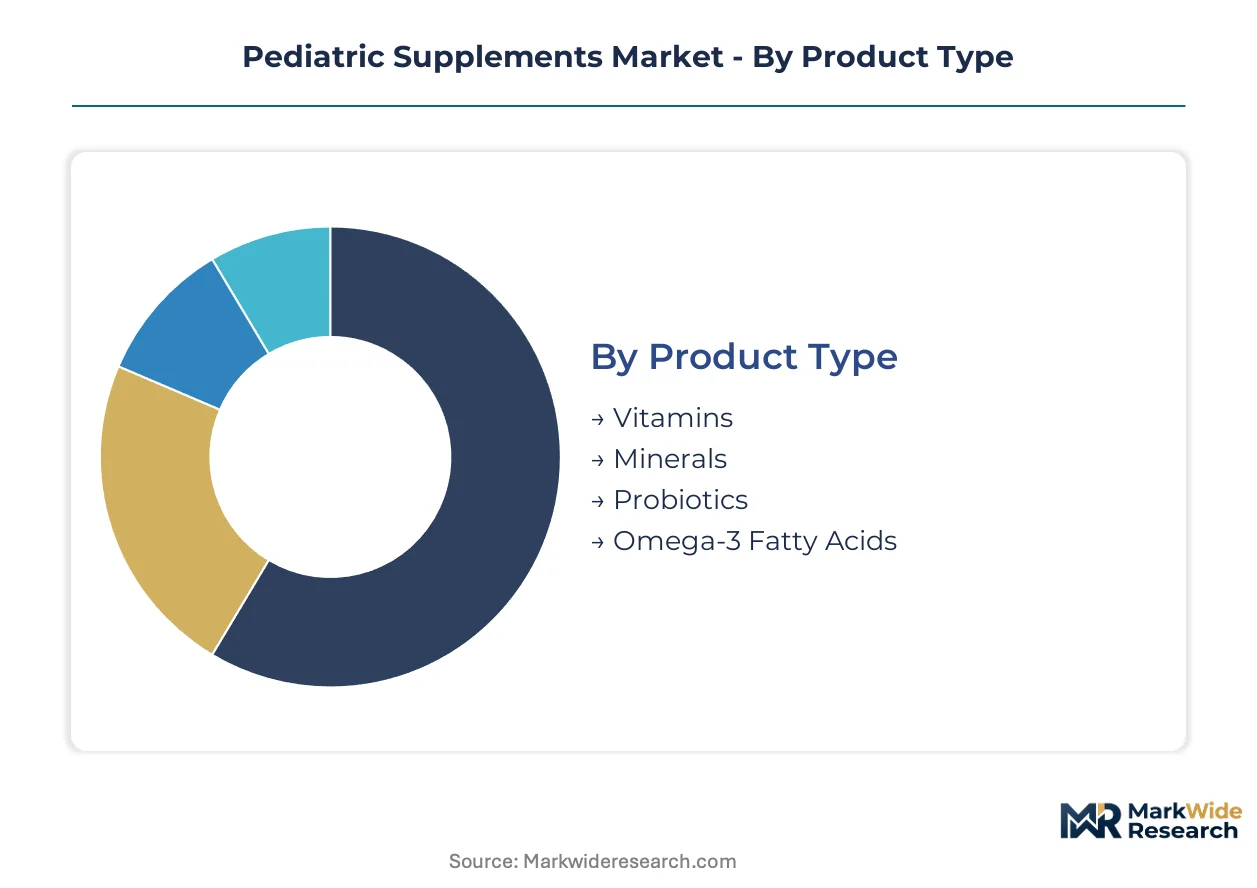
Pediatric supplement segmentation reflects distinct physiological needs across developmental stages and varying parental compliance preferences. Formulation science and channel access determine competitive positioning within each category.
Product Type:
The use-case spectrum spans from foundational micronutrient correction to targeted microbiome and neurodevelopmental support.
- Vitamins:Multivitamin complexes address documented deficiencies in vitamins D, A, and B-complex during rapid growth phases. Demand clusters in United States urban centers where pediatrician screening protocols normalize routine supplementation for toddlers.
- Probiotics:Live microbial strains delivered in microencapsulated formats support gut-immune axis development in early childhood. Adoption accelerates in Germany and China as parents seek alternatives to antibiotic-associated dysbiosis.
- Minerals:Iron, zinc, and calcium formulations target specific deficiency patterns prevalent in developing economies.
- Omega-3 Fatty Acids:DHA and EPA concentrates support neurocognitive and visual development during critical brain growth windows.
Established volume favors vitamins; emerging adoption favors probiotics.
Form:
Palatability engineering and swallowing capability constraints segment the market across age-appropriate delivery mechanisms.
- Gummies:Gelatin or pectin-based matrices incorporate taste-masking technologies to deliver micronutrients in candy-like formats. Preschooler compliance rates in United States households drive pharmacy shelf expansion and premium positioning.
- Liquid:Suspension and emulsion formats enable precise dosing titration for infants and toddlers with immature swallowing reflexes. Concentrated demand in neonatal care settings and direct-to-parent subscription channels.
- Chewable Tablets:Compressed formats suit school-aged children with developed mastication capability.
- Powder:Sachet and canister formats permit flexible dosing and beverage integration for selective eaters.
Functional necessity anchors liquid formats; discretionary preference elevates gummies.
Distribution Channel:
Channel selection reflects trust hierarchies, purchase urgency, and replenishment convenience patterns among parent demographics.
- Pharmacies:Brick-and-mortar drugstore chains and independent dispensaries leverage pharmacist counsel and prescription adjacency to capture first-time purchases. Dominant in Germany where Apotheken maintain pediatric nutrition category authority.
- Online Retail:Direct-to-parent platforms and marketplace aggregators deploy subscription algorithms tied to developmental milestones. Steepest expansion trajectory in United States coastal metros where digital-native millennial parents concentrate purchasing authority.
- Supermarkets:Mass merchandisers capture impulse and routine replenishment through proximity shopping.
- Specialty Stores:Natural products retailers command clean-label premiums through curated certification displays.
Trust-dependent initial purchases favor pharmacies; recurring convenience favors online retail.
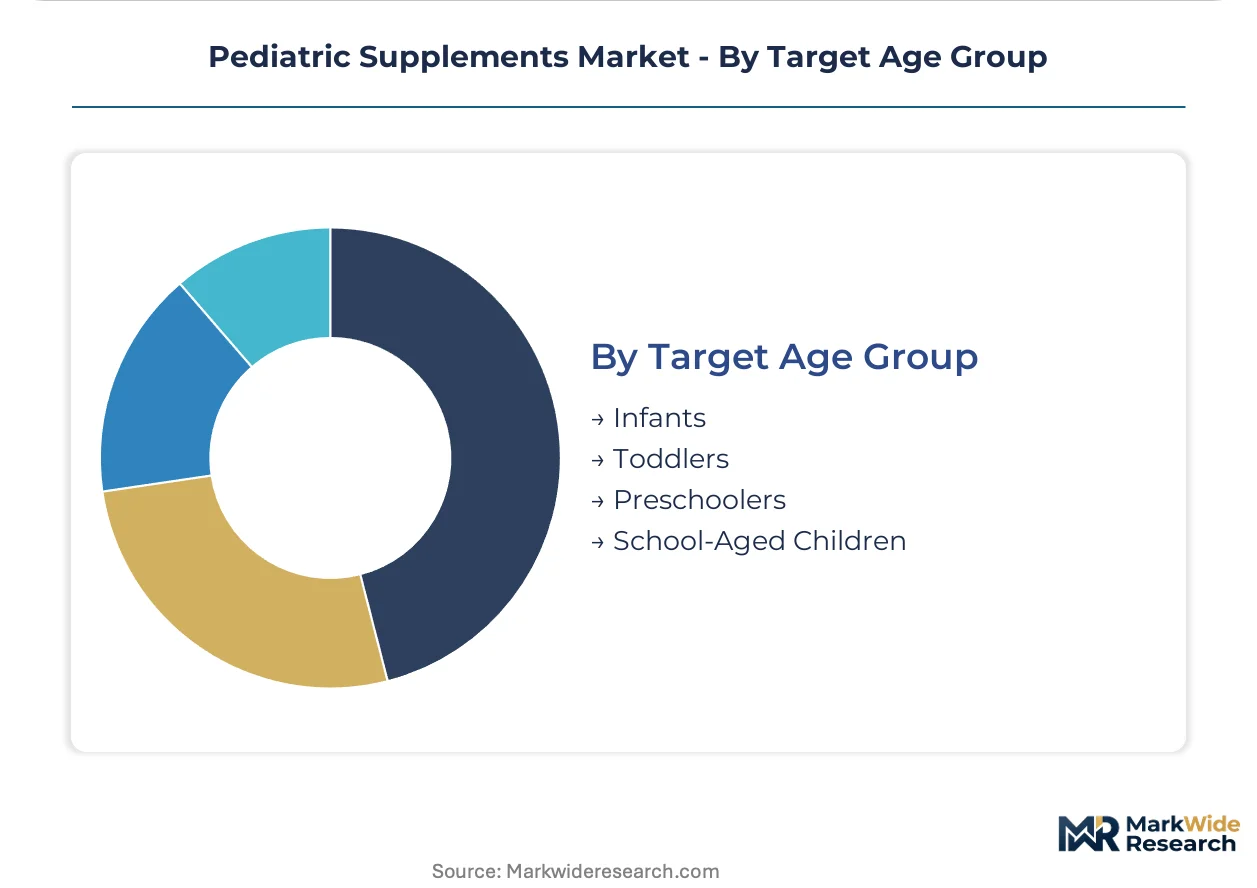
Target Age Group:
Physiological development stages dictate formulation specifications, dosing precision requirements, and parental decision-making involvement.
- Toddlers:Children aged 1-3 years require transition nutrition bridging breast milk or formula dependence to solid food diversity. Fastest-expanding buyer segment as awareness of early childhood nutrition protocols rises among first-time parents in China and the United States.
- Infants:Neonates and children under 12 months face the strictest formulation safety requirements and liquid-only delivery constraints.
- Preschoolers:Children aged 3-5 years develop autonomous food preferences, elevating palatability engineering importance.
- School-Aged Children:Academic performance and sports participation drive demand for cognitive and energy metabolism support.
Regulatory stringency defines infants; volume expansion defines toddlers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
First-time parents in coastal United States metros and China's tier-1 cities drive disproportionate category spending, while organized retail penetration and pediatrician network density determine market access trajectories across national boundaries.
United States
Millennial parents in New York and Los Angeles metro areas normalize routine supplementation through pediatrician screening protocols. FDA post-market surveillance authority shapes adverse event reporting requirements for dietary supplements. Subscription commerce clusters in Seattle and San Francisco bypass traditional pharmacy intermediaries.
Germany
Apotheken channel authority and parental trust in pharmacist counsel sustain pharmacy-dominant purchasing patterns. EFSA health claim substantiation standards constrain probiotic strain labeling and messaging flexibility. Industrial formulation expertise concentrates in Basel and Frankfurt Rhine-Main clusters.
China
Third-child policy incentives in Sichuan and Guangdong expand the addressable 0-6 year population base. NMPA registration requirements for imported pediatric formulations bifurcate domestic and foreign brand market access. E-commerce penetration in Shanghai and Beijing accelerates direct-to-parent distribution models.
India
Rising organized retail penetration in Mumbai and Bangalore metro clusters expands modern trade access for branded formulations. FSSAI consolidated import licensing reduces registration timelines and accelerates foreign brand entry. Pediatric micronutrient deficiency awareness campaigns drive government program integration.
Japan
PMDA oversight of functional food and supplement claims maintains stringent safety pharmacology standards for pediatric formats. METI industrial policy supports domestic fermentation technology leadership in probiotic strain development. Tokyo-Osaka corridor concentration of pharmaceutical R&D infrastructure enables formulation innovation.
Pediatric Supplements Market Competitive Landscape
Channel-controlling players compete with product-specialist players across pharmacy, hospital, and direct-to-parent digital channels. Market structure tilts toward consolidated multinational presence in developed economies with fragmented regional specialists in emerging markets. Pharmaceutical heritage players and consumer health spin-offs represent distinct strategic archetypes. Dominant competitive moves include portfolio diversification into adjacent pediatric nutrition formats and geographic licensing partnerships to bypass regulatory registration barriers.
Among pharmaceutical-origin multinationals, Bayer AG and Abbott Laboratories exemplify the clinical validation archetype, while Nestlé S.A. occupies a position representing consumer nutrition heritage players. Haleon sits within the consumer health spin-off category following its separation from pharmaceutical parent structures. These three anchors demonstrate how regulatory relationship depth and channel access credentials stratify competitive positioning beyond formulation capabilities alone.
| Leading Market Players |
|---|
| Bayer AG |
| Reckitt Benckiser Group plc |
| Nestlé S.A. |
| Johnson & Johnson |
| Danone S.A. |
| Abbott Laboratories |
| Sanofi S.A. |
| Haleon |
| Pfizer Inc. |
| Others |
Value Network & Pricing Analysis
Basel and Frankfurt Rhine-Main formulation clusters concentrate microencapsulation expertise and pediatric toxicology capability, concentrating upstream supply power among contract manufacturers with cold-chain-free stabilization patents. This geographic concentration of formulation science enables premium pricing for ambient-stable probiotic formats while squeezing margin on commodity vitamin blends.
Pricing Analysis
Cost-plus contracts with omega-3 indexation dominate raw material procurement, tying formulation costs to Peruvian anchovy harvest volatility. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified products from conventional pharmacy-tier offerings from mass-market supermarket lines. Price differentiation hinges on certification grade and pediatrician endorsement density. Cost compression in essential fatty acid formulations is intensifying because algal DHA substitution threatens marine-source positioning. Mass-market supermarket buyers exhibit highest price sensitivity; pharmacy-first parents accept premium positioning for clinical credibility.
Supply Chain Analysis
Extended payment terms from German pharmacy chains and supply-chain finance facilities from Swiss ingredient traders are restructuring working capital flows across the value chain. Raw material supply concentrates in Peru for marine omega-3, China for probiotic fermentation substrates, and India for vitamin premix synthesis. Manufacturing draws from algal DHA, microencapsulated lipid shells, and natural colorant substitutes. Single-source vulnerability in Peruvian anchovy quotas threatens essential fatty acid formulation continuity. Distribution runs through pharmacy chains in Germany, direct-to-parent platforms in the United States, and e-commerce aggregators in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric supplements are recovering from pandemic-era birth rate compression as China's third-child policy and German micronutrient screening protocols expand addressable demand. This cyclical recovery in birth cohorts and clinical normalization of supplementation is rebuilding volume trajectories.
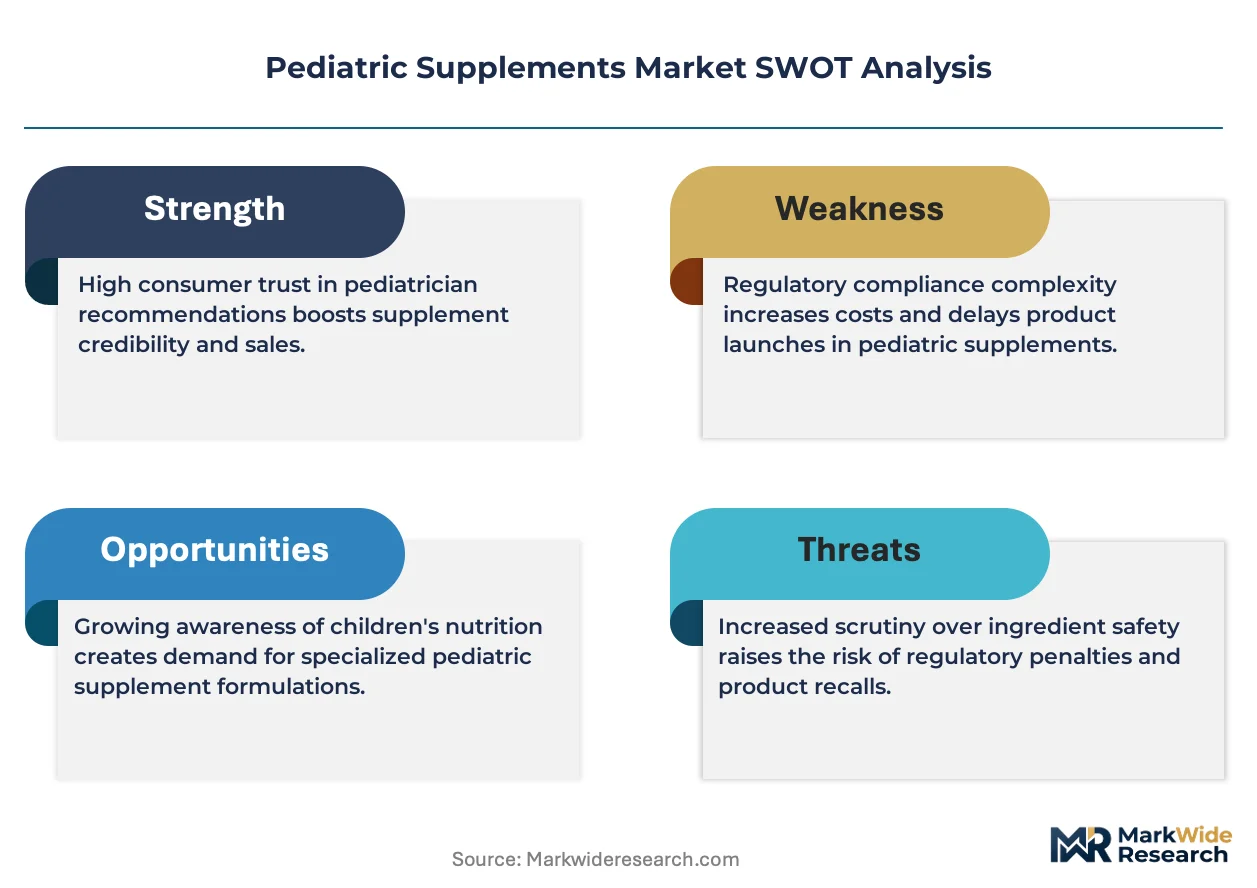
For Market Incumbents: Build clinical validation moats through pediatrician screening guideline sponsorship and hospital formulary placement. Nestlé S.A. and Abbott Laboratories should deepen probiotic strain-specific clinical trial investment to preempt EFSA health claim substantiation delays. Algal DHA substitution pressure demands backward integration into fermentation-derived omega-3 to defend marine-source margin tiers.
For New Entrants and Emerging Players: Build out direct-to-parent subscription infrastructure in United States coastal metros where millennial parents concentrate purchasing authority. India's FSSAI streamlining creates the most penetrable geography for foreign brand entry with reduced registration timelines. Clean-label certification convergence offers a go-to-market angle through Whole Foods and Sprouts channel placement commanding shelf price premiums.
For Investors and Strategic Acquirers: Long-term, this sits as a demographic-essential play because early childhood nutrition protocols are hardening into clinical standard-of-care across developed economies. Acquisition targets should concentrate on contract manufacturers with microencapsulation patents and ambient-stability expertise. The signal to watch is EFSA probiotic strain approval velocity as an inflection indicator for European market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Pediatrician guideline sponsorship transfers credibility and anchors pharmacy shelf placement. |
| Microencapsulation Patent Acquisition | Ambient-stable probiotic formats eliminate cold-chain capital requirements for retail expansion. |
| Direct-to-Consumer Platform Launch | Subscription algorithms tied to developmental milestones capture behavioral loyalty and first-party data. |
| Clean-Label Certification Stack | USDA Organic and Non-GMO Project verification commands shelf price premiums in natural retail. |
| Algal DHA Backward Integration | Fermentation-derived omega-3 secures supply against Peruvian anchovy quota volatility. |
Research Methodology
Initial hypotheses were tested against primary input from pediatric nutrition brand managers, contract manufacturing operations directors, pharmacy category buyers, and regulatory affairs specialists and refined through secondary validation. Primary interviews with formulation scientists and hospital procurement committees in Basel, Boston, and Shanghai anchored supply-side and demand-side perspectives. Secondary sources included FDA adverse event reporting databases, EFSA health claim opinions, NMPA registration filings, and Nielsen retail audit data. Bottom-up segment sizing and top-down macroeconomic triangulation converged on volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling pediatric population cohorts, pediatrician screening protocol adoption curves, and channel shift trajectories. Segmentation dimensions spanned product type, delivery form, distribution channel, and target age group with regional regulatory cluster overlays. CAGRs were derived from cohort-component population projections and per-capita supplementation penetration curves. Forecast inputs included China's birth incentive policy implementation velocity and EFSA probiotic strain approval timelines.
Stress conditions across birth rate volatility, omega-3 input cost spikes, and regulatory approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clinical guideline adoption and channel migration rates. Macroeconomic contraction, novel food substantiation requirement tightening, or technological disruption in delivery formats would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Melatonin Sleep Supplements Market
Dietary Supplements
Pet Herbal Supplements Market