
 Herbal Supplements Market | 2026-2036
Herbal Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Supplements Market Intelligence
Subscription-based replenishment services is decoupling herbal supplement sales from traditional retail shelf presence. Nature's Bounty leverages direct-to-consumer platforms to sustain recurring revenue streams. Glanbia plc anchors its position through sports-nutrition crossover formulations. Herbalife International of America Inc. dominates multi-level distribution networks across Asia-Pacific markets.
Herbal supplements comprise phytochemical concentrates derived from plant matrices, typically standardized to marker compounds such as alkaloids, flavonoids, or terpenes through solvent extraction or supercritical CO2 processing, serving therapeutic or prophylactic functions in human nutrition. Capsule and extract formats command the largest revenue pools due to dosing precision and bioavailability claims, while tea and powder segments attract price-sensitive entrants with lower processing thresholds. Standardized formulations capture premium positioning through certificate of analysis transparency, whereas full-spectrum blends compete on traditional use narratives and whole-plant synergy arguments.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements, while the EMA monitors pharmacovigilance signals for herb-drug interactions across European member states; China's NMPA governs functional food approvals under dual-use categorization that constrains marketing claims. Stakeholders must monitor evolving borderline classifications between food and pharmaceutical status, as regulatory reclassification would force reformulation investments or channel restrictions without warning.
Market Dynamics
Subscription-based replenishment services are decoupling herbal supplement sales from traditional retail shelf presence, forcing incumbents to rebuild distribution economics around recurring revenue capture rather than one-time purchase velocity.
Growth Catalysts
- DSHEA Enforcement Evolution:The FDA's New Dietary Ingredient notification requirements are professionalizing supply chains, culling marginal operators and concentrating volume among certified manufacturers with certificate of analysis transparency.
- Sports-Nutrition Crossover Formulations:Athletic performance applications are expanding addressable demand beyond traditional wellness demographics into gym and endurance sports channels with higher per-capita spending.
- E-commerce Penetration:Direct-to-consumer platforms in China, Germany, and the United States are collapsing geographic barriers, enabling niche botanicals to reach dispersed demand clusters without physical retail investment.
Market Restraints
- Raw Material Volatility:Climate-sensitive cultivation of ginseng, turmeric, and ashwagandha concentrates supply risk in India, China, and Southeast Asia with limited near-term substitution.
- Regulatory Friction:China's NMPA dual-use categorization constrains marketing claims for functional foods, forcing parallel product lines or claim dilution for cross-border sales.
- Pharmacovigilance Surveillance:The EMA's herb-drug interaction monitoring generates label warnings that compress reimbursement eligibility and physician recommendation rates across European member states.
Strategic Opportunities
- Supercritical CO2 Processing:Clean extraction technology is integrating with solvent-free positioning to capture premium pricing in German and US markets where residue-conscious buyers dominate.
- Functional Food Approvals:China's NMPA regulatory pathway for dual-use botanicals creates first-mover advantage for standardized extracts with clinical dossiers.
- Telehealth Integration:Practitioner-directed subscription models are emerging in the United States as licensed naturopaths and integrative physicians build recurring patient protocols around specific phytochemical stacks.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Marker compound standardization requires phytochemists capable of HPLC method development, a skill set concentrated in academic rather than commercial labor pools.
- CGMP Compliance Timelines:The FDA's Current Good Manufacturing Practice enforcement demands facility upgrades that freeze working capital for 18-24 months before revenue recovery.
- Certificate of Analysis Verification:Third-party testing fraud and adulterated raw materials force brands to build captive laboratory capacity or absorb margin-destroying spot-check regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Supplements Market |
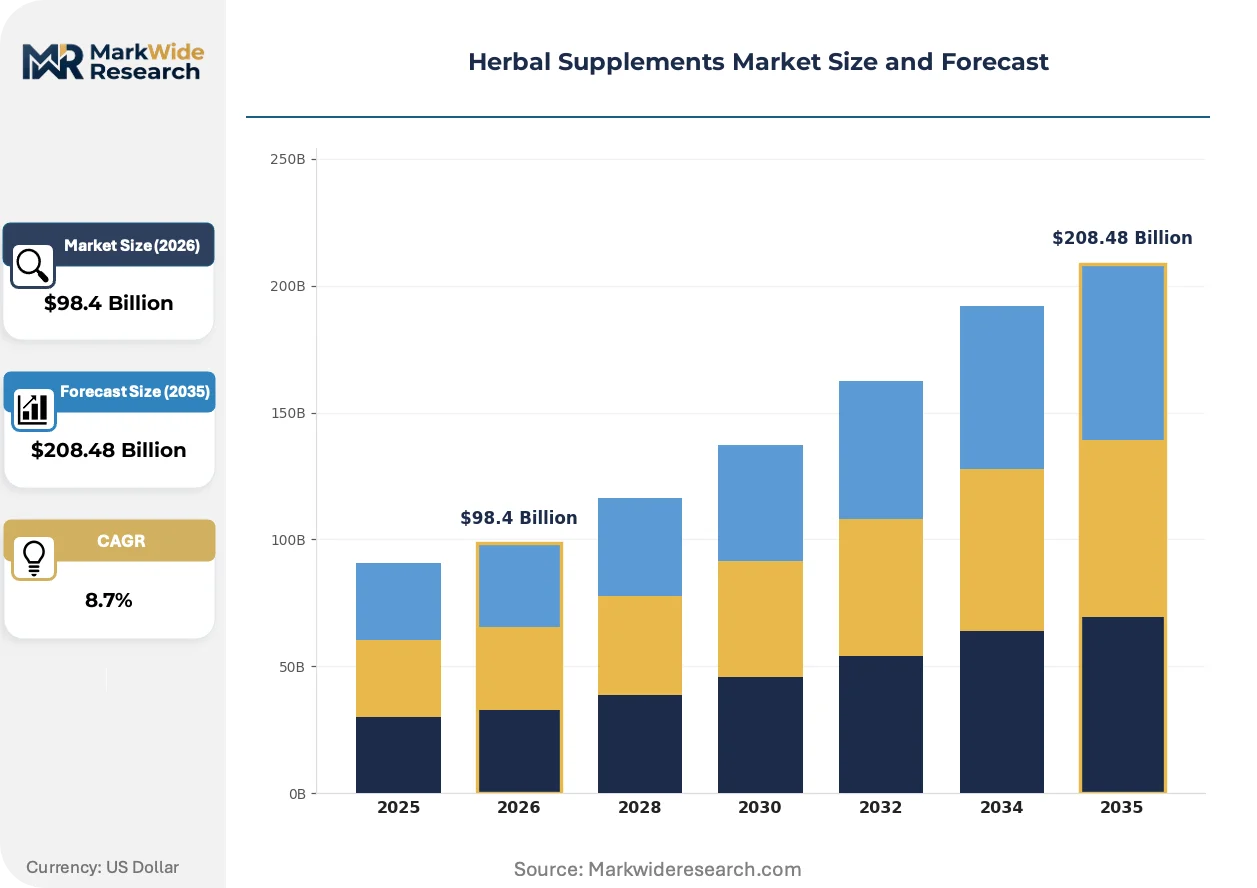
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $208.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Capsules, Powders, Teas, Oils, Tablets Formulation: Standardized, Full Spectrum, Concentrated, Organic, Customized Blends Application: Digestive Health, Immune Support, Mental Wellness, Detoxification, Joint Care, Energy Boost Customer Type: Wellness Centers, Natural Product Retailers, Healthcare Practitioners, Online Consumers, Specialty Pharmacies |
| Companies Covered | Naturalife Asia, Nature's Bounty, Archer Daniels Midland Co., Ricola Group AG, Arizona Natural Products, Glanbia plc, Blackmores, Nestle SA, Herbalife International of America Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Supplements Market Strategic Shifts & Innovations
Clean-label extraction methods and practitioner-channel integration are compressing the distance between botanical sourcing and end-user verification, reshaping how bioavailability claims get substantiated and monetized.
Supercritical CO2 extraction equipment is integrating into mid-scale processing facilities, replacing hexane and ethanol systems. Premium capsule manufacturers in Germany and the United States are adopting this technology to support residue-free positioning. The capital cost compression is enabling smaller botanical suppliers to enter standardized extract markets previously reserved for integrated chemical processors.
The EU's CSRD sustainability disclosure requirements are mandating supply chain traceability for botanical imports. Herbal supplement brands sourcing from Indian and Southeast Asian cultivation networks must now document agricultural practices and carbon intensity. Small and mid-sized European distributors without compliance infrastructure are exiting or consolidating into larger platforms with dedicated ESG reporting functions.
Practitioner-directed procurement is displacing self-directed retail purchasing for complex phytochemical formulations. Licensed naturopaths and integrative physicians in the United States are building recurring patient protocols around specific alkaloid and flavonoid stacks. This channel shift concentrates volume in professional-grade lines with clinical dossiers, compressing price-sensitive mass-market alternatives.
Herbal Supplements Market Segmentation
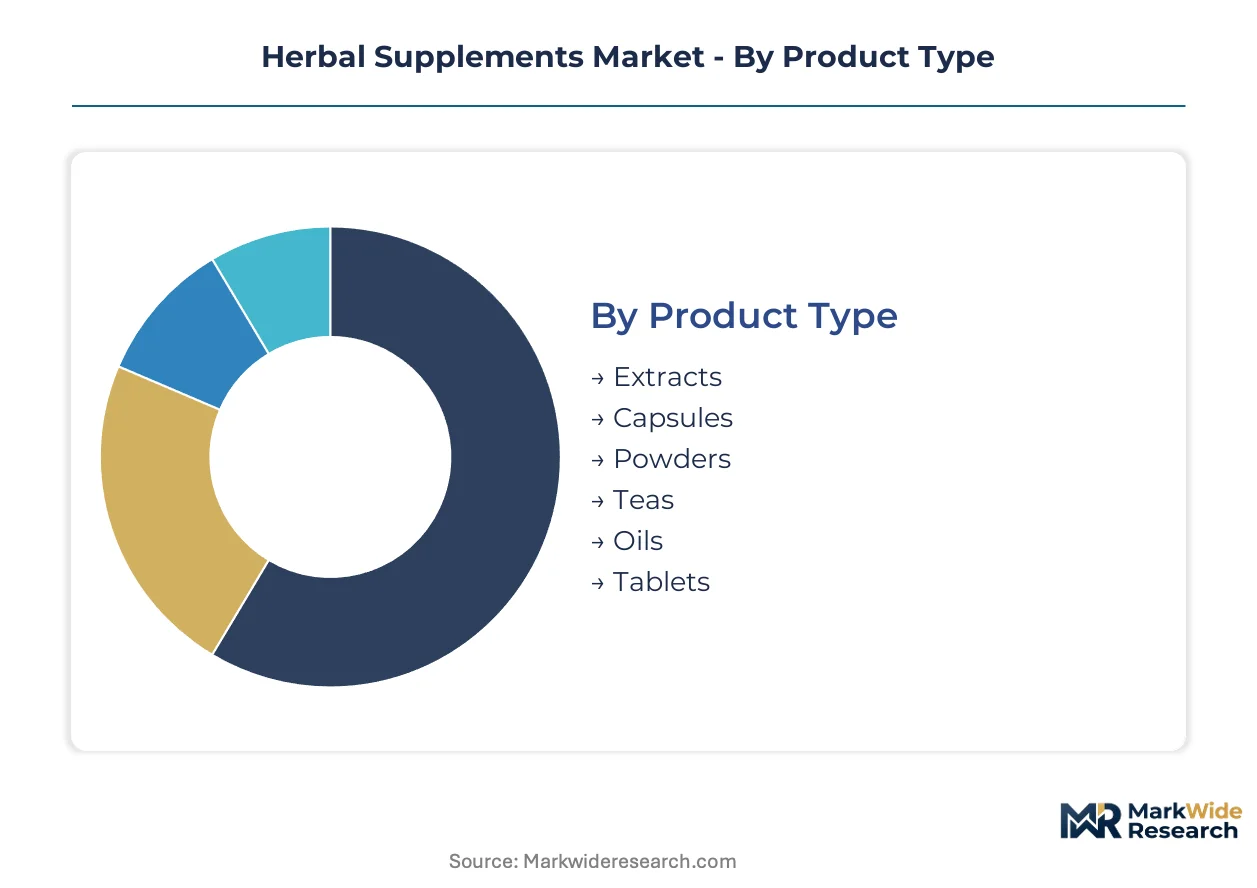
Herbal supplement segmentation reveals how formulation precision and channel economics determine margin capture. Product format and standardization level dictate regulatory burden and pricing power, while application focus shapes clinical validation requirements and reimbursement pathways.
Product Type:
Capsule and extract formats dominate premium revenue pools through dosing precision and bioavailability claims, while tea and powder segments compete on accessibility and lower processing thresholds.
- Extracts:Phytochemical concentrates standardized to marker compounds such as alkaloids or flavonoids through solvent extraction or supercritical CO2 processing. Demand concentrates in Germany and the United States where residue-conscious buyers and practitioner channels prioritize certificate of analysis transparency and clean-label positioning.
- Capsules:Encapsulated powders or granules offering precise unit dosing and extended shelf stability. Wellness centers and healthcare practitioners in the United States drive volume through protocol-based prescribing, with gelatin and vegetable-shell variants segmenting by dietary restriction compliance.
- Powders:Bulk botanical material requiring consumer preparation, competing on per-serving cost efficiency. Natural product retailers and price-sensitive online consumers in China favor this format for traditional medicine preparation flexibility.
- Teas:Whole or cut botanical material in infusion-ready form, anchored in traditional use narratives. Specialty pharmacies and wellness centers across European markets stock medicinal-grade tea lines with pharmacopoeial monograph compliance.
- Oils:Lipid-soluble active concentrates typically delivered in softgel or liquid drop formats. Healthcare practitioners prescribe these for fat-soluble phytochemical delivery where absorption kinetics matter.
- Tablets:Compressed botanical material with binders and excipients for mass-market distribution. Online consumers in volume markets select this format for convenience and travel portability.
Mature deployment sits with capsules and extracts. Newer deployment is concentrated in oils and specialized tablets targeting practitioner-directed protocols.
Formulation:
Standardization level determines regulatory pathway complexity and clinical substantiation burden, with premium positioning requiring analytical chemistry investment that marginal operators cannot sustain.
- Standardized:Marker compound quantification to defined percentages through HPLC verification, enabling structure-function claims with batch consistency. Germany's pharmacy channel and US practitioner networks demand this grade for therapeutic credibility and liability protection.
- Full Spectrum:Whole-plant extracts preserving synergistic compound matrices without isolated standardization. Natural product retailers and wellness centers promote these for traditional use narratives and entourage effect arguments.
- Concentrated:High-potency extracts with elevated active compound ratios per unit volume. Healthcare practitioners in the United States utilize these for patient compliance where dosing volume must minimize.
- Organic:Cultivation and processing certified to USDA or EU organic standards, commanding traceability premiums. Online consumers in premium demographics select these for agricultural practice transparency and pesticide avoidance.
- Customized Blends:Multi-botanical formulations tailored to specific therapeutic targets or practitioner protocols. Wellness centers and integrative medicine clinics commission these for differentiated service offerings.
Volume leadership belongs to full spectrum and standardized formulations. Steepest expansion trajectory is concentrated in customized blends serving telehealth-integrated practitioner networks.
Application:
Therapeutic indication shapes clinical evidence requirements and channel access, with wellness-positioned applications facing lighter substantiation burdens than condition-specific claims.
- Digestive Health:Botanicals targeting gastrointestinal function through antimicrobial, anti-inflammatory, or motility-modulating mechanisms. Wellness centers and natural product retailers in Germany stock these for functional dyspepsia and microbiome support protocols.
- Immune Support:Immunomodulatory phytochemicals positioned for prophylactic or acute immune challenge response. Online consumers and specialty pharmacies drove volume expansion through pandemic-period habit formation.
- Mental Wellness:Anxiolytic and adaptogenic botanicals targeting stress response and cognitive function. Healthcare practitioners in the United States prescribe these for patients seeking pharmaceutical alternatives.
- Detoxification:Hepatoprotective and elimination-supporting botanicals with traditional cleansing narratives. Wellness centers incorporate these into structured protocol programs.
- Joint Care:Anti-inflammatory botanicals for musculoskeletal comfort and mobility support. Natural product retailers and specialty pharmacies serve aging demographics with these formulations.
- Energy Boost:Stimulant and adaptogenic botanicals for physical and mental performance enhancement. Sports-nutrition crossover channels and online consumers seeking productivity optimization drive this segment.
Established positioning sits with digestive health and immune support. Emerging positioning is concentrated in mental wellness applications as practitioner integration deepens.
Customer Type:
Channel selection determines pricing architecture and compliance requirements, with direct-to-consumer platforms collapsing traditional retail intermediation.
- Wellness Centers:Facility-based providers offering integrated health services with botanical protocol integration. These operators in the United States and Germany bundle supplements with consultation fees.
- Natural Product Retailers:Brick-and-mortar and e-commerce specialists in organic and holistic health merchandise. Staff training requirements and inventory breadth differentiate regional from national players.
- Healthcare Practitioners:Licensed naturopaths, integrative physicians, and allied providers prescribing professional-grade lines. The United States shows fastest channel growth as telehealth enables recurring protocol management.
- Online Consumers:Self-directed purchasers through brand-direct websites and marketplace platforms. Subscription replenishment services are decoupling this segment from retail shelf dependence.
- Specialty Pharmacies:Compounding and functional medicine-focused dispensaries with pharmacist consultation. European markets particularly Germany maintain stronger pharmacy channel presence for botanicals.
Traditional volume concentration sits with natural product retailers. Fastest channel expansion is concentrated in online consumers and healthcare practitioners as subscription models and telehealth integration reshape procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of raw botanicals concentrates in India and China, while formulation and premium consumption gravitate toward Germany and the United States. This geographic split shapes regulatory compliance burdens and margin capture across the value chain.
United States
Healthcare practitioners and subscription-based direct-to-consumer platforms drive demand for standardized extracts and practitioner-grade capsules. The FDA enforces Current Good Manufacturing Practice regulations through facility inspections and New Dietary Ingredient notifications. Utah and California host dense clusters of dietary supplement manufacturers upgrading analytical chemistry capabilities for marker compound verification.
Germany
Pharmacy-channel distribution and residue-conscious consumers sustain premium positioning for supercritical CO2 processed extracts. The EMA monitors pharmacovigilance signals for herb-drug interactions, compressing reimbursement eligibility for products with safety warnings. Bavaria anchors production of medicinal-grade tea lines with pharmacopoeial monograph compliance.
China
Domestic cultivation of ginseng, goji, and astragalus supplies raw material for both export and functional food applications. The NMPA governs dual-use categorization that constrains marketing claims for cross-border sales. Shandong Province concentrates extraction facilities serving domestic e-commerce platforms and Southeast Asian export markets.
India
Ashwagandha, turmeric, and holy basil cultivation in Maharashtra and Karnataka underpins global supply for adaptogenic and anti-inflammatory formulations. The FSSAI regulates functional food and nutraceutical safety standards with evolving enforcement timelines. Bangalore hosts contract research organizations developing clinical dossiers for NMPA functional food approvals.
Japan
Aging demographics and traditional medicine integration sustain demand for Kampo-derived formulations and specialized tea extracts. The PMDA maintains strict borderline classifications between food and quasi-drug status, forcing claim precision in marketing materials. Tokyo-Osaka corridor concentrates distribution networks linking domestic manufacturers with retail pharmacy and wellness center channels.
Herbal Supplements Market Key Industry Players
Capital-heavy extraction and processing facilities compete with asset-light brand marketers and formulation specialists. The market structure fragments across certified manufacturers with captive laboratory capacity, mid-scale processors adopting supercritical CO2 technology, and direct-to-consumer platforms with subscription replenishment infrastructure. Strategic archetypes include integrated botanical processors, multi-level distribution networks, and practitioner-channel specialists. Competitive moves concentrate on CGMP certification acquisition, telehealth-practitioner partnership development, and ESG-compliant supply chain traceability documentation.
Among integrated processors with global raw material sourcing, Archer Daniels Midland Co. and Glanbia plc exemplify scale-driven extraction and sports-nutrition crossover strategies. Within direct-to-consumer and multi-level distribution, Nature's Bounty and Herbalife International of America Inc. occupy positions decoupled from traditional retail shelf dependence. Ricola Group AG represents heritage brand positioning anchored in traditional use narratives and pharmacy-channel access.
| Leading Market Players |
|---|
| Naturalife Asia |
| Nature's Bounty |
| Archer Daniels Midland Co. |
| Ricola Group AG |
| Arizona Natural Products |
| Glanbia plc |
| Blackmores |
| Nestle SA |
| Herbalife International of America Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap processors in Maharashtra and Shandong provinces anchor raw material sourcing, linking cultivation financing directly to contract pricing discipline for ashwagandha and ginseng rootstock. Their balance-sheet exposure to climate volatility enforces premium extraction markups that cascade through German pharmacy channels and US practitioner networks.
Pricing Analysis
Margin tightening in standardized extract tiers reflects supercritical CO2 equipment amortization and captive laboratory buildout costs. Three-tier pricing structure across premium, standard, and economy levels segments by certificate of analysis depth and residue-testing rigor. Pricing pressure stems from spot-check regimes and third-party testing fraud exposure forcing brands to absorb verification costs. Online consumers exhibit highest price sensitivity, while healthcare practitioners accept premium positioning for clinical dossier transparency.
Supply Chain Analysis
Botanical raw material supply rests on Indian adaptogenic cultivation, Chinese ginseng and goji production, and Southeast Asian turmeric networks. Dependency concentrates on ashwagandha rootstock, ginseng rhizomes, and supercritical CO2 extraction equipment. Single-source vulnerability intensifies through climate-sensitive harvest cycles with limited near-term substitution. Distribution runs through direct-to-consumer subscription platforms, practitioner-directed procurement networks, and pharmacy-channel dispensaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is displacing hexane and ethanol solvent systems, compressing capital barriers for mid-scale processors and fragmenting premium positioning.
For Market Incumbents: Deploy CGMP certification acquisition as the primary defensive lever against FDA enforcement culling marginal operators. Build captive laboratory capacity for marker compound verification to neutralize third-party testing fraud exposure. Channel control through telehealth-practitioner partnerships secures recurring protocol volumes against subscription-platform disintermediation. For New Entrants and Emerging Players: Direct-to-consumer subscription routes offer lowest barrier entry for niche botanical positioning outside established retail shelf dependence. Mental wellness applications present most penetrable segment as practitioner integration accelerates patient protocol adoption. Practitioner-channel white-label manufacturing provides go-to-market angle with clinical dossier co-development. For Investors and Strategic Acquirers: Distressed-cycle entries favor certified manufacturers with analytical chemistry infrastructure in Germany and the United States. Long-term viability centers on ESG-compliant supply chain traceability and dual-use regulatory pathway navigation. Watch NMPA functional food approval timelines as inflection signal for China market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Equipment Deployment | Clean extraction technology captures residue-conscious premium positioning in German and US markets. |
| CGMP Certification Investment | FDA facility compliance separates certified manufacturers from enforcement-culled marginal operators. |
| Telehealth-Practitioner Partnership Development | Licensed naturopath protocol integration builds recurring revenue outside retail shelf dependence. |
| ESG Supply Chain Traceability Documentation | EU CSRD disclosure requirements force agricultural practice transparency for botanical imports. |
| NMPA Functional Food Approval Pathway | China dual-use categorization creates first-mover advantage for standardized extracts with clinical dossiers. |
Research Approach
Trade databases, pharmacovigilance registries, and customs import records formed the secondary backbone, cross-referenced with primary interviews involving extraction facility operators, regulatory affairs specialists at dietary supplement manufacturers, licensed naturopaths and integrative physicians, and procurement managers at natural product retailers. Bottom-up volume triangulation across product format segments was reconciled with top-down value estimates from channel revenue analysis.
Historical trendline analysis of herbal supplement shipments tracked standardization level adoption and channel migration patterns across the projection horizon. Segmentation dimensions modeled include product format, formulation precision tier, therapeutic application focus, and customer channel type. CAGRs were derived from regression analysis of volume trajectories, incorporating raw material availability constraints and regulatory enforcement intensity as industry-specific forecast inputs.
Inputs from EMA pharmacovigilance databases and NMPA approval registries were available through the study window; gaps in real-time cultivation yield data introduce uncertainty bands around raw material cost assumptions. Forecasts reflect documented assumptions regarding DSHEA enforcement evolution and climate volatility patterns. Regulatory reclassification triggers, supply chain disruption events, and analytical chemistry talent scarcity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Nootropic Products Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Sleep Aid Supplements Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Global Beauty Supplements Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Medicinal Mushroom Powder Market