
 China Table Grapes Market | 2026-2036
China Table Grapes Market Size, Share, and Industry Trends Forecast 2026-2036
China Table Grapes Market Insights
Skilled agricultural labor availability is bifurcating the China table grapes landscape, with large-scale operations pulling experienced vineyard managers away from smaller cooperatives. China Green Food Group leverages vertical integration across cold storage and provincial distribution to sustain year-round supply consistency. Shandong Sun Grape anchors its position through dominant shelf presence in eastern province supermarket chains. Xinjiang Korla Fragrant Pear Grape differentiates via geographic specialization in high-sugar desert-climate varieties with distinct aromatic profiles.
Table grapes denote Vitis vinifera and Vitis labrusca cultivars bred for fresh consumption rather than wine or raisin processing, with brix levels typically ranging from 16 to 22 degrees and berry diameters exceeding 18 millimeters for export-grade sorting. Red Grapes occupy the largest volume share in domestic trade, while Muscat Grapes represent the fastest-growing premium tier driven by gifting culture in urban households. Supermarkets channel the majority of branded volume, though Online Retail is capturing incremental share among younger consumers seeking direct-from-orchard traceability.
China's national agricultural regulator enforces GB standards for pesticide maximum residue limits that directly determine orchard certification and market access for packaged fruit. The country's dual carbon goals pressure growers to adopt solar-powered cold storage and reduce plastic packaging intensity under MEE circular economy directives. Stakeholders must monitor how evolving SAMR food labeling requirements for origin traceability reshape procurement contracts between cooperatives and downstream retailers.
Market Dynamics
Agricultural labor migration from Shandong and Hebei to Xinjiang's mechanized desert vineyards is compressing wage differentials and forcing coastal cooperatives into premature automation investments they cannot amortize.
Growth Catalysts
- Dual carbon goals:MEE circular economy directives mandate solar-powered cold storage retrofits, creating asset-backed financing demand for provincial agricultural banks.
- GB standards harmonization:SAMR pesticide residue protocols enable certified orchards to bypass multiple provincial inspection layers, accelerating inter-provincial trade velocity.
- Desert-climate specialization:Xinjiang's Turpan Basin concentrates heat-unit accumulation for aromatic varieties that coastal humidity cannot replicate.
Market Restraints
- Input cost volatility:Potassium fertilizer prices track Belarusian supply disruptions, squeezing margin structures for Hebei cooperatives locked into annual procurement contracts.
- Supply concentration risk:Xinjiang's Korla corridor controls over half of premium Muscat volume, exposing buyers to single-region climate shocks.
- Technical limitation:Post-harvest sulfur dioxide pads remain the sole scalable decay control for long-haul rail shipments to Guangzhou and Shenzhen.
Strategic Opportunities
- Hainan duty-free channel:Offshore duty-free stores attract premium gifting demand from domestic tourists seeking traceable origin packaging.
- Blockchain provenance:SAMR food labeling requirements for origin traceability converge with Alibaba's AntChain agricultural pilots to create immutable orchard-to-retail records.
- Direct-to-consumer platforms:Douyin live-streaming enables Xinjiang growers to bypass provincial wholesale layers entirely.
Industry Challenges
- Vineyard management talent scarcity:Experienced canopy specialists command premiums that Shandong cooperatives cannot match against state-backed Xinjiang operations.
- Cold chain capex intensity:GB-compliant refrigerated warehousing requires RMB 8,000 per pallet-position investment that sub-50-hectare orchards cannot finance.
- Certification timeline compression:Green Food certification audits now demand 18-month residue documentation that delays new variety commercialization.
Report Scope
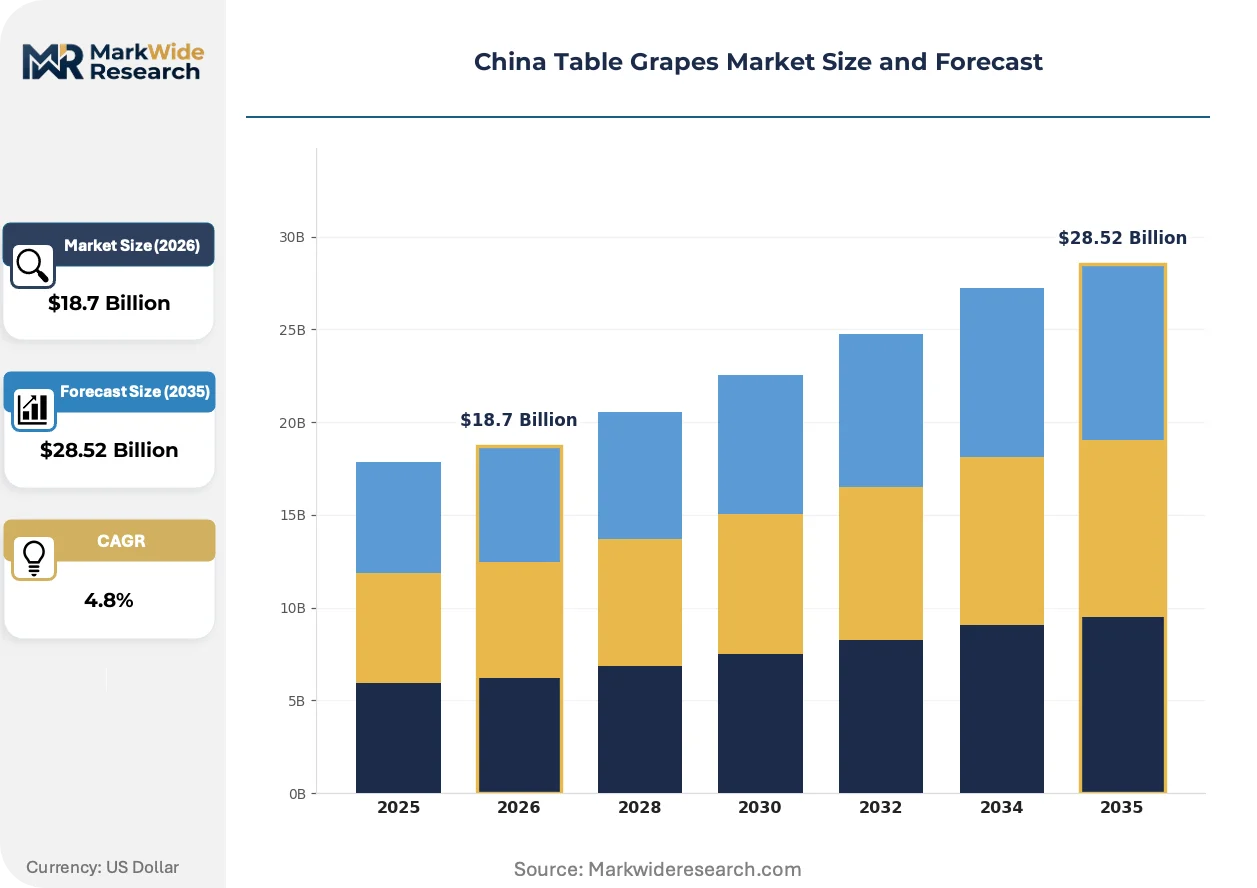
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Table Grapes Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Grapes, Green Grapes, Black Grapes, Muscat Grapes Distribution Channel: Supermarkets, Online Retail, Wholesalers, Farmers' Markets Packaging Type: Bags, Clamshells, Trays, Bulk End User: Households, Restaurants, Food Processing, Retailers |
| Companies Covered | China Green Food Group, Fujian Agro Group, Shandong Sun Grape, Hebei Chengxin Grape, Xinjiang Korla Fragrant Pear Grape, Beijing Shunxin Agriculture, Guangdong Strong Group, Zhejiang Pagoda Fruits, Yunnan Honghe Fruit, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Table Grapes Market Trends and Innovations
Domestic cold chain modernization is colliding with consumer traceability demands to reshape how table grapes move from Turpan Basin orchards to Shanghai supermarket shelves.
Smart sorting lines integrating near-infrared brix sensors and AI-powered defect detection are supplanting manual grading crews in Shandong packing houses. Large-scale operations in Yantai and Weifang deploy these systems to maintain GB export-grade consistency with one-third the labor headcount. The technology is compressing tolerance for human error in premium-tier sorting, effectively excluding smaller cooperatives from branded retail supply contracts.
China's dual carbon goals are accelerating solar photovoltaic deployment across agricultural cold storage facilities under MEE circular economy directives. Provincial energy bureaus in Xinjiang and Ningxia now condition agricultural subsidies on renewable power share thresholds. Facilities in the Turpan corridor respond by installing rooftop arrays that offset diesel generator dependency during grid instability.
Urban household procurement patterns are fragmenting across channel types as younger consumers abandon traditional wet markets for direct-from-orchard e-commerce. Tmall Farm and Pinduoduo's agricultural vertical capture Muscat gifting demand that previously flowed through physical fruit boutiques in Beijing and Shanghai. This disintermediation is most visible in first-tier cities where cold-chain logistics density enables next-day delivery from 2,000-kilometer origins.
China Table Grapes Market Segmentation
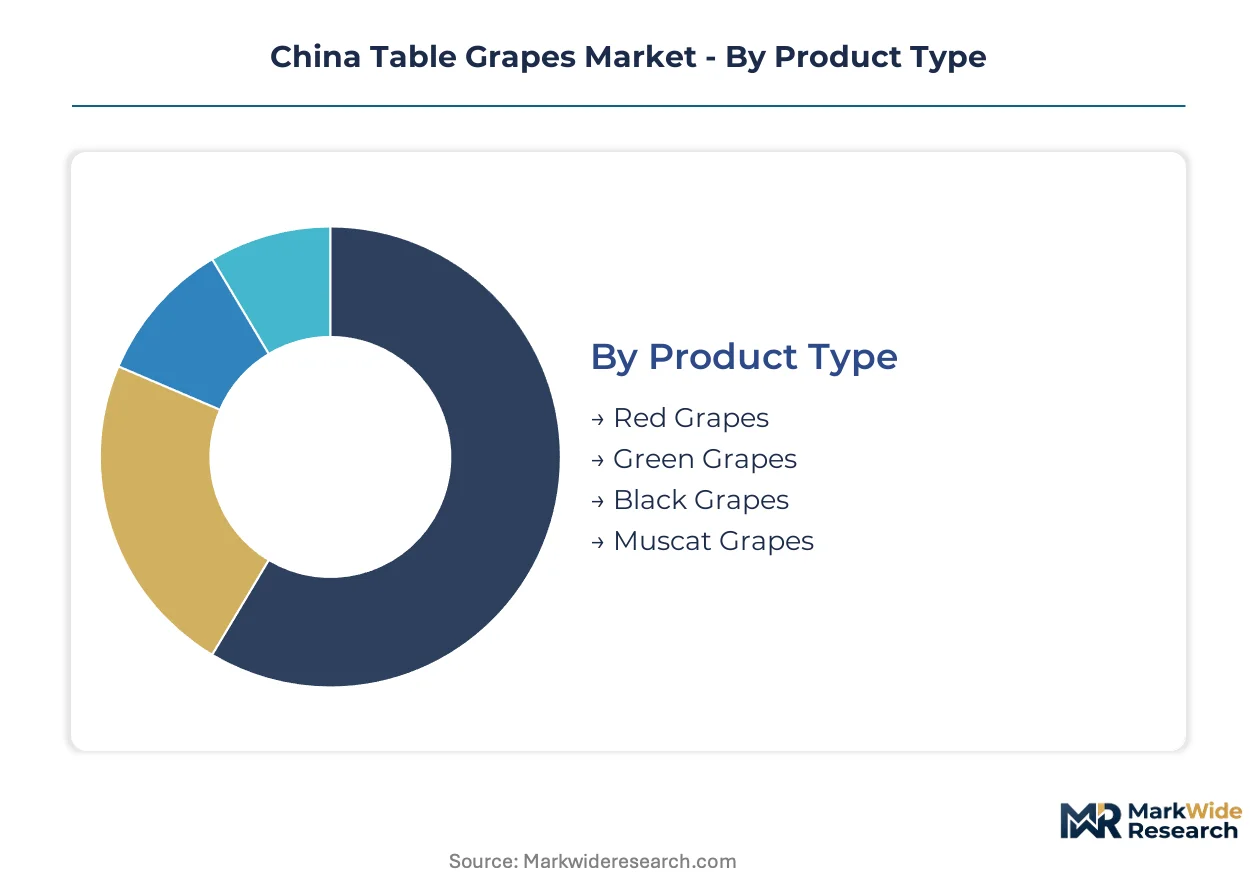
Segmentation in China's table grapes market reveals how procurement patterns and consumption occasions fragment across channels and product tiers. Understanding these divisions exposes where margin pools concentrate and which substitution threats reshape competitive positioning.
Product Type:
Substitution pressure from imported Chilean and Australian grapes hits standard-color varieties hardest, while aromatic specialty cultivars maintain defensive moats through sensory differentiation.
- Red Grapes:Vitis vinifera cultivars with anthocyanin-rich skins dominate domestic procurement volumes. Coastal tier-one supermarkets anchor demand, though Xinjiang's desert-climate production now challenges Shandong's historical supply dominance through higher brix accumulation.
- Muscat Grapes:Aromatic Vitis vinifera varieties with distinctive floral terpene profiles command premium shelf positioning. Urban gifting culture in Beijing and Shanghai drives demand concentration, with SAMR origin traceability requirements reinforcing branded premiumization.
- Green Grapes:Thompson Seedless derivatives serve processing and mid-market fresh consumption. Hebei cooperatives concentrate supply, facing margin compression from potassium fertilizer cost volatility.
- Black Grapes:Dark-skinned varieties with elevated polyphenol content target health-positioned consumption. Ningxia's emerging vineyard base experiments with these cultivars for differentiated export positioning.
Red Grapes anchors the volume base while Muscat Grapes gains share at the steepest rate.
Distribution Channel:
Cost tier fragmentation separates capital-intensive cold chain infrastructure from low-touch wholesale arbitrage, with digital intermediaries capturing margin from both extremes.
- Supermarkets:Branded retail chains with GB-compliant refrigerated display cases dominate volume throughput. Yonghui and CR Vanguard anchor procurement, with private label programs squeezing cooperative suppliers on specification consistency.
- Online Retail:Direct-to-consumer platforms with cold-chain logistics density enable next-day delivery from 2,000-kilometer origins. Tmall Farm and Pinduoduo agricultural verticals capture younger household demand seeking orchard traceability.
- Wholesalers:Provincial aggregation layers with minimal cold chain investment move unpackaged volume to secondary cities. Xinjiang's Korla corridor controls upstream supply, exposing buyers to single-region climate concentration.
- Farmers' Markets:Traditional wet market stalls with ambient temperature handling serve price-sensitive household procurement. Tier-two and tier-three cities maintain this channel's relevance despite urban migration to modern retail.
Supermarkets command the revenue concentration while Online Retail climbs the fastest.
Packaging Type:
Application-driven packaging selection separates export-grade presentation from domestic bulk efficiency, with MEE circular economy directives forcing material transitions.
- Clamshells:Rigid PET containers with modified atmosphere properties protect berry integrity for premium retail placement. SAMR labeling requirements for origin traceability integrate with clamshell surface printing.
- Bags:Perforated polyethylene films with sulfur dioxide pad compatibility serve long-haul rail shipments to Guangzhou and Shenzhen. Cost efficiency dominates procurement criteria for wholesale channel volume.
- Trays:Molded pulp or plastic platforms with stretch film overwrap balance presentation and protection for mid-tier supermarket SKUs.
- Bulk:Unpackaged volume in reusable crates serves food processing procurement and institutional restaurant demand with minimal handling overhead.
Bags carry the volume foundation while Clamshells expand most quickly on premiumization.
End User:
Customer type heterogeneity splits between ritualized gifting occasions and operational ingredient demand, with diverging quality tolerance and price elasticity.
- Households:Urban consumers in tier-one cities drive premium Muscat demand for Lunar New Year and Mid-Autumn Festival gifting. Cold chain logistics density enables direct-from-orchard e-commerce substitution of traditional fruit boutiques.
- Restaurants:Foodservice operators prioritize berry size consistency and shelf stability for dessert plating and buffet presentation. Wholesale channel procurement dominates with annual contract pricing.
- Food Processing:Juice concentrate and raisin manufacturers absorb sub-export-grade volume with relaxed cosmetic specifications. Xinjiang's Turpan Basin concentration supplies this tier through forward contract structures.
- Retailers:Supermarket and convenience store chains with private label programs enforce GB pesticide residue compliance through certified orchard audits. Green Food certification timelines compress supplier onboarding.
Households anchor consumption volume while Retailers capture value at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang's desert-climate premium grapes command shelf prices 40% above Hebei's coastal output, yet the latter retains procurement leverage through cold chain proximity to Shanghai and Beijing retail channels. This geographic pricing asymmetry shapes investment flows and variety specialization across China's table grape production belt.
Xinjiang Autonomous Region
Turpan Basin's 3,200 annual heat units drive Muscat aromatic intensity unmatched by humid coastal zones. MEE dual carbon goals mandate solar photovoltaic retrofits for cold storage facilities receiving agricultural subsidies. Korla corridor packing houses now deploy rooftop arrays to offset diesel dependency during grid instability.
Shandong Province
Weifang and Yantai clusters anchor Red Grape volume for eastern supermarket chains with next-day logistics reach. GB standards pesticide residue protocols enable certified orchards to bypass multiple provincial inspection layers. Smart sorting lines with near-infrared brix sensors compress labor headcount by two-thirds in large packing operations.
Hebei Province
Thompson Seedless derivatives serve mid-market fresh consumption and processing demand from Beijing-Tianjin-Hebei corridor. Potassium fertilizer price volatility linked to Belarusian supply disruptions squeezes cooperative margin structures. Langfang and Baoding sub-regions face skilled vineyard manager attrition to Xinjiang's state-backed wage premiums.
Yunnan Province
Honghe and Pu'er valleys exploit low-latitude climate for counter-seasonal harvest windows capturing premium pricing. SAMR food labeling requirements for origin traceability integrate with provincial agricultural blockchain pilots. Kunming logistics hubs enable direct-to-consumer e-commerce fulfillment bypassing traditional wholesale layers.
Beijing-Tianjin-Hebei Metro
Urban household gifting demand concentrates Lunar New Year and Mid-Autumn Festival procurement in premium Muscat tiers. SAMR enforces GB pesticide maximum residue limits determining orchard certification for packaged fruit market access. Cold chain density from Tianjin port facilities supports import substitution strategies for coastal retailers.
China Table Grapes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated state-backed operations in Xinjiang controlling desert-climate variety development while Shandong cooperatives compete on logistics proximity. The market structures around three tiers: large-scale integrated producers with captive cold storage, regional cooperatives locked into supermarket private label programs, and direct-to-consumer digital native growers leveraging live-streaming platforms. Strategic moves concentrate on backward integration into cold chain infrastructure and certified orchard acquisition to secure GB-compliant supply pipelines.
Among state-backed integrated producers, China Green Food Group and Xinjiang Korla Fragrant Pear Grape exemplify the vertical control archetype spanning cultivation through provincial distribution. Shandong Sun Grape occupies a position representing coastal cooperative scale concentration with dominant shelf presence in eastern supermarket chains. These three entities anchor the competitive structure, with the first two representing upstream-controlled desert specialization and the third exemplifying logistics-advantaged coastal aggregation.
| Leading Market Players |
|---|
| China Green Food Group |
| Fujian Agro Group |
| Shandong Sun Grape |
| Hebei Chengxin Grape |
| Xinjiang Korla Fragrant Pear Grape |
| Beijing Shunxin Agriculture |
| Guangdong Strong Group |
| Zhejiang Pagoda Fruits |
| Yunnan Honghe Fruit |
| Others |
Pricing and Supply Chain Analysis
Mechanized vineyard automation displaces manual canopy management across Shandong and Hebei, compressing coastal labor premiums while elevating Xinjiang's desert-climate grape pricing power through irreplaceable aromatic accumulation. This substitution dynamic redraws procurement geography and fragments margin structures between logistics-advantaged eastern cooperatives and heat-unit-specialized western operations.
Pricing Analysis
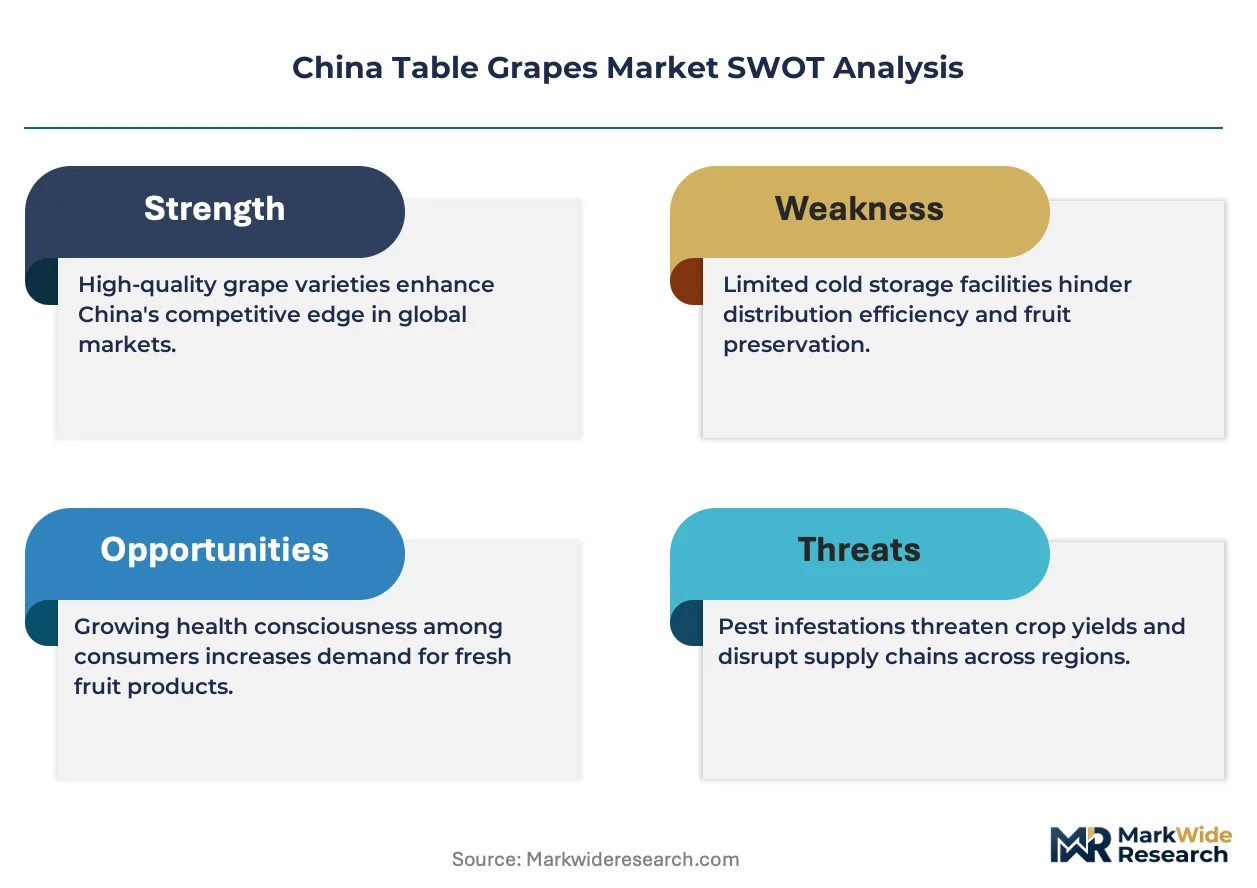
The customization-premium spread separates GB-certified orchard contracts with embedded traceability from bulk wholesale volume lacking residue documentation. Three-tier pricing structure across premium, standard, and economy levels reflects Muscat aromatic intensity, Red Grape brix thresholds, and processing-grade cosmetic tolerance. Pricing pressure stems from potassium fertilizer cost volatility linked to Belarusian supply disruptions, squeezing Hebei cooperative margins. Food processing buyers exhibit highest price sensitivity, while urban household gifting demand for traceable origin packaging shows lowest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate Xinjiang's Korla corridor, where single-region Muscat concentration compels buyers to secure forward contracts before harvest windows. Supply concentrates in Xinjiang, Shandong, and Hebei, with desert-climate varieties drawing from Turpan Basin heat accumulation and coastal output resting on cold chain proximity to Beijing-Tianjin-Hebei retail. Potassium fertilizer, sulfur dioxide pads, and clamshell packaging constitute critical input dependencies. Single-region climate vulnerability poses structural supply risk. Distribution runs through supermarket private label programs, provincial wholesale layers, and direct-to-consumer e-commerce platforms with diverging cold chain intensity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in SAMR regulatory entrenchment, where GB certification timelines and residue documentation requirements create switching costs that lock supermarket buyers into established orchard relationships.
For Market Incumbents: Fortify backward integration into solar-powered cold storage to meet MEE dual carbon subsidy thresholds and secure year-round supply consistency. Deepen captive supply of certified orchards in Xinjiang's Korla corridor to defend against climate shock vulnerability. Expand smart sorting capacity with near-infrared brix sensors to maintain GB export-grade tolerance advantages over cooperative competitors.
For New Entrants and Emerging Players: Direct-to-consumer traceability platforms represent the most penetrable service-layer gap, as incumbents under-serve younger urban households seeking orchard-to-retail blockchain records. Target first-tier city e-commerce channels with Douyin live-streaming fulfillment bypassing traditional wholesale markups. Pursue Hainan duty-free store placement for premium gifting demand with simplified origin packaging compliance.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated cold chain operators with certified orchard pipelines. Long-term viability over the projection horizon rests on renewable-powered storage assets and SAMR-compliant traceability infrastructure. Acquisition focus should center on Xinjiang-based operations with Turpan Basin vineyard control and rooftop solar retrofits. Watch for SAMR food labeling requirement enforcement acceleration as inflection indicator for traceability technology valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Orchard Acquisition | GB-compliant residue documentation secures supermarket private label contract eligibility under SAMR protocols. |
| Solar Cold Storage Retrofit | MEE dual carbon subsidy conditioning creates asset-backed financing advantages for provincial agricultural banks. |
| Blockchain Traceability Deployment | AntChain agricultural pilots converge with SAMR origin requirements to create immutable orchard-to-retail records. |
| Smart Sorting Line Investment | Near-infrared brix sensors compress labor headcount while maintaining GB export-grade specification consistency. |
| Direct-to-Consumer Platform Launch | Douyin live-streaming enables Xinjiang growers to bypass provincial wholesale layers entirely for margin capture. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with vineyard managers, cold chain logistics operators, supermarket category buyers, and provincial agricultural bureau officials; and secondary validation through China customs trade records, SAMR GB standards documentation, MEE circular economy directives, and agricultural subsidy disbursement databases. Bottom-up orchard capacity modeling triangulated against top-down provincial production statistics.
Across the analysis window, forecasts employed segmented modeling across product type, distribution channel, packaging format, and end-user occasion dimensions. CAGRs derived from historical volume trajectories, projected cold chain infrastructure deployment, and urban household gifting demand elasticity. Key inputs included potassium fertilizer price indices, MEE renewable energy share thresholds, and SAMR certification timeline compression effects.
Forecasts assume regulatory continuity in SAMR food labeling and MEE dual carbon regimes; material policy shifts would require re-modeling. Specific risks include GB standards harmonization delays, Xinjiang climate shock events, and cold chain capex financing constraints. Revision becomes warranted when potassium fertilizer volatility or SAMR enforcement acceleration crosses structural threshold levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Morocco Fruits and Vegetables Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
Asia-Pacific Sweet Potatoes Market
Fruits and Vegetables
Cranberries Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
US Fruit and Vegetables Market
Fruits and Vegetables
Brined Vegetable Market