
 Starchy Roots Market | 2026-2036
Starchy Roots Market Size, Share, and Industry Trends Forecast 2026-2036
Starchy Roots Market Analytics
Premium-grade starch specifications is reorganizing procurement priorities across the value chain. McCain Foods leverages its frozen-form dominance to secure long-term potato supply contracts in North America. Cargill Incorporated anchors global trade flows through its grain-and-root origination networks. Lamb Weston Holdings differentiates via specialized processing lines for foodservice fry specifications.
Starchy roots comprise carbohydrate-dense underground plant structures—primarily potatoes, cassava, yams, and taro—containing 15–25% amylose and 75–85% amylopectin by dry weight, extracted through washing, rasping, and centrifugal separation for food, feed, and industrial applications. Fresh-form potatoes command the largest volume pool, though dried cassava starches represent the fastest-expanding margin segment for pharmaceutical excipient and adhesive applications. Powdered forms concentrate value in infant nutrition and modified starch derivatives where Ingredion Incorporated and Tate & Lyle PLC compete on texturizing functionality.
The FDA governs starch adulteration and labeling under 21 CFR standards, while the EU Green Deal and REACH impose pesticide residue ceilings and deforestation due diligence on imported root crops. India's FSSAI and BIS standards tighten mycotoxin limits for cassava entering processed food channels. Stakeholders must monitor evolving carbon border adjustments and biogenic content verification rules that will reshape sourcing geography and processing investment.
Market Dynamics
Clean-label starch demand is compressing supply chains toward single-origin cassava sourcing, while EU Green Deal residue mandates force processors to requalify entire supplier bases. This dual pressure is restructuring procurement priorities across food, pharmaceutical, and industrial channels simultaneously.
Growth Catalysts
- EU Green Deal agricultural mandates:Tightening pesticide residue ceilings on imported root crops are accelerating investment in certified sustainable farming clusters across Southeast Asian supply basins.
- Pharmaceutical excipient demand:Modified cassava starches with specific amylopectin ratios are displacing corn-derived alternatives in tablet binding and controlled-release formulations.
- Clean-label food processing:Consumer packaged goods manufacturers are specifying native, unmodified starches for ingredient statements that exclude chemical modification terminology.
Market Restraints
- Input cost volatility:Natural gas prices directly determine drying and extraction economics for cassava starch facilities, creating margin compression during energy price spikes.
- Supply concentration risk:Premium-grade cassava root availability concentrates in Thai and Vietnamese processing corridors, exposing buyers to monsoon-driven harvest variability.
- Regulatory friction:REACH registration requirements for imported starch derivatives impose documentation burdens that delay new supplier onboarding by 12-18 months.
Strategic Opportunities
- Indian domestic market expansion:FSSAI mycotoxin standard enforcement is driving consolidation toward integrated processing facilities that can guarantee batch-level contamination control.
- Biodegradable packaging convergence:Thermoplastic starch blends with polylactic acid are opening volume channels in foodservice disposables where compostability certification commands price premiums.
- Carbon border adjustment positioning:Early biogenic content verification systems will advantage processors who can document deforestation-free sourcing ahead of 2026 implementation timelines.
Industry Challenges
- Specialized process engineering talent:Centrifugal separation optimization and modified starch reactor operation require skills that outpace regional technical education capacity in major producing regions.
- Multi-standard certification complexity:Simultaneous compliance with FDA 21 CFR, EU organic, and BIS specifications for the same production line demands redundant quality management systems.
- Legacy equipment retrofit costs:Existing rasping and extraction lines designed for commodity output cannot achieve premium-grade specifications without substantial capital reinvestment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starchy Roots Market |
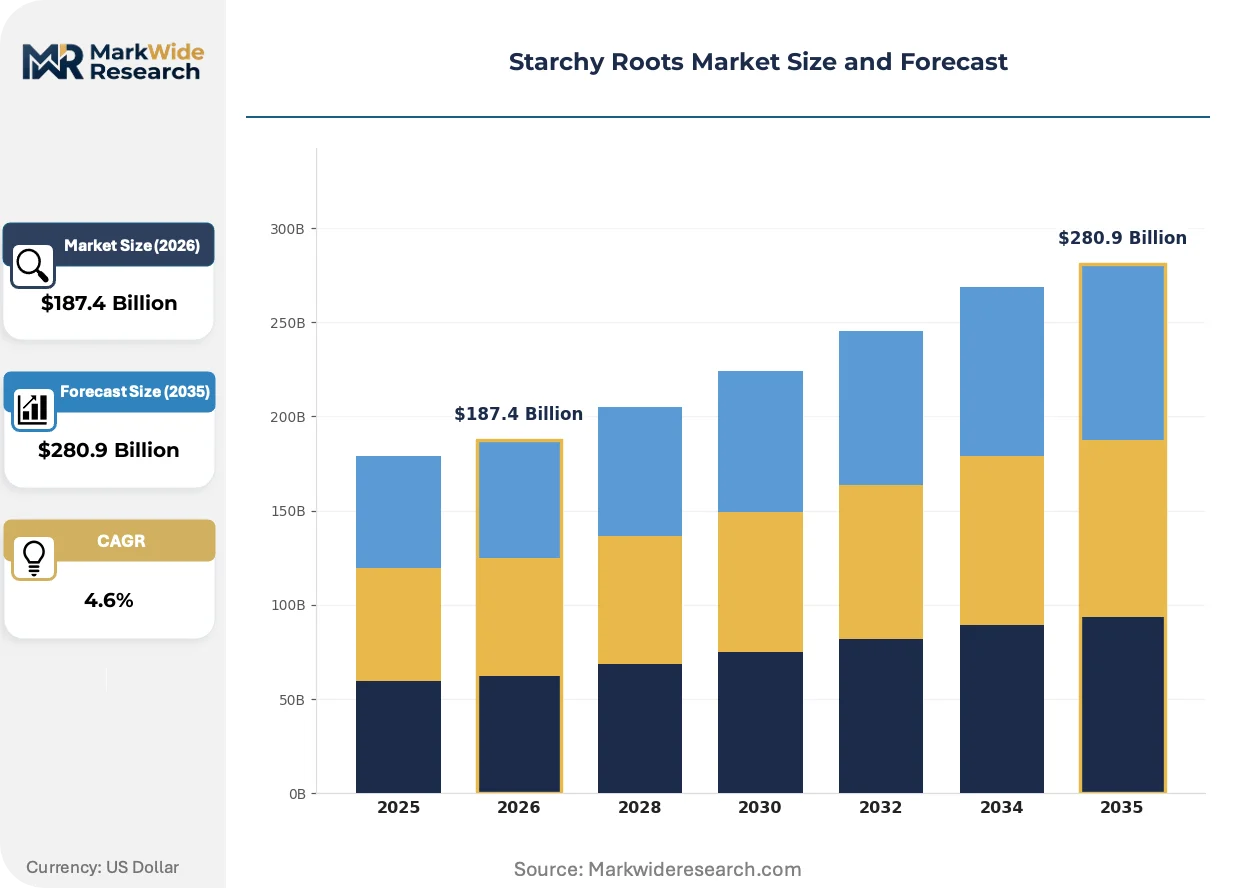
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $280.9 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potatoes, Cassava, Yams, Taro End Use Industry: Food & Beverages, Snacks, Animal Feed, Pharmaceuticals Form: Fresh, Frozen, Dried, Powdered Processing Type: Boiled, Baked, Fried, Dehydrated |
| Companies Covered | Conagra Brands, McCain Foods, Cargill Incorporated, Ingredion Incorporated, Lamb Weston Holdings, Tate & Lyle PLC, General Mills, Archer Daniels Midland Company, Simplot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starchy Roots Market Evolving Landscape
Enzymatic extraction technologies and precision fermentation routes are fragmenting the traditional mechanical processing paradigm. These advances are compressing capital requirements while enabling novel starch functionalities previously inaccessible through conventional methods.
Enzymatic debranching technology is decomposing the long-standing dominance of acid-thinned modified starches in textile sizing and adhesive applications. Specialty chemical manufacturers are adopting these biocatalytic routes to achieve consistent viscosity profiles without corrosive processing conditions. This shift is decomposing the equipment lock-in advantages held by established acid-modification facilities.
REACH deforestation due diligence rules are mandating geolocation verification for all imported root crop shipments entering European processing facilities. Compliance systems must now trace individual batches to specific farm polygons with satellite validation. Starch traders serving EU food and pharmaceutical channels are restructuring supplier contracts to embed traceability costs and liability allocation.
Foodservice operators are consolidating starch procurement through managed ingredient programs that specify functional performance rather than botanical origin. This specification-based buying is compressing traditional commodity trading margins while rewarding processors who can guarantee consistent texturizing behavior across variable raw material inputs. North American quick-service restaurant chains are driving this transition most aggressively.
Starchy Roots Market Segmentation
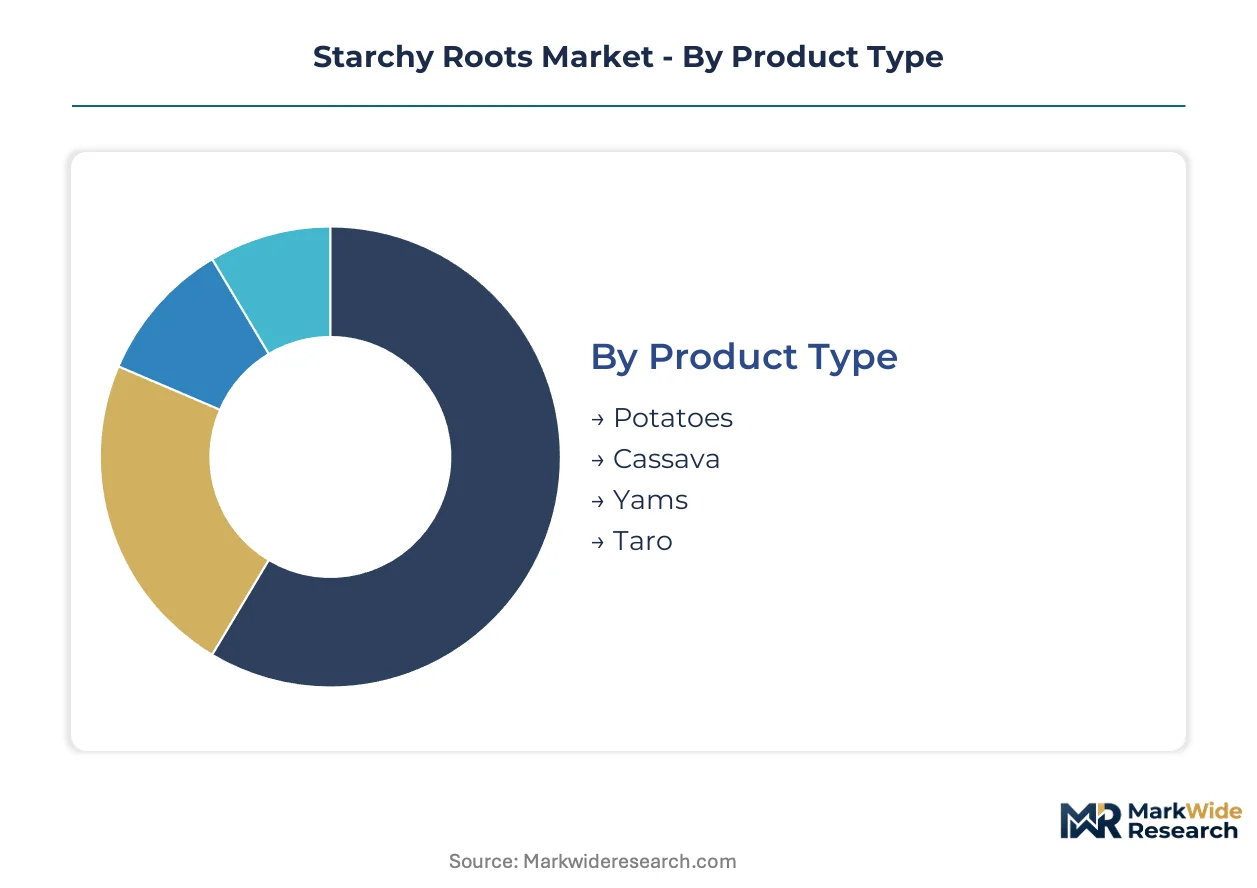
Starchy roots fragment into distinct commercial channels based on perishability, processing investment, and end-use specification intensity. Channel economics dictate margin capture, with fresh-form commodities competing on volume and processed derivatives commanding functional premiums.
Product Type:
Channel flows diverge sharply: fresh tubers serve retail and foodservice directly, while cassava and taro concentrate in industrial starch extraction corridors.
- Potatoes:Amylose content of 20-25% enables versatile texturizing across fry, flake, and modified starch applications. North American frozen fry supply chains anchor volume demand, with Lamb Weston and McCain Foods locking in long-term grower contracts to secure specification-grade tuber supply.
- Cassava:Higher amylopectin ratios (80-85%) deliver superior freeze-thaw stability for clean-label formulations. Southeast Asian processing clusters in Thailand and Vietnam supply pharmaceutical excipient manufacturers displacing corn-derived alternatives.
- Yams:West African and Caribbean supply basins serve diaspora foodservice channels with minimal processing infrastructure.
- Taro:Pacific Island and Hawaiian cultivation supports niche poi and bubble tea ingredient markets with limited scale expansion.
Potatoes dominate installed base. Cassava is where expansion concentrates.
End Use Industry:
Cost tiers separate commodity feed applications from pharmaceutical-grade specifications where contamination control justifies 10-15x price multiples.
- Food & Beverages:Clean-label starch demand is compressing supply chains toward single-origin cassiva sourcing with native, unmodified specifications. Ingredion and Tate & Lyle compete on texturizing functionality for soups, sauces, and bakery applications.
- Snacks:Extruded and sheeted products require specific amylose-amylopectin ratios for expansion control and oil uptake management. Thai processors supply ASEAN-based snack manufacturers with pre-gelatinized starches.
- Animal Feed:Dried cassava chips and potato pulp byproducts compete with grain alternatives on metabolizable energy pricing.
- Pharmaceuticals:Modified cassava starches with specified particle size distributions displace corn alternatives in tablet binding and controlled-release matrices. REACH registration requirements impose 12-18 month supplier qualification timelines.
Food & Beverages commands volume leadership. Pharmaceuticals delivers steepest expansion trajectory.
Form:
Perishability gradients determine logistics infrastructure requirements and geographic reach of each form factor.
- Fresh:Field-to-retail windows of 2-4 weeks constrain sourcing radius to 500km for potatoes, driving regional cultivation patterns around urban consumption centers.
- Frozen:McCain Foods leverages North American processing dominance to par-fry and blast-freeze for quick-service restaurant specifications.
- Dried:Southeast Asian cassava chip exports serve animal feed compounders with 12-month shelf stability enabling intercontinental shipment.
- Powdered:Infant nutrition and modified starch derivatives concentrate value where Ingredion competes on texturizing functionality.
Fresh forms dominate volume throughput. Powdered variants capture margin expansion.
Processing Type:
Capital intensity and energy exposure separate thermal processing methods, with frying and dehydration most vulnerable to natural gas price volatility.
- Boiled:Minimal processing preserves resistant starch content for digestive health positioning in prepared meal applications.
- Baked:Lower oil absorption than frying supports reduced-fat snack positioning with comparable texture outcomes.
- Fried:Par-frying operations at Lamb Weston and McCain facilities anchor North American quick-service restaurant supply chains.
- Dehydrated:Flake and granule production for mashed potato reconstitution and soup thickeners exposes processors to drying energy cost swings.
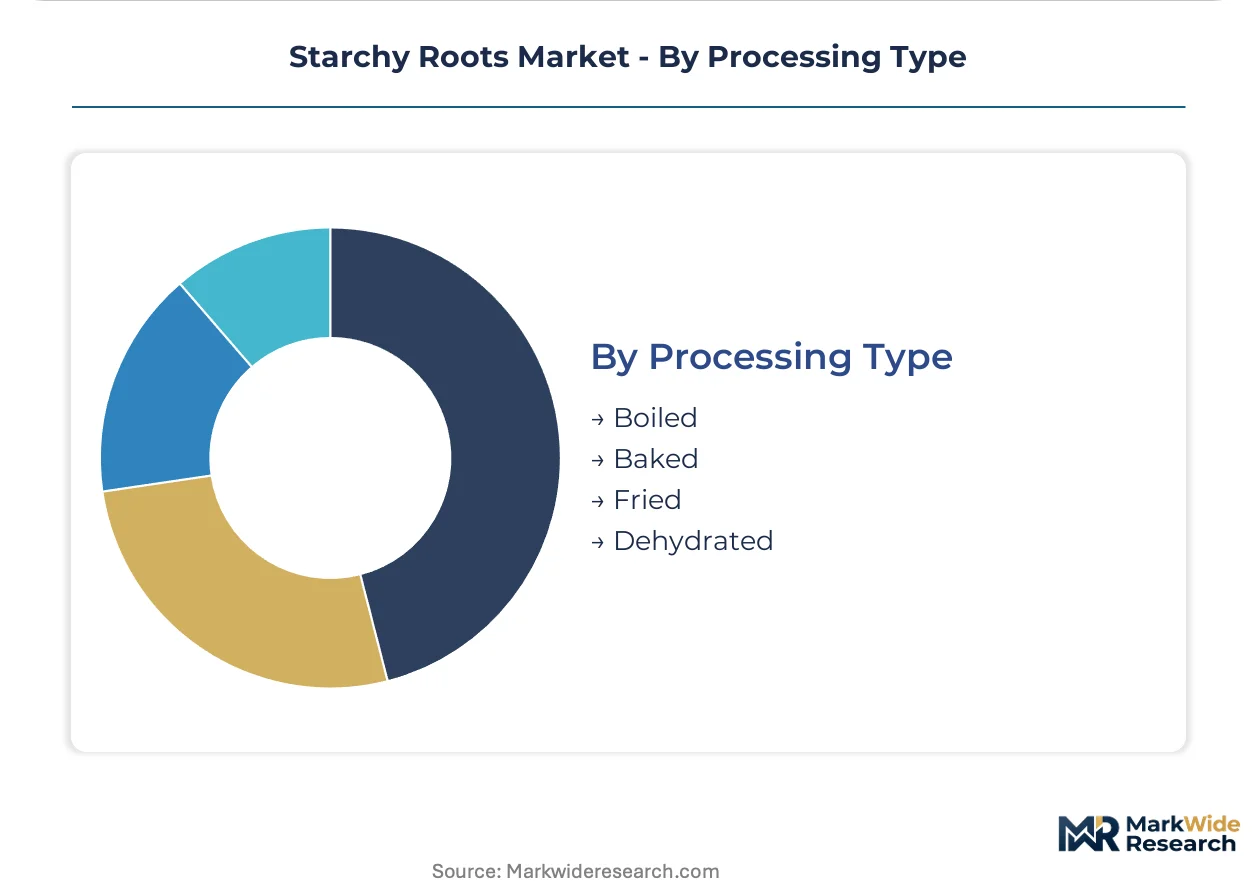
Fried processing anchors foodservice volume. Dehydrated formats are gaining share fastest in retail convenience segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand and Vietnam concentrate Southeast Asian cassava starch processing, while the United States and Germany anchor potato-derived product manufacturing. EU Green Deal residue mandates and FDA adulteration standards reshape import qualification timelines across these supply basins.
United States
Frozen fry demand from quick-service restaurant chains drives contract farming arrangements across Idaho and Washington potato growing regions. FDA 21 CFR standards govern starch adulteration limits and labeling requirements for domestic and imported root crops. McCain Foods and Lamb Weston Holdings operate processing facilities in the Columbia River Basin, locking in long-term grower supply agreements for specification-grade tubers.
Thailand
Pharmaceutical excipient manufacturers source modified cassava starches with defined amylopectin ratios from Thai processing clusters. The country's national food and drug administration enforces mycotoxin limits aligned with export market requirements. Chonburi and Rayong provinces host integrated starch extraction facilities serving Japanese and European tablet binding applications.
Germany
REACH registration requirements and EU Green Deal pesticide residue ceilings filter cassava import flows through Hamburg and Rotterdam port gateways. ECHA documentation burdens extend supplier qualification timelines for modified starch derivatives. Bavarian compounders blend thermoplastic starches with polylactic acid for biodegradable foodservice packaging serving Central European quick-service channels.
Vietnam
Tapioca starch exports to ASEAN snack manufacturers expand processing capacity in Tay Ninh and Binh Phuoc provinces. The Ministry of Agriculture and Rural Development coordinates sustainable farming cluster certification to meet EU deforestation due diligence rules. Mekong Delta drying facilities face margin pressure from natural gas price volatility affecting extraction economics.
India
FSSAI mycotoxin standard enforcement consolidates cassava processing toward integrated facilities with batch-level contamination control. BIS specifications tighten for root crops entering infant nutrition and pharmaceutical channels. Gujarat and Maharashtra starch processors invest in backward integration into captive farming to secure premium-grade raw material supply.
Starchy Roots Market Competitive Landscape
Concentration sits with diversified agribusiness conglomerates and specialized frozen-food processors. The vendor base separates into three tiers: multinational grain-and-root traders with origination networks, frozen-form specialists with foodservice fry specifications, and modified starch manufacturers competing on texturizing functionality. Dominant competitive moves include backward integration into contract farming and capacity expansion in enzymatic extraction technologies.
Among North American frozen-food processors, McCain Foods and Lamb Weston Holdings exemplify scale-driven supply chain control through long-term grower contracting. Cargill Incorporated anchors global trade flows through grain-and-root origination networks spanning multiple continents. Ingredion Incorporated occupies a position within the modified starch tier, competing on texturizing functionality for clean-label formulations.
| Leading Market Players |
|---|
| Conagra Brands |
| McCain Foods |
| Cargill Incorporated |
| Ingredion Incorporated |
| Lamb Weston Holdings |
| Tate & Lyle PLC |
| General Mills |
| Archer Daniels Midland Company |
| Simplot |
| Others |
Value Network & Pricing Analysis
Modified cassava starches displacing corn-derived alternatives in pharmaceutical excipients are simultaneously shifting procurement geography toward Thai and Vietnamese processing clusters and compressing price premiums for traditional corn suppliers. This substitution dynamic concentrates buyer power among excipient manufacturers while exposing starch processors to EU Green Deal residue compliance costs that feed directly into contract pricing.
Pricing Analysis
EU Green Deal pesticide residue mandates dictate the pricing tier structure across imported root crop channels. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered excipient grades from food-service specifications and feed-grade commodities. Cost compression in standard-tier native starches is intensifying because clean-label CPG manufacturers are consolidating volumes through managed ingredient programs. Animal feed compounders exhibit highest price sensitivity due to metabolizable energy substitution elasticity, while pharmaceutical tablet binders accept steep premiums for batch-level contamination documentation.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam gateways is extending lead times for cassava starch shipments entering German pharmaceutical processing facilities. Supply concentrates in Thailand, Vietnam, and India, with raw material flows drawing from Mekong Delta cultivation belts, Tay Ninh drying facilities, and Gujarat integrated processing complexes. Natural gas price volatility poses structural risk to extraction economics across Southeast Asian facilities. Distribution runs through frozen-form specialists for quick-service restaurant channels and bulk powder traders serving infant nutrition compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label starch demand fragmentation is creating specialized procurement niches that favor processors with single-origin certification capabilities over commodity traders. This demand-side shift rewards geographic and functional specialization across pharmaceutical, foodservice, and industrial channels.
For Market Incumbents: Shield long-term contract farming arrangements in Idaho and Washington potato regions from enzymatic extraction technology disruption by accelerating captive investment in biocatalytic processing lines. Secure REACH registration portfolios ahead of 2026 carbon border implementation to lock in European pharmaceutical channel access against emerging Thai competitors.
For New Entrants and Emerging Players: Lead with biodegradable thermoplastic starch blends for Central European foodservice packaging, where compostability certification commands immediate price premiums over conventional polystyrene. Target Bavarian compounders and quick-service restaurant supply chains with documented deforestation-free sourcing as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated cassava processors with backward control over Mekong Delta farming clusters and established EU pharmaceutical customer relationships. The long-term viability window favors facilities with batch-level mycotoxin testing infrastructure. Watch for FSSAI enforcement intensity in India as the signal indicating consolidation acceleration toward integrated processing models.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | McCain Foods locks Idaho grower supply for specification-grade frozen fry output. |
| Enzymatic Extraction Technology Adoption | Specialty chemical manufacturers bypass acid-modification equipment lock-in through biocatalytic routes. |
| REACH Registration Portfolio Expansion | Starch traders embed 12-18 month supplier qualification timelines into contract structures. |
| Biogenic Content Verification Systems | Early adopters document deforestation-free sourcing ahead of EU carbon border adjustments. |
| Managed Ingredient Program Participation | North American quick-service chains consolidate procurement through performance-based specifications. |
Research Methodology
The analysis maps fresh tuber, dried chip, and modified starch derivative channels, each validated through procurement directors at CPG manufacturers, pharmaceutical excipient buyers, and starch processing plant managers. Primary interviews with supply chain planners at frozen-food processors and regulatory affairs leads at ingredient suppliers combined with secondary validation through FDA 21 CFR filings, EU REACH registration databases, FSSAI standard notifications, and trade flow customs records. Bottom-up volume estimates from individual facility capacities triangulate against top-down demand projections from end-use consumption patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, processing investment intensity, end-use specification tier, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from trend extrapolation of clean-label substitution rates, energy cost pass-through coefficients, and pharmaceutical excipient displacement patterns. Forecast inputs include natural gas price sensitivity for drying economics and monsoon-driven harvest variability coefficients for Southeast Asian supply basins.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity, stable ASEAN trade lane access, and continued pharmaceutical excipient specification shifts would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation timelines and energy cost trajectories. Specific risks that could revise projections include abrupt FSSAI standard tightening, REACH documentation burden expansion, or breakthrough precision fermentation routes displacing mechanical extraction entirely. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Asia-Pacific Sweet Potatoes Market
Fruits and Vegetables
Global Bean Sprouts Market
Fruits and Vegetables
Fermented Cucumber Market
Fruits and Vegetables
Canada Fruits and Vegetables Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
Coconut Products Market
Fruits and Vegetables
Europe Canned Fruits Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Global Dehydrated Onion Flakes Market