
 South America Lime Market | 2026-2036
South America Lime Market Size, Share, and Industry Trends Forecast 2026-2036
South America Lime Market Analytics
Buyer concentration among beverage producers is rebalancing as multinational soft-drink bottlers consolidate procurement while craft distilleries fragment demand across smaller batches. Carmeuse leverages its bulk logistics network to serve industrial chemical buyers in southeastern Brazil. Lhoist Group anchors regional supply through its calcination facilities tailored to metallurgical lime specifications. Graymont Limited competes on maritime export routes linking Argentine quarries to Chilean copper smelters.
Lime denotes citrus fruit from Citrus aurantiifolia and Citrus latifolia species, containing citric acid concentrations of approximately 6-8% by weight, harvested green for acid profile retention and processed into juice, essential oil, or dehydrated forms for pH regulation and flavoring. Fresh lime commands the largest revenue pool among product types due to perishable supply chains and retail premiumization, while lime powder represents the fastest-expanding category as food manufacturers seek extended-shelf-life inputs. Application demand concentrates in beverage processing, where lime juice functions as a natural acidulant and flavor base, though agriculture is gaining traction for soil pH amendment in Brazil's cerrado expansion zones.
ANVISA governs pesticide residue thresholds and food additive classifications for lime-derived products entering Brazilian retail channels, while Argentina's national agricultural sanitation regulator enforces cold-chain documentation for cross-border fresh fruit shipments. The EU Green Deal's deforestation-free supply chain requirements are reshaping export eligibility criteria for South American lime processors serving European food manufacturers. Stakeholders must monitor how forthcoming MERCOSUR harmonization protocols affect cross-border phytosanitary certification burdens.
Market Dynamics
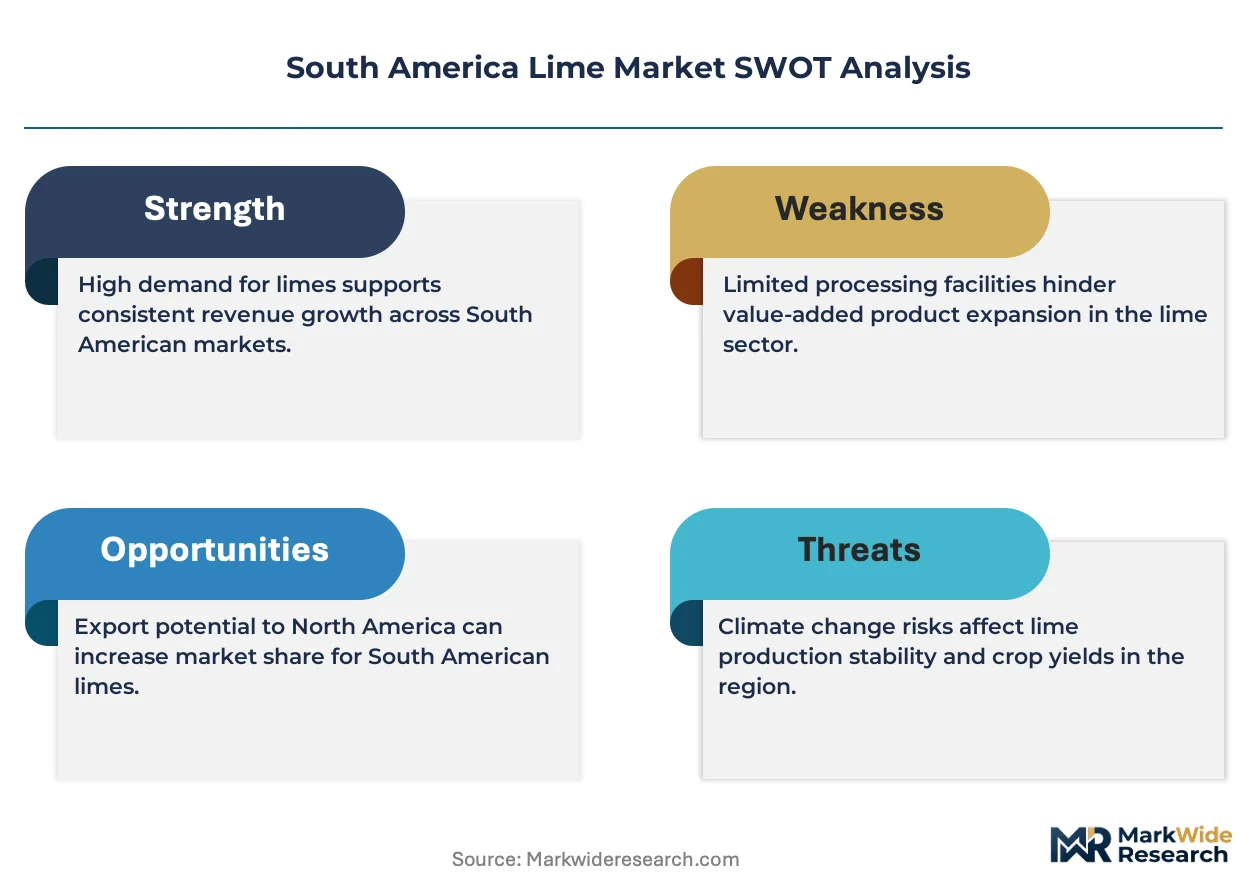
Beverage producers in Brazil and Argentina are consolidating procurement volumes while ANVISA's updated post-harvest protocols force processors to retool treatment infrastructure, compressing margins for non-compliant suppliers.
Growth Catalysts
- ANVISA Sanitation Mandates:Brazil's revised agricultural protocols are accelerating cold-chain infrastructure deployment among citrus cooperatives serving São Paulo's processing corridor.
- Soil Amendment Demand:Brazil's cerrado agricultural expansion zones are driving lime powder consumption for pH correction in soybean and corn cultivation systems.
- Essential Oil Extraction:Steam distillation technology upgrades at Argentine processing facilities are expanding high-margin terpene output for pharmaceutical and cosmetic formulators.
Market Restraints
- Input Cost Volatility:Natural gas prices for calcination operations fluctuate with Argentine pipeline supply constraints, squeezing metallurgical lime margins.
- Supply Concentration Risk:São Paulo state's processing corridor dominates fresh lime supply, creating single-point vulnerability for Brazilian beverage manufacturers.
- Substitution Threat:Citric acid from Brazilian corn-based fermentation facilities competes with lime-derived acidulants in cost-sensitive industrial applications.
Strategic Opportunities
- EU Green Deal Alignment:Deforestation-free supply chain certification opens premium export channels for Argentine lime processors serving European food manufacturers.
- Colombian Market Entry:Underdeveloped fresh lime distribution networks in Bogotá and Medellín present first-mover advantages for Brazilian exporters with cold-chain capabilities.
- Biostimulant Convergence:Integration of lime-derived calcium formulations with microbial inoculants targets precision agriculture adoption in Brazil's Mato Grosso farming belt.
Industry Challenges
- Phytosanitary Certification Complexity:Pending MERCOSUR harmonization protocols create uncertainty for cross-border fresh fruit documentation between Brazil, Argentina, and Paraguay.
- Processing Equipment Capex:ANVISA-mandated post-harvest treatment systems require seven-figure investments that smaller citrus cooperatives cannot access without cooperative financing structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Lime Market |
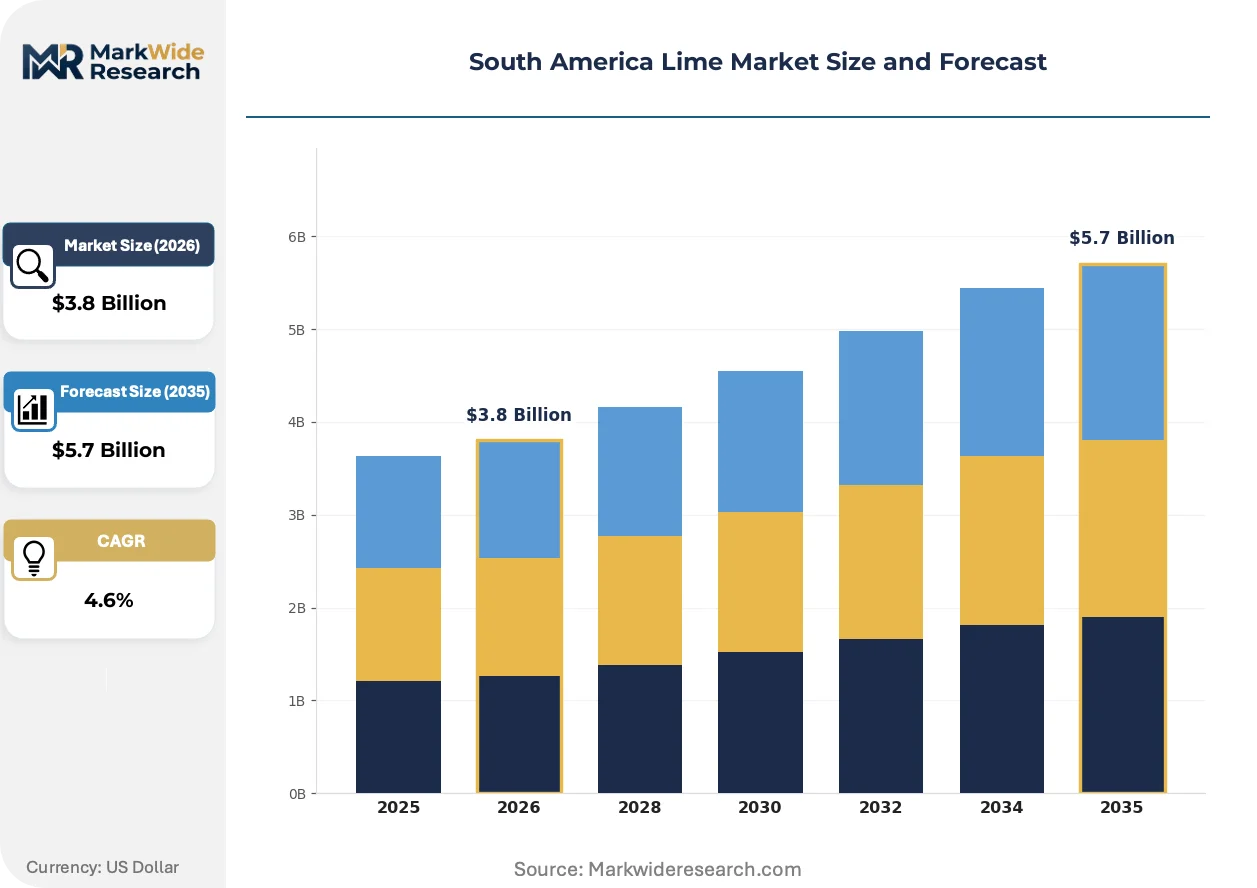
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
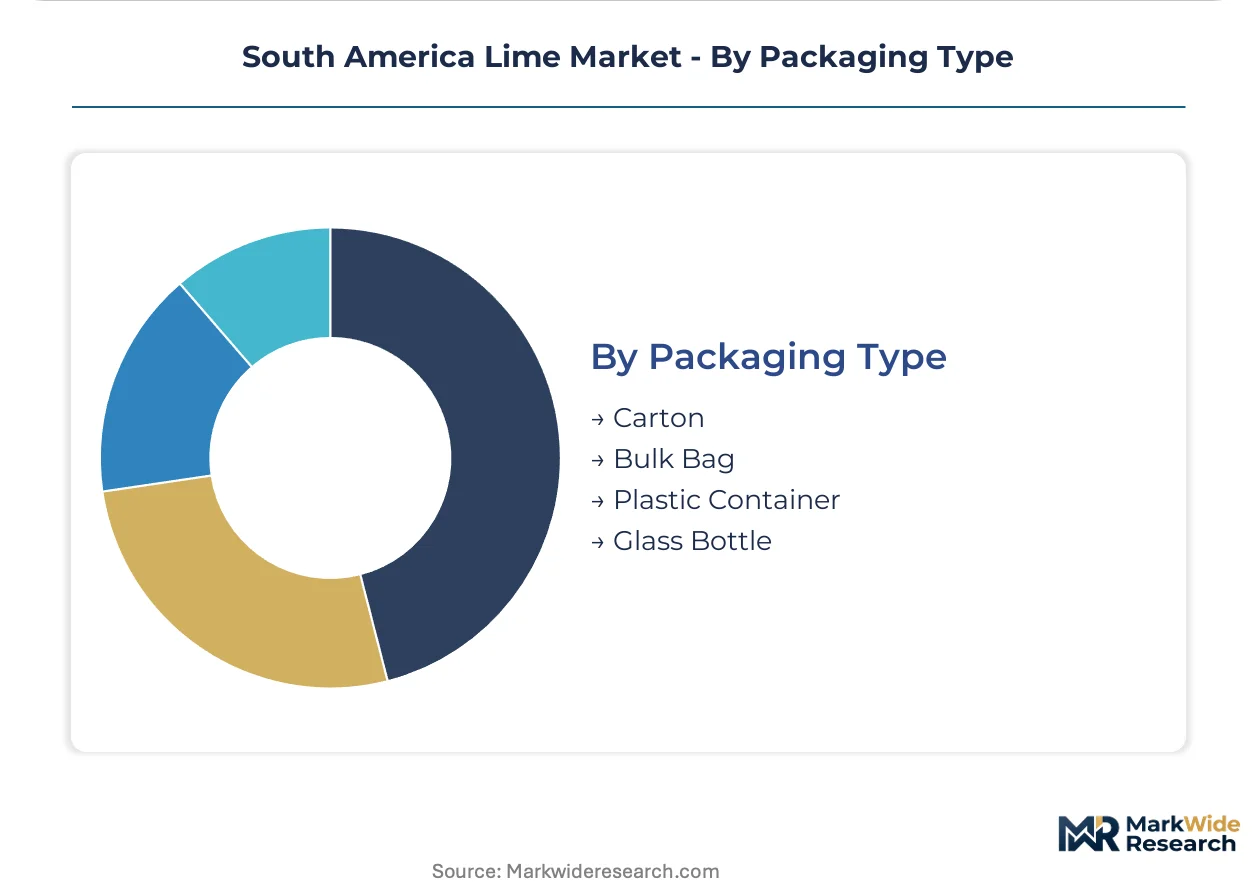
| Segmentation | Product Type: Fresh Lime, Dried Lime, Lime Juice, Lime Powder Application: Beverage, Food Processing, Agriculture, Chemical Industry End User: Retailers, Food Manufacturers, Farmers, Beverage Producers Packaging Type: Carton, Bulk Bag, Plastic Container, Glass Bottle |
| Companies Covered | Brazil Lime Producers (Collective), Argentina Lime Exporters (Collective), Carmeuse, Lhoist Group, Graymont Limited, Afrimat, United States Lime & Minerals, Inc., Minerals Technologies, Inc., Goldenberry Farms, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Lime Market Evolving Landscape
Processing technology and regulatory compliance requirements are restructuring competitive advantage across South American lime supply chains, favoring operators with integrated quality assurance and export certification capabilities.
Pulsed electric field pasteurization is overtaking thermal processing for lime juice concentrate production. Brazilian beverage bottlers in Minas Gerais are adopting PEF systems to preserve volatile aromatic compounds while extending shelf life. This technology is overtaking conventional heat treatment by eliminating thermal degradation losses that previously constrained premium juice pricing.
Argentina's national agricultural sanitation regulator is tightening cold-chain documentation requirements for cross-border fresh fruit shipments. Exporters must now deploy blockchain-traceable temperature logging from harvest through port departure. Fresh lime consignments to Chilean retail channels face the steepest compliance burden due to Andean transit duration.
Buyer consolidation among multinational soft-drink bottlers is fragmenting procurement into tiered supplier categories. Craft distilleries across Buenos Aires and Córdoba provinces now source through regional citrus cooperatives rather than direct plantation contracts. This pattern concentrates price negotiation leverage with beverage conglomerates while dispersing volume commitments across smaller agricultural units.
South America Lime Market Segmentation
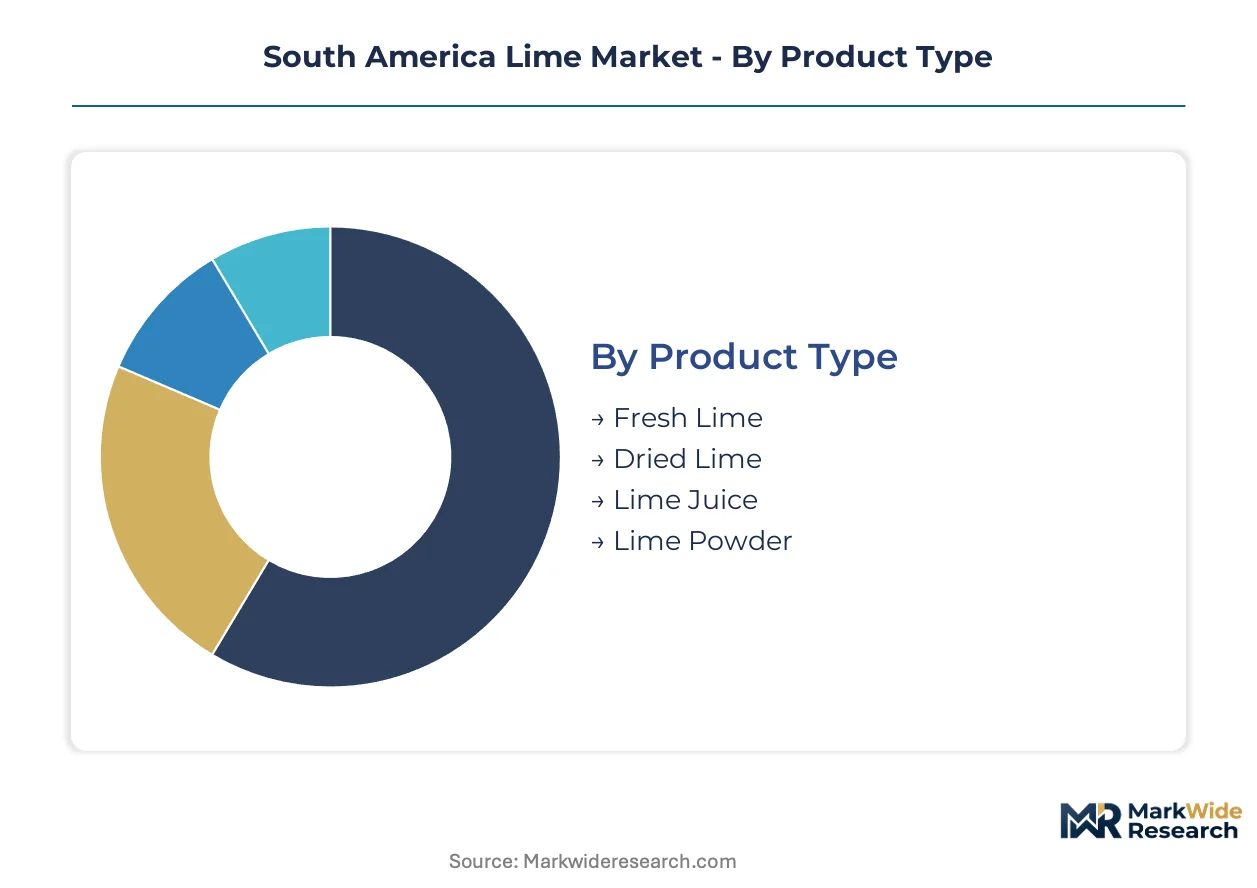
Segmentation in the South America lime market reveals how regulatory thresholds and supply chain configurations fragment commercial opportunity across distinct product formats and buyer categories. Understanding these divisions exposes where ANVISA compliance costs concentrate and which packaging and application combinations unlock premium positioning.
Product Type:
ANVISA pesticide residue thresholds apply differentially across these categories, with fresh lime facing the strictest pre-shipment inspection protocols while processed derivatives navigate additive classification rules.
- Fresh Lime:Harvested green from Citrus aurantiifolia and Citrus latifolia species at 6-8% citric acid concentration, this segment commands the largest revenue pool due to perishable supply chains requiring cold-chain documentation for cross-border movement. São Paulo state's processing corridor dominates procurement concentration for Brazilian beverage manufacturers.
- Lime Powder:Dehydrated forms with extended shelf-life properties represent the fastest-expanding category as food manufacturers seek pH regulation inputs that bypass fresh fruit spoilage constraints. Brazil's cerrado agricultural expansion zones are driving consumption for soil pH amendment in soybean and corn cultivation systems.
- Lime Juice:Concentrated and single-strength formulations serve acidulant and flavor base functions, with pulsed electric field pasteurization technology overtaking thermal processing among Minas Gerais bottlers.
- Dried Lime:Whole and sliced dehydrated fruit targets ethnic food channels and specialty beverage applications with lower volume throughput than juice or powder derivatives.
Leading the category by volume: Fresh Lime. Growing fastest: Lime Powder.
Application:
Cost tier differentiation separates commodity acidulant buyers from premium natural ingredient seekers across these four demand centers.
- Beverage:Natural acidulant and flavor base functions concentrate demand among multinational soft-drink bottlers consolidating procurement volumes while craft distilleries fragment demand across smaller batches. PEF pasteurization adoption in Minas Gerais preserves volatile aromatic compounds for premium juice pricing.
- Agriculture:Soil pH amendment applications in Brazil's cerrado expansion zones and Mato Grosso farming belt are gaining traction as precision agriculture adoption accelerates lime-derived calcium formulation demand.
- Food Processing:pH regulation and flavoring applications span preserved foods, confectionery, and sauces with mid-tier pricing sensitivity relative to beverage premiumization.
- Chemical Industry:Metallurgical lime specifications for Argentine quarries and Chilean copper smelters compete with citric acid from Brazilian corn-based fermentation facilities in cost-sensitive industrial applications.
Volume concentration: Beverage. Steepest expansion trajectory: Agriculture.
End User:
Customer type determines procurement scale and certification burden intensity, from retail traceability requirements to industrial volume commitments.
- Beverage Producers:Multinational bottlers wield tiered supplier category leverage while regional craft distilleries source through citrus cooperatives in Buenos Aires and Córdoba provinces.
- Food Manufacturers:EU Green Deal deforestation-free supply chain requirements reshape export eligibility criteria for processors serving European channels.
- Farmers:Direct procurement of lime powder for soil amendment concentrates in Brazil's Mato Grosso and cerrado zones with cooperative financing structures.
- Retailers:Fresh lime distribution networks in Bogotá and Medellín remain underdeveloped, presenting cold-chain capability advantages for Brazilian exporters.
Procurement scale leader: Beverage Producers. Fastest channel development: Retailers.
Packaging Type:
Supply concentration in São Paulo's processing corridor dictates packaging format availability for industrial versus retail channels.
- Bulk Bag:Industrial-scale lime powder and dried lime shipments for agricultural and chemical buyers dominate volume throughput with lowest unit packaging cost.
- Carton:Fresh lime retail distribution standard with cold-chain documentation requirements tightening under Argentina's national agricultural sanitation regulator for cross-border shipments.
- Plastic Container:Juice concentrate and essential oil extraction outputs for pharmaceutical and cosmetic formulators with intermediate shelf-life requirements.
- Glass Bottle:Premium juice and essential oil positioning for export channels with blockchain-traceable temperature logging mandates for Andean transit duration compliance.
Volume dominance: Bulk Bag. Premium positioning: Glass Bottle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's citrus belt anchors South American lime production, with calcination facilities and juice processing corridors clustering along southeastern Brazil's logistics spine.
Brazil
Beverage bottlers in Minas Gerais and São Paulo are consolidating procurement volumes for lime juice concentrate. ANVISA's updated agricultural sanitation protocols mandate cold-chain infrastructure upgrades across citrus cooperatives. São Paulo's processing corridor dominates fresh lime supply, creating single-point vulnerability for industrial buyers.
Argentina
Craft distilleries in Buenos Aires and Córdoba provinces fragment demand across smaller batches through regional citrus cooperatives. The national agricultural sanitation regulator enforces blockchain-traceable temperature logging for cross-border fresh fruit shipments. Argentine processing facilities are upgrading steam distillation technology for high-margin terpene extraction.
Chile
Copper smelters in northern mining districts drive metallurgical lime consumption from Argentine quarry imports. Maritime export routes linking Argentine suppliers to Chilean industrial buyers compete on logistics efficiency. Fresh lime consignments face steep compliance burdens due to Andean transit duration requirements.
Colombia
Underdeveloped fresh lime distribution networks in Bogotá and Medellín present cold-chain capability gaps for regional suppliers. Brazilian exporters with established logistics infrastructure are targeting first-mover advantages in urban retail channels. Domestic agricultural expansion in the Andean highlands is creating new soil amendment demand for lime powder.
Paraguay
Cross-border fresh fruit documentation complexity under pending MERCOSUR harmonization protocols creates regulatory uncertainty for Brazilian-Paraguayan trade corridors. Citrus cooperatives in the border region are investing in phytosanitary certification infrastructure to maintain market access. Processing equipment financing remains constrained for smaller agricultural units.
South America Lime Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty acidulant and biostimulant convergence opportunities. The market structures around three player tiers: multinational chemical conglomerates with calcination assets, regional citrus cooperatives serving beverage processors, and agricultural distributors targeting soil amendment demand. Strategic archetypes include bulk logistics operators, essential oil extraction specialists, and precision agriculture formulation developers. Dominant competitive moves center on cold-chain infrastructure deployment and EU Green Deal certification acquisition.
Within the industrial chemical tier, Carmeuse leverages its bulk logistics network to serve southeastern Brazilian metallurgical buyers, while Lhoist Group anchors regional supply through calcination facilities. Graymont Limited occupies a position on maritime export routes linking Argentine quarries to Chilean copper smelters. These three exemplify how geographic positioning and logistics integration determine competitive advantage in cross-border lime supply.
| Leading Market Players |
|---|
| Brazil Lime Producers (Collective) |
| Argentina Lime Exporters (Collective) |
| Carmeuse |
| Lhoist Group |
| Graymont Limited |
| Afrimat |
| United States Lime & Minerals, Inc. |
| Minerals Technologies, Inc. |
| Goldenberry Farms |
| Others |
Value Network & Pricing Analysis
Pulsed electric field pasteurization adoption among Minas Gerais beverage bottlers simultaneously compresses processing costs and concentrates procurement leverage with technology-enabled suppliers. This production-method transition rewards operators with cold-chain certification capabilities while marginalizing conventional thermal processors unable to fund ANVISA-mandated infrastructure upgrades.
Pricing Analysis
Warranty and service bundling separates premium juice concentrate suppliers from commodity acidulant traders in Brazilian procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects ANVISA compliance certification, volume scale commitments, and cold-chain documentation completeness. Cost compression in economy-tier lime powder intensifies because corn-derived citric acid from Brazilian fermentation facilities undercuts natural acidulant pricing. Craft distilleries in Buenos Aires and Córdoba provinces exhibit highest price sensitivity, while multinational soft-drink bottlers prioritize supply security over unit cost minimization.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-compromised fresh lime consignments remains underdeveloped across Andean transit corridors, forcing Argentine exporters to absorb spoilage losses rather than recapture value through secondary processing. Supply concentrates in São Paulo state's processing corridor, Argentina's citrus cooperatives, and Colombian distribution networks. Raw material flows draw from natural gas for calcination operations, citrus biomass for essential oil extraction, and limestone deposits for metallurgical grade production. Single-source vulnerability in São Paulo's processing corridor threatens Brazilian beverage manufacturers with supply interruption. Distribution runs through maritime export routes linking Argentine quarries to Chilean copper smelters and cold-chain corridors serving urban retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America lime market functions as a supply-constrained environment where São Paulo's processing corridor dominance props pricing power for compliant operators. Cold-chain infrastructure bottlenecks prevent rapid capacity expansion, sustaining margin premiums for certified suppliers.
For Market Incumbents: Anticipate consolidation pressure from multinational soft-drink bottlers consolidating procurement volumes into tiered supplier categories. Defensive positioning requires backward integration into citrus cooperative equity stakes and accelerated EU Green Deal deforestation-free certification acquisition. Carmeuse and Lhoist Group calcination assets face margin compression from Argentine natural gas pipeline supply constraints.
For New Entrants and Emerging Players: Begin with underdeveloped fresh lime distribution networks in Bogotá and Medellín, where cold-chain capability gaps create first-mover advantages for Brazilian exporters with established logistics infrastructure. Target lime-derived calcium biostimulant formulations for Brazil's Mato Grosso precision agriculture belt. Go-to-market execution should leverage cooperative financing structures to overcome ANVISA-mandated processing equipment capex barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational chemical conglomerates seeking calcination asset consolidation or beverage bottlers pursuing backward integration into citrus supply security. Long-term viability favors operators with integrated quality assurance and export certification capabilities spanning the analysis window. Monitor ANVISA harmonization with pending MERCOSUR protocols as the critical inflection signal for cross-border fresh fruit documentation burden reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Deployment | ANVISA compliance mandates seven-figure investments that separate certified suppliers from marginal operators. |
| EU Green Deal Certification Acquisition | Deforestation-free supply chain credentials unlock premium export channels for Argentine processors serving European food manufacturers. |
| Essential Oil Extraction Capacity Expansion | Steam distillation technology upgrades at Argentine facilities expand high-margin terpene output for pharmaceutical formulators. |
| Biostimulant Formulation Development | Lime-derived calcium integration with microbial inoculants targets precision agriculture adoption in Brazil's Mato Grosso farming belt. |
| Colombian Market Entry Partnership | Joint ventures with regional distributors overcome underdeveloped fresh lime networks in Bogotá and Medellín urban channels. |
Research Methodology
Multi-period observation of citrus cooperative procurement volumes, ANVISA compliance certification rates, and cold-chain infrastructure deployment anchored the trend analysis, supplemented by interviews with beverage procurement directors, citrus cooperative managers, ANVISA regulatory affairs specialists, and metallurgical lime plant engineers. Secondary validation drew from Brazilian agricultural sanitation protocol filings, Argentine national agricultural sanitation regulator cold-chain documentation requirements, EU Green Deal implementation guidance, and MERCOSUR harmonization protocol drafts. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches applied differential growth assumptions by product type, with fresh lime, lime powder, lime juice, and dried lime categories modeled separately. Application segmentation across beverage, agriculture, food processing, and chemical industry end-uses incorporated ANVISA pesticide residue threshold enforcement intensity and soil amendment demand trajectories in Brazil's cerrado expansion zones. CAGRs were derived from regression analysis of historical procurement patterns projected through the modeling period.
Underlying measurement precision varies by segment; lime powder and metallurgical lime categories carry tighter precision than fresh lime perishable supply chains subject to weather and spoilage volatility. Forecasts reflect assumptions about ANVISA enforcement continuity, natural gas pipeline supply stability, and MERCOSUR harmonization timeline progression. Practitioners should monitor ANVISA protocol amendment announcements, Argentine energy infrastructure investment disclosures, and EU Green Deal certification requirement updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Yacon Fruit Extract Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Rosehip Market
Fruits and Vegetables
Noni Fruit Powder Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Venezuela Fruits and Vegetable Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
Spain Tropical Fruits Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market