
 Global Jalapeno Pepper Market | 2026-2036
Global Jalapeno Pepper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Jalapeno Pepper Market Foresight
Seasonal agricultural labor availability is bifurcating the Global Jalapeno Pepper Market into mechanized large-scale operations and hand-harvest dependent specialty growers. Nature's Produce leverages vertical integration from field to retail packaging across California's Central Valley. Syngenta Crop Protection AG anchors its position through proprietary seed genetics and crop protection bundles. Olam Spices competes on dried and processed jalapeno volumes with sourcing networks spanning multiple hemispheres.
Jalapeno pepper denotes a medium-sized chili cultivar of the species Capsicum annuum, typically measuring 5,000 to 15,000 Scoville Heat Units, with thick flesh suited for fresh consumption, smoking, drying, and industrial processing into sauces and powders. Fresh Jalapeno commands the largest volume share in retail and foodservice channels, though Jalapeno Sauce generates disproportionate margin capture through branded value addition. Dried Jalapeno and Jalapeno Powder occupy niche but expanding positions within spice manufacturing and craft hot sauce formulation, where concentrated flavor and extended shelf life reduce per-unit logistics costs.
The USDA's Agricultural Marketing Service grading standards and FDA's Food Safety Modernization Act requirements shape domestic market access, while Mexico's SENASICA phytosanitary protocols govern cross-border fresh shipments. EU REACH chemical residue thresholds and evolving EFSA capsicum extract specifications influence export-oriented processing investments. Stakeholders must monitor labor automation economics against heritage cultivar premiums as climate variability shifts viable growing geographies.
Market Dynamics
Mechanical harvesting economics are bifurcating the Global Jalapeno Pepper Market into capital-intensive automated operations and labor-dependent heritage cultivar specialists, with FSMA compliance costs accelerating this structural divide.
Growth Catalysts
- FDA Food Safety Modernization Act:Mandatory preventive controls are consolidating processing capacity toward HACCP-certified facilities, squeezing out informal suppliers and concentrating procurement among verified growers.
- Hot sauce manufacturing:Craft and industrial sauce producers in Mexico's Chihuahua belt are expanding contracted acreage for specific Scoville-tuned varietals, pulling premium fresh volumes from spot markets.
- Precision irrigation:Drip and sensor-managed water systems in California's Central Valley are stabilizing yield variance, reducing weather-driven supply shocks that historically disrupted processor planning cycles.
Market Restraints
- Seasonal labor dependency:Hand-harvest requirements for premium-grade jalapenos tie production costs to H-2A visa availability and cross-border worker mobility, creating margin volatility processors cannot hedge.
- Input cost concentration:Phosphate-based fertilizer pricing and glyphosate regulatory pressure in key growing belts are compressing returns for mid-scale operators lacking backward integration into input supply.
- Substitution elasticity:Serrano and habanero peppers offer comparable Scoville profiles at lower procurement costs for industrial sauce formulations, capping price premiums jalapeno contracts can command.
Strategic Opportunities
- EU organic import channels:REACH-compliant residue thresholds and EFSA capsicum extract specifications are creating first-mover advantages for Mexican growers achieving EU organic equivalence ahead of domestic competitors.
- Smoked chipotle verticals:Post-harvest smoking and drying infrastructure investments are capturing margin upstream from sauce manufacturers, converting perishable fresh supply into shelf-stable intermediate products.
- Direct-to-foodservice distribution:Bypassing traditional wholesale produce terminals through contracted cold-chain delivery is enabling Scoville-grade specificity and harvest-date traceability for restaurant chain procurement.
Industry Challenges
- Organic certification timelines:USDA organic transition periods and SENASICA phytosanitary documentation create 24-36 month revenue gaps for growers converting conventional acreage, straining working capital.
- Genetic IP fragmentation:Proprietary hybrid seed licensing from Syngenta and competing breeders fragments varietal standardization, complicating processor efforts to lock consistent heat profiles across multi-source supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Jalapeno Pepper Market |
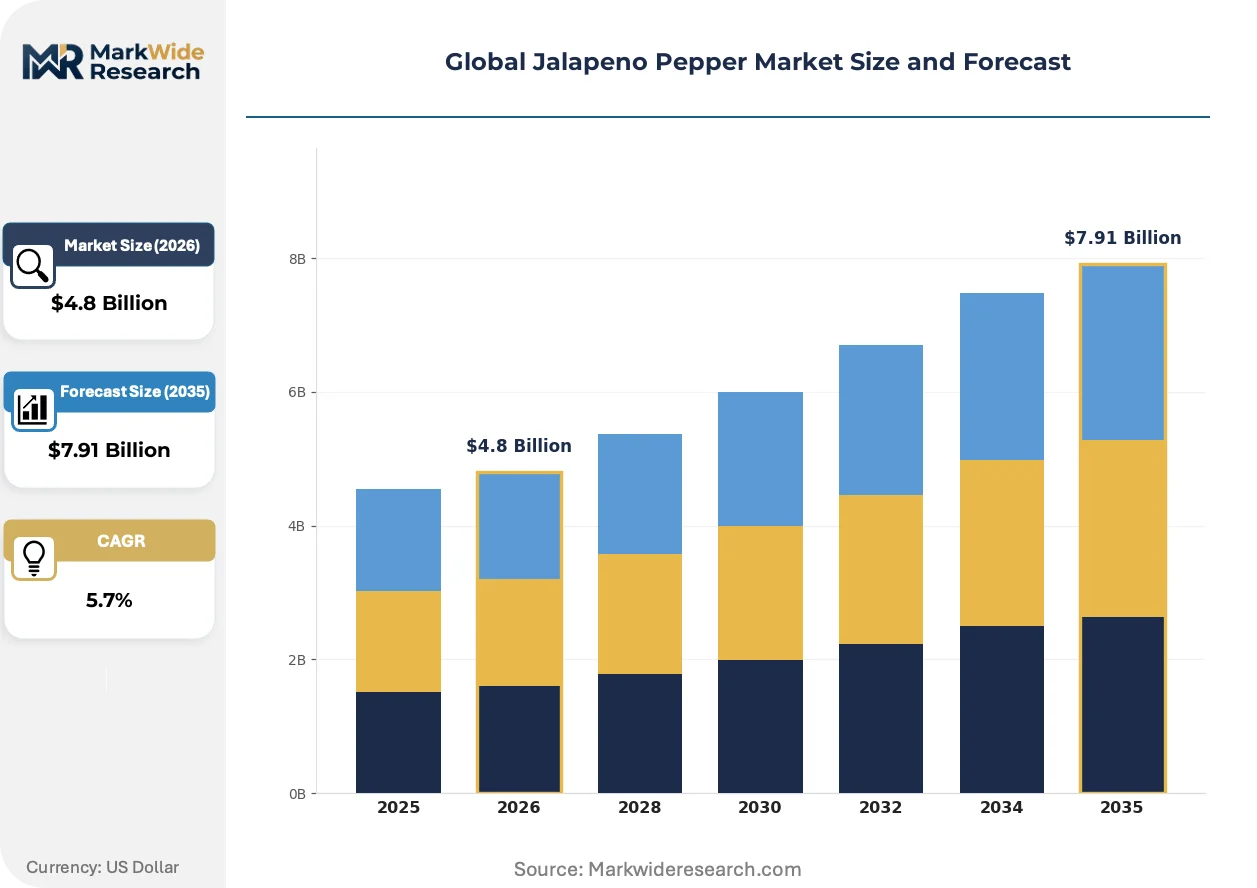
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Jalapeno, Pickled Jalapeno, Dried Jalapeno, Jalapeno Sauce, Jalapeno Powder Application: Foodservice, Household Cooking, Processed Foods, Condiments, Food Manufacturing Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Wholesale Markets, Farmers Markets Customer Type: Food Distributors, Hot Sauce Producers, Retail Bakers, Frozen Food Manufacturers, Culinary Schools |
| Companies Covered | Nature's Produce, Baloian Packing Co. Inc., L & M Companies, Syngenta Crop Protection AG, Olam Spices, Can-Am Pepper Company Ltd, Watts Farm, Bayer AG, Global Green Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Jalapeno Pepper Market Shifts & Advancements
Automation, regulatory harmonization, and procurement specificity are converging to reshape how jalapeno volumes move from field to formulation, with technology and policy acting as dual levers of competitive differentiation.
Robotic selective harvesting is decomposing the traditional labor-cost advantage of Mexican growing regions. California operators are deploying computer-vision-guided mechanical pickers that grade fruit by size and color in real time. This technology is compressing the wage differential between US and Mexican production, enabling domestic scale economics previously unattainable.
EU REACH chemical residue thresholds are forcing reformulation of crop protection protocols across export-oriented processing facilities. Maximum residue limits for organophosphates and pyrethroids now determine which harvest lots qualify for EU-bound dried and powdered products. Mexican processors are responding by segregating spray records and harvest zones to maintain parallel compliance tracks for domestic and European channels.
Restaurant chain procurement departments are mandating harvest-lot traceability and Scoville certification as standard contract terms. This specification intensity is displacing commodity spot purchasing through produce terminals. The shift is most visible in southwestern US foodservice markets, where Chipotle-grade heat consistency has become a procurement non-negotiable.
Global Jalapeno Pepper Market Segmentation
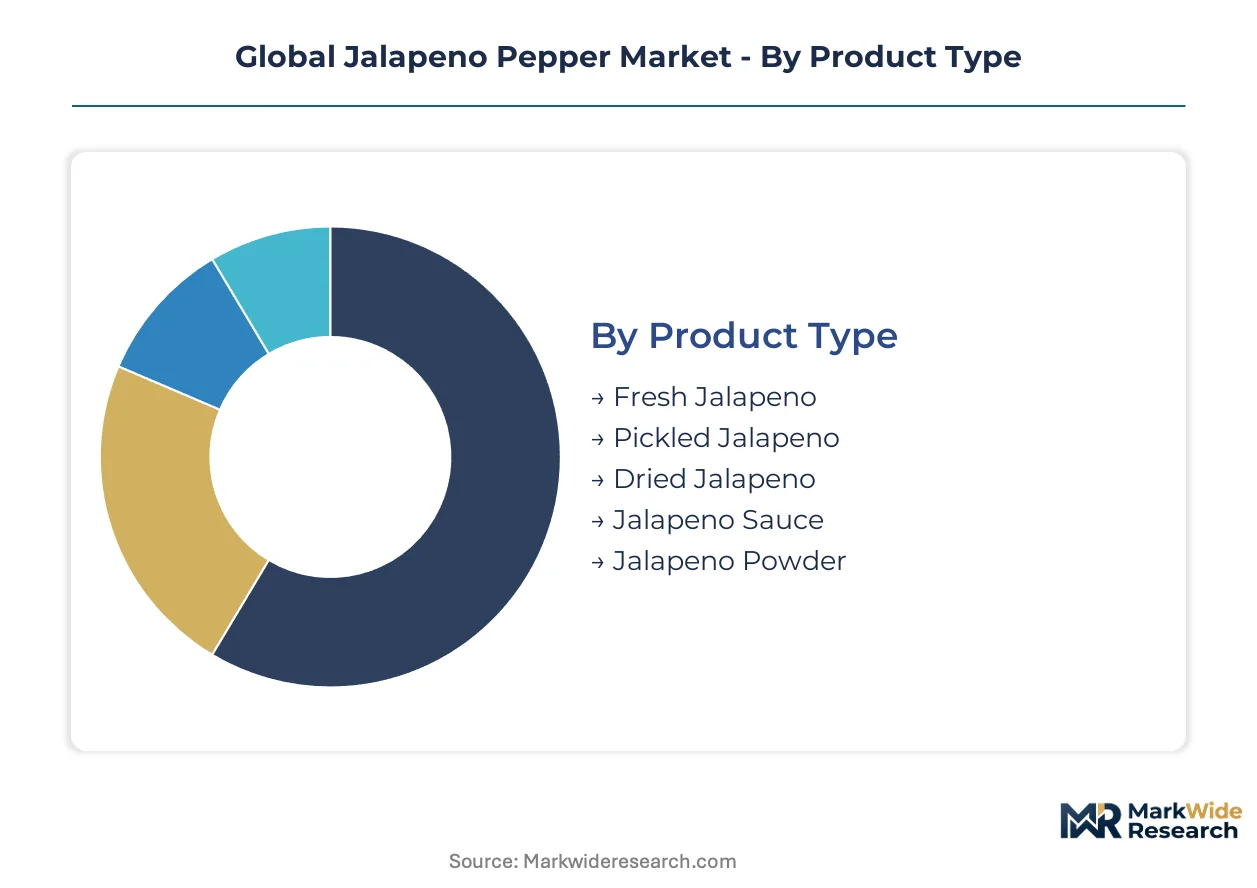
Jalapeno pepper value flows through distinct channels where perishability, processing intensity, and end-use specificity determine margin capture. Understanding how product forms, applications, and customer types concentrate purchasing power enables targeted capacity investments and contract positioning.
Product Type:
Margin pools concentrate upstream in value-added processing and downstream in branded retail, with raw commodity forms serving as volume anchors rather than profit centers.
- Fresh Jalapeno:Thick-walled pods harvested at mature green or red stages retain 5,000-15,000 Scoville Heat Units with minimal post-harvest handling. Restaurant chains in the southwestern United States and Mexico's Chihuahua belt are contracting specific harvest dates and heat profiles, bypassing terminal markets for direct cold-chain delivery. Labor costs and perishability compress margins despite commanding the largest volume position.
- Jalapeno Sauce:Fermented or vinegar-based formulations with extended shelf life capture disproportionate margin through branded value addition. Craft and industrial producers in Mexico and Texas are pulling premium fresh volumes from spot markets to secure consistent Scoville-tuned inputs for signature heat profiles.
- Pickled Jalapeno:Brine-preserved rings and slices serve nacho cheese dispensers and sandwich chains requiring uniform heat distribution. Mexican processors dominate this intermediate category through captive supply relationships with quick-service restaurants.
- Dried Jalapeno:Dehydrated whole pods or flakes concentrate flavor for spice manufacturing and craft hot sauce formulation. Extended shelf life reduces per-unit logistics costs for export-oriented processors meeting EU REACH residue thresholds.
- Jalapeno Powder:Finely milled capsicum products occupy niche positions within industrial seasoning blends and snack flavoring. EFSA capsicum extract specifications govern particle size and heat concentration for European-bound shipments.
Fresh Jalapeno holds installed capacity across California's Central Valley and Mexico's Sinaloa belt. Jalapeno Sauce is rotating up the share rankings as craft hot sauce manufacturing expands contracted acreage for specific varietals.
Application:
Demand intensity varies by preparation complexity, with foodservice and manufacturing applications driving specification requirements that commodity channels cannot satisfy.
- Foodservice:Restaurant chains mandate harvest-lot traceability and Scoville certification as standard contract terms, displacing commodity spot purchasing. Chipotle-grade heat consistency has become non-negotiable in southwestern US procurement departments, favoring suppliers with segregated spray records and dedicated harvest zones.
- Processed Foods:Frozen prepared meals and shelf-stable snacks require standardized heat units and consistent pod dimensions for automated production lines. Frozen food manufacturers in the United States are specifying stemless, uniformly sized fruit to minimize processing waste.
- Household Cooking:Retail consumers purchasing through supermarkets and farmers markets prioritize visual appeal and perceived freshness over precise heat measurement. This segment remains price-sensitive and susceptible to substitution by serrano or poblano peppers.
- Condiments:Bottled sauces and relishes combine jalapeno with vinegar, salt, and stabilizers for extended shelf life. Hot sauce producers in Mexico's Chihuahua belt anchor demand through proprietary fermentation protocols.
- Food Manufacturing:Industrial scale users incorporate jalapeno into cheese, meat, and baked goods formulations where heat must distribute evenly through matrix materials. Bakery and snack manufacturers specify powder or flake forms to avoid moisture complications.
Foodservice commands specification premiums through contracted cold-chain delivery. Processed Foods is climbing fastest as frozen meal manufacturers seek authentic heat profiles for ethnic cuisine lines.
Distribution Channel:
Channel economics reflect handling requirements and buyer concentration, with direct distribution capturing margin from traditional wholesale intermediaries.
- Supermarkets:National retail chains demand consistent sizing, packaging, and pricing across hundreds of locations, favoring suppliers with scale logistics and private-label capabilities. California's Central Valley shippers dominate this volume channel through established produce distribution networks.
- Online Retail:E-commerce platforms enable specialty sauce brands and dried pepper merchants to reach consumers outside traditional retail footprints. Shelf-stable products with extended dating perform best in this channel, though perishability constraints limit fresh jalapeno penetration.
- Specialty Stores:Mexican grocers and gourmet food retailers stock heritage cultivars and organic-certified products at price premiums. These outlets serve as testing grounds for varietal introductions before mainstream distribution.
- Wholesale Markets:Terminal produce markets in Los Angeles, Chicago, and Mexico City remain important for spot price discovery and surplus absorption. FSMA compliance costs are squeezing informal suppliers and concentrating volume among verified growers with HACCP-certified facilities.
- Farmers Markets:Direct producer-to-consumer sales capture full retail margin for small-scale operators with organic or heirloom positioning. This channel remains marginal in total volume but significant for price anchoring and brand building.
Supermarkets hold installed capacity through established produce distribution networks. Online Retail is gaining share fastest as shelf-stable sauce brands build direct consumer relationships.
Customer Type:
Purchasing sophistication varies by technical requirements, with manufacturers and culinary institutions driving specification intensity that commodity traders cannot meet.
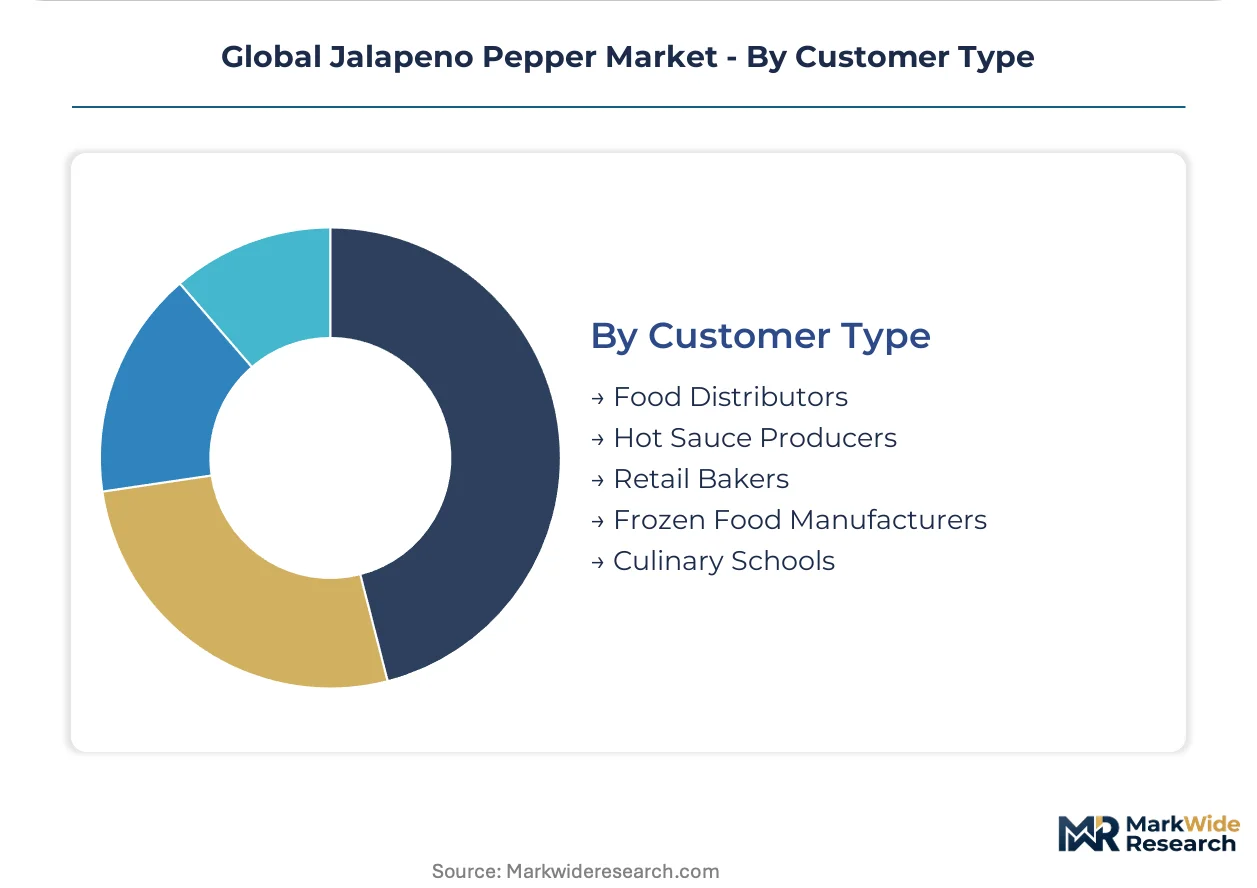
- Hot Sauce Producers:Craft and industrial formulators require consistent Scoville profiles across harvest lots for brand signature maintenance. These buyers are expanding contracted acreage in Mexico's Chihuahua belt, pulling premium fresh volumes from spot markets and enabling processor planning cycles previously disrupted by weather-driven supply shocks.
- Food Distributors:Broadline distributors serving restaurant chains aggregate demand across multiple operators, requiring suppliers to maintain segregated inventory for varying heat specifications. These intermediaries are losing share to direct contracting as chains mandate harvest-date traceability.
- Frozen Food Manufacturers:Industrial-scale users incorporate standardized jalapeno pieces into prepared meals where heat distribution and portion control determine product consistency. These buyers prioritize dimensional uniformity and microbial safety documentation over varietal provenance.
- Retail Bakers:Artisan and commercial bakeries use pickled or dried forms in savory products where moisture content and heat intensity must balance against other flavor components. This segment remains fragmented with limited purchasing leverage.
- Culinary Schools:Training institutions require fresh product for technique instruction, creating stable demand for visually perfect specimens with predictable heat levels. These buyers serve as quality validators whose supplier choices influence broader foodservice procurement.
Hot Sauce Producers hold installed capacity through proprietary fermentation and contracted acreage. Food Distributors are rotating down the share rankings as restaurant chains build direct supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA's Agricultural Marketing Service grading standards anchor regulatory oversight across the largest jalapeno producing geography. FDA's Food Safety Modernization Act and Mexico's SENASICA protocols create parallel compliance tracks that shape cross-border trade flows. Production clusters concentrate in irrigation-dependent valleys where varietal development programs and mechanization investments determine competitive positioning.
United States
California's Central Valley hosts the dominant domestic production cluster, with precision drip irrigation systems stabilizing yield variance for processor planning cycles. FDA's FSMA preventive controls mandate HACCP-certified facilities, squeezing informal suppliers and consolidating procurement among verified growers. Fresno and Kern counties anchor fresh volume supply to southwestern restaurant chains demanding harvest-lot traceability.
Mexico
Chihuahua and Sinaloa growing belts supply premium fresh volumes to craft hot sauce manufacturers seeking specific Scoville-tuned varietals. SENASICA phytosanitary documentation governs cross-border shipments, while organic transition timelines create working capital strain for conventional acreage conversions. Culiacán-based processors are investing in post-harvest smoking infrastructure to capture margin upstream from sauce formulators.
Spain
Andalusian greenhouses supply EU organic channels with REACH-compliant residue profiles, leveraging early-mover advantages in capsicum extract specifications. EFSA heat concentration standards determine which dried and powdered products qualify for European industrial seasoning blends. Almería's controlled-environment agriculture clusters compete on harvest-date specificity for foodservice distributors.
Netherlands
Westland greenhouse complexes specialize in year-round fresh supply to northern European retail chains, with automated sorting systems grading fruit by size and color. EU Green Deal sustainability requirements are reshaping energy inputs for heated cultivation. Randstad logistics hubs enable rapid cold-chain distribution to German and Belgian supermarket networks.
India
Andhra Pradesh and Karnataka growing regions supply dehydrated flake and powder volumes to export-oriented spice processors. FSSAI food safety standards and DGFT export documentation requirements shape quality protocols for industrial seasoning manufacturers. Guntur's chili processing clusters are diversifying into jalapeno-specific drying infrastructure for snack flavoring applications.
Global Jalapeno Pepper Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Global Jalapeno Pepper Market. Capital-intensive operators with captive seed genetics and backward integration into input supply command procurement relationships with specification-intensive buyers. Labor-dependent heritage cultivar specialists compete on organic certification and varietal provenance premiums. Scale-driven volume players and niche quality-focused growers represent the dominant strategic archetypes. Competitive moves concentrate on mechanization investments and direct-to-foodservice distribution bypassing traditional wholesale terminals.
Within the integrated agricultural tier, Nature's Produce exemplifies vertical control from field to retail packaging. Syngenta Crop Protection AG occupies a position anchored in proprietary seed genetics and crop protection bundles. Olam Spices represents the scale-driven processing archetype with multi-hemisphere sourcing networks for dried and processed volumes. These three entities illustrate how competitive positioning bifurcates between technology-intensive input control and geographic diversification for supply reliability.
| Leading Market Players |
|---|
| Nature's Produce |
| Baloian Packing Co. Inc. |
| L & M Companies |
| Syngenta Crop Protection AG |
| Olam Spices |
| Can-Am Pepper Company Ltd |
| Watts Farm |
| Bayer AG |
| Global Green Company Limited |
| Others |
Supply & Pricing Matrix
USDA organic certification and SENASICA phytosanitary documentation simultaneously gate market access and stratify price premiums across the Global Jalapeno Pepper Market. Compliance investments create parallel supply tiers where certified growers capture contract premiums while informal operators face terminal market exclusion.
Pricing Analysis
Long-term offtake agreements dominate procurement between Chihuahua belt growers and craft hot sauce manufacturers seeking Scoville-grade consistency, while spot markets absorb surplus volumes from non-contracted acreage. Price differentiation hinges on organic certification tier and harvest-lot traceability depth, with restaurant chains paying premiums for segregated spray records. Cost compression in mid-scale conventional production is intensifying because phosphate-based fertilizer pricing and glyphosate regulatory pressure squeeze returns. Frozen food manufacturers exhibit highest price sensitivity due to standardized input requirements, whereas hot sauce producers prioritize heat profile consistency over per-unit cost.
Supply Chain Analysis
Mexico and the United States anchor fresh jalapeno production, with California's Central Valley and Chihuahua's irrigation belts supplying distinct market tiers. Supply chains draw from proprietary hybrid seed stocks, phosphate fertilizers, and seasonal H-2A visa labor pools. Single-source vulnerability concentrates in cross-border fresh shipments where SENASICA documentation delays create perishability losses. Distribution runs through direct cold-chain delivery to foodservice chains, bypassing traditional wholesale terminals in Los Angeles and Chicago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanized harvesting capabilities and EU organic equivalence credentials represent acute scarcity assets in a market bifurcating between capital-intensive automation and heritage cultivar specialization.
For Market Incumbents: Compound defensive positioning through backward integration into precision irrigation infrastructure and captive seed genetics licensing. Syngenta-style proprietary bundles face substitution threat from open-pollinated heritage varietals capturing organic premiums. Prioritize HACCP-certified capacity additions in California's Central Valley to consolidate procurement relationships with specification-intensive restaurant chains. For New Entrants and Emerging Players: Differentiate on EU REACH-compliant residue profiles and smoked chipotle vertical integration where post-harvest infrastructure gaps persist. White-space concentrates in direct-to-foodservice distribution bypassing broadline distributors, particularly for Scoville-certified harvest lots. Target organic transition services for mid-scale Mexican growers facing working capital strain during certification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated harvesting technology deployments as computer-vision-guided mechanical pickers compress wage differentials. Long-term viability favors operators with dual-hemisphere sourcing networks and captive processing infrastructure. Acquisition targets should demonstrate segregated compliance tracks for domestic and European channels. Monitor SENASICA documentation processing speeds as inflection indicator for cross-border supply reliability.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanized Harvesting Deployment | Computer-vision-guided pickers in California's Central Valley compress labor cost differentials with Mexican production. |
| EU Organic Equivalence Certification | REACH-compliant residue thresholds create first-mover advantages for Chihuahua belt growers ahead of domestic competitors. |
| Smoked Chipotle Vertical Integration | Post-harvest smoking infrastructure in Culiacán captures margin upstream from sauce manufacturers. |
| Direct-to-Foodservice Distribution | Cold-chain delivery bypassing Los Angeles and Chicago terminals enables harvest-date traceability for restaurant chains. |
| Proprietary Seed Genetics Licensing | Syngenta-style bundled crop protection and hybrid seed control anchors consistent heat profiles for processor planning cycles. |
Research Methodology
Initial hypotheses were tested against primary input from hot sauce manufacturing procurement directors, SENASICA compliance officers, Central Valley farm operators, and EU import certification specialists, then refined through secondary validation. USDA Agricultural Marketing Service grading standards, FDA FSMA preventive controls documentation, EFSA capsicum extract specifications, and customs trade data provided foundational datasets. Bottom-up acreage and yield modeling triangulated against top-down processor demand aggregation.
Variance decomposition across the projection horizon isolates price elasticity by product form, regulatory compliance tier, and geographic supply cluster. Segmentation dimensions include fresh versus processed product type, foodservice versus retail channel, and Scoville-grade specificity. CAGRs derive from iterative reconciliation of supply-side capacity additions and demand-pull from craft hot sauce manufacturing expansion. Climate variability patterns and H-2A visa availability function as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained irrigation infrastructure investment and stable cross-border labor mobility would require recalibration. Forecasts reflect documented assumptions regarding SENASICA processing efficiency and EU residue threshold stability. Recalibration cycles align with material shifts in FSMA enforcement intensity and mechanical harvesting technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Middle East and Africa Shiitake Mushroom Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Morocco Fruits and Vegetables Market
Fruits and Vegetables
Global Dehydrated Onion Flakes Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Global Fruit Concentrate Puree Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Cucumber and Gherkins Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Fermented Cucumber Market
Fruits and Vegetables
Dragon Fruit Market