
 Rosehip Market | 2026-2036
Rosehip Market Size, Share, and Industry Trends Forecast 2026-2036
Rosehip Market Outlook
The EU Green Deal is pivoting cosmetic ingredient sourcing toward traceable, low-carbon botanical supply chains. Sabinsa Corporation leverages its extraction expertise to serve nutraceutical clients seeking standardized actives. Kerry Group Plc anchors its position through integrated supply partnerships with European cosmetic houses. Martin Bauer Group dominates organic rosehip procurement from South American growing regions.
Rosehip comprises the accessory fruit of Rosa canina and Rosa rubiginosa species, containing 30-40% essential fatty acids including linoleic and alpha-linolenic acid alongside ascorbic acid and carotenoids, typically processed through cold-press mechanical extraction or solvent extraction for concentrated actives used in skin regeneration and immune support formulations. Oil retains the largest value share among product types due to its premium positioning in dermo-cosmetic applications, while extract competes for fastest growth as nutraceutical companies seek high-potency powdered concentrates for capsule formulations. Cosmetic manufacturers represent the most concentrated end user segment, though healthcare providers are expanding therapeutic prescribing of rosehip powder for osteoarthritis management.
REACH registration requirements govern chemical safety dossiers for imported rosehip extracts entering European manufacturing facilities, while EFSA novel food evaluations constrain new product positioning claims in dietary supplements. USDA organic certification and EU organic regulation 2018/848 create parallel compliance pathways for premium channel access. Stakeholders must monitor evolving ECHA guidance on botanical substance classification to anticipate reformulation costs and supply chain requalification requirements.
Market Dynamics
EU Green Deal traceability mandates are restructuring rosehip procurement toward certified organic supply chains with documented carbon footprints, forcing cosmetic formulators to requalify Bulgarian and Chilean suppliers under stricter documentation protocols.
Growth Catalysts
- Cold-press extraction technology:German and French cosmetic houses demand mechanically processed oils that preserve heat-sensitive carotenoids and essential fatty acids for premium dermo-cosmetic positioning.
- EFSA novel food evaluations:Standardized rosehip extracts gain regulatory clearance for immune support and joint health claims, unlocking nutraceutical capsule formulations across European markets.
- Bulgarian supply chain expansion:Organic cultivation zones in the Balkans are scaling certified Rosa canina output to reduce dependency on South American import volumes.
Market Restraints
- REACH registration costs:Chemical safety dossiers for imported botanical extracts impose fixed compliance burdens on small-scale Chilean oil processors seeking European market access.
- Seasonal raw material volatility:Rosehip harvest yields fluctuate with Balkan climate patterns, creating input cost instability for cold-press mechanical extraction facilities.
- Synthetic retinol substitution:Laboratory-produced vitamin A compounds compete on price stability against natural carotenoid-rich rosehip oil in mass-market skincare formulations.
Strategic Opportunities
- Healthcare provider prescribing:Osteoarthritis management protocols in German rehabilitation clinics are expanding therapeutic use of standardized rosehip powder beyond cosmetic applications.
- EU organic regulation 2018/848:Certification harmonization creates premium channel access for South American growers meeting combined EU-USDA organic standards.
- Direct-to-clinical distribution:Nutraceutical companies bypass traditional retail channels to supply practitioner-grade extracts directly to rheumatology practices and wellness centers.
Industry Challenges
- Phytochemical standardization expertise:Formulators struggle to secure analytical chemists capable of validating consistent ascorbic acid and linoleic acid concentrations across heterogeneous botanical batches.
- Dual certification timelines:Simultaneous USDA organic and EU organic regulation 2018/848 compliance extends supplier qualification cycles by 12-18 months.
- Legacy solvent extraction retrofit:Facilities upgrading from hexane-based processes to supercritical CO2 systems face capital intensity and technical retraining requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rosehip Market |
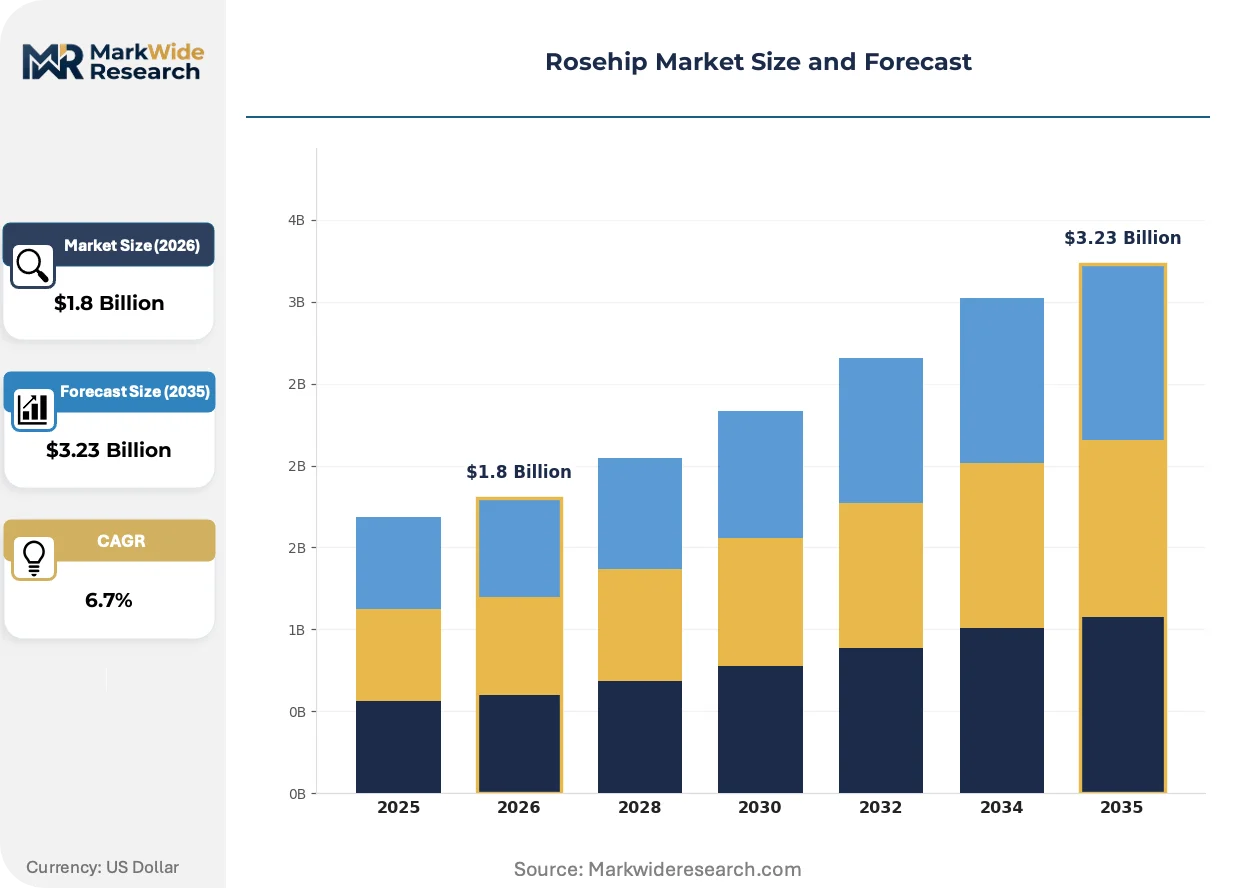
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Powder, Extract, Tea Application: Cosmetics, Dietary Supplements, Food & Beverages, Herbal Remedies Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Individuals, Healthcare Providers, Cosmetic Manufacturers, Nutraceutical Companies |
| Companies Covered | Sabinsa Corporation, Kerry Group Plc, Martin Bauer Group, Blue Sky Botanics, Spectrum Chemical, Frutarom (IFF), Bio-Botanica Inc., Oregon's Wild Harvest, Dohler GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rosehip Market Strategic Shifts
Supercritical CO2 extraction is displacing conventional solvent methods across premium oil production, while regulatory data transparency requirements and practitioner-channel expansion reshape how botanical actives reach end consumers.
Supercritical CO2 extraction systems deploy pressurized carbon dioxide to isolate heat-sensitive bioactives without thermal degradation or residual solvents. German cosmetic manufacturers are adopting this technology at pilot scale for Rosa rubiginosa oil destined for regenerative skincare lines. This precision method is electrifying competitive positioning by enabling potency-based pricing tiers that mechanical pressing cannot match.
EU Green Deal supply chain disclosure rules now mandate documented carbon intensity for imported botanical ingredients entering European manufacturing facilities. Cosmetic houses must map Chilean and Bulgarian farm-to-press emissions or risk exclusion from premium retail channels. French and German formulators are responding by embedding sustainability auditors within supplier operations to pre-validate compliance dossiers.
Practitioners in German rheumatology and physiotherapy clinics are displacing pharmacy retail as the primary channel for therapeutic-grade rosehip powder. Osteoarthritis patients receive condition-specific dosing guidance directly from healthcare providers rather than self-selecting supplement products. This channel migration concentrates demand volume within regulated clinical supply chains and compresses brand loyalty toward practitioner-endorsed extract standards.
Rosehip Market Segmentation
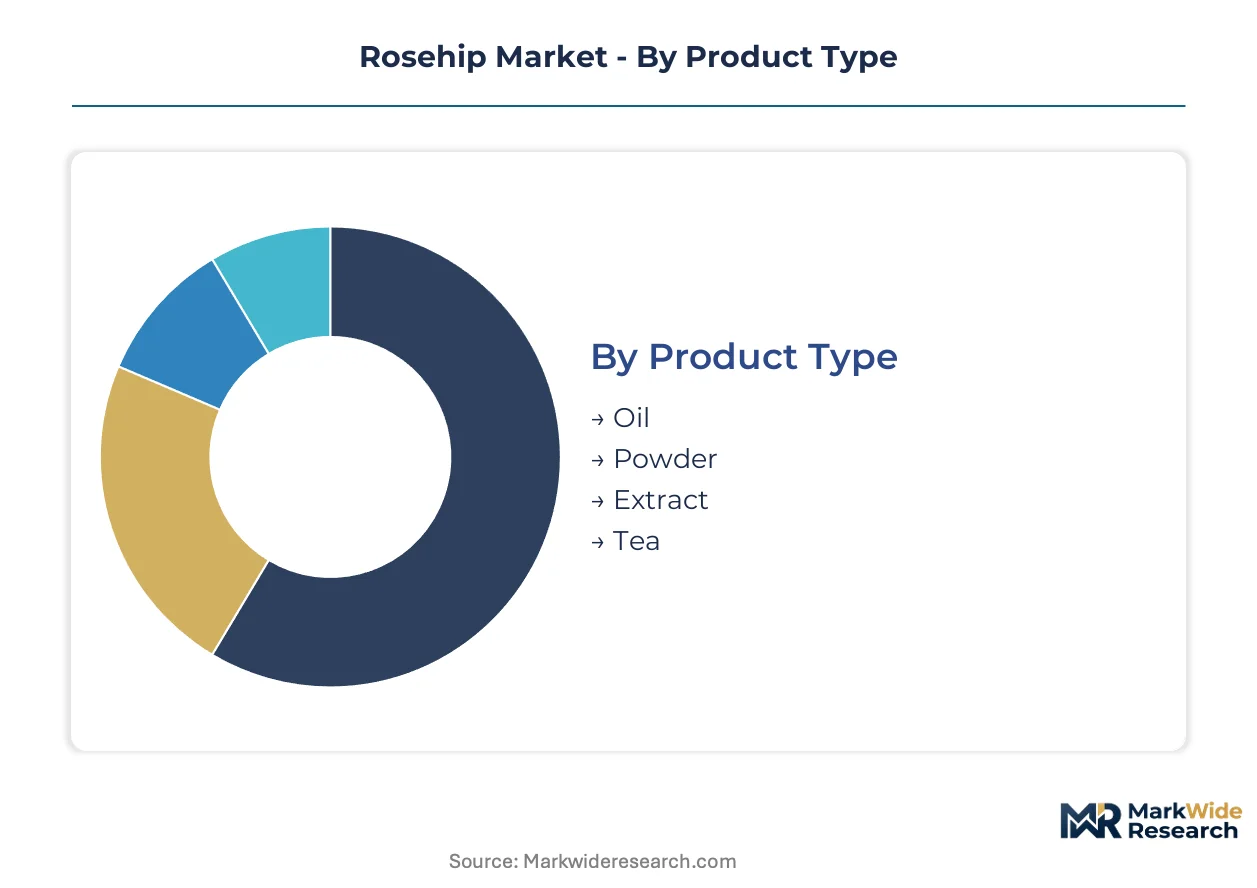
Rosehip market value concentrates in distinct product tiers that command radically different margins. Procurement patterns diverge sharply between cosmetic houses seeking cold-pressed oil purity and nutraceutical buyers prioritizing standardized extract potency.
Product Type:
Buyers differentiate primarily by extraction method sensitivity and bioactive retention requirements.
- Oil:Cold-pressed mechanical extraction preserves heat-sensitive carotenoids and essential fatty acids at 30-40% concentration. German and French cosmetic manufacturers dominate procurement for premium dermo-cosmetic formulations where thermal degradation voids efficacy claims.
- Extract:Solvent or supercritical CO2 processing yields concentrated powdered actives with validated ascorbic acid standardization. Nutraceutical companies across Europe are expanding capsule formulation capacity as EFSA novel food evaluations clarify immune support and joint health positioning.
- Powder:Ground dried fruit pulp serves bulk ingredient buyers in functional food blending.
- Tea:Whole dried hips target traditional herbal remedy consumers through health store channels.
Oil leads volumes today; extract is gaining share fastest.
Application:
End-use economics separate premium cosmetic positioning from commoditized food additive markets.
- Cosmetics:Regenerative skincare and anti-aging serums command the highest value per kilogram. Bulgarian and Chilean supply chains feed formulators in Germany and France where EU Cosmetic Product Regulation safety documentation requirements favor documented organic provenance.
- Dietary Supplements:Standardized rosehip powder for osteoarthritis management is displacing retail pharmacy distribution through direct-to-clinic supply chains in German rheumatology practices.
- Food & Beverages:Functional ingredient blending for juices and fortified foods operates on volume-scale procurement with compressed margins.
- Herbal Remedies:Traditional preparation formats serve legacy consumer segments through specialized health store networks.
Cosmetics dominates absolute value capture; dietary supplements show the steepest expansion trajectory.
Distribution Channel:
Channel selection determines regulatory exposure and margin structure for finished goods.
- Online Retail:Direct-to-consumer platforms enable potency-based pricing transparency and subscription replenishment models for standardized extract products.
- Supermarkets:Mass-market oil and tea formats compete on shelf placement and promotional velocity with limited differentiation capacity.
- Health Stores:Staff-curated positioning supports premium organic certification storytelling for discerning botanical buyers.
- Pharmacies:Regulatory legitimacy for therapeutic-grade powder concentrates depends on healthcare provider endorsement and reimbursement pathway clarity.
Pharmacies anchor therapeutic credibility; online retail climbs fastest as practitioner-channel bypass strategies mature.
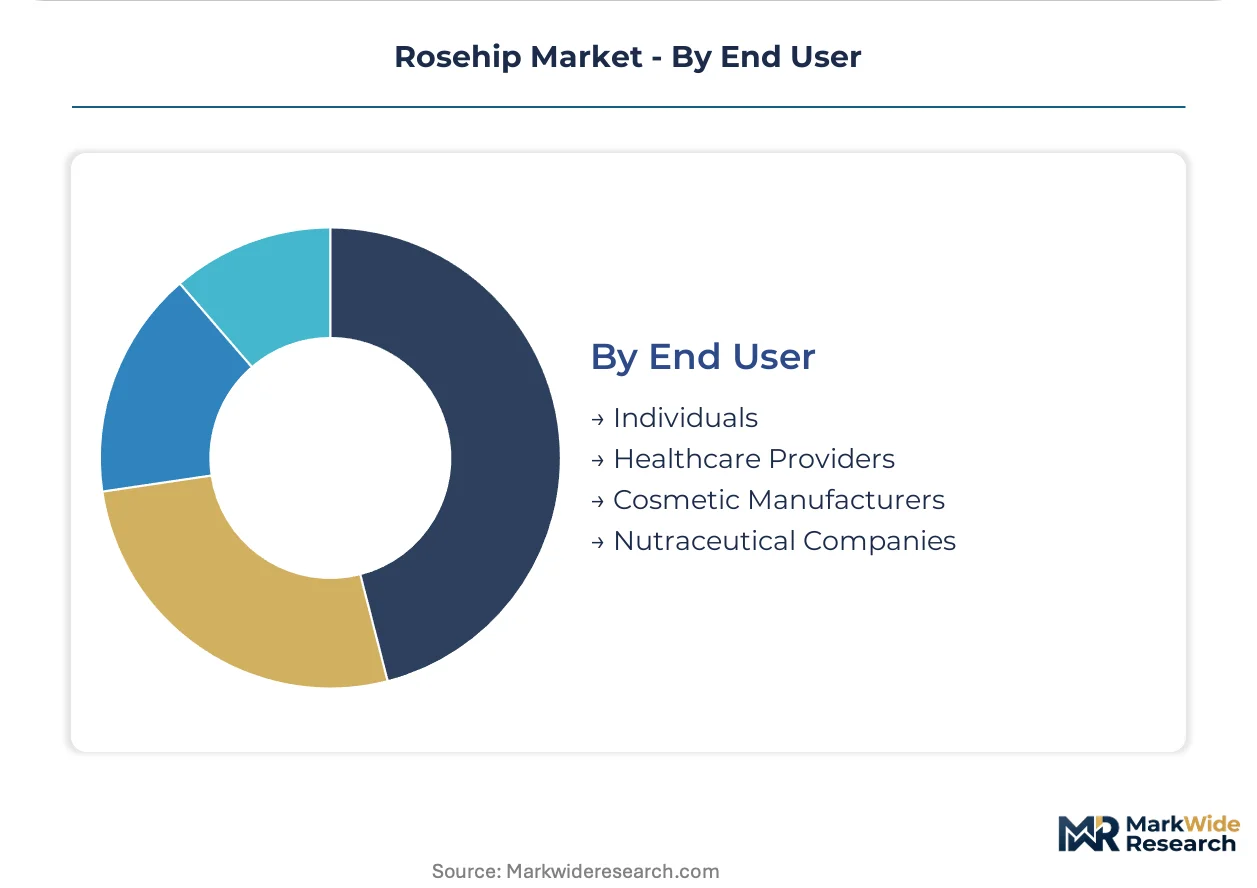
End User:
Procurement sophistication separates industrial-scale buyers from fragmented consumer demand.
- Cosmetic Manufacturers:Integrated supply partnerships with European houses require dual USDA-EU organic certification and documented carbon intensity under EU Green Deal traceability mandates.
- Nutraceutical Companies:High-volume extract procurement for capsule production demands validated phytochemical standardization that only specialized analytical laboratories can certify.
- Healthcare Providers:German rehabilitation clinics and rheumatology practices are consolidating therapeutic powder prescribing through direct distribution agreements that compress traditional retail margins.
- Individuals:Fragmented demand through retail channels shows high price elasticity and low brand loyalty.
Cosmetic manufacturers command supply priority; healthcare providers are capturing share most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rosa canina cultivation originated in the Balkans during the 1950s state-planned agricultural programs, establishing Bulgaria as the historical center of European rosehip processing before Chilean growers captured export markets in the 1990s.
Germany
Cosmetic formulators in Hamburg and Munich drive cold-pressed oil procurement for premium dermo-cosmetic lines. ECHA REACH registration requirements govern imported extract safety dossiers. The Baden-Württemberg cluster hosts supercritical CO2 extraction pilot facilities serving regenerative skincare manufacturers.
France
Paris-based cosmetic houses expand organic rosehip oil sourcing for anti-aging serum formulations. ANSM enforces EU Cosmetic Product Regulation safety documentation for botanical extracts. The Provence-Alpes-Côte d'Azur region concentrates formulation R&D laboratories validating carotenoid retention in cold-pressed oils.
Chile
Patagonian growing regions supply Rosa rubiginosa fruit to European nutraceutical buyers seeking standardized powder extracts. The national agricultural service SAG monitors phytosanitary export certification for organic consignments. Maule Region processors face EU Green Deal carbon footprint documentation requirements for farm-to-press traceability.
Bulgaria
Organic cultivation cooperatives in the Rose Valley scale certified Rosa canina output to reduce South American import dependency. The Ministry of Agriculture administers EU organic regulation 2018/848 compliance for premium channel access. Plovdiv processing facilities modernize cold-press mechanical extraction capacity for German cosmetic manufacturer contracts.
United States
Practitioner-channel distributors supply standardized rosehip powder to integrative medicine clinics in California and New York. USDA organic certification creates parallel compliance pathways for EU-exporting suppliers. Oregon's Willamette Valley hosts small-scale cold-press oil processors serving domestic natural skincare brands.
Rosehip Market Competitive Environment
Capital-heavy agricultural processors compete with asset-light formulation specialists across the rosehip value chain. The market structures around three tiers: integrated botanical extract houses with captive cultivation, specialized cold-press oil processors serving cosmetic accounts, and diversified ingredient distributors managing multi-origin supply portfolios. Dominant competitive moves include backward integration into certified organic cultivation and strategic partnerships with European cosmetic houses requiring dual USDA-EU organic certification.
Within the integrated extract tier, Sabinsa Corporation and Kerry Group Plc exemplify capital-intensive players leveraging extraction expertise across nutraceutical and cosmetic verticals. Martin Bauer Group anchors the organic procurement segment with South American supply chain control. These three entities represent distinct archetypes: technology-driven standardization, integrated supply partnership management, and geographic sourcing dominance.
| Leading Market Players |
|---|
| Sabinsa Corporation |
| Kerry Group Plc |
| Martin Bauer Group |
| Blue Sky Botanics |
| Spectrum Chemical |
| Frutarom (IFF) |
| Bio-Botanica Inc. |
| Oregon's Wild Harvest |
| Dohler GmbH |
| Others |
Value Chain & Pricing Dynamics
Supercritical CO2 extraction technology is compressing cost differentials between premium and standard rosehip oil tiers while concentrating procurement leverage among German cosmetic houses with pilot-scale adoption capabilities. This method simultaneously elevates potency-based pricing premiums and raises capital barriers for Chilean processors still reliant on mechanical cold-press infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates cold-pressed organic oil certified under EU regulation 2018/848 from conventional mechanical-press grades and bulk solvent-extracted powder. Price differentiation hinges on dual USDA-EU organic certification and validated carotenoid retention assays. Cost compression in standard-tier mechanical oils is intensifying because Bulgarian cultivation cooperatives are scaling certified Rosa canina output. Nutraceutical buyers sourcing standardized extracts for EFSA-cleared capsule formulations show lowest price sensitivity; mass-market skincare manufacturers purchasing commodity-grade oil exhibit highest elasticity.
Supply Chain Analysis
Freight cost volatility from Patagonian growing regions to Hamburg processing facilities is compressing margins for Chilean exporters facing EU Green Deal carbon documentation requirements. Supply concentrates in Bulgaria, Chile, and Germany, with Rosa canina pulp and Rosa rubiginosa fruit as primary botanical inputs alongside hexane and CO2 for extraction processing. Single-source vulnerability runs through Patagonian harvests exposed to climate pattern disruption. Distribution runs through direct-to-clinic channels for therapeutic-grade powder and integrated supply partnerships for cosmetic oil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through supercritical CO2 adoption that commands potency-based premiums while synthetic retinol substitution pressures mechanical-press commodity tiers.
For Market Incumbents: Anticipate REACH registration cost escalation by pre-qualifying Bulgarian organic suppliers under EU regulation 2018/848 before Chilean competitors complete dual certification timelines. Deepen backward integration into Rose Valley cultivation cooperatives to secure captive supply of certified Rosa canina feedstock. Defend against synthetic retinol encroachment in mass-market skincare by embedding sustainability auditors for EU Green Deal traceability compliance. For New Entrants and Emerging Players: German rheumatology practices represent an underserved buyer archetype with direct-to-clinic distribution bypassing pharmacy retail markups. White-space concentration sits in practitioner-grade rosehip powder for osteoarthritis protocols, with EFSA novel food evaluation pathways unlocking immune support claims. Target supercritical CO2 extraction partnerships with Baden-Württemberg pilot facilities to access cosmetic house procurement networks without capital-intensive facility builds. For Investors and Strategic Acquirers: Valuations sit cheapest among solvent-extraction processors facing legacy hexane retrofit requirements and dual certification timeline compression. Long-term viability favors integrated botanical extract houses with captive organic cultivation and analytical standardization capabilities. Watch ECHA guidance evolution on botanical substance classification as the inflection signal for reformulation cost spikes and supply chain requalification waves.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Enables potency-based pricing tiers for German regenerative skincare manufacturers. |
| Dual Organic Certification Investment | Unlocks premium channel access under EU regulation 2018/848 and USDA parallel pathways. |
| Direct-to-Clinical Distribution Buildout | Bypasses pharmacy retail margins for German rheumatology and physiotherapy clinic supply. |
| Backward Integration into Cultivation | Secures captive Rosa canina supply from Bulgarian Rose Valley cooperatives. |
| EFSA Novel Food Evaluation Pursuit | Clears immune support and joint health claims for European nutraceutical capsule formulations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic formulation chemists, nutraceutical procurement directors, Bulgarian cultivation cooperative managers, Chilean export processors, and German rheumatology clinic administrators with secondary validation. Sources included EFSA novel food evaluation databases, ECHA REACH registration filings, EU organic certification registries, customs trade records for rosehip oil and extract consignments, and SEC filings from listed ingredient suppliers. Bottom-up volume modeling triangulated against top-down value estimates across extraction method tiers.
Segment-weighting approaches distributed value projections across oil, extract, powder, and tea product types, with application-level splits for cosmetics, dietary supplements, food and beverages, and herbal remedies. Modeled dimensions included extraction technology, certification status, end-use concentration requirements, and regional regulatory cluster. CAGRs derived from trend extrapolation of cold-press adoption rates, supercritical CO2 facility commissioning timelines, and practitioner-channel penetration curves for therapeutic powder.
Inputs from EFSA evaluation databases and ECHA guidance documents were available through the study window; gaps in real-time Bulgarian harvest yield data and Chilean carbon footprint audit completion rates introduce uncertainty bands around supply-side capacity assumptions. Forecasts reflect documented regulatory trajectories and technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Argentina Fruits & Vegetables Market
Fruits and Vegetables
Asia-Pacific Shiitake Mushroom Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
US Vegetable Puree Market
Fruits and Vegetables
Yellow Oyster Mushroom Market
Fruits and Vegetables
Global Dehydrated Onion Flakes Market
Fruits and Vegetables
North America Organic Fruits Market