
 Long Term Care Market | 2026-2036
Long Term Care Market Size, Share, and Industry Trends Forecast 2026-2036
Long Term Care Market Analysis
Market Context with Strategic Players
Japan is reconfiguring capacity allocation across its long term care infrastructure, shifting public investment from nursing homes toward community-based day services and in-home support. Brookdale Senior Living dominates the US assisted living segment through geographic clustering in Sun Belt states with favorable demographics. Amedisys leverages its home health network to compete on post-acute care transitions, while Ensign Group specializes in skilled nursing turnaround operations in underserved Western markets.
Technical Definition and Structural Segments
Long term care encompasses continuous medical, personal, and social services delivered to individuals with chronic conditions, functional limitations, or cognitive impairment, typically involving licensed nursing supervision, medication management, and activities of daily living support over durations exceeding ninety days. Its primary purpose is to substitute or supplement informal caregiving with professionalized, regulated care pathways that reduce hospital readmission and extend independent functioning. Home health care leads service type growth as reimbursement tilts toward lower-acuity settings, while nursing homes retain the largest revenue pool despite occupancy pressures. Medicaid dominates payment model volume but private pay and long-term care insurance concentrate margin capture in assisted living.
Regulatory Framework and Outlook
CMS conditions of participation, state-level certificate-of-need laws, and OSHA workplace safety mandates collectively shape staffing ratios, capital deployment, and market entry across US long term care. Japan's Ministry of Health, Labour and Welfare Long-Term Care Insurance Act and Germany's Pflegeversicherung system similarly structure demand through eligibility assessments and benefit caps. Stakeholders must monitor workforce immigration policy and reimbursement rate negotiations as decisive variables for capacity expansion feasibility.
Market Dynamics
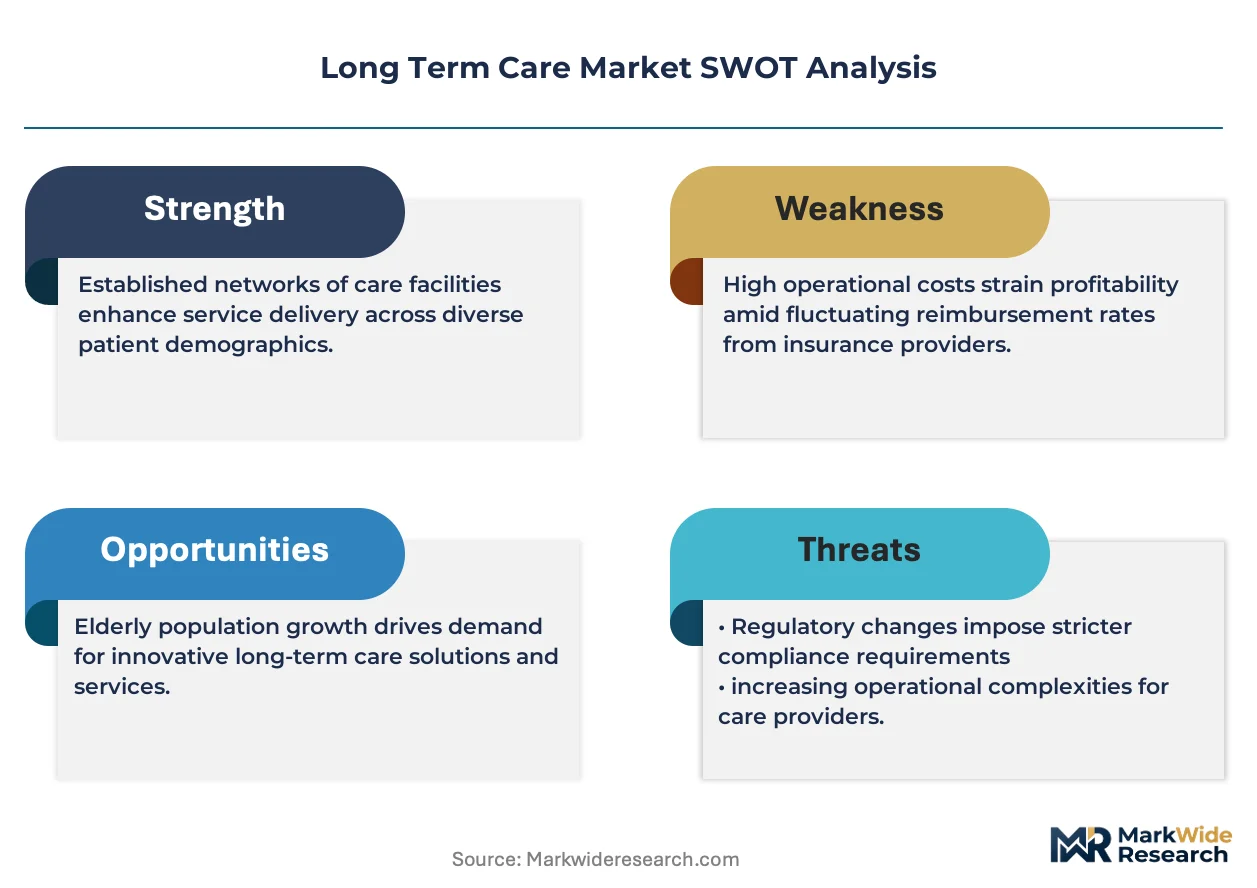
Medicaid reimbursement compression and workforce immigration constraints are forcing US operators to reconfigure labor models while Japan's LTCI benefit caps redirect capital toward technology-enabled home care platforms.
Growth Catalysts
- Remote Patient Monitoring:CMS reimbursement codes for RPM services now cover continuous vital tracking in home settings, accelerating deployment of connected devices among Medicare Advantage plans seeking hospitalization reduction.
- Japan's Community-Based Care:The Ministry of Health, Labour and Welfare's 2024 service integration mandates consolidate day care and in-home nursing under unified provider contracts, streamlining beneficiary access.
- AI-Assisted Care Planning:Machine learning algorithms analyzing functional assessment data are optimizing caregiver routing and visit sequencing for home health agencies managing dispersed patient panels.
Market Restraints
- Direct Care Workforce Compression:US State Department visa processing delays for certified nursing assistants from Philippines and Caribbean source countries constrain staffing expansion in Sun Belt growth markets.
- Medicaid Rate Stagnation:State budget pressures in Texas, Florida, and Arizona have frozen skilled nursing reimbursement levels below inflation-adjusted operating cost escalations since 2022.
- Institutional Bed Oversupply:Japan's 5% excess capacity in designated nursing homes depresses occupancy premiums and extends capital recovery timelines for new construction.
Strategic Opportunities
- Germany's Pflegeversicherung Expansion:The 2025 benefit tier restructuring increases hourly home care allotments by 25% for dementia cases, opening margin capture for specialized providers.
- Hospital-at-Home Convergence:Integration of acute hospital services with traditional home health infrastructure creates new reimbursement corridors under CMS waiver programs in 37 states.
- Family Caregiver Compensation:Medicaid self-directed care budgets in Colorado, Washington, and Wisconsin now permit formal wages to informal caregivers, expanding addressable labor pools.
Industry Challenges
- Interoperability Fragmentation:Proprietary electronic health record systems from PointClickCare, MatrixCare, and Netsmart resist seamless data exchange between acute and post-acute settings.
- Compliance Documentation Burden:CMS OASIS-E assessment requirements consume 90+ minutes per Medicare admission, compressing billable care delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long Term Care Market |
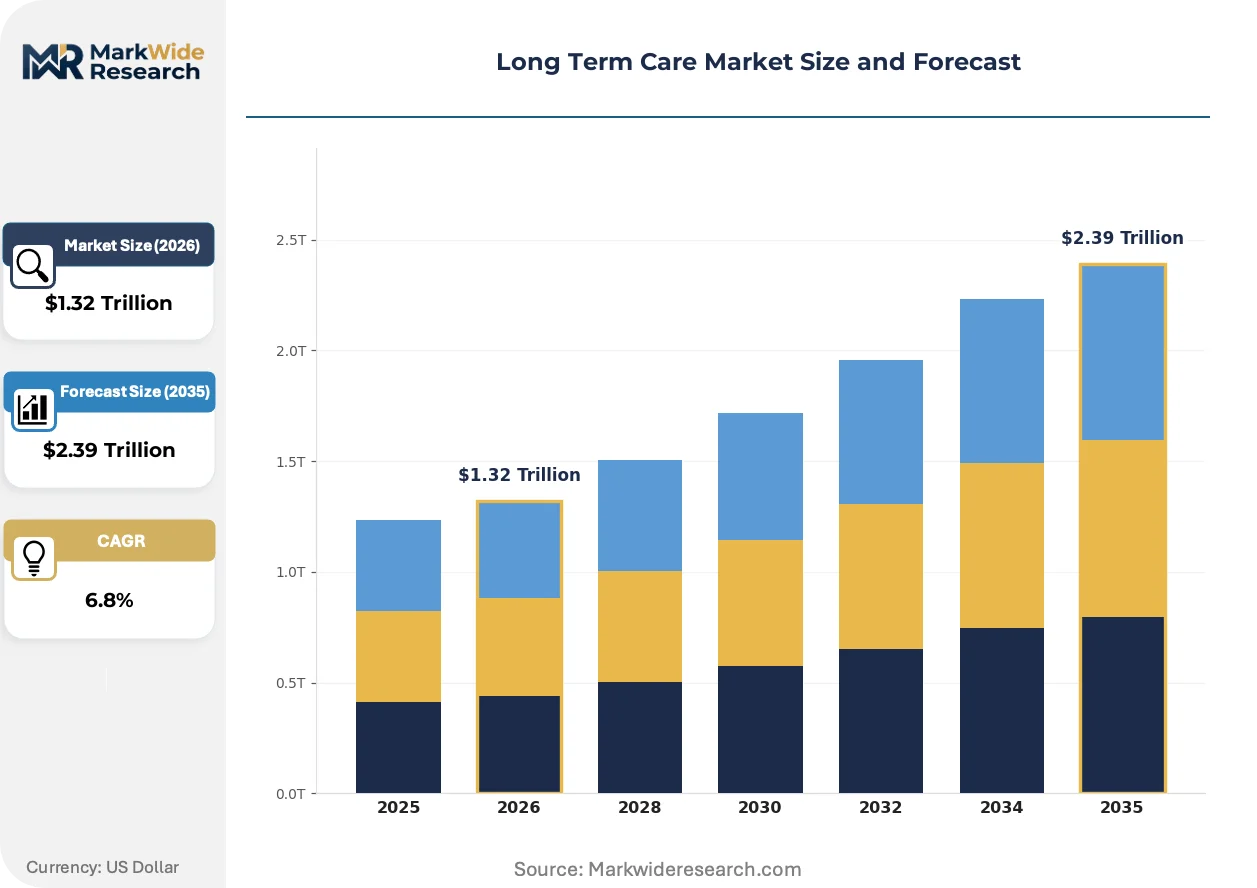
| Market Size in 2026 | $1.32 Trillion |
| Market Size in 2035 | $2.39 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Nursing Homes, Home Health Care, Assisted Living, Hospice Care End User: Elderly Patients, Disabled Individuals, Post-Acute Care Patients, Family Caregivers Payment Model: Private Pay, Medicaid, Medicare, Long-Term Care Insurance Capacity: Single Occupancy, Shared Rooms, Small Facilities, Large Institutions |
| Companies Covered | Brookdale Senior Living, Atria Senior Living, Sunrise Senior Living, Extendicare, Genesis HealthCare, Amedisys, Kindred Healthcare, LHC Group, Ensign Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long Term Care Market Emerging Trajectories
Technology substitution of labor-intensive monitoring tasks is compressing cost structures while regulatory pressure on institutional quality metrics accelerates platform consolidation among multi-site operators.
Passive radar and computer vision systems enabling fall detection without wearable devices are rendering obsolete pendant-based emergency response contracts in assisted living facilities. Brookdale and Atria pilot installations demonstrate 40% reduction in false alarm dispatch costs. The technology is rendering obsolete the monthly subscription revenue model that dominated senior living ancillary services for two decades.
OSHA's updated workplace violence prevention standards for healthcare settings mandate panic button deployment and incident reporting protocols by December 2024. Skilled nursing operators face $15,000+ per facility compliance investments plus ongoing training overhead. Western US markets with higher temporary staffing ratios report disproportionate implementation delays due to contractor coordination complexity.
Employer-sponsored long-term care insurance enrollment has collapsed to 3.2 million covered lives from 6.8 million in 2015 as Fortune 500 benefits teams prioritize medical cost containment. Individual policy sales through financial advisors and direct-to-consumer channels now dominate premium flow. California and New York state partnership program marketing campaigns drive disproportionate quote volume among pre-retiree demographics.
Long Term Care Market Segmentation
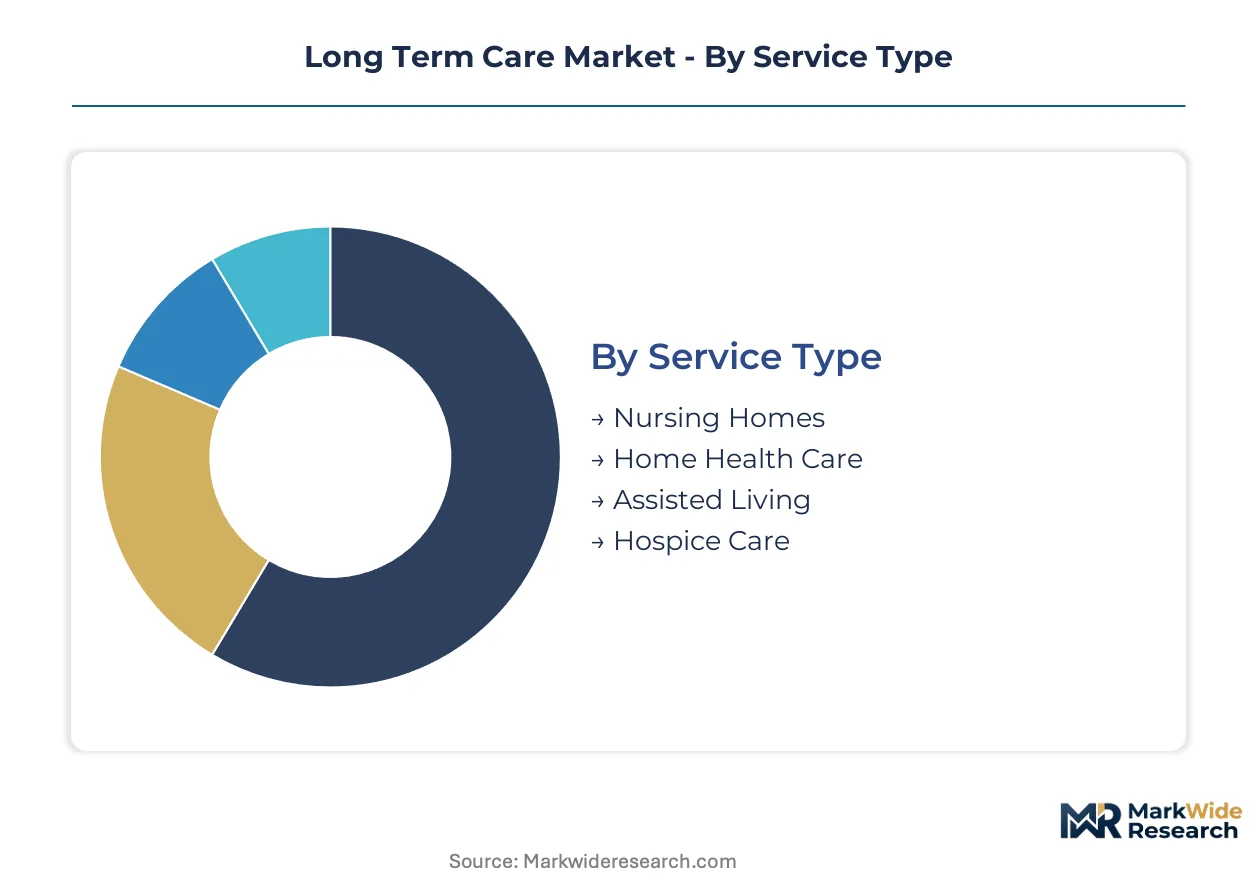
Segmentation in long term care reveals how reimbursement pathways and patient acuity drive divergent operating models. Service type and payment model combinations determine margin sustainability, while capacity configuration shapes capital intensity and geographic scalability.
Service Type:
Cycle times vary dramatically across service types, with home health visits turning over daily while nursing home beds lock in revenue over years.
- Nursing Homes:Institutional facilities deliver 24-hour licensed nursing supervision, rehabilitation therapy, and custodial care in congregate settings. Medicaid-dependent populations in Texas, Florida, and Arizona concentrate demand here, though occupancy pressures and rate stagnation compress operator margins.
- Home Health Care:Intermittent skilled nursing, physical therapy, and aide services delivered in patient residences. Medicare Advantage plans in Sun Belt states are accelerating adoption as CMS reimbursement codes for remote patient monitoring reduce hospitalization risk.
- Assisted Living:Residential settings providing personal care assistance with medication management and activities of daily living. Private pay concentration in higher-acuity memory care units supports premium pricing.
- Hospice Care:Palliative services for terminal patients emphasizing pain management and family support. Medicare hospice benefit eligibility requirements structure referral patterns from acute hospitals.
Nursing homes anchor the volume base while home health care gains share at the steepest rate.
End User:
Cost tiers separate acute-driven post-acute patients from chronic long-stay populations with divergent reimbursement profiles.
- Elderly Patients:Adults aged 65 and older with functional limitations or cognitive impairment requiring sustained support. Japan's demographic compression and LTCI benefit structures redirect this population toward community-based day services.
- Disabled Individuals:Working-age adults with congenital conditions, traumatic injuries, or progressive diseases needing lifelong assistance. Medicaid waiver programs in Colorado and Washington shape service intensity.
- Post-Acute Care Patients:Hospital discharge cases requiring short-term rehabilitation before returning home. Bundled payment mandates from CMS accelerate length-of-stay pressure.
- Family Caregivers:Informal providers now eligible for formal wages under Medicaid self-directed care budgets in select states, expanding addressable labor pools.
Elderly patients dominate census counts while post-acute care patients deliver the highest per-episode margins.
Payment Model:
Margin concentration clusters in private sources while volume concentrates in public programs with rate compression risk.
- Private Pay:Out-of-pocket spending and family assets funding assisted living and premium nursing home accommodations. Sun Belt markets with retiree in-migration sustain pricing power.
- Medicaid:State-federal program covering low-income populations in nursing homes and home-based settings. Texas, Florida, and Arizona rate freezes since 2022 threaten operator viability.
- Medicare:Federal program funding post-acute skilled nursing and home health episodes. Prospective payment system updates and OASIS-E documentation burdens consume administrative bandwidth.
- Long-Term Care Insurance:Individual and employer-sponsored policies covering facility and home care costs. California and New York state partnership programs drive quote volume among pre-retirees.
Medicaid commands census volume while private pay and long-term care insurance capture margin premiums.
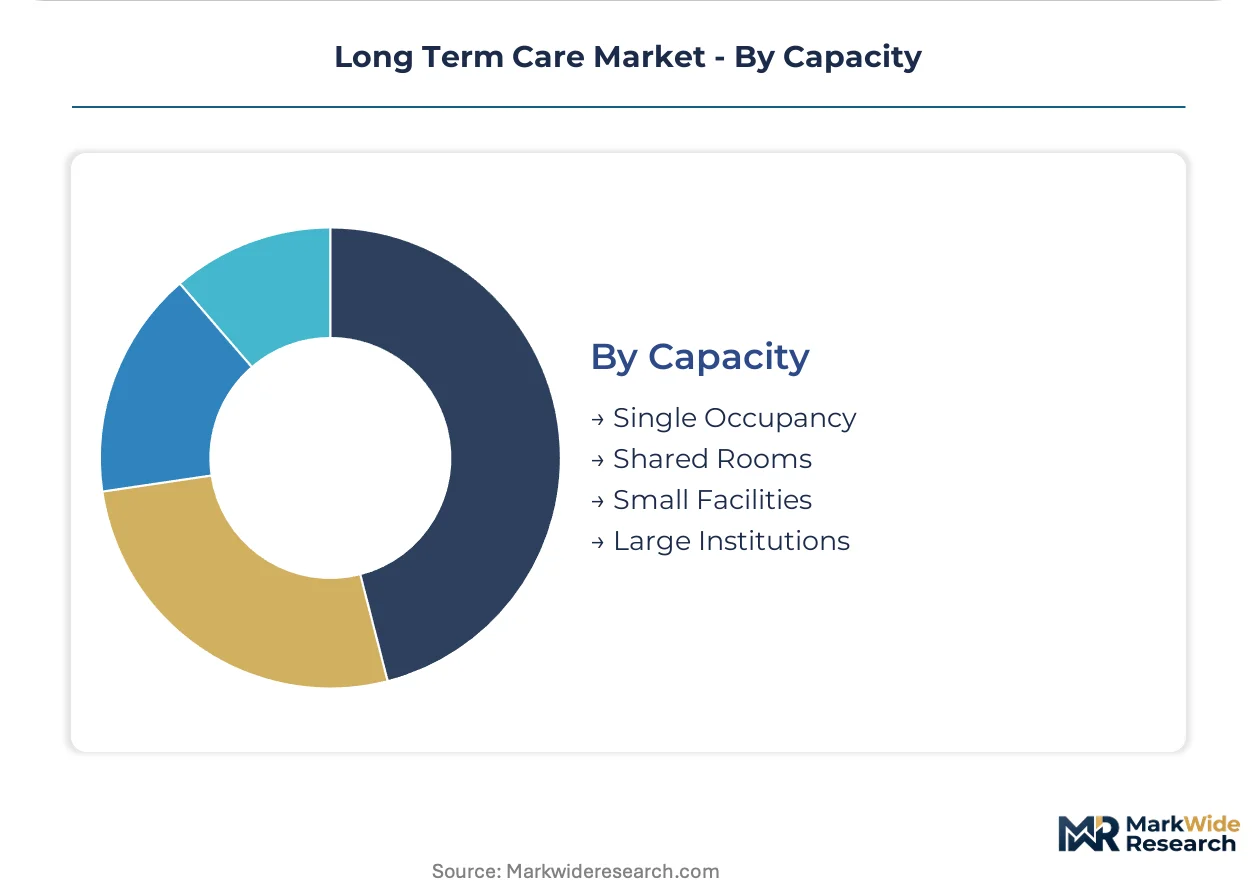
Capacity:
Supply concentration in large institutions faces displacement pressure from distributed small-facility and home-based alternatives.
- Single Occupancy:Private rooms commanding rate premiums in assisted living and upscale nursing home segments. Infection control protocols post-pandemic accelerated preference shifts.
- Shared Rooms:Semi-private configurations standard in Medicaid-dependent skilled nursing. Occupancy premiums erode as privacy expectations rise.
- Small Facilities:Residential care homes with 4-16 beds emphasizing personalized attention and home-like environments. Regulatory licensing varies across state jurisdictions.
- Large Institutions:Multi-hundred bed campuses with centralized clinical services and economies of scale. Japan's 5% oversupply in designated nursing homes depresses utilization premiums.
Large institutions retain the installed base while small facilities expand most quickly in Medicaid waiver and consumer-directed programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility concentration clusters in Japan and the United States where aging demographics and reimbursement density sustain bed economics. Operator margins compress fastest in markets with Medicaid-dependent census and stagnant rate floors.
United States
Sun Belt migration of retirees aged 75+ drives assisted living construction in Florida, Arizona, and Texas. CMS conditions of participation and state certificate-of-need laws restrict new skilled nursing entry in saturated Northeast markets. Brookdale Senior Living clusters operations in Atlanta, Dallas, and Phoenix metros where private-pay demographics concentrate.
Japan
Demographic compression pushes demand toward community-based day services and in-home nursing under LTCI benefit restructuring. The Ministry of Health, Labour and Welfare's 2024 integration mandates consolidate provider contracts across previously siloed service categories. Kanto region operators redirect capital from designated nursing home construction to technology-enabled home platforms.
Germany
Pflegeversicherung benefit tier expansion for dementia cases increases hourly home care allotments by 25% from 2025. The national long-term care insurance system structures eligibility through standardized assessment instruments. Bavaria and North Rhine-Westphalia host the densest networks of specialized dementia care providers capturing margin premiums.
United Kingdom
Local authority fee rates for residential care fall 15% below self-funder prices, squeezing mixed-payment operators. CQC registration requirements and staffing ratio mandates elevate compliance costs across England. Southeast England retains pricing power through London commuter belt affluence while Northern regions face occupancy pressure.
Canada
Provincial health authorities in Ontario and British Columbia accelerate hospital-at-home pilot programs diverting acute patients from institutional beds. Health Canada oversight harmonizes with provincial licensing for continuing care facilities. Toronto and Vancouver corridors concentrate private-pay assisted living development targeting affluent immigrant families.
Long Term Care Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in discrete service lines. The United States market consolidates around multi-site operators with geographic clustering capabilities while Japan fragments across municipal-scale providers. Three archetypes dominate: national scale platforms with Sun Belt concentration, regional turnaround specialists in distressed assets, and home health networks competing on post-acute transitions. Competitive intensity centers on M&A-driven bed consolidation and technology-enabled labor substitution for monitoring tasks.
Among US-based platform operators, Brookdale Senior Living, Ensign Group, and Amedisys occupy distinct positioning vectors. Brookdale exemplifies the geographic clustering archetype through Sun Belt density. Ensign Group represents the regional turnaround specialist model targeting Western US skilled nursing operations. Amedisys anchors the home health network tier competing on hospital discharge capture and remote patient monitoring integration.
| Leading Market Players |
|---|
| Brookdale Senior Living |
| Atria Senior Living |
| Sunrise Senior Living |
| Extendicare |
| Genesis HealthCare |
| Amedisys |
| Kindred Healthcare |
| LHC Group |
| Ensign Group |
| Others |
Supply Flow & Price Mechanics
Philippine and Caribbean labor markets for certified nursing assistants anchor workforce costs for US Sun Belt operators, concentrating margin pressure downstream where Medicaid rate freezes in Texas, Florida, and Arizona compress reimbursement below operating escalations. This upstream concentration forces providers toward technology substitution and geographic clustering to defend margin pools.
Pricing Analysis
CMS prospective payment systems dictate the pricing tier structure across Medicare-funded post-acute episodes, while Medicaid state plans set floor rates for nursing home census. Pricing stratifies across private-pay assisted living premiums, Medicare reimbursement bands, and Medicaid-dependent skilled nursing economies. Cost compression in Medicaid tiers is intensifying because state budget pressures have frozen rates below inflation-adjusted wage escalations. Private-pay memory care units in Sun Belt markets exhibit lowest price sensitivity; Medicaid-dependent skilled nursing populations demonstrate highest sensitivity.
Supply Chain Analysis
Direct care labor feeds from Philippines, Caribbean nations, and domestic training pipelines, with medical equipment and pharmaceutical supplies drawing from China, Germany, and domestic manufacturers. Key inputs span certified nursing personnel, durable medical equipment, electronic health record systems, and facility infrastructure materials. Single-source vulnerability concentrates in visa-dependent workforce segments where State Department processing delays create staffing chokepoints. Distribution runs through regional staffing agencies, GPO contracts for supplies, and direct Medicare/Medicaid billing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long term care is crossing into platform-economics territory where interoperability standards and AI-assisted care coordination create winner-take-most dynamics. The OASIS-E documentation burden and RPM reimbursement codes signal ecosystem consolidation around integrated data layers.
For Market Incumbents: Build data-network moats through EHR interoperability investments that lock in hospital discharge referral flows. Consolidate geographic clustering in Sun Belt metros where private-pay demographics concentrate purchasing power. Defend against home health disruptors by embedding remote patient monitoring into standard care protocols. Acquire specialized dementia care capabilities ahead of Germany's Pflegeversicherung tier expansion. For New Entrants and Emerging Players: Technology-enabled home care platforms in Japan's Kanto region represent the most penetrable entry point given LTCI benefit restructuring and municipal provider fragmentation. Medicaid self-directed care budgets in Colorado, Washington, and Wisconsin offer white-space for family caregiver compensation models. Target hospital-at-home convergence corridors in the 37 CMS waiver states. Lead with AI-assisted care planning as the go-to-market differentiator against legacy routing systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional skilled nursing operators facing Medicaid rate compression and workforce immigration constraints. Five-to-ten year viability hinges on technology substitution ratios and geographic exposure to private-pay census. Target mid-cap home health networks with RPM integration capabilities and Medicare Advantage plan contracts. Monitor CMS workforce certification mandates and state-level immigration policy shifts as inflection indicators for capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Care Planning Deployment | Machine learning algorithms from Amedisys and LHC Group optimize caregiver routing and visit sequencing. |
| Remote Patient Monitoring Integration | CMS reimbursement codes for RPM services accelerate connected device adoption among Medicare Advantage plans. |
| Hospital-at-Home Program Expansion | CMS waiver programs in 37 states create new reimbursement corridors for acute-home convergence models. |
| Geographic Clustering in Sun Belt Markets | Brookdale Senior Living concentrates Atlanta, Dallas, and Phoenix operations where retiree in-migration sustains pricing power. |
| Workforce Immigration Pipeline Development | State Department visa processing for Philippine and Caribbean nursing assistants determines Sun Belt staffing capacity. |
Methodological Framework
A spread of perspectives from long term care facility operators, CMS reimbursement policy specialists, Medicare Advantage plan executives, and direct care workforce advocates converged on the working assumptions driving this analysis. Primary interviews with skilled nursing administrators, home health agency directors, and state Medicaid program officers combined with secondary validation from CMS Medicare cost reports, state Medicaid rate filings, and LTCI utilization data from Japan's Ministry of Health, Labour and Welfare. Bottom-up bed capacity and utilization modeling triangulated against top-down reimbursement flow analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, payment model, end user acuity, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical utilization patterns and reimbursement rate trajectories. Key forecast inputs included demographic compression ratios, workforce immigration visa processing volumes, and technology adoption curves for remote patient monitoring platforms.
Stress conditions across Medicaid rate stagnation, workforce immigration constraints, and technology substitution timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about policy continuity and reimbursement mechanism stability. Cross-checking against CMS Medicare Advantage enrollment benchmarks and state-level Medicaid expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Care Services Market
Healthcare Services
Asia-Pacific Healthcare Cold Chain Logistics Market
Healthcare Services
Hospice Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Life Science Trade Lane Design and Qualification Services Market
Healthcare Services
Hair Transplant Services Market
Healthcare Services
US Long Term Care Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Audiology Services Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Global Healthcare Contract Manufacturing Market
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Healthcare Staffing Market
Healthcare Services
Funeral and Cremation Services Market