
 Europe Data Center Automation Market | 2026-2036
Europe Data Center Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Automation Market Analytics
Subscription-based orchestration software is rebalancing vendor revenue models toward recurring streams rather than perpetual licenses. IBM Corporation leverages its hybrid cloud automation suite to anchor enterprise accounts across Frankfurt and Paris. Microsoft Corporation competes through deep Azure integration that extends automation into edge compute nodes. VMware, Inc. specializes in virtualization-layer automation that controls multi-tenant resource allocation.
Data center automation encompasses software-defined systems that orchestrate server provisioning, thermal management, and network configuration without manual intervention, typically operating through API-driven controllers that enforce policy across thousands of physical and virtual assets. The primary commercial purpose is eliminating human latency from infrastructure scaling while containing energy overhead in facilities exceeding 10 megawatts of IT load. Software and services together capture the dominant margin pools as operators outsource complex integration work rather than build in-house competency. Cloud-based and hybrid deployment models are expanding fastest as legacy on-premises estates in London and Amsterdam undergo partial migration. AIOps and machine learning segments attract disproportionate R&D allocation because predictive failure detection directly reduces downtime penalties under strict SLA frameworks.
EMA guidelines on AI-enabled medical diagnostics and the EU AI Act's risk classification system shape product development roadmaps for automation vendors serving regulated verticals. ECHA REACH compliance and the EU Green Deal's energy efficiency mandates force hardware refresh cycles that embed automated power capping and liquid cooling orchestration. Germany's KBA and France's ANSM apply sector-specific reliability standards that filter which automation platforms qualify for automotive and pharmaceutical data environments. Stakeholders must monitor how the EU's forthcoming Data Act provisions on interoperability reshape vendor lock-in dynamics across multi-cloud estates.
Market Dynamics
The EU AI Act's risk-classification framework is forcing operators to retrofit legacy facilities with intelligent orchestration layers that can audit workload decisions in real time.
Growth Catalysts
- EU Green Deal energy mandates:Germany's national efficiency directives compel hyperscale operators to deploy automated thermal management that reduces PUE below 1.2.
- Financial services procurement:Frankfurt and London banking clusters are consolidating data center footprints while demanding API-driven infrastructure provisioning at sub-minute latency.
- Liquid cooling orchestration:Immersion and direct-to-chip cooling systems require software controllers that manage coolant flow rates across heterogeneous server generations.
Market Restraints
- Specialized engineering talent scarcity:France and Germany face acute shortages of DevOps engineers capable of integrating legacy SCADA with cloud-native orchestration stacks.
- Input cost volatility:Power distribution unit pricing fluctuates with copper and semiconductor component markets, compressing automation project margins.
- Regulatory fragmentation:France's ANSM reliability standards for pharmaceutical data environments diverge from Germany's KBA automotive requirements, forcing redundant certification cycles.
Strategic Opportunities
- Edge compute automation:Netherlands and Ireland are deploying automated micro-data centers to support low-latency AI inference for manufacturing and logistics.
- EU Data Act interoperability:The forthcoming provisions on multi-cloud data portability create openings for vendors offering vendor-agnostic orchestration middleware.
- AIOps convergence with digital twin:Predictive failure detection combined with facility simulation is attracting R&D investment from utilities and telecom operators.
Industry Challenges
- Legacy infrastructure integration:Brownfield facilities in London and Amsterdam require custom API gateways to connect 15-20 year-old building management systems with modern orchestration platforms.
- Skill set misalignment:Traditional data center operations teams lack proficiency in infrastructure-as-code tooling and Kubernetes cluster management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Automation Market |
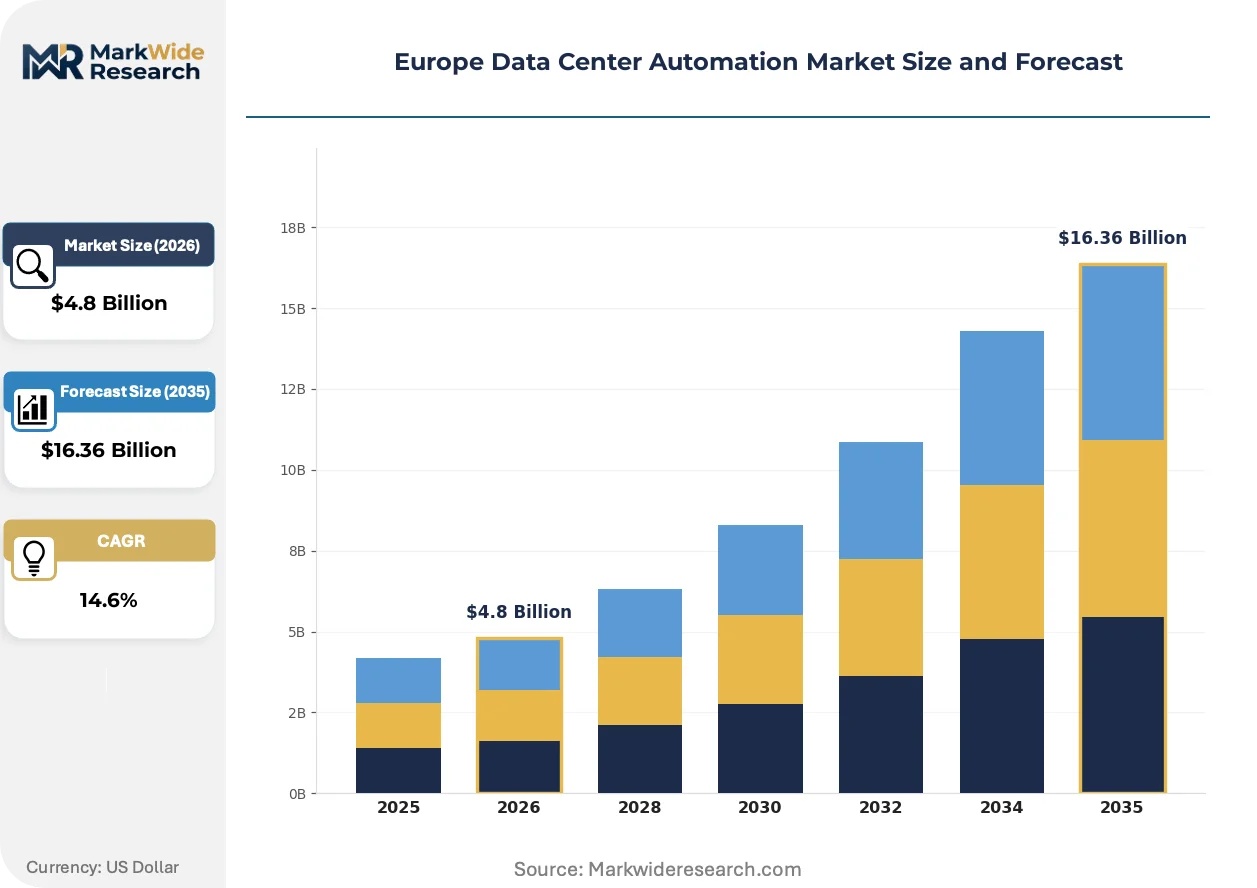
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
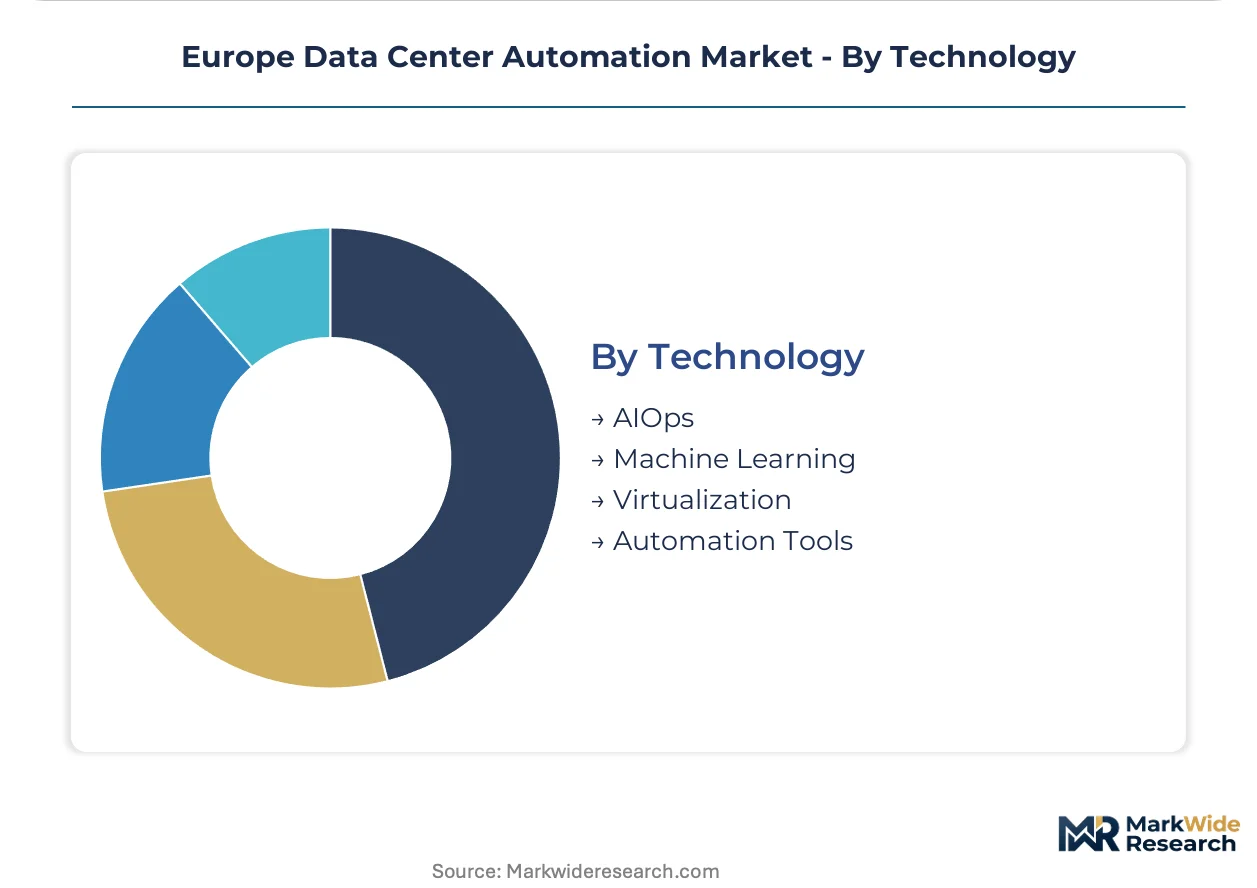
| Segmentation | Product Type: Software, Hardware, Services, Solutions Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge End User: IT Enterprises, Telecom Operators, Managed Service Providers, Government Bodies Technology: AIOps, Machine Learning, Virtualization, Automation Tools |
| Companies Covered | IBM Corporation, Oracle Corporation, BMC Software, Inc., Fujitsu Limited, Citrix Systems, Inc., Cisco Systems, Inc., Microsoft Corporation, VMware, Inc., Hewlett Packard Enterprise Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Automation Market Evolving Landscape
Automation architectures are fragmenting from monolithic platforms into composable stacks that let operators swap individual control functions without forklift upgrades.
Software-defined power distribution is modularizing how facilities manage rack-level energy budgets. Hyperscale operators in Frankfurt and Paris are adopting intelligent rack PDUs that expose consumption metrics through standardized APIs. This modularizing of power infrastructure lets colocation providers offer granular, metered billing that aligns pricing with actual compute cycles rather than flat rack rates.
The EU AI Act's high-risk system requirements are mandating automated logging and explainability for infrastructure decisions affecting sensitive workloads. Medical diagnostics and financial trading platforms must now maintain immutable audit trails of every server provisioning action. German automotive manufacturers are responding by embedding policy-as-code engines that block non-compliant workload deployments before hardware allocation occurs.
Consumption-based contracting is displacing perpetual license models across the vendor landscape. Enterprise buyers in London's financial district now negotiate automation software deals indexed to actual provisioned capacity rather than socket counts or server instances. This shift compresses vendor cash conversion cycles while transferring utilization risk from operator to supplier, with French cloud service providers leading the transition to metered orchestration pricing.
Europe Data Center Automation Market Segmentation
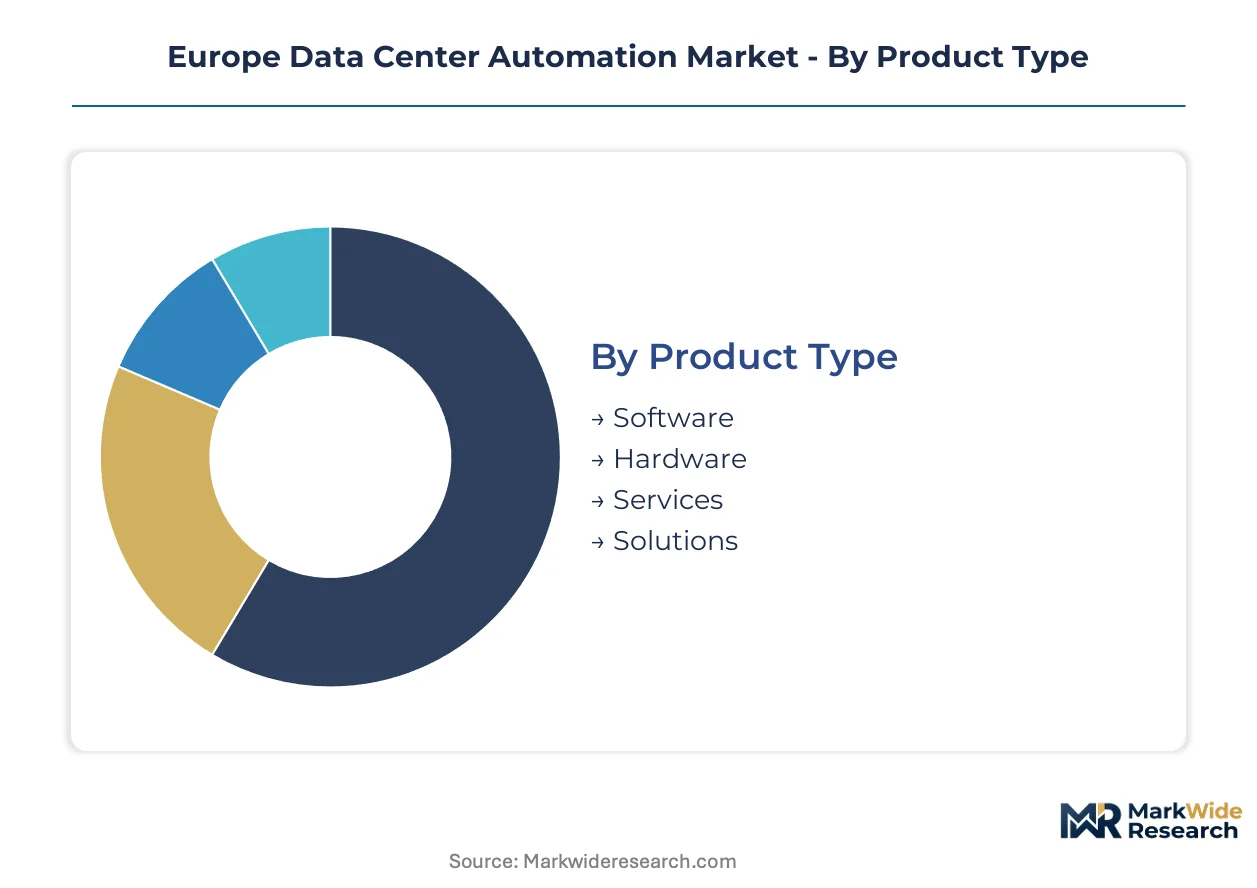
Segmentation reveals how procurement priorities diverge across deployment models and end-user sophistication. Upgrade cycles for legacy facilities in Frankfurt and London create tiered demand patterns that vendors must map precisely.
Product Type:
Replacement cycles for aging orchestration stacks drive purchasing decisions, with operators weighing integration complexity against functional breadth.
- Software:API-driven controllers orchestrate server provisioning, thermal management, and network configuration through policy engines. Frankfurt financial services clusters prioritize subscription-based orchestration platforms that enable sub-minute infrastructure scaling without perpetual license lock-in.
- Hardware:Intelligent rack PDUs, automated power distribution units, and environmental sensors embed directly into facility infrastructure. Paris hyperscale operators deploy hardware with standardized API exposure to enable granular, metered billing aligned with actual compute cycles.
- Services:Integration consulting and managed automation operations address skill gaps in legacy SCADA-to-cloud-native transitions.
- Solutions:Bundled software-hardware-service packages target brownfield modernization in Amsterdam and London facilities.
Volume placements concentrate in Software; the faster expansion belongs to Services as outsourcing accelerates.
Deployment Model:
Cost tier differentiation separates enterprise-grade orchestration from scaled-down edge implementations.
- On-Premises:Traditional data center estates retain localized control planes for latency-sensitive workloads. German automotive manufacturers mandate on-premises policy-as-code engines to satisfy KBA reliability standards for connected vehicle data.
- Cloud-Based:Fully managed orchestration offloads infrastructure maintenance to hyperscale providers. French pharmaceutical operators adopt cloud-based automation to streamline ANSM compliance documentation through centralized audit trails.
- Hybrid:Split workload management across private infrastructure and public cloud resources. London financial services firms deploy hybrid models to maintain sensitive trading data on-premises while bursting analytics to cloud.
- Edge:Distributed micro-data centers automate low-latency inference for manufacturing and logistics. Netherlands industrial corridors deploy edge automation to support real-time quality control without round-trip latency to central facilities.
Hybrid deployments capture the largest current footprint; edge automation climbs the fastest as manufacturing digitization spreads.
End User:
Application intensity varies sharply, with regulated verticals demanding certified platforms while telecom operators prioritize scale economics.
- IT Enterprises:Corporate data center operators automate server lifecycle management and capacity planning. UK banking clusters consolidate footprints while demanding API-driven provisioning at sub-minute latency.
- Telecom Operators:Network function virtualization and 5G core automation drive infrastructure orchestration requirements.
- Managed Service Providers:Multi-tenant automation platforms enable differentiated colocation offerings across client segments.
- Government Bodies:Sovereign cloud and defense data facilities impose strict compliance and security mandates on automation vendors.
IT Enterprises dominate current procurement; Managed Service Providers gain share fastest as colocation automation becomes competitive differentiator.
Technology:
Margin concentration follows capability depth, with predictive systems commanding premium pricing over basic automation tooling.
- AIOps:Predictive failure detection and automated remediation reduce downtime penalties under strict SLA frameworks. EU AI Act high-risk system requirements mandate immutable audit trails for AIOps decisions affecting medical diagnostics and financial trading platforms.
- Machine Learning:Workload pattern recognition and demand forecasting optimize resource allocation dynamically. German hyperscale operators embed ML-based thermal prediction to maintain PUE below 1.2 under national efficiency directives.
- Virtualization:Software-defined compute, storage, and network abstraction layers enable rapid resource reconfiguration.
- Automation Tools:Script-based and low-code orchestration utilities address simpler, repetitive infrastructure tasks.
AIOps commands the steepest pricing premium; Machine Learning shows the steepest expansion trajectory as predictive capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors European data center automation demand, with financial services clusters driving sub-minute infrastructure provisioning requirements across the Rhine-Main metropolitan region.
Germany
Automotive manufacturers and hyperscale operators propel automation procurement in Hesse and Bavaria. Germany's KBA imposes strict reliability standards on connected vehicle data infrastructure. Frankfurt's banking district deploys policy-as-code engines to block non-compliant workload deployments before hardware allocation occurs.
United Kingdom
London's financial services sector consolidates data center footprints while demanding API-driven provisioning capabilities. The UK Information Commissioner's Office enforces data residency requirements that shape hybrid automation architectures. The Slough-London corridor hosts dense colocation clusters where metered orchestration pricing is displacing perpetual licenses.
France
Pharmaceutical operators and cloud service providers accelerate automation adoption in Île-de-France. ANSM reliability standards for medical data environments filter qualified automation platforms for Paris-region facilities. The Saclay plateau research cluster integrates automated thermal management to satisfy EU Green Deal efficiency mandates.
Netherlands
Industrial corridors deploy edge automation to support real-time manufacturing quality control without central facility latency. REACH compliance obligations through ECHA shape hardware refresh cycles for Amsterdam data centers. The Eindhoven-Tilburg manufacturing belt automates micro-data centers for low-latency AI inference in logistics operations.
Ireland
Hyperscale facility construction intensifies automation demand across Greater Dublin. The national data center strategy imposes energy efficiency thresholds that favor intelligent workload management systems. The Grange Castle business park anchors multi-tenant automation platforms serving North American cloud operators.
Europe Data Center Automation Market Competitive Landscape
Capital-heavy infrastructure vendors compete with asset-light software specialists across the European automation stack. The market structure concentrates around three tiers: hyperscale cloud providers with integrated orchestration suites, enterprise software vendors with hybrid cloud automation platforms, and specialized virtualization-layer specialists. Strategic moves center on consumption-based contracting models that transfer utilization risk from operators to suppliers, alongside API standardization efforts that reduce legacy integration friction.
Among US-based technology conglomerates, IBM Corporation and Microsoft Corporation exemplify divergent competitive archetypes. IBM leverages subscription-based orchestration software to anchor enterprise accounts across Frankfurt and Paris financial districts. Microsoft competes through deep Azure integration that extends automation into edge compute nodes. VMware, Inc. occupies a distinct position specializing in virtualization-layer automation that controls multi-tenant resource allocation. These three represent the spectrum from full-stack platform provision to infrastructure abstraction specialization.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| BMC Software, Inc. |
| Fujitsu Limited |
| Citrix Systems, Inc. |
| Cisco Systems, Inc. |
| Microsoft Corporation |
| VMware, Inc. |
| Hewlett Packard Enterprise Company |
| Others |
Value Network & Pricing Analysis
Hyperscale operators in Frankfurt and London concentrate procurement volumes, forcing vendors toward consumption-based SaaS models that transfer utilization risk from buyer to supplier. This buyer concentration enables granular metered pricing indexed to provisioned capacity rather than perpetual licenses, while EU Green Deal compliance costs embed into software-hardware bundles.
Pricing Analysis
Uptime guarantees anchor value-based pricing for automation platforms serving financial services clusters. Subscription tiers stratify across enterprise, mid-market, and edge deployment levels, with Frankfurt banking groups least sensitive due to SLA penalty exposure. Cost compression in mid-market software stems from open-source orchestration alternatives, while hardware automation commands premium pricing tied to liquid cooling integration complexity.
Supply Chain Analysis
Dual-sourcing requirements from German automotive and French pharmaceutical operators mandate multi-supplier qualification for intelligent rack PDUs and environmental sensors. Manufacturing concentrates in Germany, Taiwan, and the Netherlands for precision power distribution units. Copper and semiconductor feedstock volatility creates margin pressure, while distribution runs through systems integrators and direct hyperscale contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as EU AI Act compliance costs force sub-scale vendors toward exit or acquisition. Tier-1 software vendors capture displaced customers from automation specialists lacking certification depth.
For Market Incumbents: Lock in enterprise accounts through policy-as-code engines that preemptively block non-compliant workload deployments under KBA and ANSM standards. Deepen backward integration into intelligent rack PDU manufacturing to control hardware margin pools and reduce exposure to copper price swings. Prioritize R&D allocation toward AIOps modules that satisfy EMA audit trail requirements for high-risk AI systems. For New Entrants and Emerging Players: Mid-sized French pharmaceutical operators represent an underserved buyer archetype seeking cloud-based automation without hyperscale vendor lock-in. Netherlands edge compute deployments for manufacturing quality control offer white-space penetration with lower certification barriers than Frankfurt financial services. Lead with API-agnostic orchestration middleware that capitalizes on forthcoming EU Data Act interoperability mandates. For Investors and Strategic Acquirers: The window for entry favors virtualization-layer specialists with proven multi-tenant resource management and established ANSM or KBA certification pathways. Long-term viability hinges on recurring revenue concentration above project-based services. Watch for inflection when hyperscale capex disclosures signal accelerated liquid cooling retrofit cycles across legacy London and Amsterdam facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure and AWS native orchestration captures hybrid workload management across Frankfurt banking estates. |
| Acquisition of Specialist Firm | Virtualization-layer automation targets address multi-tenant resource allocation gaps in Paris colocation markets. |
| Strategic Partnership | Systems integrator alliances accelerate brownfield SCADA-to-cloud-native transitions in London facilities. |
| Product Launch | Policy-as-code engines preempt EU AI Act non-compliance penalties for German automotive data infrastructure. |
| Geographic Expansion | Edge automation deployment in Eindhoven-Tilburg corridor captures low-latency manufacturing inference demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with data center operations directors, DevOps engineering leads, colocation procurement managers, and systems integration specialists. ECHA REACH documentation, EU AI Act implementation guidance, and national energy efficiency directive filings provided regulatory boundary conditions. SEC 10-K disclosures from automation vendors and hyperscaler capex reports supplied financial validation. Bottom-up facility-level automation spend estimates triangulated against top-down vendor revenue aggregation.
Data-stream reconciliation across deployment model, end-user vertical, technology layer, and geographic adoption pattern dimensions shaped the analytical framework. CAGRs derived from fitted growth curves applied to base-year market sizing, with cross-validation against infrastructure build-out pipelines and regulatory compliance deadlines. Liquid cooling retrofit intensity and AIOps module attach rates served as industry-specific forecast inputs across the projection horizon.
Revisions become necessary when EU Data Act interoperability provisions accelerate faster than anticipated, or when copper and semiconductor input costs diverge materially from baseline assumptions. Deviation in Germany's national efficiency directive enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Database Automation Systems Market
Automation
Retail Automation Market
Automation
Service Delivery Automation (SDA) Market
Automation
Global Process Automation and Instrumentation Market
Automation
Global Direct Mail Automation Software Market
Automation
Modular Laboratory Automation Market
Automation
Playout Automation Market
Automation
Italy Marketing Automation Software Market
Automation
Marketing Automation Solutions Market
Automation
Elevator Control Market
Automation
Global Business Process Automation Software Market
Automation
Helpdesk Automation Market
Automation
Computer Numerical Control Market
Automation
Distribution Automation Solutions Market
Automation
Global Zig-Bee Automation Market
Automation
Postal Automation System Market