
 Stearoyl Lactylates Market | 2026-2036
Stearoyl Lactylates Market Size, Share, and Industry Trends Forecast 2026-2036
Stearoyl Lactylates Market Analytics
China is narrowing its dependence on imported stearoyl lactylate intermediates through domestic esterification capacity additions near Shanghai. Cargill leverages backward integration into vegetable oil feedstocks to secure cost-advantaged stearic acid supplies for its emulsifier operations. Corbion specializes in fermentation-derived alternatives that compete with petrochemical-route stearoyl lactylates in premium bakery applications.
Stearoyl lactylates are anionic surfactants synthesized from stearic acid and lactic acid via esterification, typically yielding products with acid values between 60-120 mg KOH/g and HLB values near 8-12, functioning primarily as dough conditioners and emulsifiers in food systems. Food-grade stearoyl lactylates dominate volume throughput due to entrenched use in commercial bread production, while pharmaceutical-grade variants command superior margins as tablet binders and controlled-release excipients. Powder delivery mode leads in logistics efficiency for large-scale food manufacturers, though liquid formats are gaining traction in automated dosing systems at industrial bakeries.
The FDA maintains GRAS status for sodium stearoyl lactylate under 21 CFR 172.846, while EFSA evaluates E481 through the EU food additive reauthorization program, with both frameworks pushing suppliers toward enhanced purity documentation and supply chain traceability. China's SAMR implements GB standards for food emulsifiers that require foreign producers to secure registration through designated port health authorities. Stakeholders must monitor evolving clean-label definitions across these jurisdictions, as regulatory reinterpretation of "natural" versus "synthetic" process routes threatens to reclassify established stearoyl lactylate grades and redirect procurement specifications.
Market Dynamics
Bakery chains in North America and Europe are accelerating clean-label emulsifier procurement, forcing stearoyl lactylate suppliers to reconfigure process documentation and purity certification workflows around EFSA and FDA traceability mandates.
Growth Catalysts
- GRAS Affirmation Pathway:The FDA's 21 CFR 172.846 framework validates sodium stearoyl lactylate for broad food applications, reducing regulatory friction for commercial bread producers seeking ingredient approval.
- Industrial Bakery Automation:Large-scale automated dosing systems at commercial bakeries favor liquid stearoyl lactylate formats, creating pull-through demand for precision-delivery emulsifier systems.
- E481 Reauthorization Momentum:EFSA's ongoing food additive reassessment under EU Regulation 1333/2008 is consolidating supplier qualification requirements, advantaging pre-certified producers with established purity documentation.
Market Restraints
- Stearic Acid Feedstock Volatility:Vegetable oil price swings directly compress emulsifier margins, as palm and soybean oil markets transmit cost pressure through the esterification supply chain.
- Fermentation-Derived Substitution:Corbion's bio-based alternatives compete on clean-label positioning, threatening petrochemical-route stearoyl lactylates in premium bakery segments willing to absorb higher unit costs.
- Cross-Border Registration Friction:China's SAMR GB standards require foreign producers to secure port-specific health authority registrations, extending time-to-market for non-domestic suppliers.
Strategic Opportunities
- Pharmaceutical-Grade Excipient Expansion:Tablet binder and controlled-release applications command superior margins versus food-grade volumes, with compounding pharmacies driving specification upgrades.
- Domestic Esterification Capacity in China:Shanghai-area production additions are narrowing import dependence, creating partnership openings for technology licensors and engineering contractors.
- Clean-Label Definition Arbitrage:Divergent regulatory interpretations of "natural" process routes across FDA, EFSA, and SAMR jurisdictions allow suppliers to position identical chemistries under varying claim frameworks.
Industry Challenges
- HLB Specification Tightening:Automated bakery systems demand narrower 8-12 HLB value ranges, requiring process control investments that strain mid-scale producers without captive laboratory infrastructure.
- Acid Value Documentation Burden:60-120 mg KOH/g certification requirements for each production lot multiply analytical chemistry overhead, particularly for powder-format specialists serving fragmented artisan bakery channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stearoyl Lactylates Market |
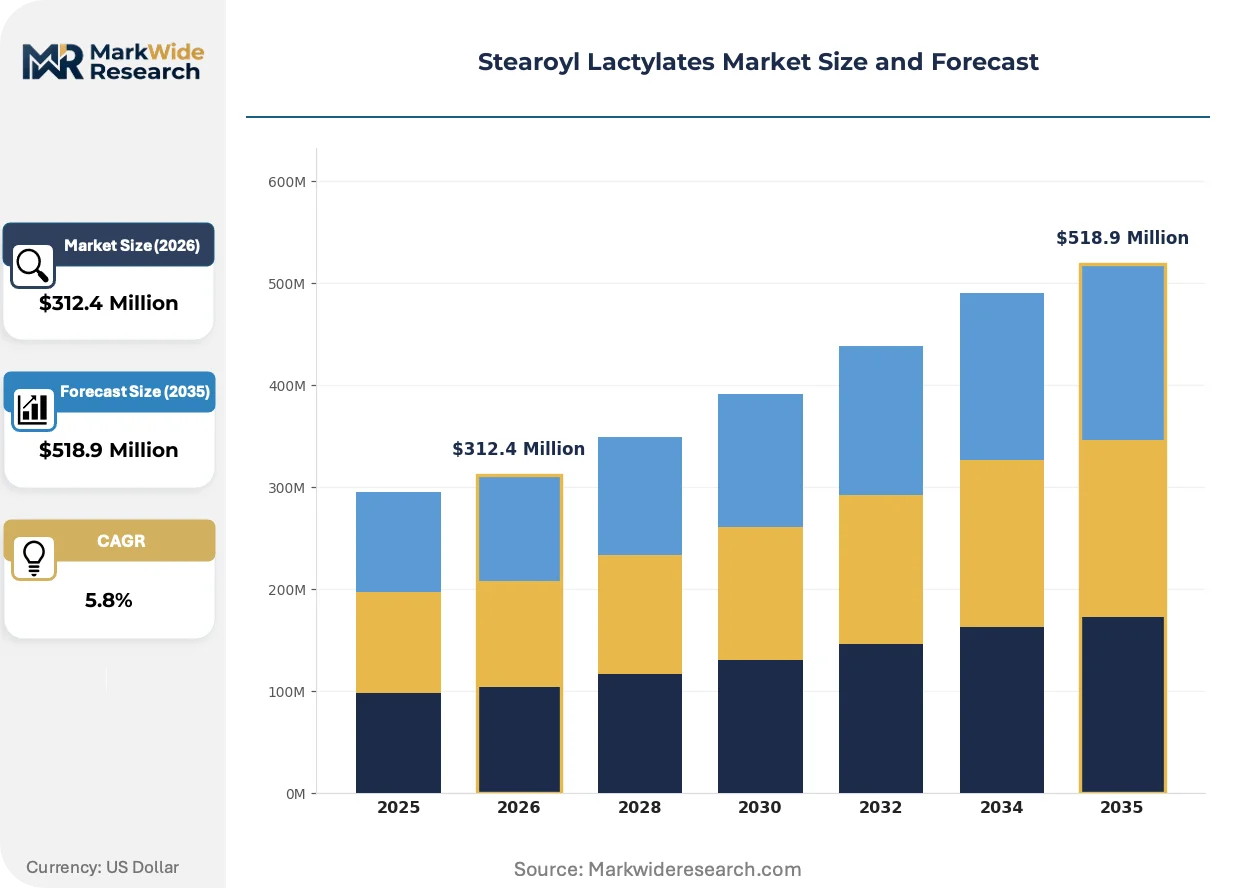
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Application: Baked Goods, Dairy Products, Confectionery, Personal Care Delivery Mode: Liquid, Powder, Granular, Paste End User: Food Manufacturers, Cosmetic Brands, Pharmaceutical Companies, Contract Manufacturers |
| Companies Covered | Palsgaard A/S, Archer Daniels Midland Company, Cargill, DuPont de Nemours, Ingredion Incorporated, Corbion, Kerry Group, Stepan Company, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stearoyl Lactylates Market Evolving Landscape
Process transparency and delivery-format flexibility are reshaping competitive positioning in stearoyl lactylate supply, with automation compatibility and regulatory pre-certification emerging as primary vendor selection criteria.
Enzymatic esterification is hybridizing conventional chemical synthesis routes, enabling producers to document milder process conditions for clean-label claims. Industrial bakeries in Germany and the Netherlands are piloting these variants for private-label bread lines. The technology is compressing the cost premium between petrochemical and fermentation-derived emulsifiers.
EFSA's E481 reauthorization timeline is compressing supplier consolidation, as smaller producers lacking enhanced purity documentation exit the EU market. The industrial consequence is qualification bottlenecking at major bakery chains. Powder-format specialists serving artisan channels face the steepest compliance cost escalation.
Automated procurement platforms are displacing traditional distributor relationships in North American commercial baking. Large-scale manufacturers now direct-source emulsifier volumes through integrated supply chain portals, extracting price transparency and lot-traceability guarantees. This pattern concentrates most visibly in the United States, where regional bakery cooperatives aggregate purchasing power.
Stearoyl Lactylates Market Segmentation
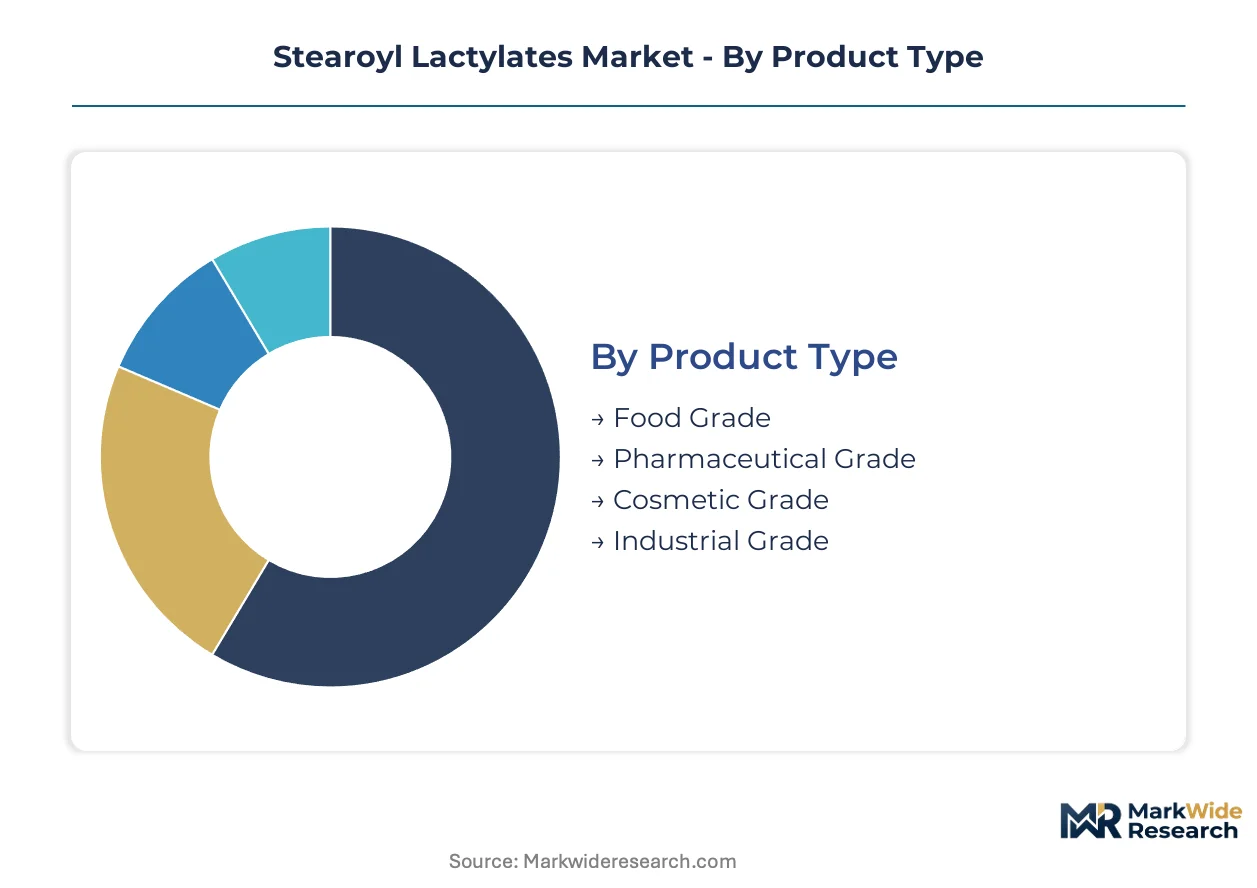
Stearoyl lactylate suppliers configure product portfolios around purity tiers and delivery formats that match distinct customer technical requirements. Segmentation discipline separates high-margin pharmaceutical excipients from commodity food-grade volumes while accommodating automation trends in industrial baking.
Product Type:
Mature grades dominate current revenue, though emerging specifications are capturing margin expansion in specialized applications.
- Food Grade:Standardized emulsifiers with acid values between 60-120 mg KOH/g serve commercial bread production. FDA's GRAS affirmation under 21 CFR 172.846 locks in procurement volumes at North American bakery chains facing clean-label compliance deadlines.
- Pharmaceutical Grade:Higher-purity variants function as tablet binders and controlled-release excipients in compounding pharmacy applications. Demand concentrates at specialty chemical distributors serving United States pharmaceutical compounders seeking enhanced documentation packages.
- Cosmetic Grade:Refined specifications for emulsion stability in skin-care formulations.
- Industrial Grade:Cost-optimized variants for non-food surfactant applications.
Food Grade handles the majority of throughput; Pharmaceutical Grade is the fastest mover on share.
Application:
Volume concentration tracks end-use automation levels and regulatory exposure intensity across consumer-facing sectors.
- Baked Goods:Dough conditioning and crumb softening in industrial bread lines. Large-scale automated dosing systems at United States commercial bakeries favor liquid formats with precise HLB value control.
- Dairy Products:Emulsion stabilization in processed cheese and whipped toppings. EFSA's E481 reauthorization under EU Regulation 1333/2008 is tightening purity documentation requirements for European dairy processors.
- Confectionery:Fat bloom inhibition in chocolate coatings.
- Personal Care:Surfactant functionality in lotion and cream formulations.
Baked Goods commands the largest volume position; Dairy Products is expanding most quickly as clean-label reformulation accelerates.
Delivery Mode:
Format selection reflects logistics economics against dosing precision requirements in customer manufacturing environments.
- Liquid:Pumpable emulsifier systems for automated bakery dosing equipment. German and Dutch industrial bakeries are piloting enzymatic-process variants in liquid format for private-label bread lines.
- Powder:Dry-flowing material for bulk handling and extended shelf stability. Powder specialists serving fragmented artisan bakery channels face steepest analytical chemistry overhead from acid value certification requirements.
- Granular:Low-dust handling characteristics for intermediate-scale food manufacturers.
- Paste:Semi-solid consistency for specialized compounding applications.
Powder maintains the highest shipment volumes; Liquid is climbing the fastest as automation penetration deepens.
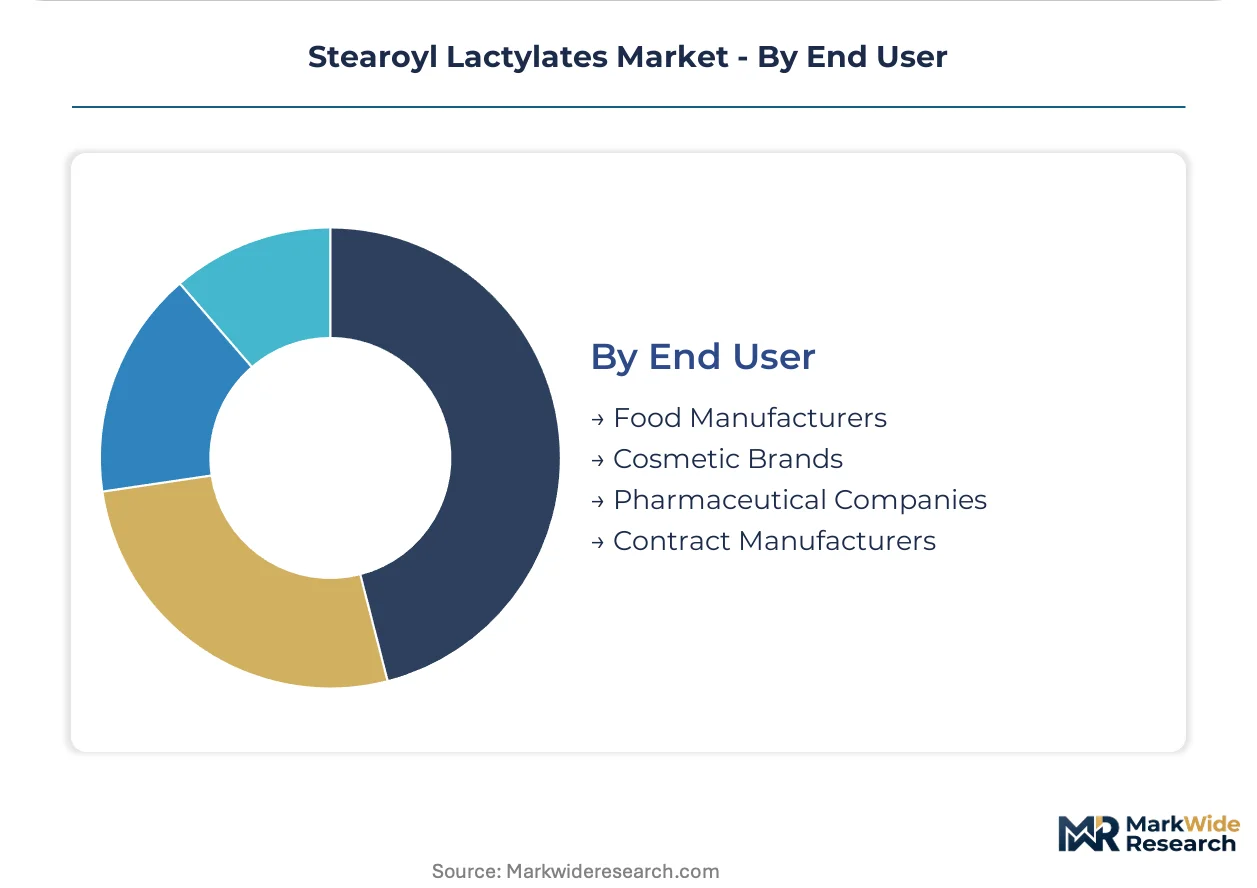
End User:
Customer type determines specification stringency, contract structure, and supplier qualification pathway complexity.
- Food Manufacturers:Industrial bakeries and processed food producers purchasing bulk emulsifier volumes. United States regional bakery cooperatives now aggregate procurement through automated supply chain portals demanding lot-traceability guarantees.
- Cosmetic Brands:Formulators seeking emulsion stability with mildness claims.
- Pharmaceutical Companies:Drug manufacturers requiring excipient-grade documentation for tablet and capsule applications.
- Contract Manufacturers:Toll producers serving multiple brand owners with flexible specification capabilities.
Food Manufacturers represent the dominant demand source; Pharmaceutical Companies show the steepest expansion trajectory as excipient outsourcing grows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk handling infrastructure underwrites Europe's emulsifier trade position, while Shanghai's Yangshan deepwater complex anchors Asia-Pacific esterification capacity expansion.
United States
Commercial bakery cooperatives in the Midwest and Southeast aggregate procurement through automated supply chain portals. FDA's GRAS framework under 21 CFR 172.846 streamlines ingredient approval for industrial bread producers. Chicago and Minneapolis-St. Paul host concentrated toll manufacturing capacity serving regional bakery chains.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia pilot enzymatic-process emulsifier variants for private-label bread lines. EFSA's E481 reauthorization under EU Regulation 1333/2008 tightens purity documentation requirements. The Hamburg-Bremen port cluster handles bulk stearic acid feedstock imports for domestic esterification operations.
China
Domestic esterification capacity additions near Shanghai reduce dependence on imported stearoyl lactylate intermediates. SAMR's GB standards for food emulsifiers require foreign producers to secure port-specific health authority registrations. Yangtze River Delta chemical parks concentrate backward-integrated vegetable oil processing for captive stearic acid supply.
Netherlands
Rotterdam's liquid bulk terminals enable cost-efficient stearic acid import logistics for European emulsifier manufacturers. EFSA jurisdiction over E481 additive coding mandates enhanced supply chain traceability documentation. The Eindhoven-Tilburg corridor hosts specialty chemical distributors serving German and Belgian bakery chains.
India
Processed cheese and bakery sector expansion in Maharashtra and Gujarat drives food-grade emulsifier demand growth. FSSAI's food additive regulations align with Codex Alimentarius standards while imposing domestic labeling requirements. The Mundra-JNPT port corridor on the west coast facilitates palm-derived stearic acid imports from Southeast Asia.
Stearoyl Lactylates Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and esterification technology. The supplier base organizes around three archetypes: multinational ingredient platforms with backward-integrated oilseed processing, fermentation-derived specialty chemical houses, and regional esterification contractors serving artisan bakery channels. Consolidation pressure intensifies as EFSA reauthorization deadlines eliminate smaller producers lacking enhanced purity documentation. Dominant competitive moves include strategic partnerships with automated bakery equipment vendors and capacity licensing agreements in China's Yangtze River Delta chemical parks.
Among multinational ingredient platforms, Cargill and Archer Daniels Midland occupy positions anchored by captive vegetable oil supply chains. Corbion represents the fermentation-derived alternative archetype, competing on clean-label positioning against petrochemical-route producers. BASF SE and Stepan Company sit within the specialty surfactant tier, supplying pharmaceutical-grade specifications alongside food-grade volumes.
| Leading Market Players |
|---|
| Palsgaard A/S |
| Archer Daniels Midland Company |
| Cargill |
| DuPont de Nemours |
| Ingredion Incorporated |
| Corbion |
| Kerry Group |
| Stepan Company |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Shanghai's Yangtze River Delta chemical parks concentrate domestic esterification capacity additions that compress import premiums for Chinese bakery chains while amplifying pricing power for backward-integrated vegetable oil processors serving export markets. This geographic supply concentration creates divergent pricing dynamics across procurement channels, with automated supply chain portals at United States commercial bakeries extracting transparency while European artisan channels absorb documentation cost pass-throughs.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certifications governs transaction economics, with acid value documentation and HLB precision separating premium tiers from commodity volumes. Food-grade stearoyl lactylates face margin compression from enzymatic-process alternatives piloted in German industrial bakeries, while pharmaceutical-grade excipients retain pricing resilience through compounding pharmacy demand concentration. Contract manufacturers demonstrate highest price sensitivity due to fragmented order scales, whereas multinational bakery cooperatives leverage portal-aggregated volumes for preferential terms.
Supply Chain Analysis
Export-control restrictions on fermentation-derived lactic acid technology limit technology transfer to Chinese domestic producers, constraining clean-label alternative supply expansion outside European and North American patent holders. The stearoyl lactylate supply chain draws from palm and soybean oil feedstocks concentrated in Malaysia, Indonesia, and Argentina, with stearic acid intermediates subject to vegetable oil price volatility transmission. Single-source vulnerability in pharmaceutical-grade certification documentation creates qualification bottlenecks at major bakery chains. Distribution runs through automated procurement platforms displacing traditional distributor relationships in North American commercial baking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stearoyl lactylate market rewards producers possessing captive laboratory infrastructure for HLB specification control and acid value lot certification, creating capability scarcity that separates qualified suppliers from margin-compressed commodity players. This skill gap intensifies as EFSA reauthorization deadlines eliminate smaller producers lacking enhanced purity documentation.
For Market Incumbents: Entrench qualification advantages by securing E481 pre-certification ahead of EU reauthorization deadlines and expanding enzymatic esterification capacity for clean-label claim differentiation. Corbion's fermentation-derived alternatives threaten petrochemical-route incumbents in premium bakery segments; backward integration into vegetable oil feedstocks preserves margin position against stearic acid price volatility. For New Entrants and Emerging Players: Pursue technology licensing partnerships with Shanghai-area chemical parks to capture domestic Chinese demand growth as SAMR registration requirements extend time-to-market for foreign competitors. Pharmaceutical-grade excipient specifications offer the most penetrable white-space target, with compounding pharmacy demand concentration supporting premium positioning without direct confrontation with entrenched food-grade volume leaders. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-derived specialty chemical houses with patent-protected enzymatic process routes and established EFSA documentation packages. Long-term viability hinges on clean-label claim durability across divergent regulatory interpretations of natural process definitions. The signal to monitor is EFSA's final E481 reauthorization text, which could reclassify established grades and redirect procurement specifications toward enzymatic variants.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Esterification Capacity Addition | Enables clean-label positioning for EFSA-compliant European bakery chains. |
| Backward Integration into Vegetable Oil Processing | Cargill's captive stearic acid supply secures cost advantage against feedstock volatility. |
| Pharmaceutical-Grade Certification Investment | Captures tablet binder demand from United States compounding pharmacy expansion. |
| Automated Supply Chain Portal Integration | Qualifies vendors for Midwest and Southeast bakery cooperative procurement aggregation. |
| China Domestic Esterification Licensing | Navigates SAMR port-registration friction through Yangtze River Delta partnerships. |
Research Methodology
Cross-validation between primary interviews with plant managers at esterification facilities and secondary analysis of FDA GRAS filings anchors the qualitative findings in documented regulatory pathways. The research program combined discussions with procurement leads at North American commercial bakeries, technical R&D directors at multinational ingredient platforms, and distribution channel partners serving European artisan channels. Secondary validation drew from EFSA food additive reauthorization dossiers, SEC 10-K disclosures by listed ingredient suppliers, customs trade data on stearic acid feedstock flows, and ACC sector reports on emulsifier demand trends. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down capacity assessments from domestic esterification expansions.
Calibration against historical price realization data and documented procurement contract structures shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include grade tier differentiation, delivery mode logistics economics, end-use industry automation levels, and regional regulatory cluster alignment. CAGRs were derived from elasticity-adjusted demand projections incorporating bakery sector automation penetration rates and clean-label reformulation timelines. Forecast inputs included EFSA reauthorization schedule assumptions and SAMR registration processing duration estimates for foreign producers.
Sensitivities concentrate around EFSA's final E481 reauthorization text interpretation and SAMR's enforcement posture on port-specific health authority registrations. Forecasts reflect assumptions regarding enzymatic process cost compression trajectories and vegetable oil price volatility persistence. Material shifts in clean-label regulatory definitions across FDA, EFSA, or SAMR jurisdictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Propane-1,2-Diol Esters Of Fatty Acid Market
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
US Esters Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Glycerol Diacetate Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Glycerine Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Triisostearyl Citrate Market