
 Ethyl Linalool Market | 2026-2036
Ethyl Linalool Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyl Linalool Market Foresight
Buyer concentration among multinational fragrance houses is restructuring procurement patterns across the ethyl linalool supply base. Givaudan leverages long-term supply agreements with specialty chemical producers to secure volume commitments for high-purity grades. Firmenich anchors its competitive position through backward integration into terpene feedstock processing in key European manufacturing sites. Symrise competes by specializing in customized ethyl linalool blends tailored to regional fragrance preferences.
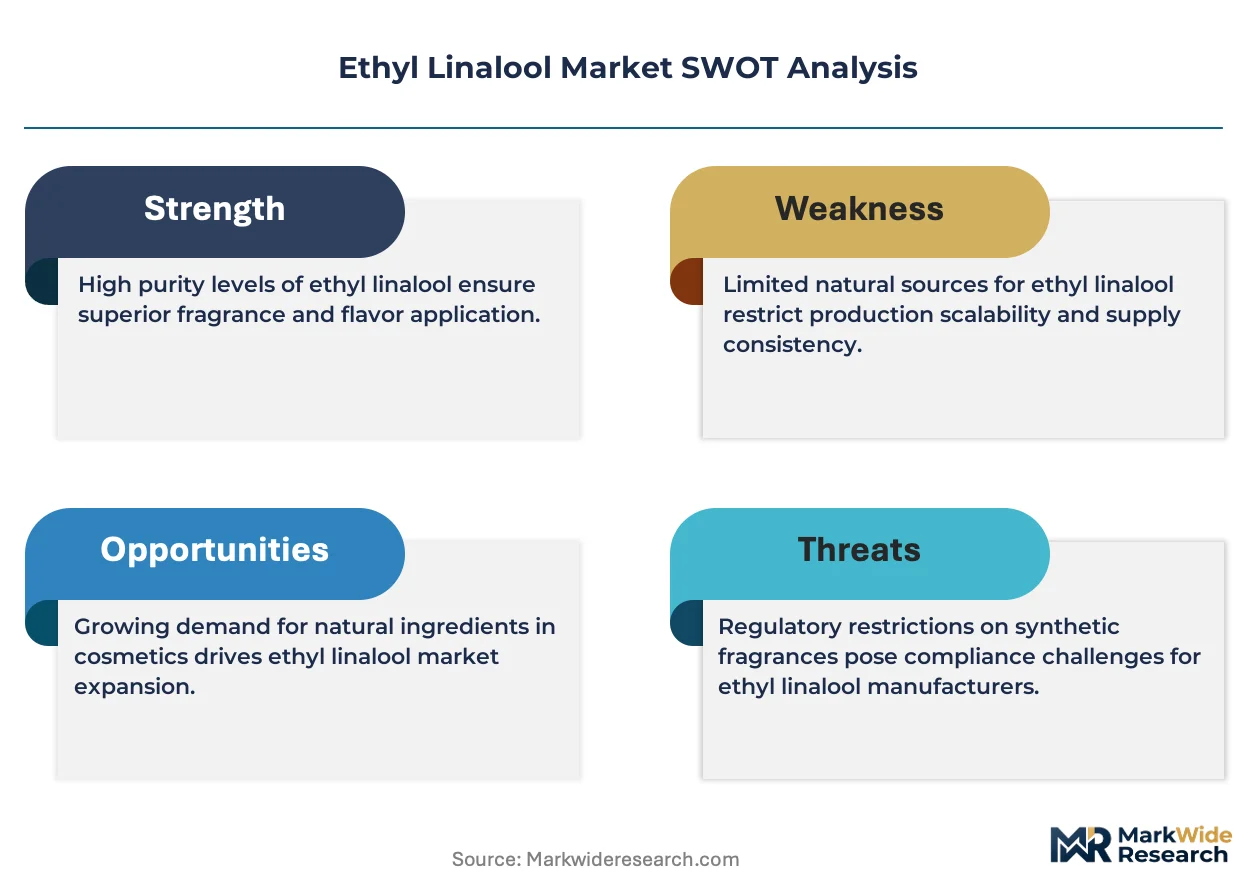
Ethyl linalool is a tertiary alcohol with a floral odor profile, synthesized via ethylation of linalool or extracted from natural essential oil fractions, and functions primarily as a fragrance ingredient and flavoring agent in consumer formulations. Synthetic ethyl linalool dominates volume throughput due to cost efficiency and consistent batch quality, while bio-based ethyl linalool captures expanding margin pools as cosmetic brands reformulate for renewable content claims. The fragrance application leads absolute consumption, though food flavoring represents a structurally higher-margin outlet where purity certifications command price premiums.
REACH registration requirements in Europe and FDA food additive regulations in the United States constrain market access for unqualified producers and elevate compliance costs for cross-border suppliers. China's SAMR and national GB standards for fragrance chemicals impose additional testing protocols on imported material. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualify alternative supply sources before compliance deadlines tighten.
Market Dynamics
Fragrance houses are consolidating procurement around bio-based ethyl linalool grades, forcing specialty chemical suppliers to restructure production footprints and certification pipelines to retain contract volumes.
Growth Catalysts
- REACH registration mandates:European ECHA compliance requirements for fragrance chemicals are filtering out unqualified producers and concentrating demand among certified suppliers with established dossiers.
- Personal care reformulation:Cosmetic manufacturers are accelerating renewable content claims by specifying bio-based ethyl linalool in fragrance compound specifications.
- China:Domestic cosmetic production scaling by Zhejiang NHU and regional formulators is expanding synthetic and natural ethyl linalool offtake for both local consumption and export fragrance compounding.
Market Restraints
- Terpene feedstock volatility:Natural linalool extraction depends on citrus and wood biomass harvest cycles, creating input cost instability that compresses margin predictability for bio-based producers.
- Supplier concentration:Synthetic ethyl linalool capacity clusters among specialty chemical producers in Germany and China, exposing buyers to geographic supply disruption risk.
- Regulatory fragmentation:Divergent FDA food additive rules, REACH purity thresholds, and China's SAMR GB standards force redundant testing and multi-jurisdiction compliance spend.
Strategic Opportunities
- Food flavoring certification:High-purity grades meeting FEMA GRAS and ISO 9001 standards command structural price premiums in beverage and confectionery applications.
- India:BIS fragrance chemical standards and expanding domestic cosmetic manufacturing create white space for qualified ethyl linalool suppliers establishing local technical service presence.
- Biotechnology convergence:Microbial fermentation routes to linalool precursors are opening pathways to fully renewable ethyl linalool with traceable carbon credentials.
Industry Challenges
- REACH dossier maintenance:Ongoing substance evaluation and data fee obligations strain mid-tier producers with limited regulatory affairs staffing.
- Process analytical chemistry expertise:Chiral purity verification and batch-to-batch consistency require specialized chromatography capabilities that compete for scarce technical talent.
- Legacy equipment retrofit costs:Existing linalool ethylation infrastructure requires capital-intensive upgrades to meet tightening emission controls under China's MEE guidelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyl Linalool Market |
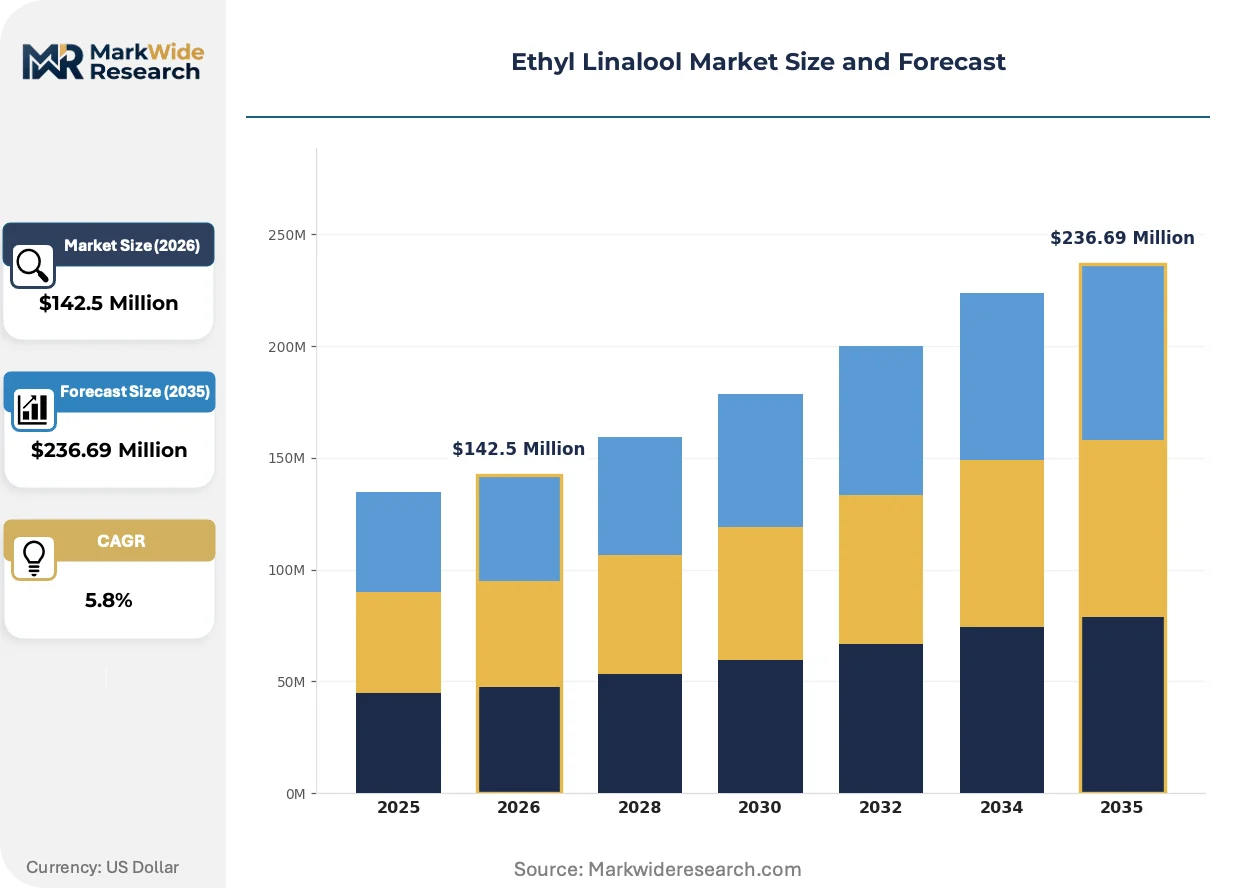
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Ethyl Linalool, Synthetic Ethyl Linalool, Bio-based Ethyl Linalool, Pure Ethyl Linalool Application: Fragrance, Food Flavoring, Cosmetics, Household Products End User: Food Industry, Personal Care Industry, Cleaning Industry, Pharmaceutical Industry Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale Distribution |
| Companies Covered | Givaudan, Firmenich, Symrise, IFF, Mane, Takasago, Robertet, Zhejiang NHU Co., Ltd, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyl Linalool Market Shifts & Advancements
Continuous processing technologies and renewable feedstock traceability systems are compressing batch cycle times while enabling carbon accounting claims that command procurement preference.
Flow chemistry reactor systems for linalool ethylation are modularizing synthetic ethyl linalool production from batch to continuous operation. Specialty chemical producers in the Netherlands and Switzerland are retrofitting pilot plants to demonstrate ton-scale throughput with reduced solvent waste. This modularization is enabling distributed manufacturing footprints closer to fragrance compounding centers, compressing logistics costs and lead times for just-in-time fragrance house procurement.
REACH authorization candidate list expansion for fragrance allergens is tightening purity specifications for ethyl linalool imports into EU manufacturing sites. ECHA's 2024-2025 substance evaluation work program targets tertiary alcohols used in consumer products, elevating analytical documentation burdens. Fragrance compounders are responding by dual-sourcing from REACH-registered suppliers with established safety data sheet libraries and toxicology packages.
Long-term supply agreements with fixed-volume, indexed-pricing structures are displacing spot market purchasing among multinational fragrance houses. Procurement teams at Givaudan, Firmenich, and Symrise are consolidating supplier panels to three to four qualified producers per region, trading price flexibility for supply security. This concentration is most visible in China, where domestic cosmetic manufacturers are mirroring multinational procurement discipline to secure feedstock for export fragrance production.
Ethyl Linalool Market Segmentation
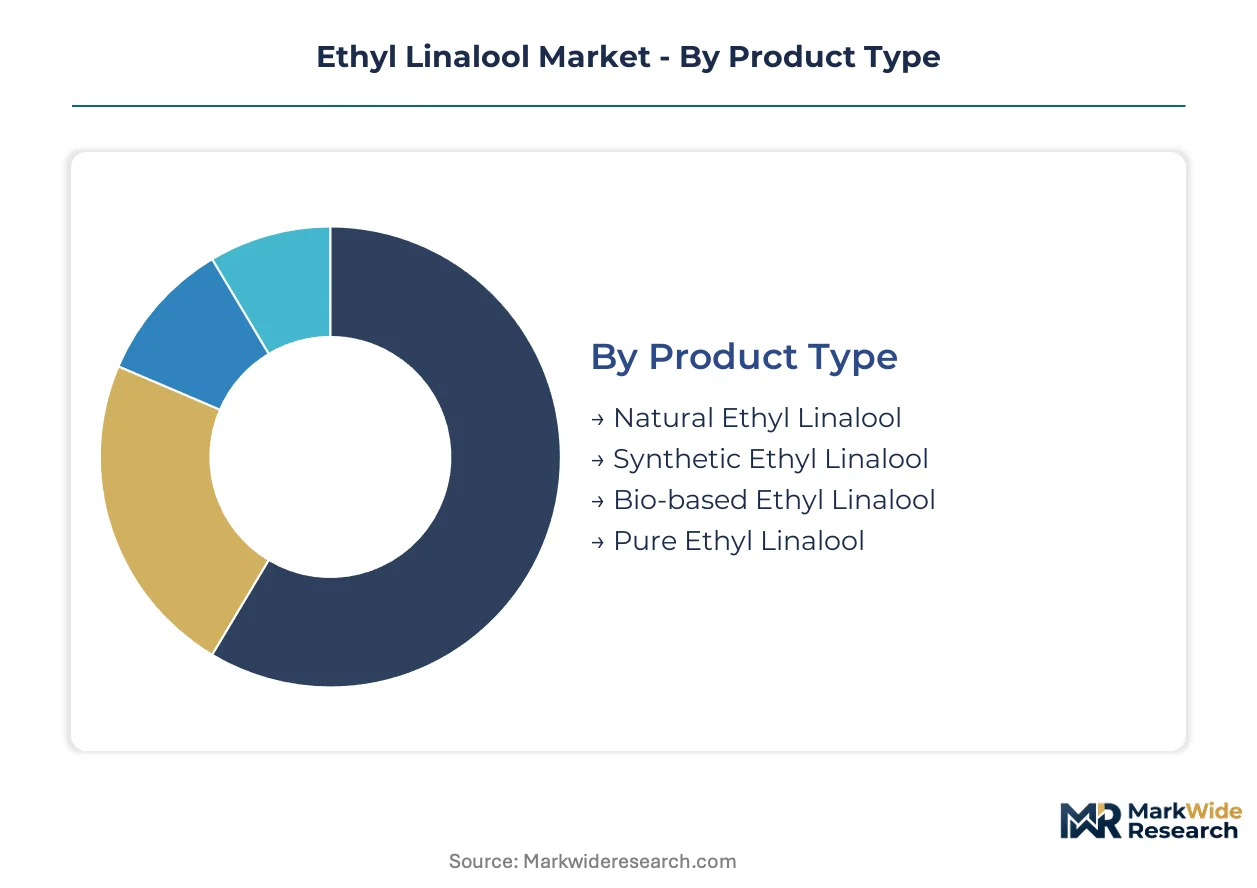
Segmentation in ethyl linalool reveals divergent margin structures across production methods and end-use specifications. Procurement teams at fragrance houses weight purity grades against renewable content claims, while food safety certifications filter supplier eligibility in high-margin flavoring applications.
Product Type:
Synthetic variants dominate tonnage throughput while bio-based grades capture expanding premium pools as cosmetic brands reformulate for traceable carbon credentials.
- Synthetic Ethyl Linalool:Manufactured via acid-catalyzed ethylation of linalool feedstock with consistent isomeric ratios and batch-to-batch uniformity. Fragrance compounders in Germany and China anchor procurement volumes here for cost-predictable base notes in mass-market personal care.
- Bio-based Ethyl Linalool:Derived from microbial fermentation of sugarcane or corn-derived precursors with verifiable renewable carbon content. L'Oréal and Unilever sustainability targets are redirecting specification sheets toward certified bio-based grades despite 15-30% price premiums.
- Natural Ethyl Linalool:Fractionally distilled from ho wood and coriander essential oils with variable terpene profiles limiting standardization.
- Pure Ethyl Linalool:Chromatography-refined to >99% chemical purity for pharmaceutical and high-end flavoring applications with strict contaminant thresholds.
Today's leader: Synthetic Ethyl Linalool. Tomorrow's challenger: Bio-based Ethyl Linalool.
Application:
Fragrance formulation consumes absolute volume while food flavoring commands structural price premiums where FEMA GRAS and ISO certifications gate market access.
- Fragrance:Primary outlet incorporating ethyl linalool as a floral-woody middle note in fine perfumes, functional fragrances, and air care products. Givaudan and Firmenich compound annual requirements in the thousands of metric tons for European and Asian manufacturing.
- Food Flavoring:High-purity grades flavor beverages, confectionery, and savory applications with sensory thresholds measured in parts per million. FDA food additive regulations and EFSA flavoring evaluations impose toxicology documentation burdens that concentrate supply among dossier-complete specialists.
- Cosmetics:Skincare and color cosmetic formulations leverage ethyl linalool for scent masking and product identity in leave-on and rinse-off applications.
- Household Products:Surface cleaners, laundry detergents, and air fresheners specify economical synthetic grades where odor intensity outweighs longevity requirements.
Fragrance holds volume dominance. Food flavoring posts the steepest expansion trajectory as clean-label positioning drives natural and bio-based ingredient substitution.
End User:
Personal care manufacturers consolidate procurement around audited suppliers while pharmaceutical qualification timelines extend supplier relationships across decade-long horizons.
- Personal Care Industry:Cosmetic and toiletry manufacturers specify ethyl linalool in shampoos, lotions, and deodorants with REACH-compliant safety data sheets mandatory for EU market access.
- Food Industry:Beverage and processed food producers require FEMA GRAS-listed or FDA-approved flavoring substances with lot traceability and contaminant testing protocols.
- Cleaning Industry:Institutional and consumer cleaning product formulators prioritize cost-efficient synthetic grades with functional fragrance performance over ingredient provenance claims.
- Pharmaceutical Industry:Oral care and topical drug manufacturers demand pharmacopeial-grade material with elemental impurity profiles meeting ICH Q3D guidelines.
Personal care anchors current procurement volumes. Pharmaceutical qualification represents the longest-term contract horizon with highest switching costs.
Distribution Channel:
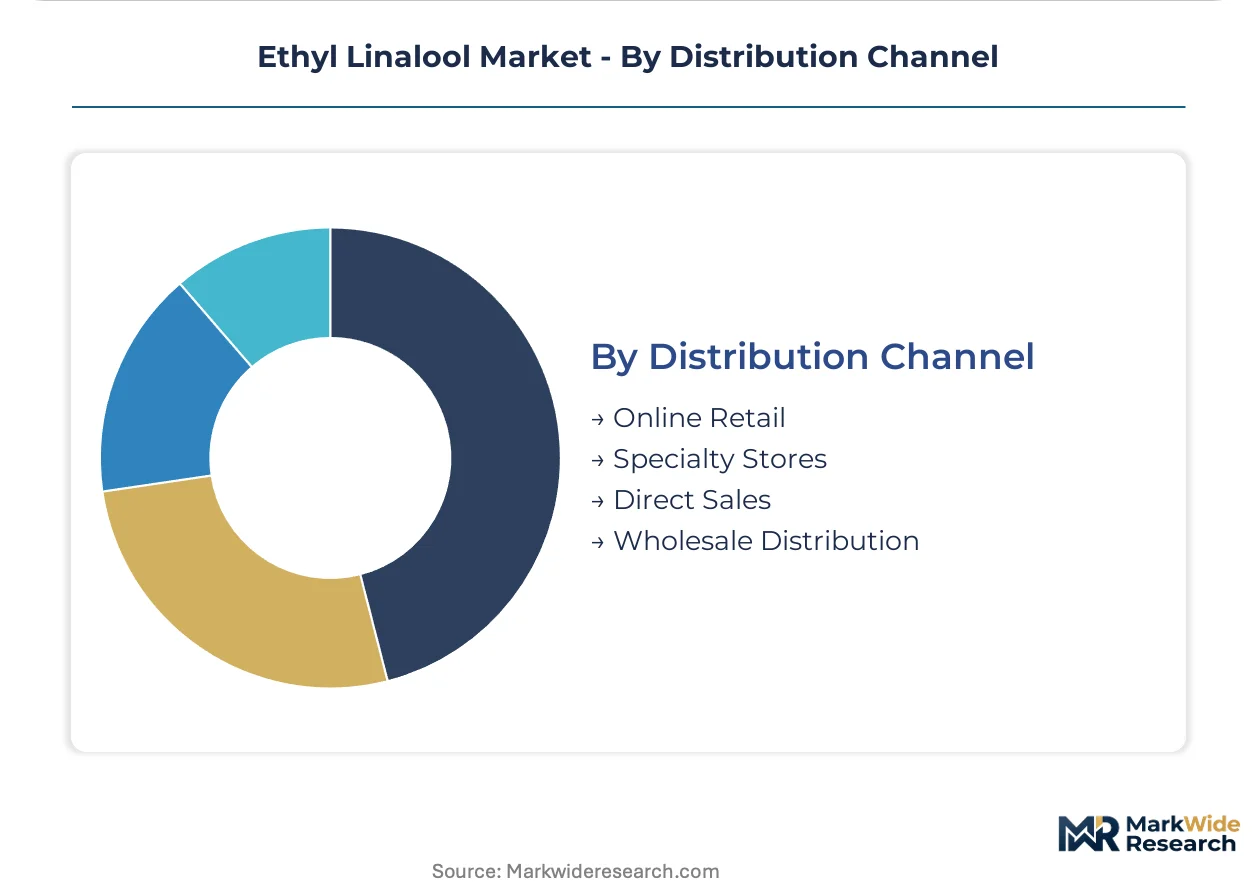
Direct sales relationships dominate bulk chemical procurement while specialty stores serve small-batch artisan formulators with minimum order quantities below one metric ton.
- Direct Sales:Long-term supply agreements between fragrance houses and specialty chemical producers with fixed-volume, indexed-pricing structures and dedicated account management.
- Wholesale Distribution:Regional chemical distributors inventory standard grades for mid-tier cosmetic manufacturers without direct supplier relationships.
- Online Retail:E-commerce platforms serve independent perfumers and small cosmetic brands with packaged quantities and technical documentation downloads.
- Specialty Stores:Fragrance raw material suppliers in Grasse, Paris, and New York City serve atelier customers with curated essential oil and aroma chemical selections.
Direct sales capture the largest contract values. Online retail is gaining share fastest among emerging indie beauty brands bypassing traditional procurement hierarchies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineers and fragrance compounders concentrate in Basel, Grasse, and Shanghai, anchoring regional production clusters that supply multinational formulation houses with certified ethyl linalool grades.
China
Zhejiang NHU and domestic cosmetic manufacturers scale synthetic and natural production capacity to serve both local consumption and export fragrance compounding. SAMR and national GB standards for fragrance chemicals impose additional testing protocols on imported material. The Yangtze River Delta hosts concentrated specialty chemical infrastructure where producers retrofit legacy equipment to meet tightening emission controls under MEE guidelines.
Germany
Specialty chemical producers anchor synthetic ethyl linalool capacity with established REACH dossiers and acid-catalyzed ethylation infrastructure. ECHA compliance requirements for fragrance chemicals filter out unqualified producers and concentrate demand among certified suppliers. The Rhine-Ruhr and Bavarian chemical corridors house backward-integrated terpene feedstock processing operations serving European fragrance compounders.
United States
Fragrance houses specify high-purity grades for personal care reformulation targeting renewable content claims. FDA food additive regulations and FEMA GRAS listing requirements impose toxicology documentation burdens that concentrate supply among dossier-complete specialists. The New Jersey-Pennsylvania chemical belt and Texas Gulf Coast host formulation centers and distribution infrastructure for North American procurement.
France
Grasse-based fragrance compounders source ethyl linalool for fine perfume and functional fragrance applications with strict contaminant thresholds. REACH registration mandates and ECHA substance evaluation programs elevate analytical documentation burdens for tertiary alcohols used in consumer products. The Provence-Alpes-Côte d'Azur region maintains historic aroma chemical expertise with technical service capabilities for artisan and industrial formulators.
Switzerland
Geneva and Basel headquarters of multinational fragrance houses drive procurement consolidation around long-term supply agreements with fixed-volume, indexed-pricing structures. Swissmedic and EU regulatory alignment through bilateral agreements streamline cross-border chemical trade. The Basel-Ludwigshafen chemical corridor enables just-in-time delivery to European compounding centers with reduced logistics lead times.
Ethyl Linalool Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across synthetic and bio-based production vectors. The market exhibits tiered concentration with multinational fragrance houses anchoring demand and specialty chemical producers supplying certified grades. Three archetypes dominate: backward-integrated terpene processors, synthetic aroma chemical specialists, and biotechnology-enabled renewable producers. Competitive moves center on long-term supply agreement consolidation and fermentation route development for traceable carbon credentials.
Among Switzerland-based fragrance houses, Givaudan and Firmenich occupy positions as demand-side anchors consolidating procurement panels to three to four qualified producers per region. Zhejiang NHU Co., Ltd exemplifies the China-based specialty chemical producer archetype with scaled synthetic capacity serving both domestic cosmetic manufacturers and export markets. These named entities represent the competitive tension between established synthetic producers and emerging bio-based challengers reshaping specification standards.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich |
| Symrise |
| IFF |
| Mane |
| Takasago |
| Robertet |
| Zhejiang NHU Co., Ltd |
| BASF SE |
| Others |
Supply & Pricing Matrix
Flow chemistry reactor modularization is compressing batch cycle times while redistributing production footprints closer to fragrance compounding centers, simultaneously lowering unit economics for continuous-process synthetic grades and fragmenting geographic supply concentration away from legacy German and Chinese batch plants.
Pricing Analysis
Certification bundling versus unbundled base-chemical supply splits procurement economics across fragrance house panels. Three-tier pricing structure across premium, standard, and economy levels anchors on purity certification and renewable content verification, with bio-based grades from microbial fermentation routes commanding 15-30% premiums over synthetic benchmarks. Cost compression in standard synthetic tiers is intensifying because Zhejiang NHU and domestic Chinese producers are scaling acid-catalyzed ethylation capacity for export markets. Mid-tier cosmetic manufacturers exhibit highest price sensitivity, while pharmaceutical qualification timelines make drug manufacturers least elastic to spot price movements.
Supply Chain Analysis
Ocean freight rate volatility and Yangtze River Delta port congestion are elevating landed costs for European fragrance compounders sourcing from Chinese synthetic producers. Supply concentrates in Germany, China, and Switzerland, with backward-integrated terpene processing in the Rhine-Ruhr corridor and Basel-Ludwigshafen chemical corridor feeding just-in-time requirements. Natural linalool extraction draws from citrus biomass harvest cycles in Brazil and wood distillation in Southeast Asia, creating input cost instability. Single-source vulnerability runs through Zhejiang NHU's dominant synthetic capacity share. Distribution runs through direct long-term supply agreements with fixed-volume, indexed-pricing structures displacing spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH authorization candidate list expansion for fragrance allergens is concentrating demand among dossier-complete suppliers with established toxicology packages and ECHA-compliant safety data sheet libraries.
For Market Incumbents: To counter biotechnology-enabled renewable producers capturing margin pools from L'Oréal and Unilever sustainability targets, Firmenich and Givaudan should deepen backward integration into terpene feedstock processing at European manufacturing sites and accelerate REACH dossier maintenance investments to filter mid-tier competitors from procurement panels.
For New Entrants and Emerging Players: BIS fragrance chemical standards in India open a window for qualified suppliers establishing local technical service presence, with white space concentrated in mid-tier cosmetic manufacturers bypassing multinational procurement hierarchies and food flavoring applications where FEMA GRAS certification gates premium pricing.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier synthetic producers facing REACH data fee obligations and emission control retrofit costs under China's MEE guidelines. Five-to-ten-year viability hinges on fermentation route development for traceable carbon credentials. The signal to watch is microbial fermentation scale-up announcements from Netherlands and Switzerland pilot plant operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Terpene Feedstock | Firmenich anchors competitive position through captive supply of linalool precursors at key European sites. |
| REACH Dossier Consolidation | ECHA compliance requirements filter unqualified producers and concentrate procurement among certified suppliers. |
| Microbial Fermentation Scale-Up | Biotechnology routes to linalool precursors enable fully renewable ethyl linalool with traceable carbon credentials. |
| Long-Term Supply Agreement Restructuring | Givaudan leverages fixed-volume, indexed-pricing structures to secure volume commitments for high-purity grades. |
| Regional Technical Service Expansion | India's BIS standards create white space for suppliers establishing local presence among domestic cosmetic manufacturers. |
Research Methodology
Multiple input streams — fragrance house procurement leads, specialty chemical plant managers, regulatory affairs directors at ECHA-registered suppliers, and customs trade data — were reconciled through bottom-up and top-down triangulation. Primary interviews with Givaudan, Firmenich, and Symrise procurement teams, Zhejiang NHU technical sales directors, and Grasse-based compounders were cross-validated against secondary sources including REACH registration databases, FDA food additive filings, SAMR GB standard publications, and SEC 10-K disclosures from diversified chemical conglomerates.
Historical volume trajectories were cross-referenced against panel input from fragrance compounders and fermentation technology developers to anchor projections across the analysis window. Segmentation dimensions modeled include production method tier, application specification, end-use industry qualification, and regional regulatory cluster. CAGRs were derived from supply-side capacity announcements, demand-side procurement contract visibility, and substitution elasticity estimates for bio-based versus synthetic grades.
Revisions become necessary when REACH substance evaluation timelines accelerate, China's MEE emission controls tighten retroactively, or microbial fermentation routes achieve cost parity with acid-catalyzed ethylation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Global Oxidized Polyethylene Wax Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Europe Wax Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Propane-1,2-Diol Esters Of Fatty Acid Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Oleyl Alcohol Market
Oleochemicals
Pentalide (Cyclopentadecanolide) Market
Oleochemicals
Petrolatum Market
Oleochemicals
Cetyl Esters Market
Oleochemicals
Global Wax Market
Oleochemicals
1-Decene Market
Oleochemicals
Tallow Amine Market
Oleochemicals
Isopropyl Esters Market