
 Canada Pallets Market | 2026-2036
Canada Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Pallets Market Insights
RFID-enabled pallet tracking is reconfiguring how Canadian supply chains manage inventory visibility and asset recovery. UFP Industries Inc. leverages its national manufacturing footprint to sustain bulk supply contracts with major retailers across provincial distribution hubs. St. Boniface Pallet Company anchors its competitive position through specialized hardwood block pallet production serving Manitoba's agricultural processing sector. Enviro Pallet Recovery Ltd. differentiates by operating closed-loop recovery systems that extend pallet lifecycle value for cost-sensitive industrial buyers.
A pallet is a portable, horizontal platform typically constructed from wood, plastic, or composite materials, designed with top deck boards and bottom stringers or blocks to permit forklift or pallet jack entry from multiple sides, with standard dimensions of 48 by 40 inches dominating North American freight compatibility. Its primary commercial purpose is to consolidate goods into unit loads that streamline mechanical handling, storage density, and intermodal transfer across warehouses, trucks, and rail cars. Wood material still dominates Canadian pallet consumption due to low input costs and established repair infrastructure, though plastic pallets are capturing share in pharmaceutical and cold storage applications where washability and dimensional consistency command premium positioning. Block-type construction leads in automated handling environments because four-way entry reduces forklift maneuvering time, while stringer designs persist in traditional warehousing where two-way access suffices and purchase price sensitivity remains acute.
Health Canada enforces pharmaceutical distribution standards that mandate contamination-resistant pallet surfaces for drug shipments, directly elevating plastic and composite specifications in that end-use channel. The Canadian Food Inspection Agency's Safe Food for Canadians Regulations impose traceability requirements that push food and beverage handlers toward standardized, trackable pallet pools rather than informal wood exchanges. The Canadian Standards Association maintains structural integrity benchmarks for pallet load ratings that influence procurement specifications for heavy manufacturing and chemical sector buyers. Stakeholders must weigh capital allocation between wood repair networks and plastic pool investments as regulatory pressure intensifies on hygienic, traceable load platforms.
Market Dynamics
Health Canada's contamination-resistant mandates and the Canadian Food Inspection Agency's traceability rules are compressing demand toward hygienic, trackable pallet platforms, forcing capital reallocation from wood repair networks to plastic pool systems.
Growth Catalysts
- Cold chain expansion:Pharmaceutical distributors and frozen food operators across Ontario and British Columbia are scaling pallet fleets to meet temperature-controlled logistics requirements.
- RFID integration:Asset tracking technology is enabling real-time inventory visibility and reducing pallet loss rates for third-party logistics providers.
- Safe Food for Canadians Regulations:The Canadian Food Inspection Agency's traceability mandates are pushing food handlers toward standardized, trackable pallet pools.
Market Restraints
- Lumber price volatility:Softwood input costs fluctuate with British Columbia timber supply constraints and US trade duty impacts.
- Plastic pallet capex burden:Premium pricing for hygienic surfaces limits adoption among cost-sensitive agricultural processors in Manitoba.
- Repair infrastructure lock-in:Established wood pallet refurbishment networks in the Greater Toronto Area resist full conversion to composite alternatives.
Strategic Opportunities
- Closed-loop recovery systems:Industrial buyers in Alberta's chemical sector seek lifecycle extension services to reduce per-trip platform costs.
- Automated handling convergence:Block-type four-way entry designs align with warehouse robotics deployment in Quebec distribution corridors.
- Provincial warehousing consolidation:Third-party logistics network rationalization in the Greater Toronto Area creates pooled fleet management demand.
Industry Challenges
- Hygiene certification timelines:Pharmaceutical-grade surface validation under Health Canada Good Manufacturing Practice standards extends procurement cycles.
- Legacy system integration:RFID-enabled asset tracking requires retrofitting existing warehouse management systems in established distribution facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Pallets Market |
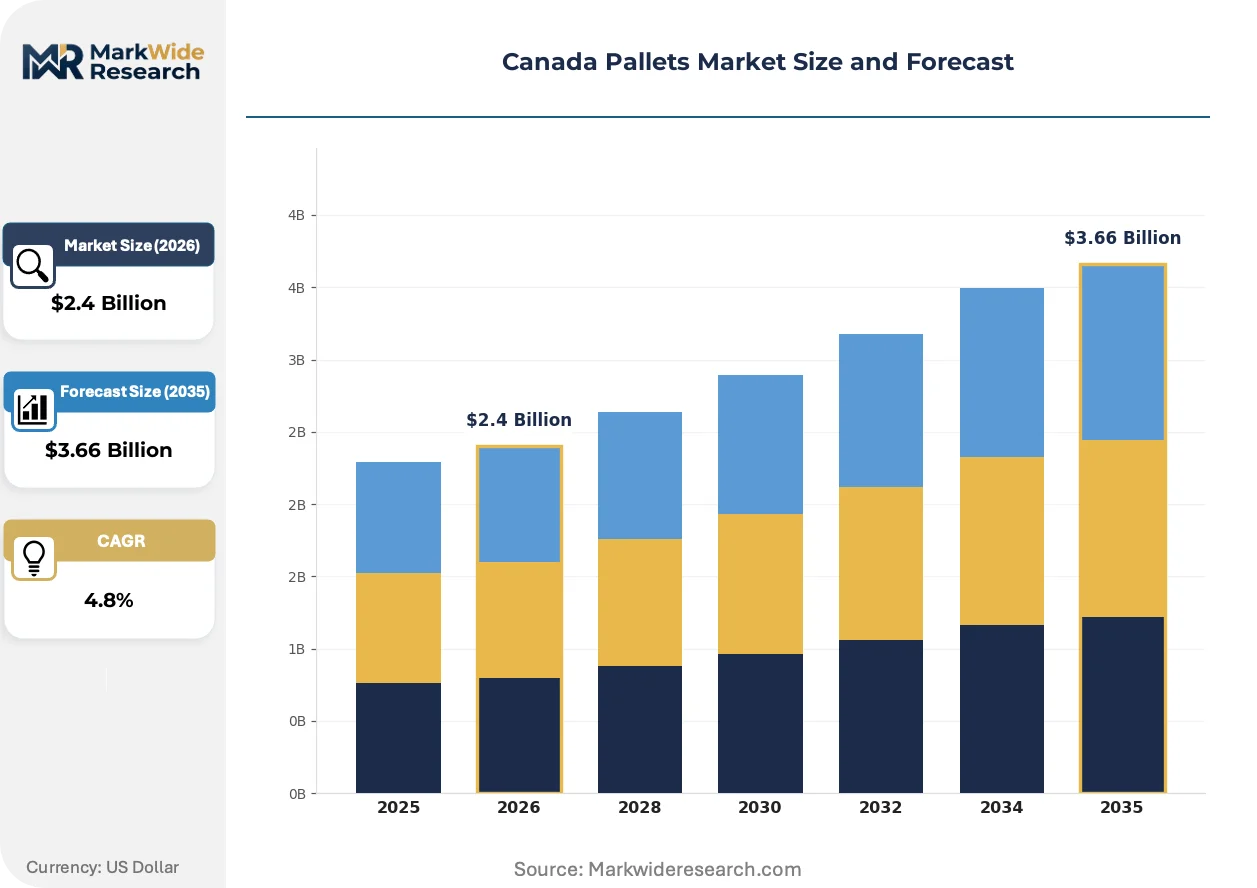
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Plastic, Metal, Composite, Corrugated Fiberboard Type: Block, Stringer, Double Face, Single Face, Reversible Application: Manufacturing, Warehousing, Transportation, Export, Cold Storage End User: Food & Beverage, Pharmaceuticals, Electronics, Chemicals, Construction |
| Companies Covered | Trican Packaging Inc., St. Boniface Pallet Company, UFP Industries Inc., Canada Pallet Source, Pallet Management Group Inc., Enviro Pallet Recovery Ltd., Bluewater Pallet Inc., Verbeek Pallet Supply Co. Ltd., Alberta Pallet Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Pallets Market Trends and Innovations
Canadian pallet supply chains are converging around digital asset tracking, regulatory hygiene mandates, and pooled fleet economics that favor standardized platforms over informal exchange networks.
RFID-enabled pallet identification is virtualizing inventory management across pharmaceutical and cold storage operations. Major distributors in Ontario are deploying tagged block pallets to automate yard management and reduce manual scanning labor. This virtualization is compressing asset recovery cycles and enabling dynamic pool sizing based on real-time demand signals.
The Canadian Food Inspection Agency's Safe Food for Canadians Regulations are mandating lot-level traceability for food-contact surfaces. Handlers must maintain documented chain-of-custody records that informal wood exchanges cannot satisfy. Cold storage operators in British Columbia are responding by migrating to certified plastic pool programs with embedded serialization.
Third-party logistics buyers are consolidating supplier relationships around full-service fleet management contracts. Single-source pallet pooling with maintenance and recovery obligations is displacing spot-market wood procurement in the Greater Toronto Area warehousing corridor. This concentration is most visible among pharmaceutical distributors facing Health Canada audit requirements for contamination control documentation.
Canada Pallets Market Segmentation

Canadian pallet procurement patterns diverge sharply across material classes and handling specifications. Cold storage operators in British Columbia prioritize washability over upfront cost, while Manitoba agricultural processors resist premium materials despite regulatory pressure. Understanding these segment-specific trade-offs reveals where substitution economics favor plastic over wood.
Material:
Wood pallets turn over fastest through informal repair networks in the Greater Toronto Area, while plastic and metal platforms cycle slowly through closed-loop pool systems. Composite materials occupy an intermediate position with moderate replacement frequency tied to certification renewal schedules.
- Wood:Softwood and hardwood construction dominates Canadian pallet consumption due to established refurbishment infrastructure across Ontario and Quebec. Manitoba agricultural processors and Quebec manufacturing facilities rely on wood's low per-trip cost despite Health Canada contamination-resistant mandates pushing pharmaceutical handlers toward alternatives.
- Plastic:Injection-molded and thermoformed platforms command premium positioning in pharmaceutical distribution and frozen food chains where the Canadian Food Inspection Agency's traceability rules require documented hygienic surfaces. British Columbia cold storage operators are expanding plastic fleets to meet drug shipment standards under Health Canada Good Manufacturing Practice protocols.
- Metal:Steel and aluminum constructions serve heavy manufacturing and chemical sector applications requiring extreme load ratings beyond wood or plastic capacity.
- Composite:Engineered wood-plastic blends target export applications needing ISPM-15 compliance without hardwood scarcity constraints.
- Corrugated Fiberboard:Lightweight paper-based platforms handle single-trip air freight and retail display applications where return logistics prove uneconomical.
Wood dominates installed base. Plastic is where expansion concentrates.
Type:
Cost tiers separate automated handling environments from manual operations. Block construction commands price premiums for four-way entry flexibility, while stringer designs maintain economy positioning.
- Block:Four-way entry construction permits forklift access from all sides, reducing maneuvering time in automated warehouse environments. Quebec distribution corridors deploying robotics favor block pallets for compatibility with automated storage and retrieval systems.
- Stringer:Two-way entry designs with parallel bottom boards persist in traditional warehousing where purchase price sensitivity outweighs handling efficiency gains. Ontario third-party logistics providers with established manual operations retain stringer specifications for cost containment.
- Double Face:Top and bottom deck surfaces support reversible loading and enhanced stability for rack storage applications.
- Single Face:One-sided platforms serve lightweight, stackable loads in retail backroom and display staging contexts.
- Reversible:Identical top and bottom deck construction permits either surface to bear loads, extending useful life in high-rotation pool systems.
Stringer designs anchor volume procurement. Block configurations are climbing the fastest as automation spreads.
Application:
Volume concentrates in warehousing and manufacturing, while margin concentrates in cold storage and export certification.
- Manufacturing:Heavy industrial loads require CSA-rated structural integrity for chemical and automotive component shipping.
- Warehousing:The Greater Toronto Area's third-party logistics consolidation drives pooled fleet demand for standardized platforms.
- Transportation:Intermodal compatibility demands 48-by-40-inch dimensional consistency across truck and rail interfaces.
- Export:ISPM-15 heat treatment mandates favor plastic and composite alternatives to avoid hardwood documentation burdens.
- Cold Storage:Pharmaceutical and frozen food chains in Ontario and British Columbia specify plastic platforms for contamination resistance and dimensional stability under temperature cycling.
Warehousing commands pallet flow volume. Cold storage is gaining share fastest.
End User:
Customer type determines specification stringency, with pharmaceuticals and food facing the tightest regulatory constraints.
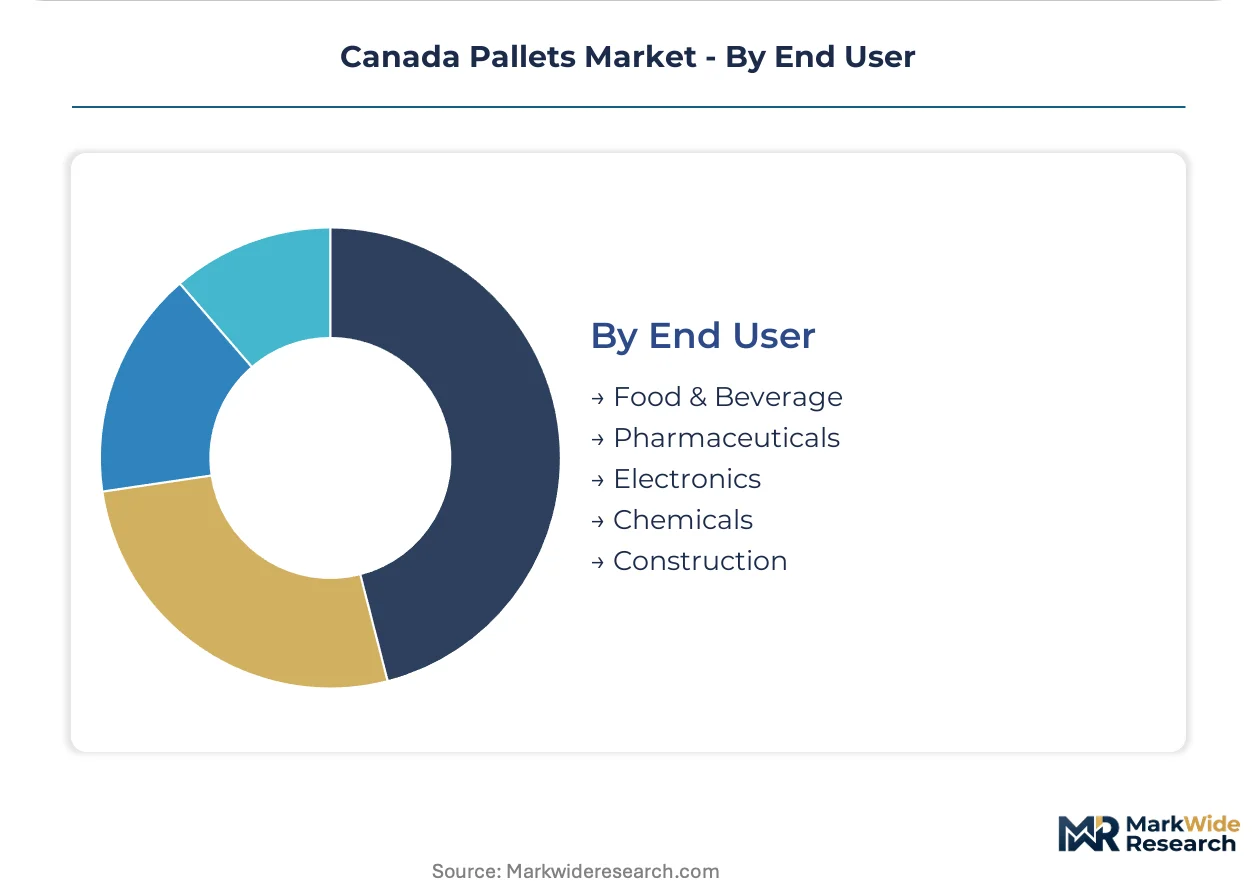
- Food & Beverage:Handlers across Canada migrate toward standardized pool systems to satisfy the Canadian Food Inspection Agency's Safe Food for Canadians Regulations lot-level traceability requirements.
- Pharmaceuticals:Distributors face Health Canada audit requirements for contamination control documentation that informal wood exchanges cannot satisfy.
- Electronics:Static control and cleanroom compatibility specifications drive specialty material selection.
- Chemicals:Alberta petrochemical facilities seek lifecycle extension services to reduce per-trip platform costs in closed-loop recovery arrangements.
- Construction:Bulk material handling tolerates lower-grade refurbished wood with minimal specification overhead.
Food and beverage anchors procurement volume. Pharmaceuticals is where specification premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports pallet-supported goods primarily to the United States through integrated North American supply chains, with cross-border manufacturing and retail distribution driving platform standardization at 48-by-40-inch specifications.
Ontario
Pharmaceutical distributors and third-party logistics providers in the Greater Toronto Area are consolidating distribution networks around pooled pallet fleets. Health Canada's Good Manufacturing Practice standards mandate contamination-resistant surfaces for drug shipments. Cold storage operators in Mississauga and Brampton are expanding plastic pallet deployments to meet temperature-controlled logistics requirements.
Quebec
Automated warehouse robotics deployment in Montreal and Laval distribution corridors favors block-type four-way entry pallet designs. The province's food processing sector faces Canadian Food Inspection Agency traceability mandates under Safe Food for Canadians Regulations. Pallet pooling services in the Montreal-Quebec City axis are capturing share from informal wood exchanges.
British Columbia
Frozen food chains and pharmaceutical cold storage operators in Vancouver and Surrey are scaling hygienic pallet fleets. Health Canada audit requirements for contamination control documentation drive specification premiums. Timber supply constraints from provincial forest management policies elevate input cost volatility for local softwood pallet fabricators.
Alberta
Petrochemical facilities in Calgary and Edmonton seek closed-loop recovery systems to reduce per-trip platform costs. The Canadian Standards Association's structural integrity benchmarks influence procurement for heavy manufacturing loads. Industrial buyers in the province's chemical corridor are contracting lifecycle extension services from specialized recovery operators.
Manitoba
Agricultural processors in Winnipeg and surrounding grain handling facilities rely on wood pallet refurbishment networks despite regulatory pressure. Cost sensitivity limits plastic pallet adoption among bulk commodity handlers. St. Boniface Pallet Company anchors regional hardwood block pallet production serving provincial food processing and export grain operations.
Canada Pallets Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. National-scale fabricators with multi-provincial manufacturing footprints capture bulk supply contracts from major retailers and third-party logistics consolidators. Regional specialists defend positions through material expertise in hardwood or recovery services. The competitive landscape rewards backward integration into timber sourcing and forward integration into pooled fleet management. Strategic moves concentrate on repair network densification and RFID-enabled asset tracking partnerships.
Among national-scale operators, UFP Industries Inc. exemplifies channel-controlling reach through its distributed manufacturing presence across provincial hubs. St. Boniface Pallet Company and Enviro Pallet Recovery Ltd. represent contrasting specialist archetypes—one anchored in hardwood block production for agricultural processing, the other in closed-loop lifecycle services for industrial cost containment. These three players occupy positions spanning the premium specification, regional material specialization, and circular economy service tiers that define competitive segmentation in Canadian pallet supply.
| Leading Market Players |
|---|
| Trican Packaging Inc. |
| St. Boniface Pallet Company |
| UFP Industries Inc. |
| Canada Pallet Source |
| Pallet Management Group Inc. |
| Enviro Pallet Recovery Ltd. |
| Bluewater Pallet Inc. |
| Verbeek Pallet Supply Co. Ltd. |
| Alberta Pallet Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
The Greater Toronto Area warehousing corridor compresses per-trip platform costs through pooled fleet economics while amplifying price premiums for Health Canada-certified hygienic surfaces. British Columbia timber supply constraints feed input cost volatility into softwood pallet fabrication, pushing pharmaceutical distributors toward plastic pool systems with documented contamination control.
Pricing Analysis
Legacy wood refurbishment, current plastic pool subscriptions, and emerging RFID-tagged composite platforms stratify across premium, standard, and economy tiers. Pricing separates pharmaceutical-grade certified surfaces from agricultural bulk handlers and construction sector refurbished wood. Cost compression in standard wood tiers intensifies because Manitoba grain processors resist premium material conversion. Agricultural processors exhibit highest price sensitivity; pharmaceutical cold storage operators show least.
Supply Chain Analysis
Extended payment terms from Ontario third-party logistics providers and supply-chain finance facilities anchor working capital structures for regional fabricators. Canadian softwood draws from British Columbia interior forests and Quebec boreal zones, with resin and RFID hardware feeding from United States and Asian electronics hubs. Single-source vulnerability concentrates in British Columbia timber supply under provincial forest management policies. Distribution runs through Greater Toronto Area consolidation hubs serving cross-border United States freight corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around RFID-enabled asset tracking interoperability, with pharmaceutical and food sector mandates forcing standardized pool participation over informal exchange networks.
For Market Incumbents: Harden repair network densification in Ontario and Quebec to defend against plastic pool substitution. Anchor backward integration into British Columbia and Quebec timber sourcing to offset input cost volatility. Certify block pallet production lines for Health Canada Good Manufacturing Practice compliance to capture pharmaceutical specification premiums. For New Entrants and Emerging Players: Pursue closed-loop recovery services for Alberta petrochemical facilities, where lifecycle extension demand outpaces specialized supply. Target Manitoba agricultural processors with hybrid wood-plastic composite platforms bridging cost sensitivity and emerging traceability requirements. Deploy direct fleet management contracts with mid-size cold storage operators bypassing incumbent pool intermediaries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized pallet fabrication divisions lacking RFID integration capabilities. Long-term viability centers on pooled fleet operators with embedded serialization infrastructure serving regulated end-uses. Watch Health Canada audit enforcement intensity as inflection indicator for plastic pool penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Asset Tracking Integration | Enables real-time inventory visibility for Ontario pharmaceutical distributors under Health Canada mandates. |
| Closed-Loop Recovery System Expansion | Reduces per-trip platform costs for Alberta chemical sector buyers through lifecycle extension services. |
| Block Pallet Automation Alignment | Matches Quebec warehouse robotics deployment with four-way entry compatibility for automated storage systems. |
| Provincial Pool Network Consolidation | Captures Greater Toronto Area third-party logistics rationalization through single-source fleet management contracts. |
| Health Canada Certification Investment | Unlocks pharmaceutical distribution premiums via contamination-resistant surface validation under Good Manufacturing Practice standards. |
Research Methodology
Desk research of Canadian Standards Association technical bulletins, Health Canada regulatory filings, and Canadian Food Inspection Agency guidance documents preceded structured interviews with third-party logistics procurement directors, cold storage facility managers, pallet pool operators, and hardwood fabrication plant supervisors. Primary fieldwork combined with secondary validation against customs trade data, provincial forest management reports, and industry association membership directories. Bottom-up volume estimates from provincial manufacturing and warehousing counts triangulated against top-down market sizing from national freight tonnage and pallet-to-load ratios.
Assumptions held fixed include Health Canada Good Manufacturing Practice enforcement intensity, Canadian Food Inspection Agency traceability mandate implementation pace, and British Columbia timber supply availability. Variables included RFID adoption curves across pharmaceutical and food end-uses, plastic pool subscription pricing elasticity, and cross-border United States freight volume fluctuations. CAGRs derived from segment-level volume projections weighted by material substitution elasticities and automation penetration rates across Quebec and Ontario distribution corridors. Forecast inputs incorporated cold storage construction permits, pharmaceutical distribution facility expansions, and warehouse robotics deployment data.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting capital-intensive plastic pool investments, lumber futures volatility, or cross-border trade policy would shift the trajectory. Regulatory enforcement intensity, technological substitution rates, and supply chain reshoring patterns represent additional revision triggers. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
Pallet Boxes Market
Pallets Packaging
Corrugated Pallets Market
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Corrugated Pallet Wrap Market
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
North America Pallet Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Europe Pallet Wrapping Machine Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Pallet Wraps Market