
 Avocado-Based Products Market | 2026-2036
Avocado-Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
Avocado-Based Products Market Outlook
Organic certification under USDA NOP is reorganizing competitive access for North American suppliers. Calavo Growers leverages its integrated sourcing network across California and Mexico to secure year-round supply continuity. Mission Produce anchors its position through controlled-ripening technology and direct retail partnerships. Simplot Foods competes via frozen avocado formats tailored to commercial kitchen workflows.
Avocado-based products encompass oils, purees, spreads, and dehydrated forms derived from Persea americana fruit pulp, typically processed through cold-press extraction or high-pressure preservation to retain lipid profiles exceeding 60% monounsaturated fat content. These outputs serve food manufacturing, foodservice preparation, and direct retail consumption as functional ingredients or finished goods. Avocado oil commands premium positioning among the product type categories due to its smoke-point advantage and clean-label appeal. The foodservice end-user segment is expanding fastest as operators replace conventional fats with avocado derivatives in menu development. Pouch packaging is gaining traction relative to glass jars for foodservice bulk dispensing and e-commerce shipping efficiency.
FDA oversight of nutrition claims and USDA NOP organic standards govern product labeling and import eligibility for US-bound shipments. Mexico's SENASICA phytosanitary protocols and the FDA's Food Safety Modernization Act preventive controls shape cross-border supply chain compliance burdens. Stakeholders must monitor evolving EU deforestation regulation traceability requirements that could redirect export volumes toward alternative certification schemes.
Market Dynamics
USDA NOP organic certification requirements are reshaping supplier qualification thresholds across North American distribution channels, forcing processors to restructure sourcing relationships and documentation systems to maintain retail shelf access.
Growth Catalysts
- High-Pressure Preservation:Cold-press extraction systems now integrate high-pressure processing to extend shelf life without thermal degradation, enabling clean-label positioning for retail oils and purees.
- FDA Nutrition Labeling:Updated requirements for plant-based fat disclosure are accelerating reformulation of spreads and cooking fats toward monounsaturated-dominant profiles that avocado derivatives naturally deliver.
- Foodservice Menu Expansion:US restaurant chains are systematically replacing conventional fats with avocado oils in frying and finishing applications, creating pull-through demand for bulk formats.
Market Restraints
- Input Cost Volatility:Fresh avocado pricing fluctuates with Michoacán harvest cycles and California drought conditions, compressing processor margins on contracted output volumes.
- Supply Concentration Risk:Mexico's SENASICA phytosanitary enforcement creates single-point vulnerability for US-bound shipments, with inspection delays disrupting just-in-time foodservice delivery.
- Smoke-Point Substitution:Refined high-oleic sunflower and safflower oils achieve comparable thermal performance at lower cost, limiting premium pricing power in commercial frying segments.
Strategic Opportunities
- EU Deforestation Regulation:Traceability mandates opening market share for certified-sustainable suppliers who can document chain-of-custody from orchard to processor.
- E-Commerce Pouch Formats:Flexible packaging replacing glass jars for direct-to-consumer shipping, reducing breakage rates and dimensional weight charges.
- Dehydrated Avocado Powder:Extended-shelf-life formats penetrating camping, military, and emergency food applications where fresh supply is impractical.
Industry Challenges
- Organic Certification Timeline:USDA NOP transition periods require three years of documented chemical-free cultivation, constraining rapid supply expansion from conventional orchards.
- Ripening Technology Integration:Controlled-atmosphere systems for post-harvest conditioning demand specialized capital equipment and trained technicians, creating operational bottlenecks for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avocado-Based Products Market |
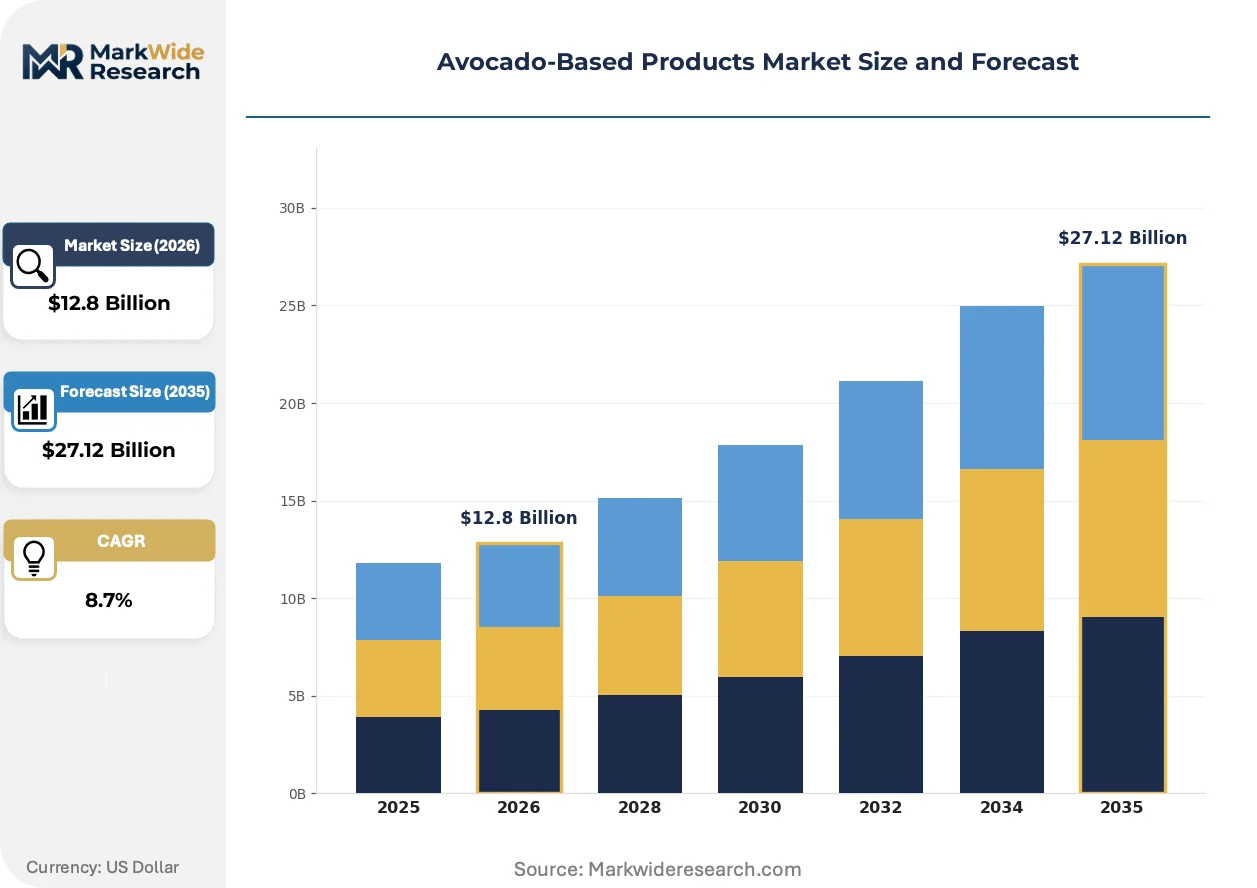
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Avocado Oil, Guacamole, Avocado Spread, Dried Avocado Packaging Type: Bottle, Jar, Pouch, Bulk End User: Household, Foodservice, Retail, Food Processing Distribution Channel: Supermarket, Online, Specialty Store, Wholesale |
| Companies Covered | Avocados From Mexico, Fresh Del Monte Produce, Calavo Growers, Salazar, Simplot Foods, Mission Produce, Eagle Eye Produce, Index Fresh, West Pak Avocado, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avocado-Based Products Market Strategic Shifts
Cold-press extraction technology is segmenting the competitive landscape between premium unrefined outputs and cost-optimized refined alternatives, while regulatory traceability requirements and shifting procurement patterns are restructuring how buyers evaluate supplier relationships.
High-pressure processing is bifurcating the preservation technology landscape. This non-thermal method inactivates spoilage microorganisms while preserving heat-sensitive polyphenols and chlorophyll. Food manufacturers targeting clean-label positioning are adopting HPP-treated purees at accelerated rates. The technology is bifurcating the market into HPP-capable premium suppliers and conventional thermal processors competing on cost.
EU deforestation regulation traceability mandates are forcing documentation system overhauls. Processors must now geolocate every orchard contributing to a finished product and maintain auditable chain-of-custody records. Bulk oil importers serving European food manufacturers face the steepest compliance burdens, with many redirecting sourcing toward certified sustainable suppliers in Jalisco and Nayarit.
Direct procurement relationships between processors and foodservice chains are displacing traditional distributor intermediaries. Large restaurant groups now contract directly for controlled-ripening programs and custom pouch sizes. This disintermediation concentrates purchasing power among national account buyers while squeezing regional distributors into smaller independent restaurant segments. The shift is most visible in California and Texas, where chain penetration in fast-casual dining is highest.
Avocado-Based Products Market Segmentation
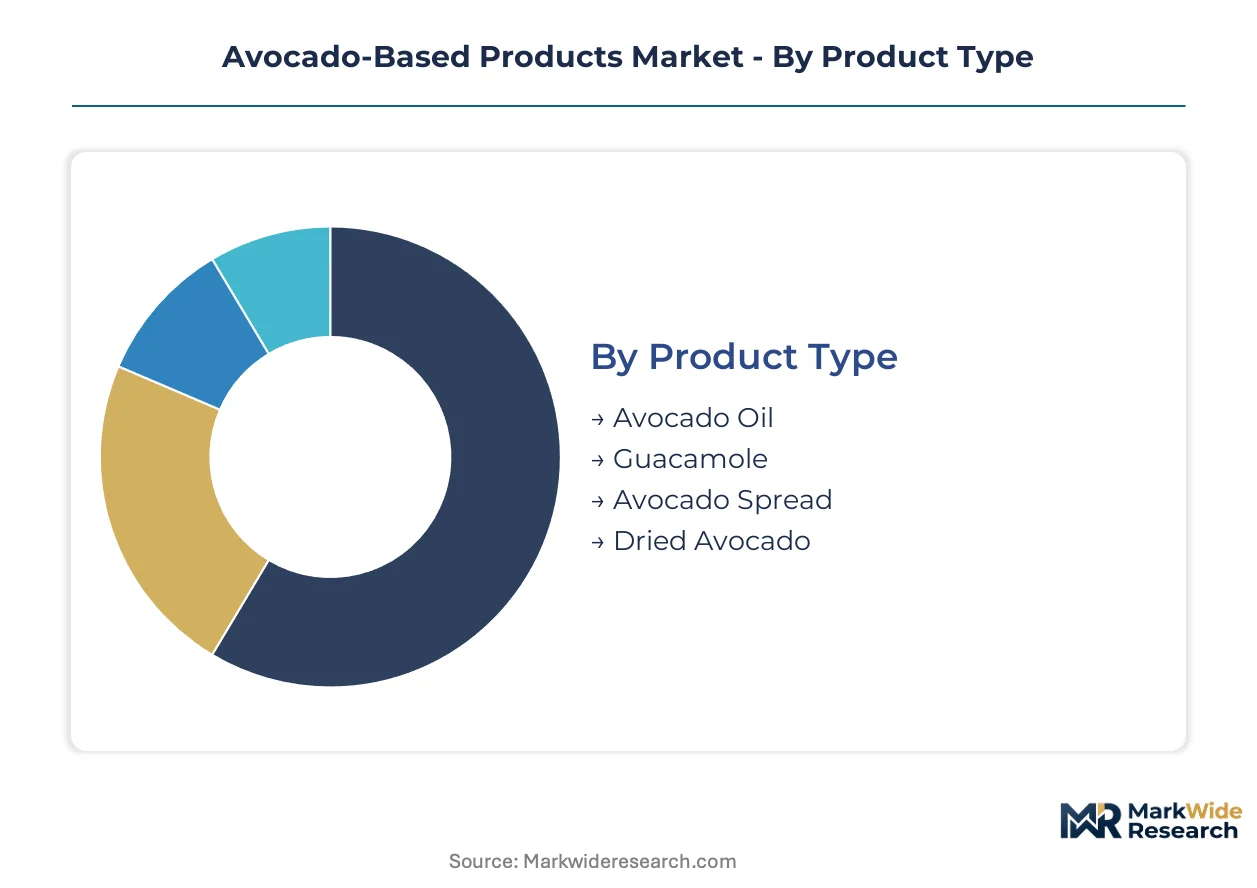
Avocado-based product demand fragments across distinct usage contexts, each imposing unique formulation and packaging specifications. Understanding these segment boundaries clarifies where processors must deploy cold-press extraction versus high-pressure preservation, and which distribution infrastructure each channel demands.
Product Type:
Domestic consumption in the United States concentrates on fresh-adjacent formats, while export-led demand pulls toward shelf-stable derivatives with extended logistics tolerance.
- Avocado Oil:Cold-pressed unrefined grades retain chlorophyll and polyphenol content above 60% monounsaturated fat, commanding premium positioning in California and Texas retail. Refined variants with 270°C smoke points penetrate foodservice frying in Florida and Arizona where operators seek butter replacements.
- Guacamole:High-pressure processed fresh formats dominate US foodservice procurement from fast-casual chains in Texas and California. Frozen and retort-stabilized versions serve export markets where cold chain reliability varies.
- Avocado Spread:Emulsified formulations with extended ambient stability target sandwich manufacturing and institutional feeding operations.
- Dried Avocado:Freeze-dried and air-dried powders concentrate lipids for nutraceutical applications and military ration packs.
Avocado oil commands the established base. The steepest expansion runs through guacamole as foodservice chains systematize procurement.
Packaging Type:
Cost tier separation between premium presentation formats and operational bulk solutions drives material selection and filling line investment.
- Bottle:Amber glass and PET formats with nitrogen flushing preserve oxidative stability for retail oils in premium supermarket placements. California processors favor domestic glass sourcing despite weight penalties.
- Pouch:Multi-layer flexible structures with fitment closures reduce dimensional weight for e-commerce fulfillment and foodservice dispensing systems.
- Jar:Wide-mouth glass containers dominate spread and guacamole retail in traditional Northeast and Midwest markets.
- Bulk:Intermediate bulk containers and drum formats serve food manufacturing and chain restaurant commissaries with direct pump-off systems.
Bottle formats anchor premium retail positioning. Pouch configurations are climbing the fastest as direct-to-consumer channels expand.
End User:
Application maturity separates established household consumption from emerging industrial integration pathways.
- Foodservice:Chain restaurant operators in Texas and California specify controlled-ripening programs and custom pouch sizes, displacing traditional distributor relationships.
- Food Processing:Clean-label reformulation in baked goods and dairy alternatives drives avocado oil and puree incorporation by manufacturers seeking monounsaturated fat claims.
- Household:Supermarket and online purchases concentrate in coastal states with established avocado consumption culture.
- Retail:Private label and branded finished goods compete for shelf space in conventional and natural channel supermarkets.
Household consumption provides volume stability. Food processing applications are gaining share fastest as ingredient suppliers pivot toward functional fat replacement.
Distribution Channel:
Supply concentration in Mexico and California shapes which channels control inventory flow to distinct customer tiers.
- Supermarket:Conventional and natural channel retailers in California, Texas, and Florida maintain dedicated produce-adjacent sets for oils and spreads.
- Wholesale:Broadline and specialty distributors serve independent restaurants and smaller foodservice accounts outside major metropolitan procurement zones.
- Online:Direct-to-consumer and third-party marketplace sales accelerate pouch format adoption for shipping efficiency.
- Specialty Store:Gourmet and ethnic retailers in urban centers stock premium unrefined oils and small-batch spreads.
Supermarket channels maintain the volume base. Online distribution is expanding most quickly as subscription models reduce customer acquisition costs for emerging brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Lázaro Cárdenas on Mexico's Pacific coast anchors cross-border avocado flows with dedicated cold-chain infrastructure handling bulk shipments to California and Texas distribution hubs.
United States
Foodservice chains in Texas and California drive bulk procurement of controlled-ripening avocado formats. FDA Food Safety Modernization Act preventive controls govern import inspections at San Diego and McAllen border crossings. Los Angeles and Dallas-Fort Worth host the largest ripening and repackaging facilities serving national restaurant distribution.
Mexico
Michoacán's orchard belt supplies the majority of raw fruit for processing into oils and purees. SENASICA phytosanitary protocols regulate export eligibility through inspection checkpoints in Uruapan and Morelia. Jalisco and Nayarit are expanding certified-sustainable acreage to meet EU deforestation regulation traceability requirements.
Canada
Health Canada and PMRA regulate maximum residue limits for imported avocado-based products entering Vancouver and Toronto. Retail demand concentrates in Ontario and British Columbia supermarkets with established organic produce sections. Montreal's foodservice distributors are expanding guacamole and oil offerings for fast-casual restaurant chains.
Germany
EFSA nutrition claims standards shape labeling requirements for avocado oil sold through Frankfurt and Hamburg wholesale channels. EU Green Deal sustainability criteria are redirecting procurement toward certified-origin suppliers with documented chain-of-custody. Bavaria's food processing sector integrates avocado purees into dairy alternative formulations.
United Kingdom
London and Southeast England supermarkets anchor retail demand for premium unrefined avocado oils. FSA allergen labeling requirements apply to spread and guacamole products manufactured for UK distribution. Manchester-based foodservice distributors are expanding pouch-format offerings for independent restaurant accounts.
Avocado-Based Products Market Competitive Environment
Listed leaders compete with private specialists across ripening technology and sourcing integration. The vendor base spans vertically integrated growers, regional packers, and branded finished-goods processors. Three archetypes dominate: orchard-controlled integrators, ripening-technology specialists, and private-label manufacturers. Competitive moves concentrate on backward integration into Mexican sourcing and direct foodservice contracting.
Within the integrated-grower tier, Calavo Growers and Mission Produce exemplify sourcing-network control across California and Mexico. Simplot Foods occupies a position among frozen-format specialists serving commercial kitchen workflows. These three anchors represent distinct strategic positions: year-round supply continuity, controlled-atmosphere ripening systems, and frozen product standardization.
| Leading Market Players |
|---|
| Avocados From Mexico |
| Fresh Del Monte Produce |
| Calavo Growers |
| Salazar |
| Simplot Foods |
| Mission Produce |
| Eagle Eye Produce |
| Index Fresh |
| West Pak Avocado |
| Others |
Value Chain & Pricing Dynamics
Refined high-oleic sunflower oil displacing avocado oil in commercial frying applications simultaneously redraws procurement geography toward Ukraine and Argentina while compressing margin structures across Michoacán-dependent processors. This substitution dynamic forces avocado suppliers to defend premium positioning through certification tiers rather than smoke-point parity.
Pricing Analysis
Volume-discount tiering separates contract foodservice chains from spot-market independent restaurants, with annual offtake commitments commanding 15-20 point spreads. Three-tier pricing structure across premium unrefined, standard refined, and economy bulk grades tracks USDA NOP organic certification and cold-press extraction method. Cost compression in the economy tier intensifies as refined seed oils achieve functional equivalence at lower input costs. Chain restaurant procurement teams exhibit lowest price sensitivity due to menu-premiumization strategies, while independent operators maximize spot-market flexibility.
Supply Chain Analysis
Port congestion at Lázaro Cárdenas and container availability constraints on the Pacific trade lane elevate landed costs for US-bound shipments during peak harvest windows. Raw fruit supply draws from Michoacán's orchard belt, Jalisco's certified-sustainable expansion zones, and California's drought-stressed Central Valley. Single-source vulnerability concentrates in SENASICA phytosanitary enforcement checkpoints, where inspection delays cascade through just-in-time foodservice delivery schedules. Distribution runs through controlled-ripening facilities in Los Angeles and Dallas-Fort Worth before final-mile deployment to chain restaurant commissaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where USDA NOP organic certification timelines and SENASICA compliance infrastructure create three-year barriers against rapid supply expansion.
For Market Incumbents: Shield market position through backward integration into Jalisco certified-sustainable acreage and captive controlled-ripening capacity. Invest in high-pressure processing equipment to maintain clean-label differentiation against refined seed oil substitutes. Priority defensive moves center on securing multi-year direct contracts with fast-casual chains before new entrants achieve organic certification eligibility. For New Entrants and Emerging Players: Anchor in dehydrated avocado powder formats for military and emergency food applications where supply-chain resilience commands premium pricing. Target camping goods distributors and institutional feeding operations as the most penetrable white-space segments. Go-to-market execution should leverage e-commerce pouch formats to bypass entrenched supermarket slotting fee barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ripening-technology specialists lacking upstream orchard control. Long-term viability across the analysis window hinges on traceability infrastructure investments ahead of EU deforestation regulation enforcement. Acquisition screening should prioritize processors with documented chain-of-custody systems in Jalisco and Nayarit. The critical inflection signal to monitor is SENASICA inspection protocol tightening that would accelerate consolidation among margin-constrained mid-scale operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified-Sustainable Orchards | Secures EU deforestation regulation compliance and long-term supply continuity from Jalisco and Nayarit. |
| High-Pressure Processing Capacity Expansion | Enables clean-label positioning for retail purees against thermally processed competitors. |
| Direct Foodservice Chain Contracting | Bypasses distributor intermediaries and locks in volume commitments from Texas and California operators. |
| E-Commerce Pouch Format Launch | Reduces dimensional weight charges and breakage rates for direct-to-consumer shipping channels. |
| USDA NOP Organic Certification Investment | Creates three-year supply barriers and unlocks premium shelf placement in California and Texas retailers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with ripening facility operators, foodservice procurement directors, and SENASICA compliance officers; and secondary validation through FDA import inspection records, USDA NOP certification databases, and customs trade flow documentation. Bottom-up volume estimates from processor capacity utilization triangulated against top-down demand segmentation across foodservice, food manufacturing, and household channels.
Across the projection horizon, the analytical framework modeled product type, packaging format, end-user segment, and distribution channel dimensions. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated Michoacán harvest cycle variability, California drought frequency, and EU deforestation regulation implementation timelines.
Material uncertainties — SENASICA enforcement intensity shifts, refined seed oil price volatility, and organic certification queue delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about trade lane stability and phytosanitary protocol continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Europe Freeze-Dried Fruits and Vegetable Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
Fava Beans Market
Fruits and Vegetables
Lingonberry Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Colombia Fruits and Vegetables Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Europe Frozen Fruits and Vegetables Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Global Gooseberry Market
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Dates Market