
 North America Engineering Research and Development (ER&D) Services Market | 2026-2036
North America Engineering Research and Development (ER&D) Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Engineering Research and Development (ER&D) Services Market Insights
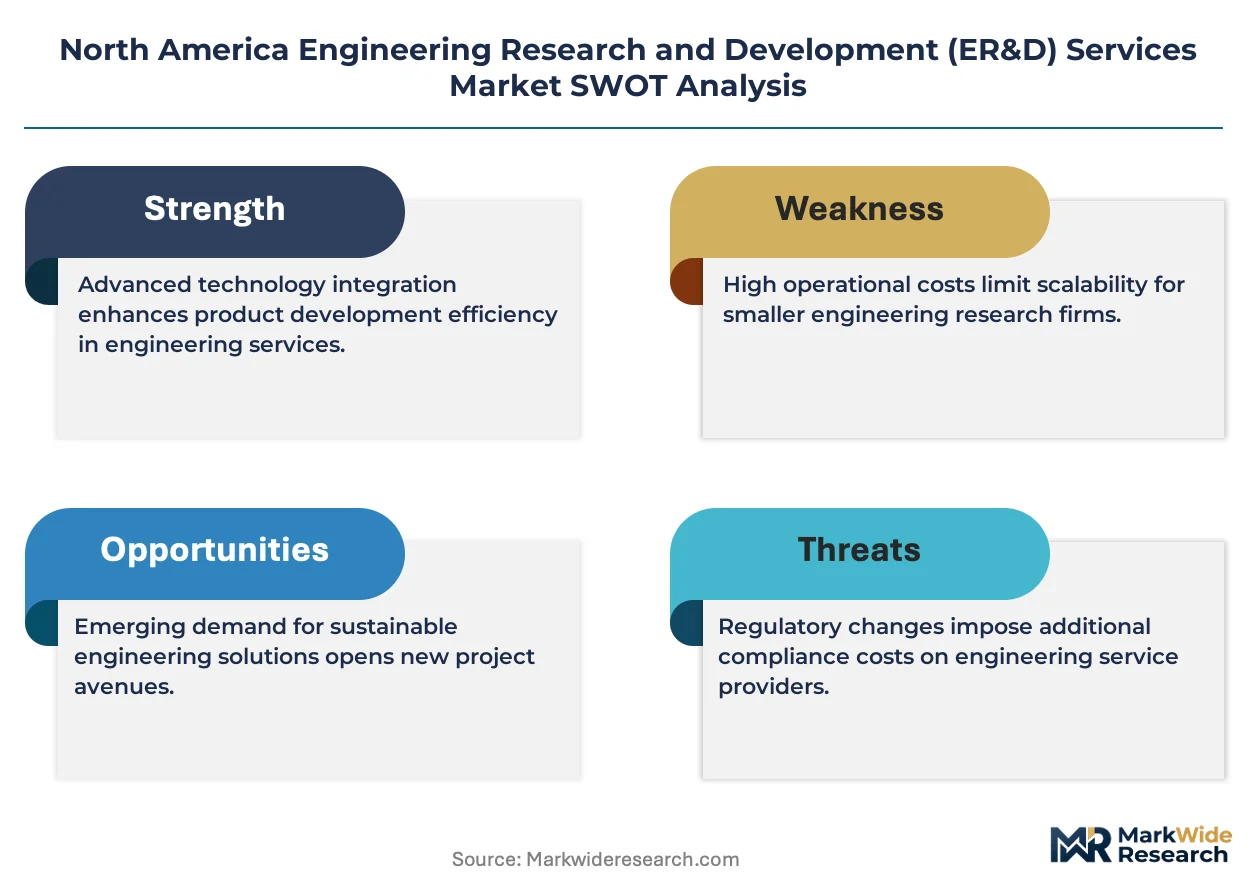
Mid-market manufacturers are rotating engineering budgets toward external ER&D partners as product complexity outpaces in-house capacity. Accenture PLC leverages its digital thread expertise to anchor large-scale aerospace programs across the U.S. Midwest. Tata Technologies Inc. specializes in automotive powertrain design, competing directly with Wipro Limited for Detroit-based OEM contracts. HCL Technologies Limited sustains its position through embedded software capabilities that dominate connected vehicle development cycles.
Engineering Research and Development (ER&D) Services encompass outsourced technical design, prototyping, testing, and systems integration delivered across mechanical, electrical, and software engineering disciplines, typically governed by stage-gate development protocols and IP protection frameworks. These services enable client organizations to compress development timelines, access specialized talent pools, and distribute technical risk without maintaining full captive engineering infrastructure. Design Services and Testing Services command the largest share of contracted value, while Prototyping Services is accelerating fastest as digital twin workflows collapse physical iteration cycles. The Automotive vertical leads absolute spending, though Healthcare is widening fastest as FDA-regulated device makers outsource biomechanical engineering and simulation-driven verification.
FDA quality system regulations and the U.S. CHIPS and Science Act reshape where ER&D work gets performed, with compliance requirements and domestic content incentives steering contract awards toward U.S.-based engineering centers. NHTSA safety standards and EPA emissions protocols force automotive ER&D providers to maintain dual certification tracks for powertrain and autonomous systems validation. Stakeholders must weigh the trade-off between nearshore delivery premiums and the contracting flexibility that federal procurement rules increasingly mandate for critical technology development.
Market Dynamics
The CHIPS and Science Act is rerouting federal semiconductor R&D contracts toward domestic engineering centers, while automotive electrification timelines compress development cycles and force OEMs to externalize powertrain design.
Growth Catalysts
- CHIPS Act incentives:Federal domestic content requirements steer advanced packaging and chip design work to U.S.-based ER&D providers, creating captive demand pools in Arizona and Texas.
- Automotive electrification:Detroit-based OEMs are expanding outsourced battery thermal management and electric drivetrain engineering to hit 2030 production targets.
- Digital twin adoption:Aerospace primes in California and Washington state are collapsing physical prototyping cycles through simulation-driven verification workflows.
Market Restraints
- Specialized talent scarcity:Embedded systems engineers with automotive functional safety certification command 40-60% wage premiums, eroding project margins.
- Domestic facility cost inflation:Laboratory and cleanroom construction in U.S. tech corridors has outpaced general commercial real estate, locking out mid-tier providers.
- Export control friction:Bureau of Industry and Security restrictions on semiconductor design tools create compliance overhead for cross-border engineering teams.
Strategic Opportunities
- FDA-regulated device engineering:Minnesota and Massachusetts medical device clusters are outsourcing biomechanical simulation and verification to ER&D specialists.
- Grid modernization engineering:FERC interconnection queue reforms are accelerating demand for power electronics and energy storage system design.
- Dual-use technology convergence:Defense primes are licensing commercial automotive battery management IP for unmanned systems, opening classified-adjacent contract channels.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D validation for autonomous vehicle software extends program schedules by 8-14 months.
- IP contamination risk:Shared engineering environments between competing automotive OEMs create forensic audit requirements that slow project initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Engineering Research and Development (ER&D) Services Market |
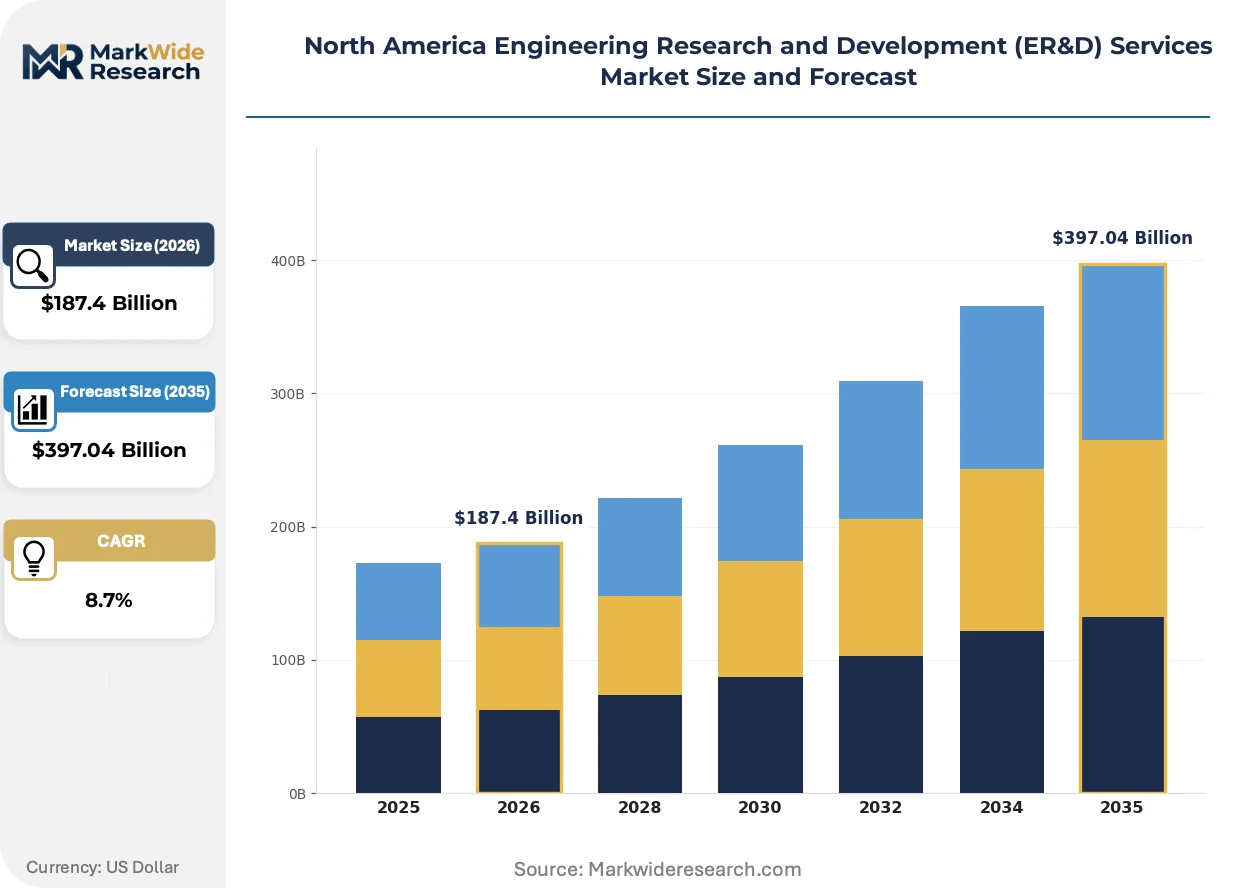
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design Services, Testing Services, Prototyping Services, Consulting Services Industry Vertical: Aerospace, Automotive, Healthcare, Telecommunications Technology: IoT, AI, Cloud Computing, Simulation Software End User: Manufacturers, Startups, Enterprises, Government Agencies |
| Companies Covered | Tata Technologies Inc., Infosys Limited, Wipro Limited, HCL Technologies Limited, Tech Mahindra Limited, Capgemini SE, Tata Consultancy Services Ltd., Cognizant Technology Solution Corporation, Accenture PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Engineering Research and Development (ER&D) Services Market Trends and Innovations
Digital engineering workflows are collapsing traditional stage-gate boundaries, while regulatory compliance requirements harden into competitive moats for certified providers.
Generative design software is fragmenting mechanical engineering task allocation. The technology automates topology optimization and material selection for lightweight structural components. Automotive and aerospace OEMs in Michigan and California are embedding these tools into early-stage development. Traditional CAD-centric engineering hierarchies are fragmenting as algorithmic design shifts power toward materials specialists and simulation engineers.
The U.S. CHIPS and Science Act is mandating domestic foundry engineering presence for federal contract eligibility. Semiconductor OEMs must maintain U.S.-based design centers to access $52 billion in federal incentives. This is concentrating advanced packaging R&D in Arizona and Texas, displacing previous offshore engineering arrangements with Taiwan and South Korea.
Outcome-based contracting is displacing time-and-materials engineering agreements. Automotive OEMs now tie 30-50% of ER&D fees to verified performance milestones rather than labor hours. This concentrates risk with engineering service providers while compressing buyer procurement cycles. The shift is most visible in Detroit's electric vehicle program sourcing, where Tier 1 suppliers face liquidated damages clauses for missed thermal management targets.
North America Engineering Research and Development (ER&D) Services Market Segmentation
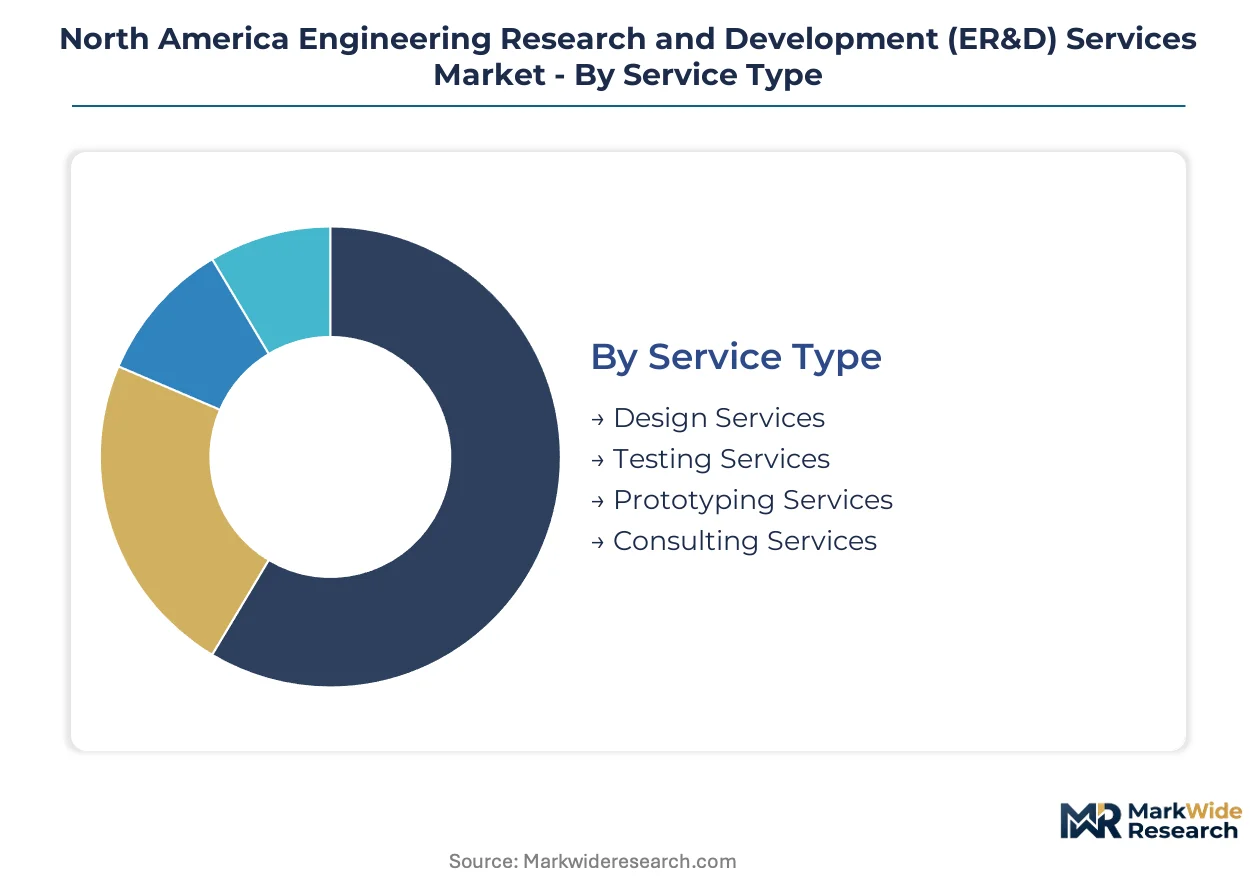
Engineering service procurement in North America fragments across technical disciplines, regulatory environments, and buyer sophistication levels. Understanding these segment boundaries reveals where contract value concentrates and which capability investments yield competitive differentiation.
Service Type:
FDA, EPA, and NHTSA compliance requirements create divergent certification burdens across service categories, with medical device design demanding quality system documentation that automotive testing escapes.
- Design Services:Encompasses CAD modeling, systems architecture, and design-for-manufacturing optimization across mechanical, electrical, and software domains. Michigan automotive OEMs and California aerospace primes anchor contract volume, driven by electrification timelines that compress in-house capacity. Established volume favors Design Services; emerging adoption favors Prototyping Services.
- Testing Services:Covers validation protocols, environmental stress screening, and regulatory certification testing governed by stage-gate milestones. Minnesota medical device clusters and Detroit powertrain engineering centers drive concentration, constrained by ISO 17025 laboratory accreditation requirements.
- Prototyping Services:Rapid physical iteration and digital twin-enabled virtual validation workflows. Texas semiconductor packaging facilities and Washington state aerospace suppliers are expanding adoption fastest as digital workflows collapse iteration cycles.
- Consulting Services:Strategic technology roadmapping and regulatory pathway advisory. Federal CHIPS Act procurement rules steer government contract awards toward U.S.-based consulting presence.
Margin compression hits commoditized testing; differentiation concentrates in integrated design-prototype workflows.
Industry Vertical:
Defense procurement rules and FDA quality system regulations partition engineering talent pools, with cleared facility requirements and ISO 13485 certification creating non-overlapping supplier bases.
- Aerospace:Structures engineering, propulsion systems design, and avionics integration governed by FAA airworthiness standards. Washington state and California defense corridors concentrate spending, propelled by unmanned systems programs and commercial space launch timelines.
- Automotive:Powertrain electrification, battery thermal management, and autonomous vehicle software development. Detroit-based OEMs anchor contract value, though EPA emissions protocols and NHTSA safety standards extend validation schedules. Technology maturation favors Automotive; regulatory complexity favors Healthcare.
- Healthcare:Biomechanical simulation, medical device verification, and imaging system design under FDA 21 CFR Part 820 quality system requirements. Minnesota and Massachusetts device clusters are expanding outsourced engineering fastest as FDA premarket submission timelines tighten.
- Telecommunications:Network infrastructure design, RF engineering, and edge computing hardware development. FCC equipment authorization rules and spectrum allocation decisions steer R&D investment cycles.
Automotive commands absolute contract value; Healthcare shows steepest expansion trajectory as regulatory submission outsourcing accelerates.
Technology:
Intellectual property protection frameworks and export control classifications fragment technology adoption patterns, with EAR-controlled simulation tools restricting cross-border engineering team deployment.
- IoT:Sensor integration, edge connectivity architectures, and embedded firmware development for connected products. Automotive telematics and industrial asset monitoring anchor demand, constrained by FCC Part 15 certification requirements for radio frequency devices.
- AI:Machine learning model development, computer vision systems, and predictive maintenance algorithms. Healthcare diagnostic imaging and aerospace predictive analytics are gaining share fastest as FDA AI/ML-based SaMD guidance clarifies validation pathways.
- Cloud Computing:High-performance computing infrastructure, simulation workload orchestration, and collaborative design platforms. Semiconductor design teams in Arizona and Texas dominate adoption, driven by CHIPS Act domestic content incentives.
- Simulation Software:Finite element analysis, computational fluid dynamics, and multi-physics modeling tools. Aerospace primes in California are collapsing physical prototype cycles through simulation-driven verification workflows.
Simulation Software anchors mature procurement budgets; AI engineering services capture emerging investment priority.
End User:
Procurement sophistication and technical staffing depth create distinct service requirements, with government agencies mandating cost accounting standards that commercial buyers waive.
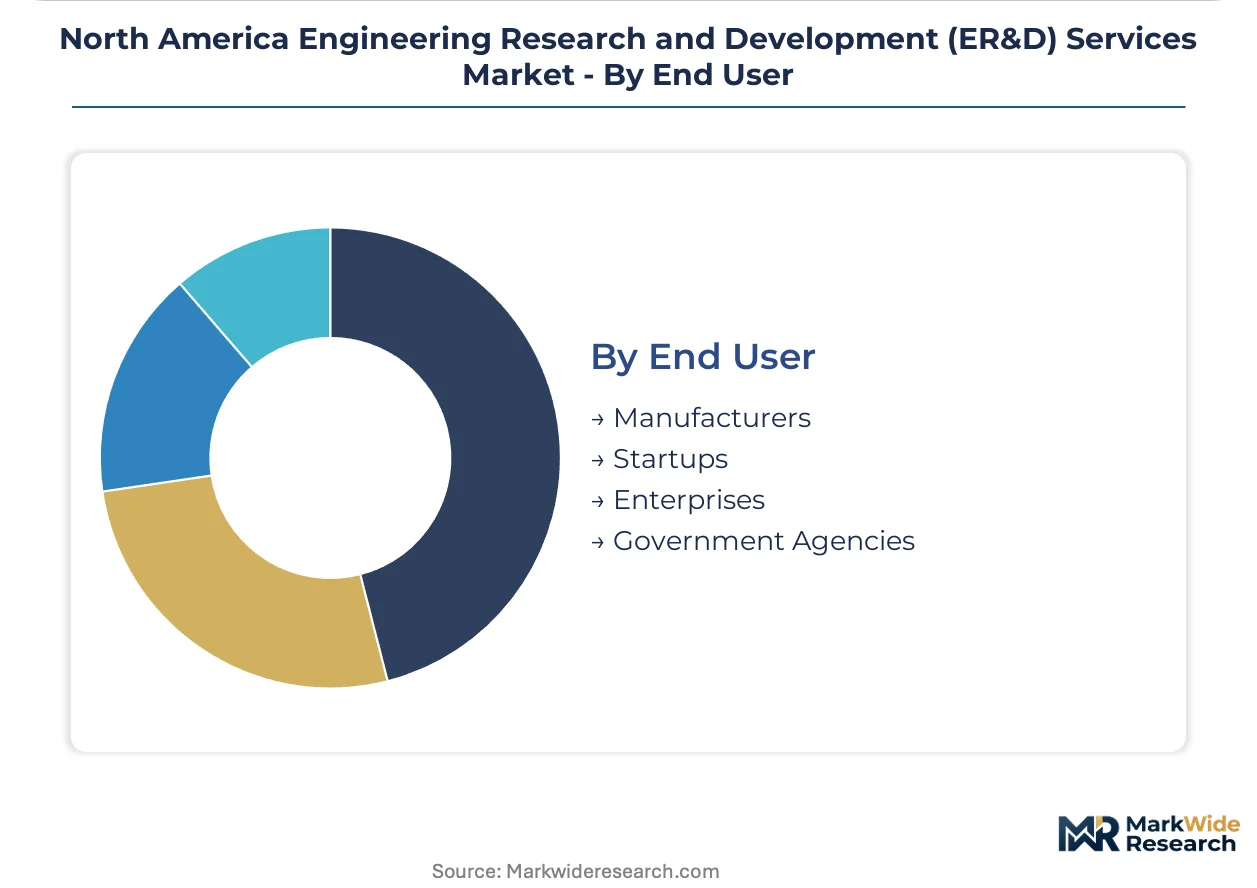
- Manufacturers:Tier 1 and Tier 2 suppliers across automotive, aerospace, and industrial equipment. Michigan and Ohio manufacturing belts concentrate demand, motivated by product complexity that exceeds captive engineering headcount.
- Startups:Venture-backed hardware companies lacking internal engineering infrastructure. California and Boston venture corridors drive concentration, though specialized talent scarcity inflates project premiums. Capital access favors Startups; procurement scale favors Enterprises.
- Enterprises:Fortune 500 industrial conglomerates with distributed R&D footprints. Digital transformation mandates and legacy system modernization anchor contract value.
- Government Agencies:Defense primes, national laboratories, and federal research centers. FAR compliance requirements and security clearance protocols restrict eligible supplier pools.
Enterprise procurement dominates contract value; Startup engagement expands fastest as venture hardware formation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports specialized aerospace engineering talent to U.S. defense primes along the Great Lakes corridor, while Mexico's manufacturing belt absorbs automotive design overflow from Detroit. Federal procurement rules and domestic content incentives reshape where ER&D work gets performed across the continent.
United States
CHIPS Act incentives steer advanced packaging and chip design work toward Arizona and Texas engineering centers. FDA quality system regulations and NHTSA safety standards force automotive and medical device providers to maintain dual certification tracks. Silicon Valley tech corridors and Michigan automotive clusters concentrate contract value as OEMs externalize powertrain design.
Canada
Toronto-Waterloo aerospace engineering clusters supply composite structures expertise to Boeing and Airbus programs. Federal procurement rules under the Industrial and Technological Benefits policy require domestic engineering presence for defense contracts. Montreal's flight simulation sector anchors avionics testing capacity for North American primes.
Mexico
Bajío Region automotive suppliers absorb Detroit OEM overflow for interior systems and powertrain component validation. USMCA domestic content requirements steer Tier 1 engineering work toward Mexican manufacturing belts. Querétaro's aerospace cluster hosts Bombardier and GE Aviation engineering centers for structural assembly design.
North America Engineering Research and Development (ER&D) Services Market Competitive Landscape
Listed leaders compete with private specialists across talent acquisition and certification depth, creating a tiered structure where scale-driven IT services conglomerates face off against niche engineering boutiques. The vendor base splits between full-stack digital transformation providers and pure-play mechanical design houses. Three archetypes dominate: India-headquartered IT services giants with embedded engineering divisions, European-origin consulting conglomerates with aerospace heritage, and North American-born digital specialists. Competitive moves center on outcome-based contracting structures and domestic facility expansion to capture CHIPS Act eligibility.
Within the IT services tier, Accenture PLC and Tata Technologies Inc. exemplify divergent positioning strategies. Accenture anchors large-scale aerospace programs through digital thread expertise across the U.S. Midwest. Tata Technologies occupies a specialized position in automotive powertrain design, competing for Detroit-based OEM contracts against Wipro Limited. These three represent how scale, vertical focus, and geographic presence create distinct competitive vectors in outsourced engineering procurement.
| Leading Market Players |
|---|
| Tata Technologies Inc. |
| Infosys Limited |
| Wipro Limited |
| HCL Technologies Limited |
| Tech Mahindra Limited |
| Capgemini SE |
| Tata Consultancy Services Ltd. |
| Cognizant Technology Solution Corporation |
| Accenture PLC |
| Others |
Pricing and Supply Chain Analysis
Digital twin workflows substituting physical prototyping cycles simultaneously relocate engineering value toward simulation software licenses and compress billable hours for traditional mechanical design. This substitution redraws supply geography toward Arizona and Texas semiconductor packaging clusters while eroding margin pools in Detroit's legacy CAD-centric supplier base.
Pricing Analysis
Technology-generation pricing gaps separate legacy CAD-based engineering services from emerging AI-augmented design automation and next-generation quantum simulation platforms. Project-based fee structures dominate, with price differentiation driven by ISO 26262 functional safety certification tier and embedded software complexity. Pricing pressure intensifies in commoditized testing segments as automated validation tools collapse manual verification timelines. Tier 1 automotive OEMs exhibit highest price sensitivity due to outcome-based contracting mandates, while FDA-regulated medical device makers accept premium rates for quality system documentation.
Supply Chain Analysis
Taiwan Strait transit vulnerabilities expose North American semiconductor design tool dependencies, with EAR-controlled simulation software creating compliance friction for cross-border engineering teams. Engineering talent supply concentrates in India, Poland, and Vietnam for embedded systems development, while raw material dependencies span specialized computing hardware, cleanroom equipment, and certified testing apparatus. Single-source vulnerability runs through Taiwan-based foundry engineering partnerships that dominate advanced packaging R&D. Distribution feeds from captive offshore development centers through U.S.-based client-facing program offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering Research and Development services function as a service-attach opportunity where outcome-based maintenance contracts and continuous verification subscriptions expand faster than discrete hardware design engagements. Recurring revenue layers around digital twin platform licenses and automated regression testing subscriptions outpace traditional stage-gate project economics.
For Market Incumbents: Secure domestic facility expansion in Arizona and Texas to capture CHIPS Act eligibility requirements, while anchoring ISO 13485 certification depth against emerging healthcare-focused boutiques. Functional safety certification scarcity threatens margin compression as automotive electrification timelines accelerate. Vertical integration into simulation software distribution reinforces pricing power against algorithmic design commoditization. For New Entrants and Emerging Players: FDA 510(k) fast-track specialization opens white-space in Minnesota and Massachusetts medical device clusters where incumbent IT services giants lack quality system depth. Target biomechanical simulation and verification outsourcing as the most penetrable segment given tightening premarket submission timelines. Pursue strategic partnerships with academic medical centers to anchor clinical validation credibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive engineering boutiques in Michigan and Ohio facing succession pressure as founder-owners approach retirement. Long-term viability centers on dual-use technology convergence where defense primes license commercial automotive IP for unmanned systems. Watch Bureau of Industry and Security export control expansions as the inflection signal for domestic engineering center valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CHIPS Act Compliance Certification | Federal domestic content requirements steer advanced packaging contracts toward eligible U.S. engineering centers. |
| ISO 26262 ASIL-D Accreditation | Automotive functional safety certification extends validation schedules and locks out unqualified competitors. |
| Digital Twin Platform Integration | Simulation-driven verification workflows collapse physical prototyping cycles and anchor recurring subscription revenue. |
| FDA Quality System Partnership | ISO 13485-certified engineering centers capture outsourced biomechanical simulation from Minnesota device clusters. |
| Dual-Use Technology Licensing | Defense primes licensing commercial automotive battery management IP opens classified-adjacent contract channels. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with engineering procurement officers, program managers at Tier 1 automotive suppliers, biomedical device executives, and federal contracting specialists; and secondary validation against SEC 10-K filings, FDA 510(k) submission databases, CHIPS Act procurement disclosures, and Bureau of Industry and Security export control classifications. Bottom-up project pipeline analysis triangulated against top-down OEM R&D budget allocations.
Across the analysis window, the forecasting framework modeled service type evolution, industry vertical penetration, technology adoption curves, and end-user procurement sophistication. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Key inputs included automotive electrification timeline acceleration, FDA premarket submission outsourcing rates, and federal domestic content incentive disbursement patterns.
Underlying assumptions cover stable CHIPS Act funding continuity and unaltered export control classifications, with deviation risk concentrated in automotive production target revisions and healthcare regulatory pathway changes. Practitioners should keep alternative scenarios live as federal procurement rule amendments and semiconductor foundry geography shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Bridge Inspection System Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
Foundation Repair Services Market
Engineering Services
Aerospace Engineering Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Architectural Services Market
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Engineering Services Market
Engineering Services
Engineering Design Service Market
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market