
 Qatar Payments Market | 2026-2036
Qatar Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Payments Market Analytics
Embedded finance bundling is pivoting how Qatari merchants select payment infrastructure, collapsing separate acquiring, wallet, and loyalty functions into unified stacks. Qatar National Bank leverages its branch network to anchor merchant relationships at premium hospitality venues. Ooredoo Money competes through telecom-integrated mobile wallets that bypass traditional banking onboarding friction. Mastercard Incorporated extends its position via tokenization partnerships with local issuers seeking contactless migration.
Payments encompass the electronic transfer of monetary value between transacting parties using card networks, digital wallets, bank rails, or mobile money platforms, with settlement latency, interchange fee structures, and PCI-DSS compliance serving as core technical parameters governing system architecture. The Qatar Payments Market segments by payment method, transaction type, end user, and service type. Mobile wallets within payment method represent the fastest-growing vector as NFC terminal deployment accelerates across Doha's retail and transit infrastructure. Payment processing services capture disproportionate margin pools due to volume-based pricing tiers and cross-border currency conversion attach rates.
Qatar Central Bank's regulatory sandbox and the Qatar Financial Centre Authority govern licensing, data localization, and open banking standards that shape fintech market access and product specifications. The country's national payments system operator enforces real-time gross settlement protocols that constrain non-bank provider participation. Stakeholders must monitor how central bank digital currency pilots and open API mandates reshape competitive moats between incumbent banks and wallet-native challengers.
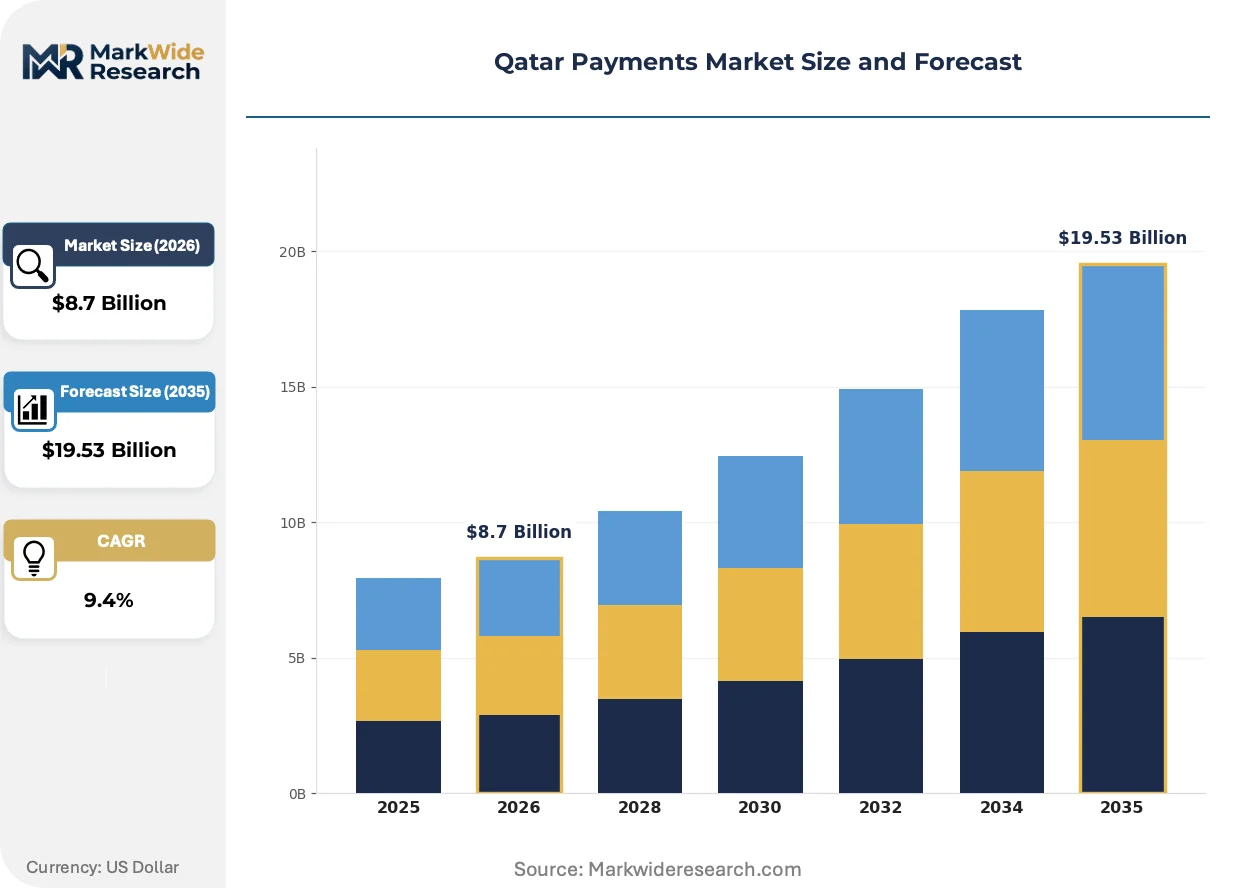
Market Dynamics
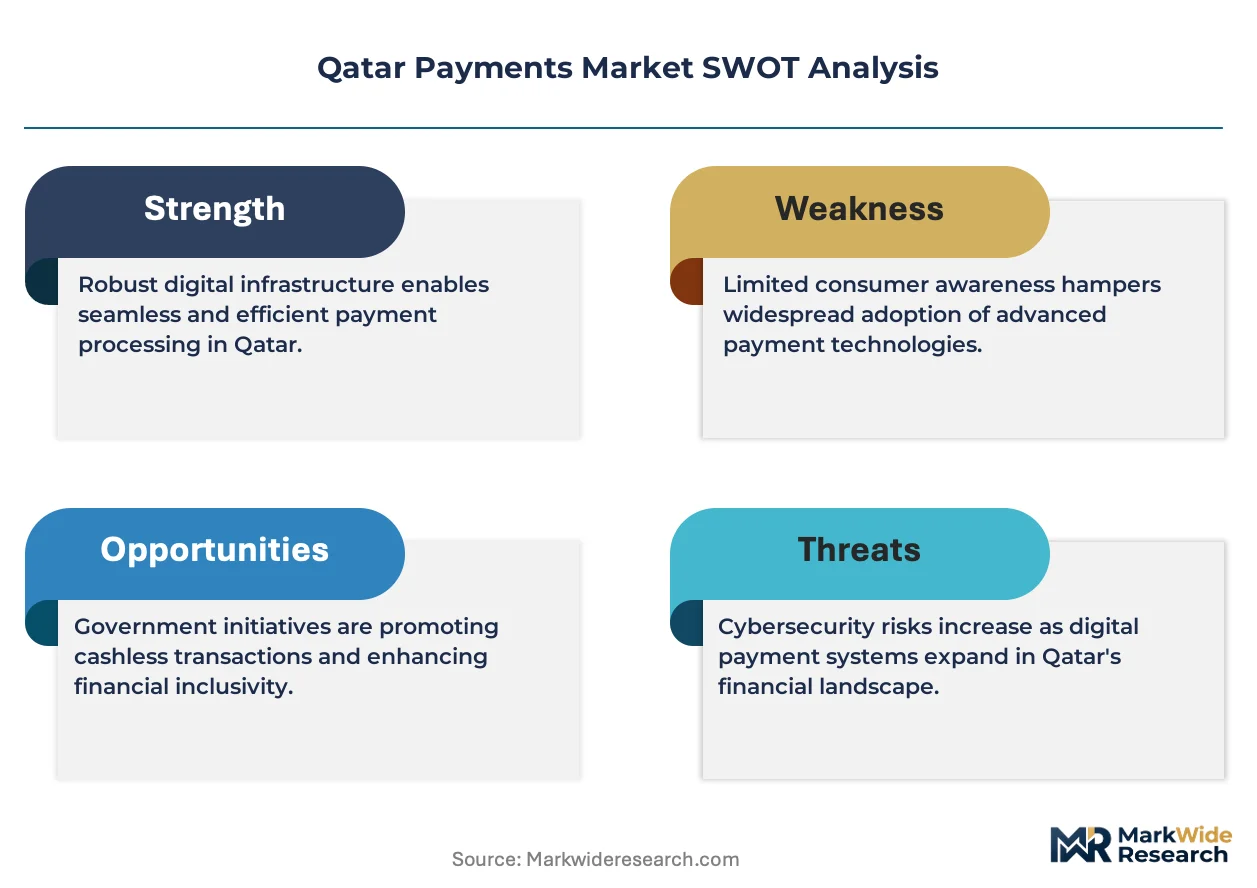
Qatar's payments infrastructure is undergoing a fundamental reconfiguration as the Qatar Central Bank's regulatory sandbox dismantles the traditional bank-centric licensing monopoly, enabling non-bank wallet providers to capture merchant relationships previously locked behind branch networks.
Growth Catalysts
- NFC Terminal Deployment:Transit authority mandates for contactless fare collection across Doha's metro and bus networks are forcing retail merchants to upgrade point-of-sale hardware, creating downstream wallet adoption pull-through.
- Qatar Central Bank Sandbox:The regulatory framework permits live experimentation with tokenized credentials and real-time settlement protocols, reducing time-to-market for fintechs from 18 months to under 90 days.
- Hospitality Transaction Velocity:FIFA World Cup legacy infrastructure and year-round tourism flows concentrate high-frequency, low-value payments in Doha's hotel and restaurant corridor, accelerating mobile wallet penetration.
Market Restraints
- Real-Time Gross Settlement Protocols:The national payments system operator enforces bank-only participation in settlement finality, forcing wallet providers to route through correspondent banking relationships that add 15-40 basis points to transaction economics.
- Data Localization Mandates:Qatar Financial Centre Authority requirements for domestic server infrastructure raise capex thresholds for foreign fintech entrants, privileging capitalized incumbents with existing data center presence.
- Interchange Fee Compression Resistance:Premium hospitality merchants negotiate bespoke acquiring rates that undercut standard pricing tiers, constraining processor margin pools in the highest-volume transaction categories.
Strategic Opportunities
- Lusail Smart City Integration:The planned city's IoT infrastructure creates white space for payment-embedded utility and mobility services that bundle transit, parking, and retail into unified wallet experiences.
- Cross-Border Remittance Rails:South Asian expatriate worker corridors into Qatar remain underserved by low-cost digital channels, presenting opportunity for blockchain-anchored settlement partnerships with Bangladesh and Nepal regulators.
- Open API Standardization:Anticipated Qatar Central Bank mandates for account information and payment initiation services will force incumbent banks to expose customer data, enabling third-party wallet providers to build on top of legacy deposit bases.
Industry Challenges
- PCI-DSS Certification Bottlenecks:Qualified security assessor capacity in the Gulf region is concentrated in Dubai and Riyadh, extending compliance timelines for Doha-based fintechs by 4-6 months.
- Legacy Core Banking Integration:Wallet-native challengers face fragmented API documentation and batch-oriented settlement windows when connecting to incumbent bank infrastructure, degrading real-time user experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Payments Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Cards, Debit Cards, Mobile Wallets, Bank Transfers Transaction Type: Online Payments, Point of Sale, Recurring Payments, Peer-to-Peer End User: Consumers, Merchants, Enterprises, Financial Institutions Service Type: Payment Processing, Fraud Detection, Currency Conversion, Digital Wallet Management |
| Companies Covered | PayPal Holdings, Inc., CashU, Qatar National Bank, Mastercard Incorporated, Qatar Islamic Bank, Commercial Bank of Qatar, Ooredoo Money, Visa Inc., Doha Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Payments Market Evolving Landscape
Tokenization architecture and biometric authentication protocols are collapsing the traditional separation between payment credentials and identity verification, enabling Qatar's hospitality sector to merge checkout, loyalty, and access control into single-touch interactions.
SoftPOS technology is automating merchant onboarding by converting standard Android devices into payment acceptance terminals without dedicated hardware procurement. Small retailers in Doha's souq districts are adopting this capability within 48-hour activation windows, compressing the traditional 2-4 week terminal deployment cycle. The technology is automating acquirer sales force economics by eliminating physical site visits and logistics coordination.
Qatar Central Bank's anticipated open banking framework will mandate standardized API disclosures for account aggregation and payment initiation. This regulatory shift forces incumbent banks to expose transaction histories and balance data to licensed third parties, eroding proprietary data moats. Premium card issuers are responding by accelerating tokenization partnerships to maintain brand presence at the point of interaction.
Corporate treasury departments in Qatar's energy and construction sectors are consolidating vendor payment flows onto single-platform solutions that embed FX hedging and working capital analytics. This procurement consolidation displaces fragmented bank relationships and manual reconciliation processes. The shift is most visible among mid-market contractors executing government infrastructure contracts with milestone-based disbursement requirements.
Qatar Payments Market Segmentation
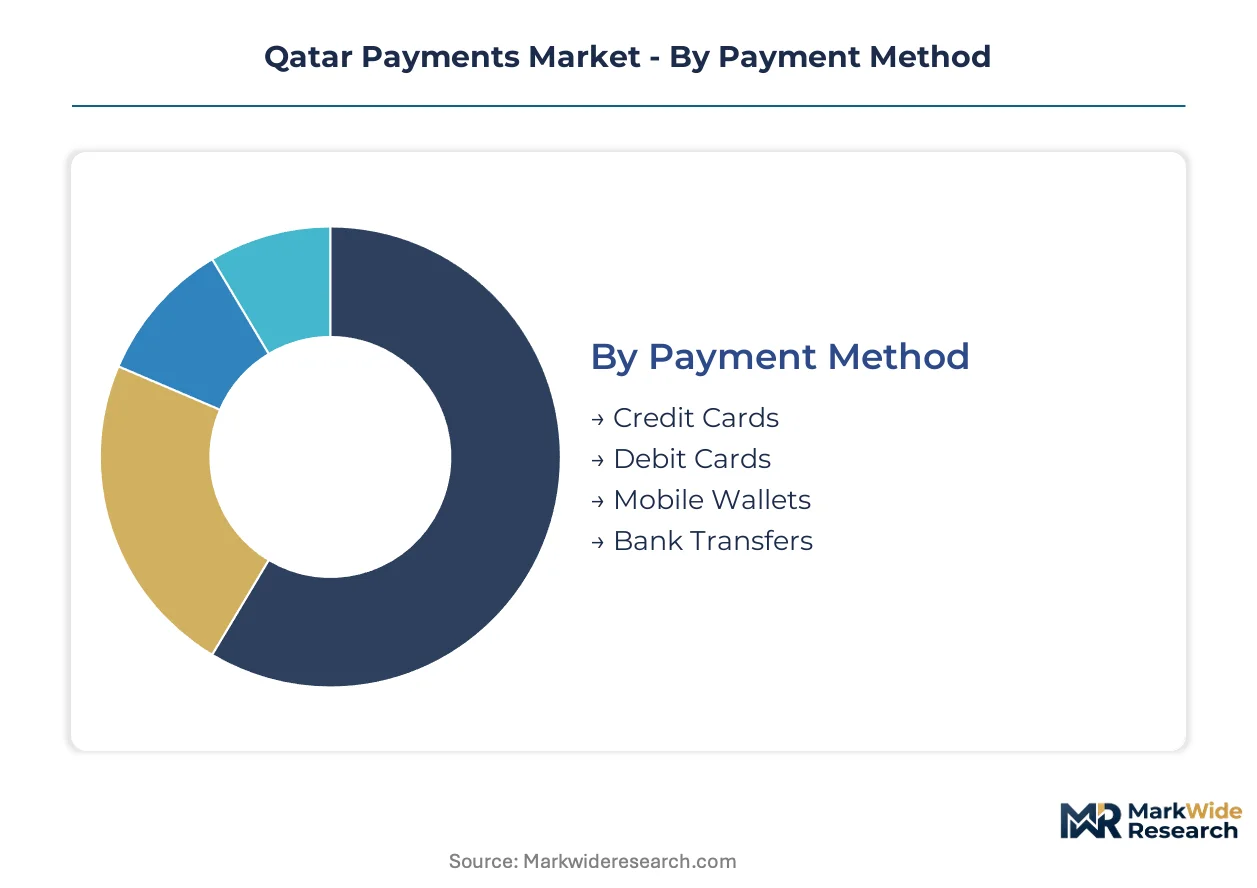
Qatar's payment infrastructure fragmentation demands granular segmentation to map how regulatory requirements, hardware dependencies, and user behaviors concentrate value across distinct transaction modes. Each category carries specific compliance burdens from Qatar Central Bank mandates that reshape provider economics.
Payment Method:
PCI-DSS Level 1 certification governs card-based segments, while mobile wallets navigate Qatar Central Bank sandbox approvals with lighter hardware requirements but stricter data localization protocols.
- Credit Cards:Tokenized credential networks dominate hospitality and luxury retail corridors in Doha's West Bay district. Qatar National Bank and international schemes maintain acquiring relationships at premium venues where contactless terminal penetration exceeds other merchant tiers.
- Mobile Wallets:NFC-enabled smartphone applications are displacing card-present transactions across transit and quick-service restaurant verticals. Ooredoo Money and bank-integrated wallets leverage telecom distribution to bypass traditional branch onboarding friction in Lusail and Pearl-Qatar developments.
- Debit Cards:PIN-verified bank-issued instruments anchor salary disbursement and government benefit distribution channels.
- Bank Transfers:Real-time gross settlement rails constrain non-bank participation to correspondent banking arrangements with 15-40 basis point cost overlays.
Mobile wallets sit at the top of the volume ranking, with credit cards climbing the fastest as FIFA World Cup legacy infrastructure drives contactless terminal refresh cycles.
Transaction Type:
Cost tier differentiation separates hardware-intensive point-of-sale deployments from lightweight peer-to-peer applications that bypass merchant acquiring infrastructure entirely.
- Point of Sale:Terminal-dependent transactions require EMV certification and local network integration with Qatar's national switch. Retail merchants in Doha's Souq Waqif and City Center corridors absorb hardware refresh costs to maintain card scheme compliance.
- Peer-to-Peer:Wallet-to-wallet transfers operate on closed-loop telecom or banking rails with minimal interchange leakage. South Asian expatriate corridors into Industrial Area labor camps concentrate demand for low-cost remittance substitutes.
- Online Payments:3D Secure authentication and merchant category code restrictions govern e-commerce checkout flows.
- Recurring Payments:Mandate management and pre-authorization frameworks service utility and subscription billing verticals.
Point of sale commands the highest absolute transaction value, with peer-to-peer expanding most quickly as wallet penetration deepens among unbanked labor populations.
End User:
Customer type determines pricing architecture, with enterprise segments negotiating bespoke acquiring rates that undercut standard interchange tiers available to smaller merchants.
- Merchants:Hospitality and retail acquirers in Doha's Corniche and Katara zones negotiate volume-based pricing with embedded loyalty and analytics attachments. Premium hotel operators extract sub-interchange rates through direct bank relationships that compress processor margins.
- Enterprises:Corporate treasury departments in energy and construction sectors consolidate vendor payments onto single-platform solutions with embedded FX hedging. Mid-market contractors executing government infrastructure contracts drive demand for milestone-based disbursement automation.
- Consumers:Individual account holders select payment instruments based on reward structures and contactless acceptance ubiquity.
- Financial Institutions:Banks and wallet operators compete for deposit base access through API-integrated payment initiation services.
Merchants generate the highest transaction throughput, with enterprises gaining share fastest as procurement digitization displaces fragmented banking relationships.
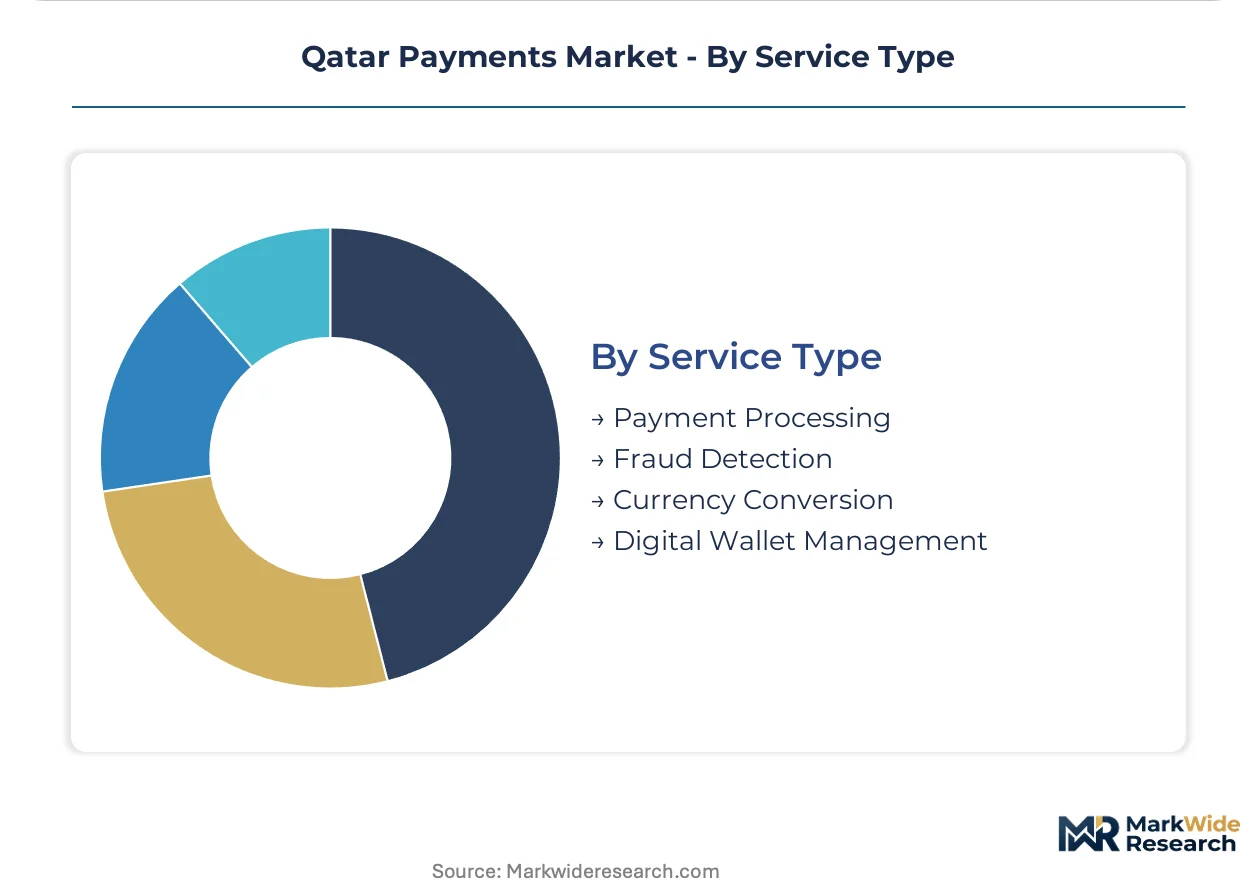
Service Type:
Margin concentration varies sharply across the stack, with payment processing capturing volume-based economics while fraud detection attaches subscription pricing to transaction flows.
- Payment Processing:Acquiring and authorization infrastructure commands the largest revenue pool through interchange capture and cross-border currency conversion spreads. Qatar's real-time gross settlement protocols limit non-bank direct participation, forcing wallet providers into correspondent banking arrangements.
- Digital Wallet Management:Credential tokenization and user interface layers compete for primary account status through loyalty integration and merchant-funded rewards. SoftPOS deployment is collapsing merchant onboarding timelines from weeks to hours in Doha's traditional souq districts.
- Fraud Detection:Machine learning scoring engines attach to transaction flows as subscription or per-check services.
- Currency Conversion:FX spread capture concentrates on remittance corridors and cross-border e-commerce settlements.
Payment processing dominates absolute revenue generation, with digital wallet management ascending fastest as embedded finance bundling collapses previously separate infrastructure layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's payments infrastructure traces its modern lineage to the Qatar Central Bank's establishment of national electronic clearing systems in the early 2000s, which created the foundational rails for today's digital wallet proliferation across Doha's commercial corridors.
Doha Metropolitan Area
Hospitality and tourism transactions in West Bay and the Corniche district drive the highest mobile wallet penetration rates in Qatar. Qatar Central Bank's regulatory sandbox enables fintech experimentation with tokenized credentials and real-time settlement protocols. The Lusail development corridor concentrates NFC terminal deployment as transit authority mandates force retail merchant hardware upgrades.
Al Rayyan Municipality
Education City and healthcare cluster institutions generate recurring payment flows for tuition and medical services. The Qatar Financial Centre Authority enforces data localization requirements that raise infrastructure thresholds for foreign entrants. Mall of Qatar and surrounding retail nodes anchor acquiring relationships for premium hospitality merchants.
Al Wakrah Municipality
Industrial Area labor camps concentrate demand for low-cost peer-to-peer remittance substitutes among South Asian expatriate workers. The national payments system operator's real-time gross settlement protocols constrain non-bank wallet participation to correspondent banking arrangements. Hamad Port logistics operations drive corporate treasury digitization for vendor payment consolidation.
Al Khor and Al Thakhira
North Field energy sector operations generate high-value B2B payment flows requiring milestone-based disbursement automation. Qatar Central Bank's anticipated open banking framework will mandate API disclosures for account aggregation services. Ras Laffan Industrial City anchors specialized payment processing relationships for energy and construction contractors.
Umm Salal and Al Daayen
Residential developments in Lusail and Pearl-Qatar create white space for payment-embedded utility and mobility services. SoftPOS technology adoption accelerates merchant onboarding in traditional souq districts by converting Android devices into acceptance terminals. Barwa City and surrounding communities concentrate telecom-integrated wallet distribution through Ooredoo's retail network.
Qatar Payments Market Competitive Landscape
The competitive structure tilts toward bank-centric incumbents with branch network advantages and telecom-integrated challengers bypassing traditional onboarding friction. Qatar National Bank leverages its physical presence to anchor merchant relationships at premium hospitality venues. Three strategic archetypes dominate: legacy banks with acquiring infrastructure, telecom-operated mobile wallets, and international scheme providers extending tokenization partnerships. Dominant competitive moves include sandbox-enabled fintech experimentation and SoftPOS deployment compressing merchant activation timelines.
Among bank-based operators, Qatar National Bank, Qatar Islamic Bank, and Commercial Bank of Qatar occupy positions anchored by branch networks and direct central bank settlement access. Mastercard Incorporated and Visa Inc. represent the international scheme tier extending tokenization architecture to local issuers. Ooredoo Money exemplifies the telecom-integrated challenger archetype leveraging mobile distribution to capture wallet relationships outside traditional banking channels. PayPal Holdings, Inc. and CashU sit within the cross-border digital payment segment serving e-commerce and remittance corridors.
| Leading Market Players |
|---|
| PayPal Holdings, Inc. |
| CashU |
| Qatar National Bank |
| Mastercard Incorporated |
| Qatar Islamic Bank |
| Commercial Bank of Qatar |
| Ooredoo Money |
| Visa Inc. |
| Doha Bank |
| Others |
Value Network & Pricing Analysis
Hospitality merchant consolidation in Doha's West Bay corridor forces payment processors to absorb hardware deployment costs upfront, compressing margins until transaction volumes cross subsidy recovery thresholds. This procurement concentration privileges incumbents with existing terminal fleets and correspondent banking relationships.
Pricing Analysis
Three-tier pricing structure across premium hospitality, standard retail, and economy peer-to-peer levels governs Qatar's payment landscape. Premium hotel operators extract sub-interchange rates through direct Qatar National Bank relationships, while standard retail absorbs EMV certification costs. Pricing pressure stems from SoftPOS technology collapsing merchant onboarding timelines and eliminating hardware lease revenue streams. Small souq merchants exhibit highest price sensitivity, whereas energy sector treasuries prioritize FX hedging integration over transaction fees.
Supply Chain Analysis
Direct-to-merchant channels dominate hardware distribution, with terminal manufacturers routing through Qatar Central Bank-certified system integrators for EMV compliance. Payment hardware supply concentrates in China, Taiwan, and South Korea for NFC chipsets and secure element modules. Semiconductor fabrication for tokenization security modules draws from TSMC and Samsung foundry capacity. Single-source vulnerability sits with qualified security assessor concentration in Dubai and Riyadh, extending PCI-DSS certification timelines for Doha-based fintechs by 4-6 months.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's payments market compounds value through regulatory architecture, with Qatar Central Bank's open banking mandates forcing incumbent banks to expose customer data and erode proprietary moats.
For Market Incumbents: Deploy tokenization partnership levers to maintain brand presence at point-of-interaction as wallet-native challengers erode deposit base access. Qatar National Bank must accelerate SoftPOS merchant onboarding to defend against Ooredoo Money's telecom distribution advantage. Incumbents should secure direct central bank settlement access before real-time gross settlement protocols expand to non-bank participants. For New Entrants and Emerging Players: Qatar Central Bank's regulatory sandbox in Doha opens a window for fintech experimentation with 90-day time-to-market compression. White space concentrates in Lusail smart city payment-embedded utility services and Industrial Area peer-to-peer remittance corridors for South Asian expatriates. New entrants should anchor go-to-market through telecom-integrated distribution bypassing traditional branch onboarding friction. For Investors and Strategic Acquirers: Asymmetric upside sits with wallet-native challengers possessing sandbox approvals and data localization infrastructure. Long-term viability favors providers with direct central bank settlement access or correspondent banking relationships below 20 basis points cost overlay. Watch Qatar Central Bank digital currency pilot announcements as inflection signal for incumbent-displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sandbox Fintech Experimentation | Qatar Central Bank's 90-day approval window accelerates tokenized credential deployment ahead of incumbent response cycles. |
| SoftPOS Merchant Activation | Android-based terminal conversion collapses Doha souq onboarding from weeks to hours, displacing hardware logistics providers. |
| Open Banking API Integration | Mandated account information services force Qatar National Bank to expose transaction histories to licensed third-party wallets. |
| Cross-Border Remittance Partnership | Blockchain-anchored settlement with Bangladesh and Nepal regulators targets South Asian expatriate labor camp corridors. |
| Lusail Smart City Bundling | IoT-embedded transit, parking, and retail payments create unified wallet experiences in Qatar's planned development corridor. |
Research Methodology
Multiple input streams — primary interviews with payment processing executives, Qatar Central Bank regulatory affairs leads, and hospitality merchant acquiring managers — were reconciled against secondary validation from Qatar Financial Centre Authority filings, SEC disclosures by international scheme providers, and customs data on terminal hardware imports. Bottom-up transaction volume modeling and top-down GDP-attribution approaches were triangulated to constrain estimate variance.
Data-stream reconciliation across payment method, transaction type, end user, and service type segmentation dimensions produced volume and value outputs over the projection horizon. CAGRs were derived from fitted growth curves anchored to NFC terminal deployment trajectories and wallet penetration elasticity estimates. Forecast inputs incorporated Qatar Central Bank sandbox approval velocity and open banking mandate implementation timelines.
Revisions become necessary when regulatory sandbox scope expands, central bank digital currency pilots advance, or real-time gross settlement protocols modify non-bank participation rules. Forecasts reflect assumptions about merchant hardware refresh cycles and expatriate remittance corridor digitization. Periodic stress-testing of base assumptions against Qatar Central Bank policy announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Transit Cards Market
Payments
Credit Card Issuance Services Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Online Charging System (OCS) Market
Payments
Vietnam Payments Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Money Transfer Agencies Market
Payments
China Forex Cards Market
Payments
Global Utility Billing Software Market
Payments
Instant Payments Market
Payments
Norway Mobile Payments Market
Payments
Indonesia Prepaid Cards Market
Payments
United Kingdom Mobile Payments Market
Payments
Payment Service Provider Market
Payments
Hong Kong Credit Cards Market
Payments
Contactless Payment Ring Market