
 Crypto Payment Gateway Market | 2026-2036
Crypto Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Crypto Payment Gateway Market Analysis
The capital-intensity gap between self-hosted infrastructure and hosted API deployment is collapsing. Stripe leverages its existing merchant network to embed crypto rails without standalone node operations. BVNK anchors its model on banking-as-a-service licenses across multiple jurisdictions. CoinsPaid specializes in high-velocity settlement for iGaming and digital commerce verticals.
A crypto payment gateway is a software layer that encrypts transaction data, validates blockchain confirmations, and converts volatile digital assets into fiat or stablecoin balances for merchants. Settlement latency typically ranges from near-instant for Layer-2 networks to several hours for main-chain Bitcoin, with fee structures scaling by network congestion and confirmation depth. Hosted solutions dominate current merchant adoption due to minimal technical setup, while API solutions attract enterprises requiring white-label control over user interfaces and fund flows. Cross-border payments represent the fastest-growing transaction type as businesses seek alternatives to correspondent banking delays and FX markups.
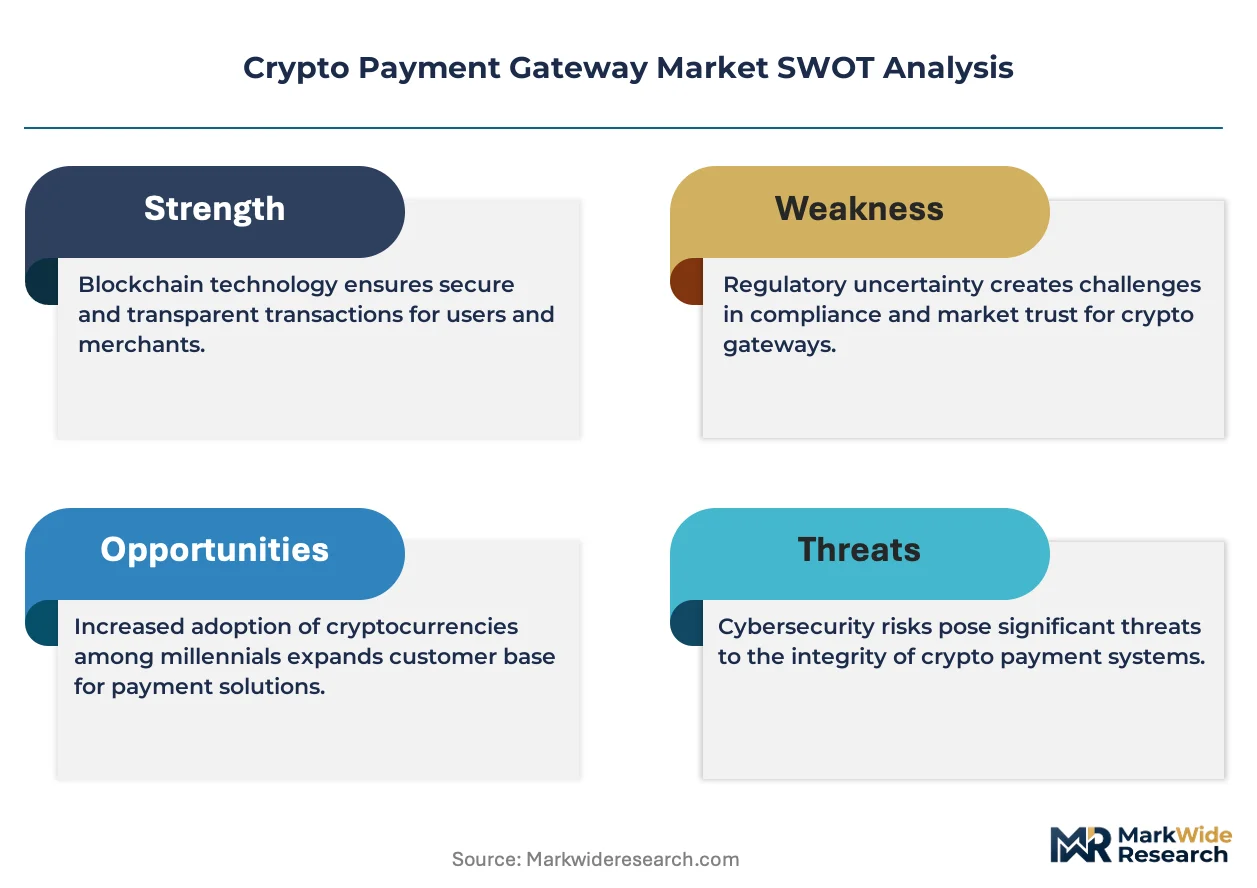
The SEC and state-level financial regulators in the United States enforce money transmitter licensing that determines market access for gateway operators. MiCA in the European Union establishes reserve requirements and consumer protection standards that elevate compliance costs for smaller entrants. ISO 20022 messaging standards and FATF travel rule implementation shape technical architecture for transaction monitoring. Stakeholders must weigh jurisdictional licensing breadth against the operational overhead of multi-entity compliance structures as regulatory fragmentation persists.
Market Dynamics
Settlement velocity requirements from iGaming and cross-border commerce are compressing the technical gap between hosted and self-hosted gateway architectures. Merchants now demand sub-minute finality regardless of underlying blockchain confirmation depth.
Growth Catalysts
- MiCA Licensing Framework:The European Union's unified regulatory regime reduces jurisdictional fragmentation for gateway operators holding banking-as-a-service credentials across member states.
- Layer-2 Settlement Rails:Polygon and Arbitrum integrations enable near-instant confirmation for e-commerce checkouts without exposing merchants to base-layer volatility.
- Singapore Banking Partnerships:The Monetary Authority of Singapore's payment institution framework attracts gateway providers seeking APAC regulatory clarity and correspondent banking access.
Market Restraints
- State-Level Licensing Proliferation:The United States maintains fifty distinct money transmitter regimes, each requiring separate surety bonds and compliance audits that multiply operational overhead.
- Stablecoin Reserve Requirements:MiCA mandates full asset backing and segregation for euro-denominated stablecoins, elevating capital costs for settlement liquidity providers.
- Correspondent Bank De-risking:Traditional clearing banks in the United Kingdom and Switzerland terminate relationships with crypto-facing entities, constricting fiat off-ramp capacity.
Strategic Opportunities
- Brazilian Cross-Border Remittance:Central Bank of Brazil's Pix instant payment system integration with crypto rails addresses correspondent banking delays for LATAM corridor flows.
- ISO 20022 Convergence:Messaging standardization between traditional SWIFT networks and blockchain transaction formats enables hybrid settlement architectures for enterprise treasury operations.
- Embedded Finance Distribution:SaaS platforms and vertical software providers integrate white-label crypto checkout modules, bypassing direct merchant acquisition costs.
Industry Challenges
- Travel Rule Implementation:FATF requirements for originator and beneficiary data transmission across unhosted wallets create technical architecture burdens that delay product launches.
- Blockchain Forensics Integration:Real-time transaction monitoring for sanctions compliance demands specialized engineering talent scarce in traditional fintech labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crypto Payment Gateway Market |
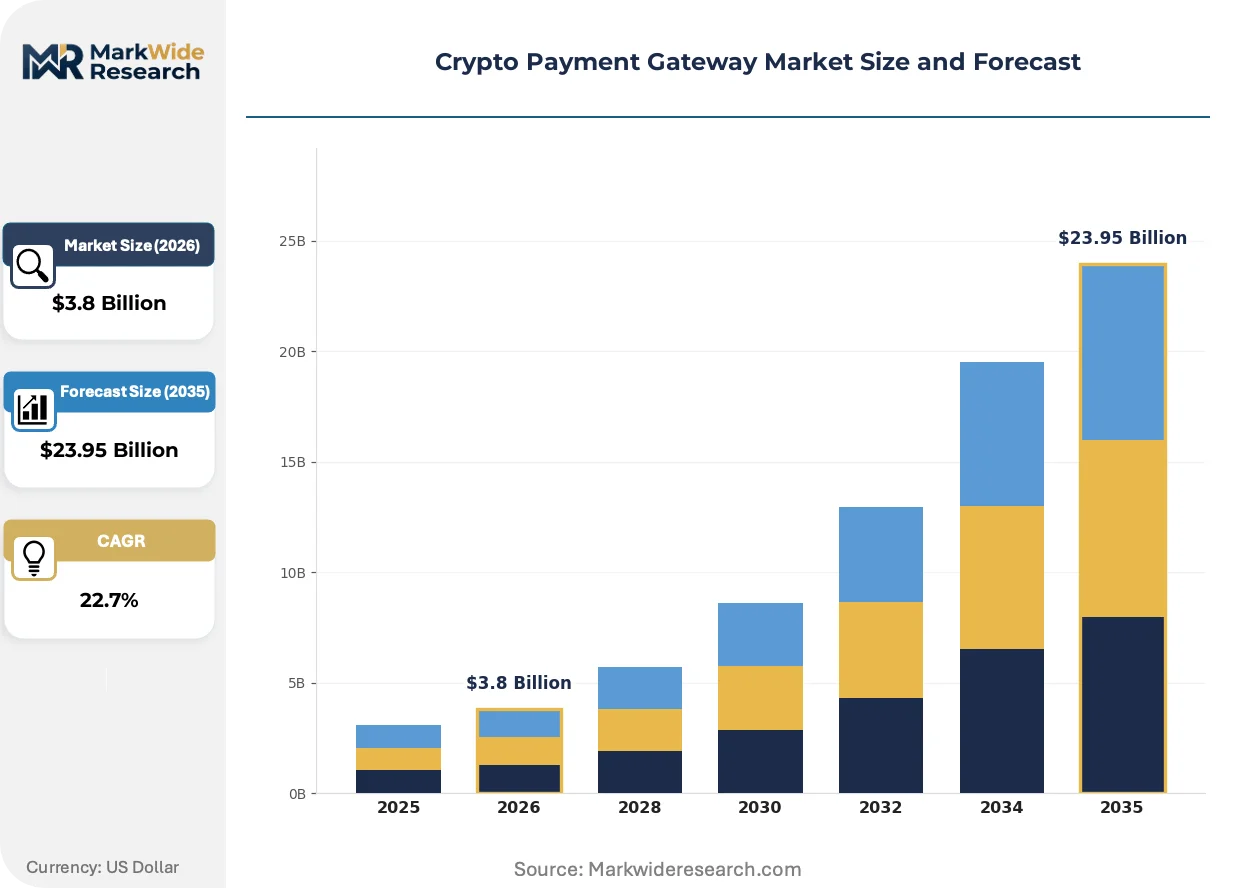
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Hosted Solutions, Self-Hosted Solutions, API Solutions, Multi-Currency Solutions End User: E-Commerce Platforms, Retail Businesses, Service Providers, Cryptocurrency Exchanges Transaction Type: Online Transactions, In-Store Transactions, Cross-Border Payments, Peer-to-Peer Transactions Integration Method: Web Integration, Mobile Integration, POS Integration, Custom Integration |
| Companies Covered | Stripe, BitPay, BVNK, CoinPayments, CoinGate, NOWPayments, Triple A, PayRam, CoinsPaid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crypto Payment Gateway Market Emerging Trajectories
Gateway infrastructure is splitting between low-code merchant onboarding and enterprise-grade API control. This technical divergence is reshaping competitive positioning across settlement speed, compliance automation, and fund custody models.
Layer-2 network adoption is bifurcating merchant gateway preferences. Polygon's proof-of-stake chain delivers sub-second finality for digital commerce checkouts. iGaming operators and NFT marketplaces have migrated settlement volume to these rails. The technology is compressing the pricing power of legacy main-chain gateway providers.
MiCA's reserve requirements and consumer protection standards are forcing operational restructuring. Gateway operators must maintain segregated cold storage and publish audited attestations. Smaller hosted providers in Germany and France are consolidating to distribute compliance costs across larger transaction bases.
Merchant procurement of gateway services now prioritizes bundled compliance over standalone transaction fees. Platforms in Singapore and the United Kingdom negotiate flat-rate subscriptions covering KYC automation, travel rule screening, and regulatory reporting. This unbundling of payment processing from risk management is visible most acutely in high-velocity verticals.
Crypto Payment Gateway Market Segmentation
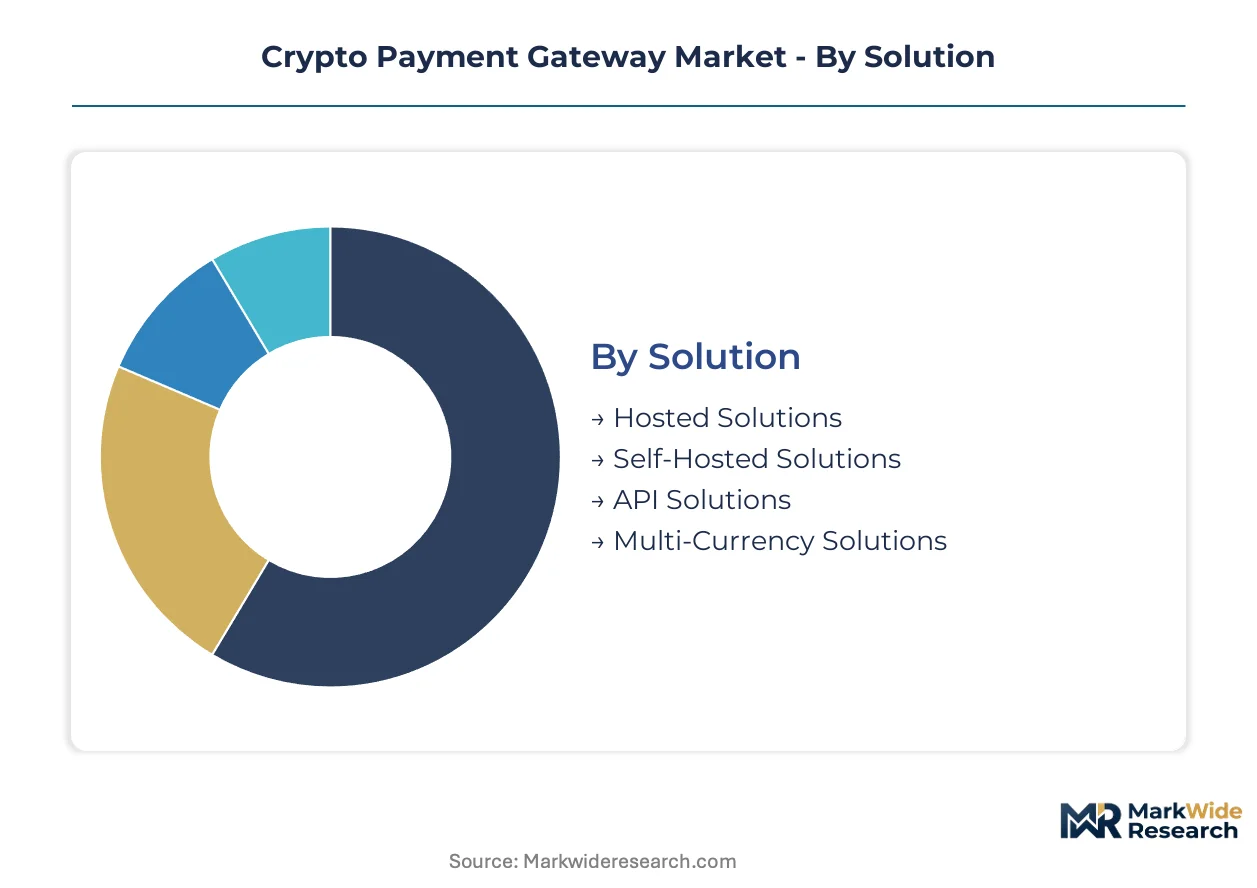
Crypto payment gateway segmentation reveals how technical architecture choices map directly to regulatory exposure and capital requirements. Merchants select solution tiers based on jurisdictional licensing burdens, settlement velocity needs, and custody risk tolerance.
Solution:
MiCA reserve requirements and state-level money transmitter rules create divergent compliance costs across deployment models. Hosted solutions minimize licensing overhead for merchants while API architectures demand direct regulatory engagement.
- Hosted Solutions:Third-party providers manage node infrastructure, private key custody, and fiat off-ramp relationships. E-commerce platforms in Germany and France favor this model to avoid MiCA-mandated cold storage audits and segregated reserve obligations.
- Self-Hosted Solutions:Merchants operate proprietary nodes and maintain direct control over transaction validation. Cryptocurrency exchanges and high-volume iGaming operators in Singapore deploy this architecture to achieve sub-minute finality without intermediary dependencies.
- API Solutions:White-label integration layers embed crypto checkout into existing merchant software stacks. Retail businesses seeking branded payment experiences drive demand across the United Kingdom and Switzerland.
- Multi-Currency Solutions:Unified rails supporting Bitcoin, Ethereum, and stablecoin settlement through single integration endpoints. Cross-border remittance corridors in Brazil and Mexico favor this flexibility.
Hosted solutions handle the majority of throughput; API solutions are gaining share fastest among enterprise merchants.
End User:
Settlement latency requirements vary sharply by merchant category. Digital commerce platforms demand near-instant confirmation while physical retailers prioritize POS integration reliability.
- E-Commerce Platforms:Online merchants require Layer-2 network compatibility and automated stablecoin conversion to minimize checkout abandonment. United States-based marketplaces drive volume through Stripe-embedded crypto rails.
- Retail Businesses:Brick-and-mortar operators depend on POS hardware integration and QR-code-based wallet connectivity. Singapore's shopping district merchants lead APAC adoption of hybrid fiat-crypto terminals.
- Service Providers:Subscription and SaaS businesses leverage recurring billing automation with volatility hedging. United Kingdom consultancies and digital agencies represent concentrated demand.
- Cryptocurrency Exchanges:Trading platforms require deep liquidity pools and institutional-grade custody for high-velocity settlement. Offshore operators in the British Virgin Islands and Seychelles anchor wholesale transaction volumes.
E-commerce platforms dominate current transaction value; service providers are expanding most quickly as recurring billing models mature.
Transaction Type:
Correspondent banking friction and FX markup avoidance reshape demand patterns across payment categories. Geographic distance between sender and receiver increasingly determines rail selection.
- Cross-Border Payments:B2B and remittance flows bypass SWIFT delays through blockchain settlement. Brazilian Pix-crypto integrations and United Kingdom-Singapore corridors show steepest expansion trajectories.
- Online Transactions:Digital checkout processes integrate crypto alongside card networks. Polygon and Arbitrum finality compresses merchant exposure to price volatility.
- Peer-to-Peer Transactions:Direct wallet transfers without intermediary processing. Travel rule compliance burdens constrain growth in FATF-regulated jurisdictions.
- In-Store Transactions:Physical point-of-sale crypto acceptance through NFC and QR interfaces. Limited adoption outside Singapore and Swiss urban centers due to hardware upgrade costs.
Cross-border payments command the highest average transaction size; online transactions lead on absolute volume.
Integration Method:
Developer resource availability and time-to-market pressure determine technical implementation paths. Low-code options accelerate merchant onboarding while custom builds retain pricing power.
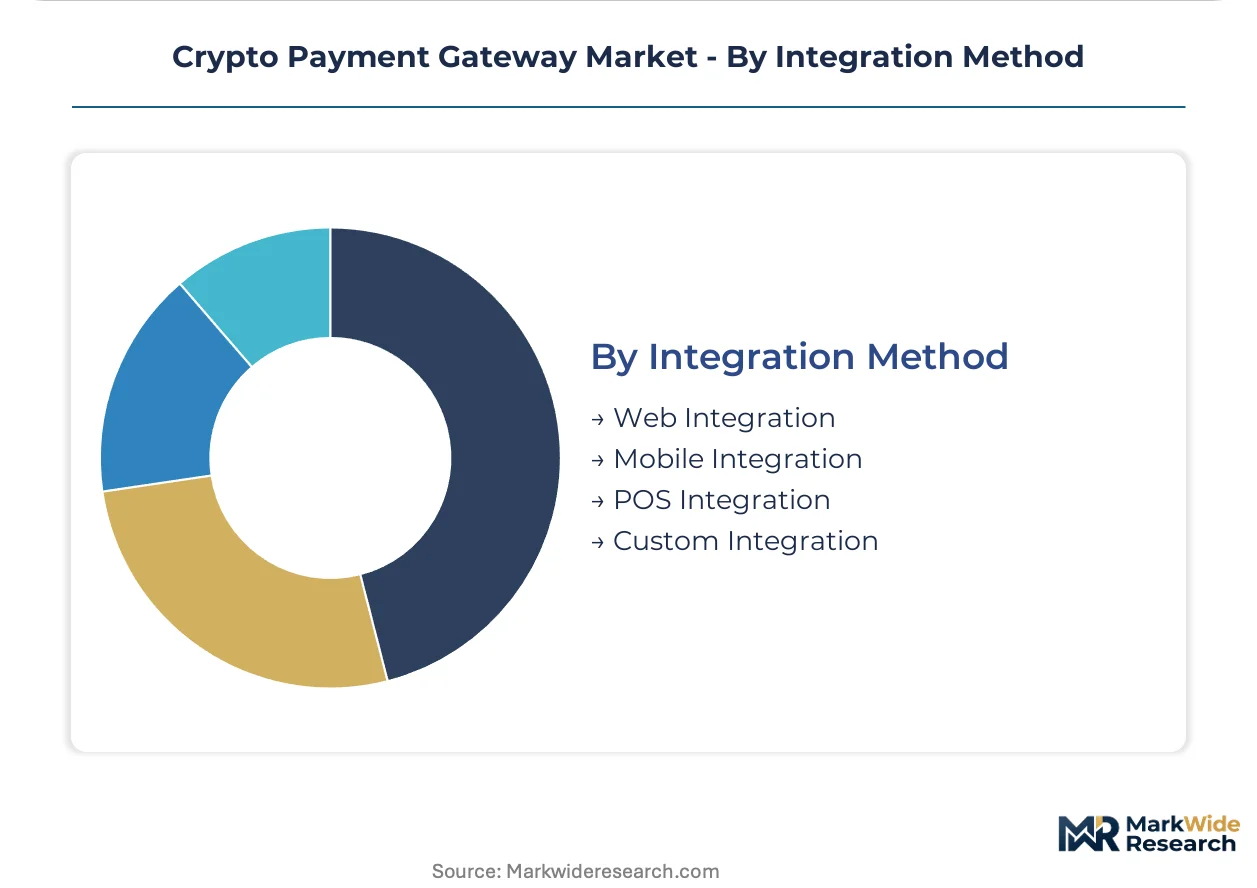
- Web Integration:JavaScript SDKs and hosted checkout pages enable rapid deployment. Small merchants across the United States and United Kingdom favor this minimal-technical-setup path.
- Mobile Integration:Native iOS and Android SDKs support in-app purchasing with biometric authentication. Southeast Asian super-apps drive concentrated demand.
- POS Integration:Hardware terminal compatibility with existing retail infrastructure. European payment service providers bundle this capability under MiCA-compliant service packages.
- Custom Integration:Direct API access for enterprise treasury and ERP system connectivity. Large United States retailers and institutional traders require this control level.
Web integration captures the broadest merchant base; mobile integration is climbing fastest as in-app commerce expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Singapore and the United States, where banking partnerships and regulatory clarity command premium settlement fees, while operators in fragmented European jurisdictions absorb higher compliance costs per transaction.
United States
E-commerce platforms and iGaming operators drive merchant onboarding volumes through Stripe-embedded crypto rails. State-level money transmitter licensing across fifty jurisdictions multiplies operational overhead, particularly for smaller gateway entrants. New York and California anchor the highest transaction densities, where institutional traders demand sub-minute finality.
Singapore
Cross-border remittance corridors and APAC treasury operations concentrate demand for fiat off-ramp capacity. The Monetary Authority of Singapore's payment institution framework provides regulatory clarity that attracts BVNK and other banking-as-a-service providers. The city-state's correspondent banking relationships enable settlement liquidity unavailable in neighboring jurisdictions.
Germany
MiCA-mandated cold storage audits and segregated reserve obligations reshape operational costs for hosted solution providers. Berlin and Frankfurt host consolidating gateway operators seeking to distribute compliance burdens across larger transaction bases. E-commerce merchants favor third-party hosted models to avoid direct licensing engagement.
United Kingdom
Service providers and digital agencies leverage recurring billing automation with volatility hedging through API-integrated gateways. Correspondent bank de-risking by traditional clearing institutions constricts fiat off-ramp capacity for crypto-facing entities. London's fintech cluster drives white-label checkout module demand from SaaS platforms.
Brazil
Cross-border remittance flows through Pix instant payment system integration address correspondent banking delays for LATAM corridor settlements. The Central Bank of Brazil's open banking framework enables hybrid crypto-fiat architectures. São Paulo anchors merchant adoption of multi-currency settlement rails for B2B trade.
Crypto Payment Gateway Market Vendor Landscape
Concentration sits with embedded finance platforms and banking-as-a-service operators that leverage existing merchant networks and regulatory licenses. The vendor base stratifies across three tiers: low-code hosted providers serving small merchants, API-first platforms targeting enterprise treasuries, and specialized operators for high-velocity verticals. Strategic moves center on jurisdictional license accumulation and Layer-2 network integration to compress settlement latency.
Among embedded finance platforms, Stripe exemplifies the archetype of leveraging existing merchant relationships to embed crypto rails without standalone infrastructure investment. BVNK occupies a position within the banking-as-a-service tier, anchoring multi-jurisdictional licensing strategies. CoinsPaid represents specialization in high-velocity settlement for iGaming and digital commerce verticals where sub-minute finality commands premium positioning.
| Leading Market Players |
|---|
| Stripe |
| BitPay |
| BVNK |
| CoinPayments |
| CoinGate |
| NOWPayments |
| Triple A |
| PayRam |
| CoinsPaid |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with banking-as-a-service providers lock in both fiat off-ramp access and fee visibility for gateway operators navigating MiCA reserve requirements and state-level money transmitter bonding. These contractual structures concentrate pricing power with licensed entities in Singapore and the United States while compressing margins for unlicensed hosted providers competing on transaction fees alone.
Pricing Analysis
The customization-premium spread between white-label API configurations and standard hosted checkout tiers spans three-to-five-fold in effective per-transaction cost. Subscription-based SaaS pricing dominates enterprise procurement, bundling KYC automation, travel rule screening, and regulatory reporting into flat-rate tiers. Price differentiation hinges on settlement velocity guarantees and jurisdictional licensing breadth, with Layer-2 finality commanding substantial premiums over main-chain settlement. Cost compression in the hosted provider tier is intensifying as MiCA compliance overhead forces consolidation. Small e-commerce merchants exhibit highest price sensitivity, while institutional treasuries prioritize latency and custody controls over per-basis-point fees.
Supply Chain Analysis
The United States, Singapore, and Germany anchor critical infrastructure across three distinct layers: node operations, banking partnerships, and regulatory licensing. Gateway operators draw from specialized engineering talent pools for blockchain forensics integration, cold storage custody solutions, and ISO 20022 messaging compliance. Single-source vulnerability concentrates in correspondent banking relationships, where traditional clearing institutions in the United Kingdom and Switzerland terminate crypto-facing accounts without warning. Distribution runs through embedded finance platforms that leverage existing merchant networks rather than direct acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gateway operators face sustained substitution pressure from stablecoin-native treasury infrastructure and central bank digital currency pilots that could disintermediate crypto-fiat conversion rails entirely. Incumbents must defend their positioning against these parallel settlement systems while regulatory fragmentation persists.
For Market Incumbents: Consolidate jurisdictional license portfolios to capture banking-as-a-service pricing premiums before MiCA implementation elevates barriers. Acquire specialized blockchain forensics capabilities to automate travel rule compliance and reduce engineering talent dependency. Vertical integration into Layer-2 node operations secures settlement velocity guarantees that differentiate against stablecoin-native competitors.
For New Entrants and Emerging Players: Anchor in Brazilian cross-border remittance corridors where Pix-crypto integration addresses correspondent banking delays with minimal incumbent saturation. Target service provider verticals in the United Kingdom seeking recurring billing automation with volatility hedging, a segment expanding faster than saturated e-commerce checkout. Pursue white-label distribution through vertical SaaS platforms to bypass direct merchant acquisition costs.
For Investors and Strategic Acquirers: Banking-as-a-service operators with multi-jurisdictional licensing breadth present the most defensible acquisition profile against regulatory fragmentation and stablecoin substitution. Long-term viability hinges on jurisdictional optionality rather than transaction volume scale. Monitor central bank digital currency pilot announcements as the critical inflection signal for crypto-fiat gateway displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Jurisdictional License Accumulation | MiCA and MAS frameworks in Europe and Singapore create captive regulatory moats against unlicensed competitors. |
| Layer-2 Network Integration | Polygon and Arbitrum finality compresses settlement latency for iGaming and e-commerce merchant retention. |
| Embedded Finance Distribution | Stripe's merchant network penetration demonstrates bypass of direct acquisition through platform partnerships. |
| Blockchain Forensics Automation | Real-time sanctions screening addresses FATF travel rule burdens without scarce engineering headcount expansion. |
| Stablecoin Reserve Structuring | MiCA-mandated segregation and attestation requirements elevate capital costs that favor consolidated operators. |
Methodological Framework
A standing panel of gateway operations executives, compliance officers at banking-as-a-service providers, merchant acquisition leads, and Layer-2 protocol engineers provided ongoing calibration across the study period. Primary interview findings were cross-validated against secondary sources including SEC filings for publicly traded fintech platforms, European Banking Authority MiCA implementation guidance, Monetary Authority of Singapore payment institution licensing registers, and FATF mutual evaluation reports. Bottom-up transaction volume estimates from merchant onboarding data were reconciled with top-down market sizing derived from banking partnership capacity disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including solution architecture tier, end-user vertical, transaction type, and integration complexity against settlement velocity requirements and jurisdictional regulatory cluster. CAGRs were derived from trend extrapolation of merchant onboarding trajectories, adjusted for licensing barrier effects and correspondent banking capacity constraints. Industry-specific inputs included Layer-2 network adoption curves and MiCA implementation timeline assumptions.
Material uncertainties — regulatory enforcement intensity variations, correspondent bank de-risking acceleration, and central bank digital currency launch timing — sit outside the modeled envelope. Forecasts reflect assumptions about sustained merchant demand for crypto-fiat conversion despite stablecoin-native alternatives. Recalibration cycles align with material shifts in MiCA secondary legislation, FATF travel rule technical guidance updates, and major central bank digital currency pilot announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
India Payments Market
Payments
Belgium Payments Market
Payments
Vietnam Payments Market
Payments
Cash Management System Market
Payments
Money Transfer Agencies Market
Payments
Mobile Point of Sale (POS) Market
Payments
New Zealand Payments Market
Payments
E-Commerce Payments Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Middle East and Africa Payment Gateway Market
Payments
Canada POS Terminal Market
Payments
United States Payments Market
Payments
Brazil POS Terminal Market
Payments
Nigeria Mobile Money Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
China Forex Cards Market