
 North America Health Tourism Market | 2026-2036
North America Health Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
North America Health Tourism Market Analytics
Concierge care coordination is restructuring how health tourism packages are assembled and sold in North America. Mayo Clinic anchors its health tourism draw through integrated diagnostic-to-treatment pathways that attract international patients seeking complex cardiac and oncology interventions. Cleveland Clinic competes through its dedicated international patient center, which controls appointment logistics, interpretation services, and post-discharge follow-up. Cedars-Sinai leverages its Los Angeles location to capture entertainment-industry executive wellness segments alongside traditional medical travelers.
North America health tourism encompasses the organized travel of patients across domestic and international borders to access medical, surgical, dental, or wellness services, typically involving pre-arranged appointments, dedicated patient liaisons, and bundled accommodation-clinical packages. Cosmetic surgery and dental procedures sustain the highest volume flows, while rehabilitation services and wellness treatments capture expanding margins as employers and insurers broaden covered benefit categories. Medical tourism facilitators and insurance companies represent the fastest-growing end-user channel, displacing individual direct-booking patterns as intermediaries consolidate itinerary control and negotiate facility rates.
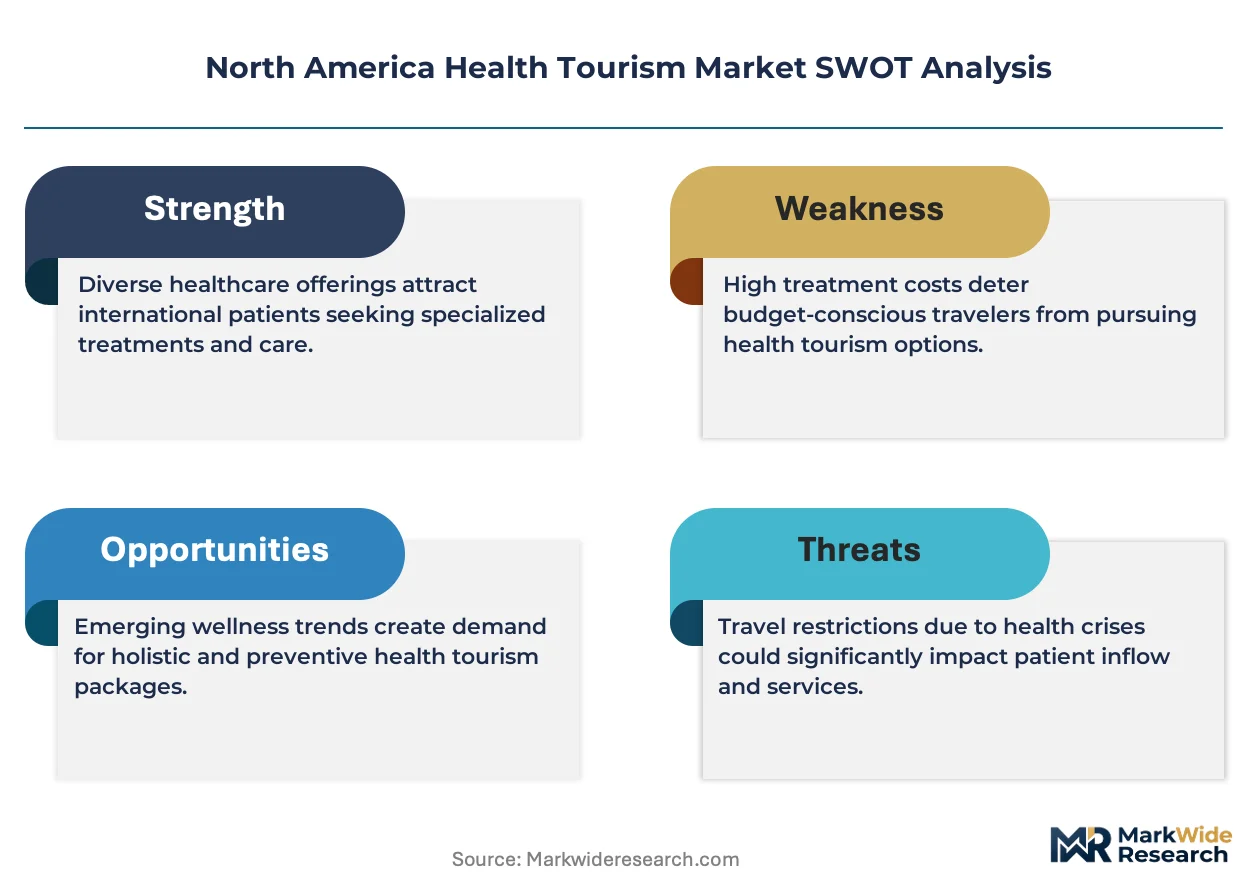
FDA oversight of device and pharmaceutical standards shapes which procedures clinics may legally market to inbound patients, while state-level medical boards in Florida, California, and Texas govern physician licensing requirements that determine cross-border practice eligibility. The Canadian province-by-province health authority structure creates parallel regulatory complexity for U.S. patients seeking cost arbitrage in elective procedures north of the border. Stakeholders must monitor evolving state telehealth reciprocity agreements and provincial wait-list policies, as these regulatory shifts will determine which destination corridors capture shifting patient flows.
Market Dynamics
Concierge care coordination is restructuring how health tourism packages are assembled and sold across the United States, Canada, and Mexico, with intermediaries consolidating itinerary control and negotiating facility rates directly with destination medical centers.
Growth Catalysts
- FDA medical device approval pathways:Streamlined premarket notification processes accelerate clinic certification timelines, enabling faster deployment of advanced surgical technologies at destination facilities in Florida and California.
- Corporate wellness programs:Large employers are expanding health tourism benefit offerings to include elective procedures and rehabilitation services, creating guaranteed patient volume flows for bundled accommodation-clinical packages.
- Telehealth licensing reforms:State-level reciprocity agreements in Texas and Arizona permit cross-border virtual consultations, reducing pre-travel friction for international patients scheduling complex interventions.
Market Restraints
- HIPAA compliance complexity:Cross-border data transfer requirements create legal friction for Canadian and Mexican clinics marketing services to U.S. patients, requiring costly infrastructure investments.
- Physician licensing fragmentation:State medical boards in California, Texas, and Florida maintain non-uniform telemedicine practice standards, limiting physician mobility across destination corridors.
- Canadian provincial wait-list policies:Variable elective surgery queues across Ontario, British Columbia, and Quebec create unpredictable capacity for U.S. patients seeking cost arbitrage in procedures north of the border.
Strategic Opportunities
- Mexico border-state medical corridor:Underserved elective surgery demand from uninsured U.S. patients concentrates near Tijuana, Monterrey, and Guadalajara, where facility operating costs run substantially below domestic benchmarks.
- IRA preventive care incentives:Medicare expansion of covered wellness screenings creates reimbursement pathways for domestic health tourism packages bundling diagnostic travel with follow-up interventions.
- Remote patient monitoring convergence:Wearable biosensors paired with telehealth platforms enable post-discharge surveillance of international patients, reducing readmission liability for destination hospitals.
Industry Challenges
- Medical interpreter certification gaps:Shortage of credentialed healthcare interpreters fluent in Mandarin, Arabic, and Portuguese limits clinic capacity to serve high-growth inbound patient segments from Asia-Pacific and Middle East markets.
- Accreditation timeline compression:Joint Commission International certification processes require 18-24 month facility preparation cycles, delaying market entry for new destination medical centers competing for health tourism volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Health Tourism Market |
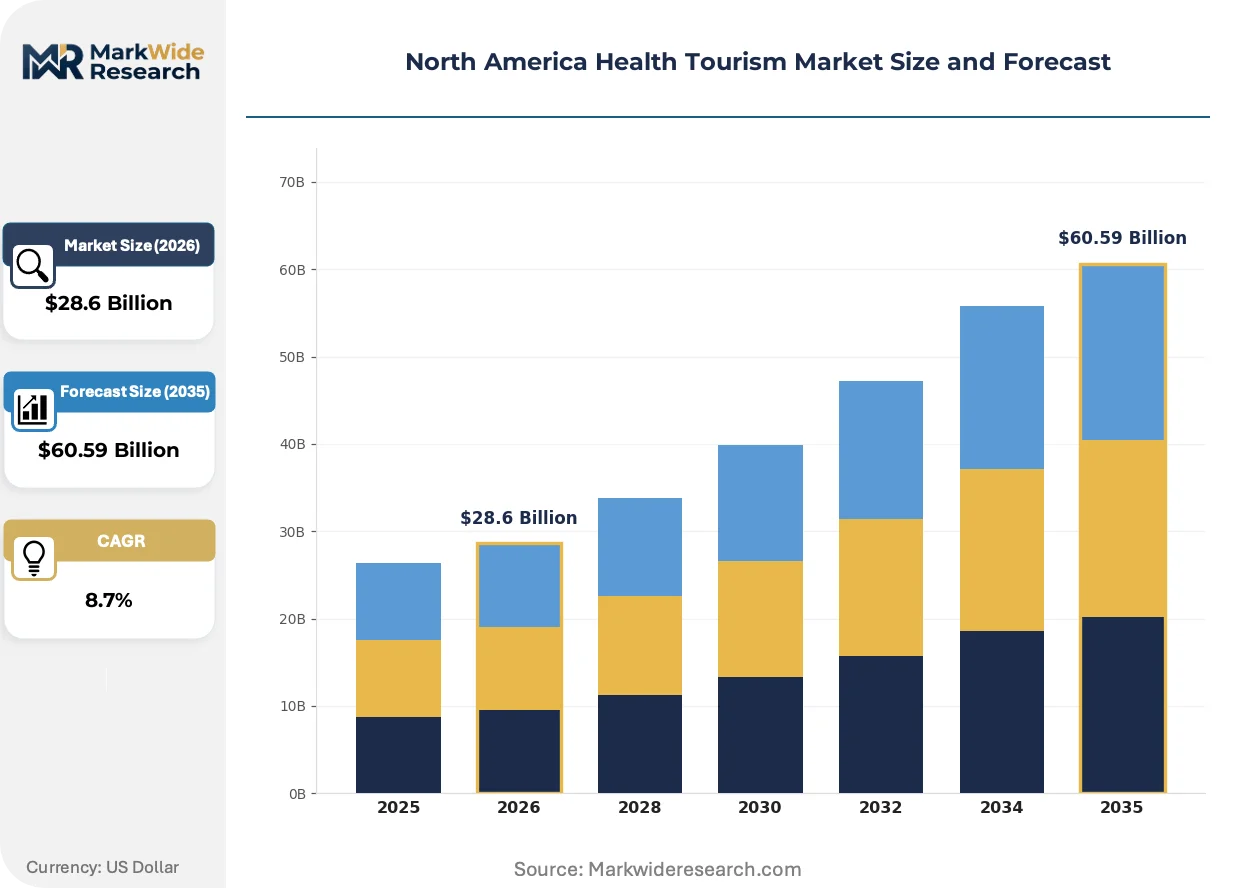
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Surgery, Dental Procedures, Rehabilitation Services, Wellness Treatments End User: Individuals, Corporations, Insurance Companies, Medical Tourism Facilitators Destination Type: Hospitals, Clinics, Wellness Retreats, Spas Motivation: Cost Savings, Quality of Care, Availability of Specialists, Integrated Packages |
| Companies Covered | The Johns Hopkins Hospital, Mayo Clinic, Cleveland Clinic, Cedars-Sinai, Massachusetts General Hospital, UCSF Health, NewYork-Presbyterian Hospital, Brigham and Women's Hospital, Ronald Reagan UCLA Medical Center, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Health Tourism Market Evolving Landscape
Digital health infrastructure is compressing the traditional health tourism value chain, enabling real-time pre-consultation, remote monitoring, and automated care coordination that displaces legacy facilitator intermediaries.
Artificial intelligence diagnostic triage is integrating into pre-arrival patient screening protocols at major destination medical centers. International patient coordinators at facilities in Houston and Los Angeles deploy machine learning algorithms to match symptoms with specialist availability, reducing appointment scheduling friction by automating preliminary case review. This technology is integrating historically separate intake, insurance pre-authorization, and travel logistics functions into unified digital workflows.
State telehealth reciprocity agreements are expanding physician practice eligibility across U.S. borders. Texas and Florida medical boards now recognize licenses from 15+ states, enabling specialist consultants to conduct virtual pre-operative consultations with international patients without physical presence requirements. Canadian provincial health authorities are responding with parallel telemedicine licensing frameworks to retain cross-border patient flows.
Employer-sponsored health tourism procurement is consolidating through specialized benefit administrators. Large self-insured corporations in manufacturing and energy sectors now contract directly with destination medical centers in Scottsdale and Miami, bypassing traditional insurance intermediaries. This channel shift is most visible in Texas and California, where tech and aerospace employers negotiate fixed-price bundled contracts for elective orthopedic and cardiac procedures.
North America Health Tourism Market Segmentation
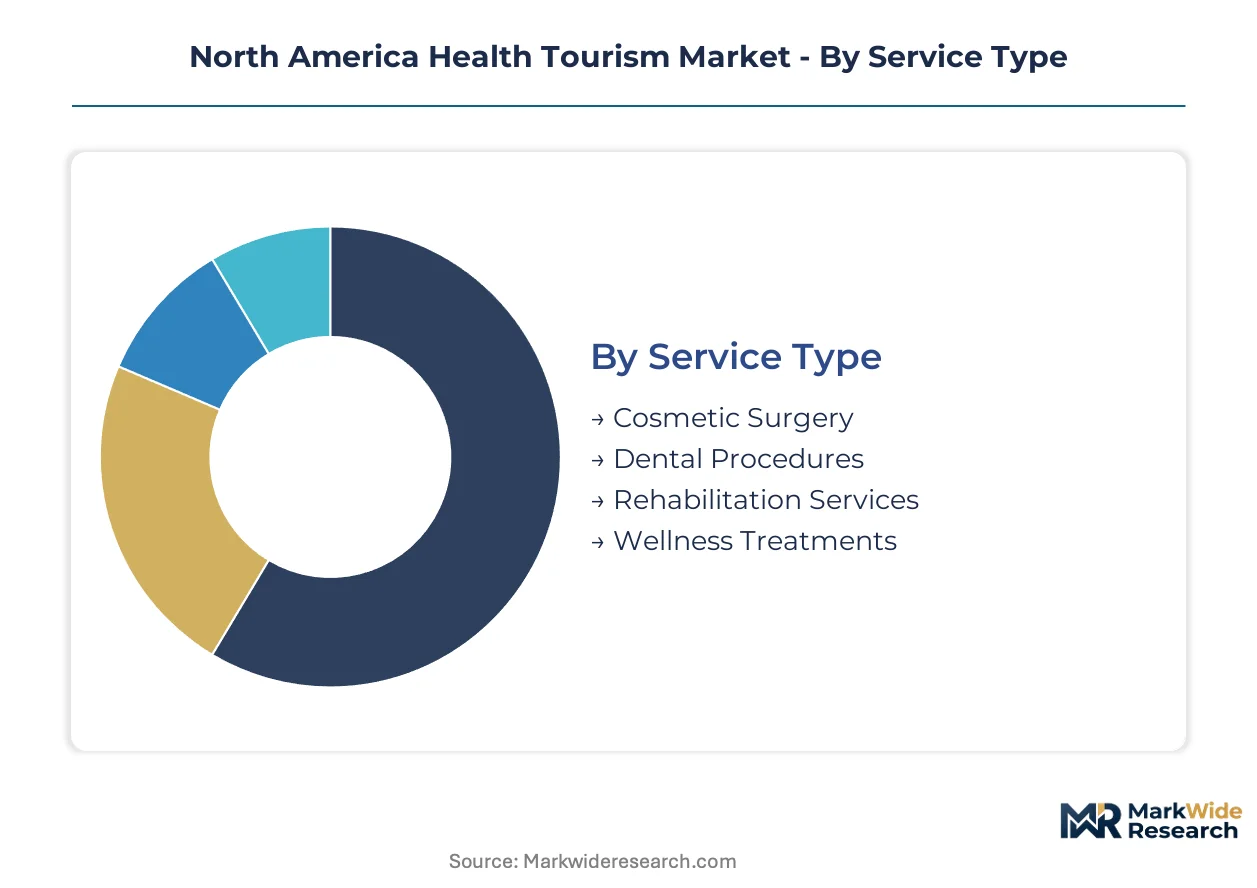
Segmentation in North American health tourism reveals how patient priorities, booking channels, and facility types create distinct commercial corridors. Each dimension shapes pricing power, regulatory exposure, and intermediary capture rates differently across the United States, Canada, and Mexico.
Service Type:
Cost sensitivity and procedure complexity separate patient flows across service categories, with elective interventions commanding premium coordination while wellness offerings scale through volume.
- Cosmetic Surgery:Aesthetic procedures ranging from minimally invasive injectables to complex reconstructive surgery require board-certified plastic surgeons and accredited surgical suites. Demand clusters in Miami and Los Angeles, where celebrity proximity and Latin American patient flows sustain premium pricing for facial rejuvenation and body contouring packages.
- Dental Procedures:Restorative and cosmetic dentistry including implants, veneers, and full-mouth reconstruction represents the highest-volume cross-border flow, particularly from uninsured U.S. patients to Tijuana and Cancun facilities where cost arbitrage runs 60-70% below domestic benchmarks.
- Rehabilitation Services:Post-operative physical therapy and addiction recovery programs.
- Wellness Treatments:Preventive diagnostics, stress management, and longevity protocols.
Cosmetic surgery leads volumes today; wellness treatments are gaining share fastest.
End User:
Procurement centralization determines itinerary control, with institutional buyers consolidating volume and squeezing facilitator margins while direct-to-patient channels fragment.
- Individuals:Self-funded patients researching and booking procedures independently through online platforms and direct clinic contact, bearing full price transparency risk and coordination burden.
- Corporations:Self-insured employers in Texas energy and California technology sectors negotiating direct contracts with Scottsdale and Miami medical centers for bundled orthopedic and cardiac procedures, bypassing traditional insurance intermediaries entirely.
- Insurance Companies:Payers expanding narrow networks to include Mexican and Canadian facilities for cost containment on elective procedures.
- Medical Tourism Facilitators:Intermediaries consolidating appointment logistics, interpretation, and accommodation booking for international patients.
Individuals still dominate transaction counts; corporations are climbing the fastest as benefit administrators consolidate procurement.
Destination Type:
Capital intensity and regulatory tier separate facility types, with hospital-based care capturing complex cases while lighter settings scale wellness volume.
- Hospitals:Full-service acute care institutions with emergency backup capacity and Joint Commission accreditation, anchoring cardiac and oncology tourism in Houston and Rochester through integrated diagnostic-to-treatment pathways.
- Clinics:Ambulatory surgical centers and specialty practices focusing on single-day procedures.
- Wellness Retreats:Residential preventive health programs combining diagnostics with lifestyle intervention.
- Spas:Non-medical relaxation and aesthetic service providers.
Hospitals anchor revenue per patient; clinics show the steepest expansion trajectory as same-day surgery protocols proliferate.
Motivation:
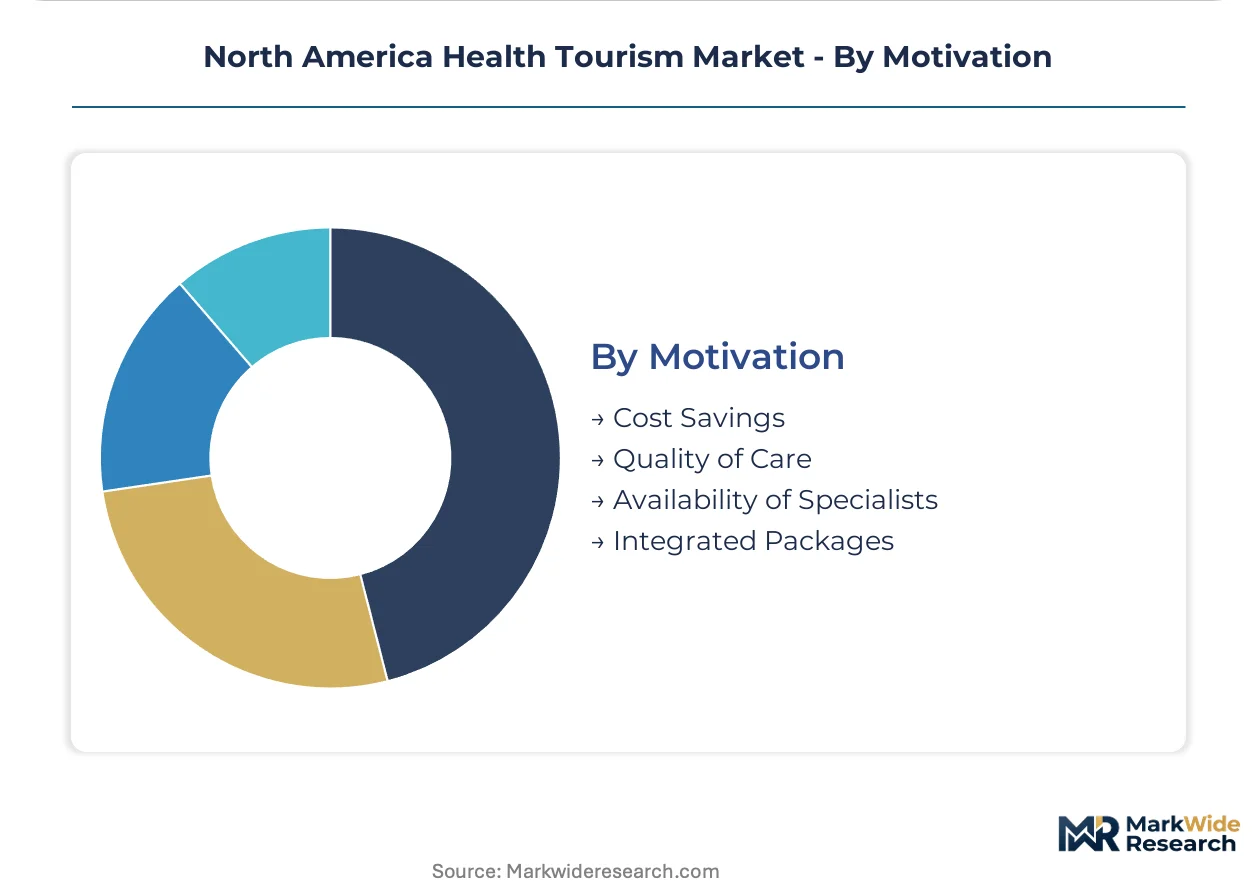
Patient decision hierarchies reveal market stratification, with price-driven flows concentrating at border corridors while quality-seekers cluster at academic medical centers.
- Cost Savings:Primary driver for uninsured and high-deductible patients arbitraging procedure prices across the U.S.-Mexico border, where all-inclusive dental and bariatric packages in Baja California and Nuevo León undercut domestic rates by half or more.
- Quality of Care:Academic medical center reputation and outcomes data driving international patients to Mayo Clinic and Cleveland Clinic for complex cardiac and oncology interventions unavailable in home countries.
- Availability of Specialists:Access to specific surgeons or novel treatment protocols not offered locally.
- Integrated Packages:Bundled accommodation-clinical offerings with concierge coordination.
Cost savings motivates the largest patient population; integrated packages are expanding most quickly as employers and facilitators standardize bundled offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health tourism infrastructure attracts international patients through FDA-cleared device pathways and state-level telehealth reciprocity, while Mexico leverages cost arbitrage at border clinics serving uninsured cross-border demand. Canada competes through provincial health authority networks offering elective procedure alternatives to U.S. wait-list pressures.
United States
Florida, California, and Texas concentrate destination medical facilities near major transport hubs, with corporate wellness programs expanding health tourism benefit offerings for elective procedures. FDA medical device approval pathways streamline clinic certification timelines, accelerating deployment of advanced surgical technologies. Mayo Clinic in Rochester and Cleveland Clinic anchor cardiac and oncology tourism through integrated diagnostic-to-treatment pathways.
Mexico
Tijuana, Monterrey, and Guadalajara capture underserved elective surgery demand from uninsured U.S. patients, where facility operating costs run substantially below domestic benchmarks. Dental and bariatric packages in Baja California and Nuevo León undercut U.S. rates by half or more. State-level medical boards in Texas and Arizona recognize telemedicine licenses, enabling virtual pre-operative consultations for cross-border patients.
Canada
Ontario, British Columbia, and Quebec attract U.S. patients seeking cost arbitrage in elective procedures, though variable provincial wait-list policies create unpredictable capacity. Health Canada and provincial health authorities govern physician licensing and facility accreditation. Toronto and Vancouver medical centers compete through shorter queues for orthopedic and cardiac interventions compared to U.S. metropolitan markets.
North America Health Tourism Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with academic medical centers commanding premium positioning for complex interventions while ambulatory surgical centers scale through volume-driven elective procedures. The vendor base concentrates around hospital systems with Joint Commission International accreditation and dedicated international patient centers. Three archetypes dominate: destination hospital networks, medical tourism facilitators, and employer-sponsored benefit administrators. Competitive moves center on M&A consolidation of facilitator networks and direct contracting partnerships with self-insured corporations.
Among U.S.-based academic medical centers, Mayo Clinic, Cleveland Clinic, and Cedars-Sinai occupy positions as anchor institutions for inbound health tourism. Mayo Clinic exemplifies the integrated care pathway archetype through its Rochester and Florida campuses. Cleveland Clinic represents the dedicated international patient center model with controlled appointment logistics and interpretation services. Cedars-Sinai sits within the entertainment-industry wellness segment, leveraging its Los Angeles location for executive health packages alongside traditional medical travelers.
| Leading Market Players |
|---|
| The Johns Hopkins Hospital |
| Mayo Clinic |
| Cleveland Clinic |
| Cedars-Sinai |
| Massachusetts General Hospital |
| UCSF Health |
| NewYork-Presbyterian Hospital |
| Brigham and Women's Hospital |
| Ronald Reagan UCLA Medical Center |
| Others |
Value Network & Pricing Analysis
Medical device component indices and pharmaceutical raw material benchmarks cascade through North American health tourism supply chains, compressing margins at Mexican border clinics while amplifying pricing power at U.S. academic medical centers with captive procurement networks. Cost differentials between FDA-regulated device tiers and Health Canada-equivalent standards create three-band pricing stratification across destination corridors.
Pricing Analysis
Capacity additions in Baja California and Nuevo León are reshaping price floors for dental and bariatric packages, forcing Arizona and Texas border competitors into cost-matching positions. Three-tier pricing structure across academic medical centers, ambulatory surgical facilities, and wellness retreats separates Mayo Clinic premium cardiac pathways from Tijuana clinic volume plays. Pricing pressure stems from employer-sponsored procurement consolidation negotiating fixed-price bundled contracts. Uninsured U.S. patients crossing into Mexico exhibit highest price sensitivity; corporate benefit administrators demonstrate lowest sensitivity due to outcomes-based contracting.
Supply Chain Analysis
Freight costs for temperature-sensitive biologics and specialized surgical equipment concentrate procurement leverage with hospital networks operating dedicated logistics arms. Mexico, the United States, and Canada anchor device and pharmaceutical sourcing, with Tijuana clinics drawing from maquiladora-adjacent distributors. Supply chains rest on FDA-cleared implants, Health Canada-approved pharmaceuticals, and Mexican COFEPRIS-registered generics. Single-source vulnerability runs through Joint Commission International accreditation bottlenecks. Distribution runs through medical tourism facilitators consolidating itinerary control, direct employer contracting channels, and clinic-direct patient acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American health tourism operates as a geographic-arbitrage play, with uninsured U.S. patients capturing 60-70% cost savings on elective procedures in Mexican border states against domestic benchmarks.
For Market Incumbents: Deploy concierge care coordination platforms to lock in corporate wellness contracts before benefit administrators consolidate procurement further. Mayo Clinic and Cleveland Clinic should deepen backward integration into remote patient monitoring technology to reduce readmission liability for international patients. Joint Commission International certification investments create moats against unaccredited Mexican clinic entrants. Threat substitution emerges from telehealth licensing reforms enabling virtual pre-operative consultations without physical presence requirements. For New Entrants and Emerging Players: IRA preventive care incentives in the United States open a window for domestic health tourism packages bundling diagnostic travel with Medicare-reimbursed wellness screenings. White-space targets cluster in employer-sponsored rehabilitation services and addiction recovery programs, segments where procurement centralization remains incomplete. The most penetrable geography sits in underserved U.S. manufacturing corridors where self-insured employers lack established destination medical center relationships. Go-to-market positioning should emphasize direct contracting with benefits administrators, bypassing traditional insurance intermediaries entirely. For Investors and Strategic Acquirers: Asymmetric upside sits with medical tourism facilitator networks consolidating appointment logistics, interpretation services, and accommodation booking functions. Long-term viability over the next decade hinges on regulatory arbitrage durability between FDA, Health Canada, and COFEPRIS approval pathways. Acquisition targets should screen for facilities with existing Joint Commission International accreditation or near-term certification timelines. The signal to watch is state telehealth reciprocity expansion compressing pre-travel friction for international patients scheduling complex interventions.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Commission International Certification | Accreditation unlocks employer-sponsored procurement channels and insurance network inclusion for destination facilities. |
| Corporate Wellness Direct Contracting | Bypassing traditional insurance intermediaries captures guaranteed patient volume flows from self-insured employers. |
| Telehealth Licensing Expansion | State reciprocity agreements reduce pre-travel friction for international patients scheduling complex cardiac interventions. |
| Remote Patient Monitoring Integration | Wearable biosensors paired with telehealth platforms reduce readmission liability for hospitals treating international patients. |
| Medical Interpreter Certification Programs | Credentialed Mandarin and Arabic interpreters unlock capacity to serve high-growth inbound patient segments from Asia-Pacific markets. |
Research Methodology
Bottom-up corporate wellness procurement modeling reconciled against top-down destination medical center capacity tracking forms the analytical core of this study. Primary interviews with international patient coordinators, benefits administrators at self-insured employers, GPO contracts managers, and biomedical engineers at accredited facilities combined with secondary validation against FDA 510(k) filings, Health Canada device licensing databases, hospital procurement records, and state medical board telehealth reciprocity agreements. Triangulation across these sources calibrated patient volume estimates and pricing benchmarks.
Input-output matrices mapped procedure-specific demand drivers against facility capacity constraints across the projection horizon. Segmentation dimensions modeled include service type complexity tiers, end-user procurement centralization levels, destination facility accreditation status, and patient motivation hierarchies. CAGRs derived from regression analysis of historical patient flow data against regulatory event timelines and employer benefit expansion patterns. Forecast inputs incorporated Joint Commission International certification pipeline visibility and state-level telehealth licensing reform trajectories.
Revisions become necessary when Canadian provincial wait-list policies shift unpredictably or when FDA medical device approval pathways experience substantive procedural changes. Forecasts reflect assumptions about regulatory arbitrage durability and employer benefit expansion continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
China Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market