
 Mate Tea Market | 2026-2036
Mate Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Mate Tea Market Insights
Cold-brew extraction and nitrogen-infusion technology is fragmenting traditional mate preparation methods across commercial channels. Guayakí leverages certified organic supply chains to anchor premium positioning in North American natural food retail. Taragüi sustains dominant cultivation scale across Argentina's Misiones province, while Las Marías competes through integrated processing infrastructure that controls quality from harvest to packaging.
Mate tea consists of dried leaves and stems of Ilex paraguariensis, typically containing 80-150 mg caffeine per liter and rich in polyphenols such as chlorogenic acid, consumed primarily as a stimulant beverage with cultural roots in the Southern Cone. Organic and ready-to-drink formulations now lead growth trajectories as health food stores and specialty retailers expand refrigerated grab-and-go offerings, while loose leaf occupies mature demand concentrated in traditional South American households. Powder and extract forms capture emerging functional ingredient applications as cafes and restaurants experiment with mate-infused beverages and culinary applications.
Argentina's SENASA enforces phytosanitary certification for yerba mate exports, while Brazil's National Health Surveillance Agency (ANVISA) regulates ready-to-drink mate labeling and health claims; both frameworks shape product formulation and market access timelines for international suppliers. The EU's novel food regulations and F-Gas standards for cold-chain equipment add compliance layers for European-bound shipments. Stakeholders must monitor evolving caffeine disclosure requirements and organic certification reciprocity agreements as distribution channels diversify beyond traditional ethnic markets into mainstream retail.
Market Dynamics
Cold-brew extraction and nitrogen-infusion systems are fragmenting traditional mate preparation methods, compressing the gap between artisanal loose-leaf rituals and industrial-scale ready-to-drink production. This technological bifurcation is redrawing competitive boundaries between heritage processors and beverage multinationals.
Growth Catalysts
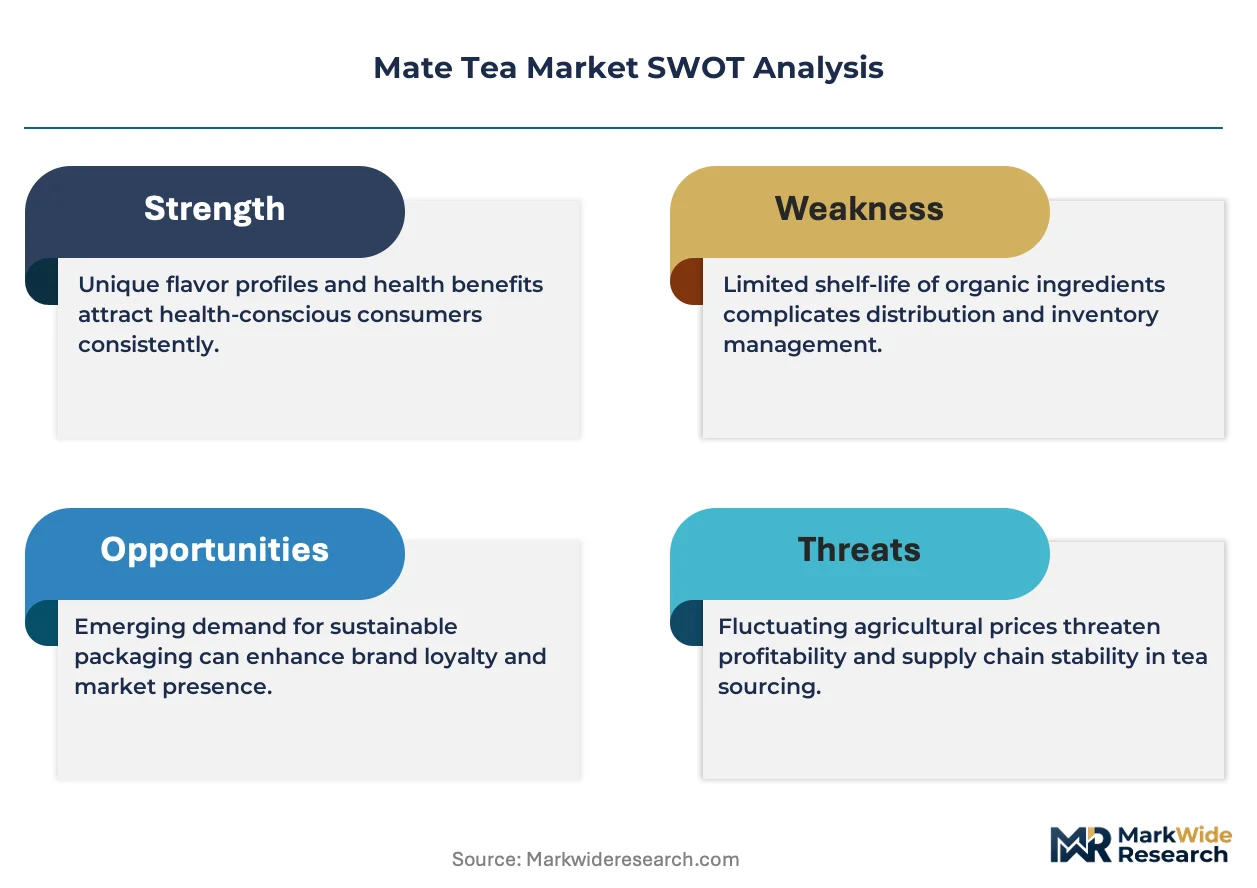
- Caffeine-conscious substitution:Health-conscious consumers in North American specialty beverage channels are pivoting from coffee to yerba mate for sustained energy without jitters, expanding refrigerated grab-and-go shelf space.
- EU organic certification reciprocity:Streamlined mutual recognition agreements between Argentina's SENASA and EU organic frameworks are accelerating export clearance timelines for certified producers.
- Functional ingredient extraction:Chlorogenic acid and polyphenol concentrates from Ilex paraguariensis are penetrating nutraceutical formulations, creating upstream demand for standardized raw material supply.
Market Restraints
- Input cost volatility:Argentine peso devaluation and climate-driven harvest variability in Misiones province are destabilizing raw leaf pricing for international buyers.
- Supply concentration risk:Overreliance on Argentina's Misiones corridor for premium organic leaf creates single-point vulnerability to regional drought or phytosanitary shutdowns.
- Regulatory friction:Brazil's ANVISA health claim restrictions on ready-to-drink mate labeling limit functional positioning in Latin America's largest addressable market.
Strategic Opportunities
- Underpenetrated German market:Europe's largest economy shows minimal per-capita yerba mate consumption despite established South American diaspora networks in Berlin and Hamburg.
- Cafe channel innovation:Nitrogen-infused draft mate systems are displacing kombucha taps in US coastal urban coffeehouse chains, creating equipment and training revenue streams.
- Clean-label convergence:Cold-brew technology paired with biodegradable packaging aligns with EU Green Deal circular economy mandates, qualifying products for preferential retail placement.
Industry Challenges
- Phytosanitary certification timelines:SENASA export documentation delays frequently miss ocean freight windows, forcing air freight cost absorption or inventory stockouts.
- Flavor standardization gaps:Absence of ISO-recognized sensory grading protocols creates quality disputes between Argentine harvest batches and North American bottling contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mate Tea Market |
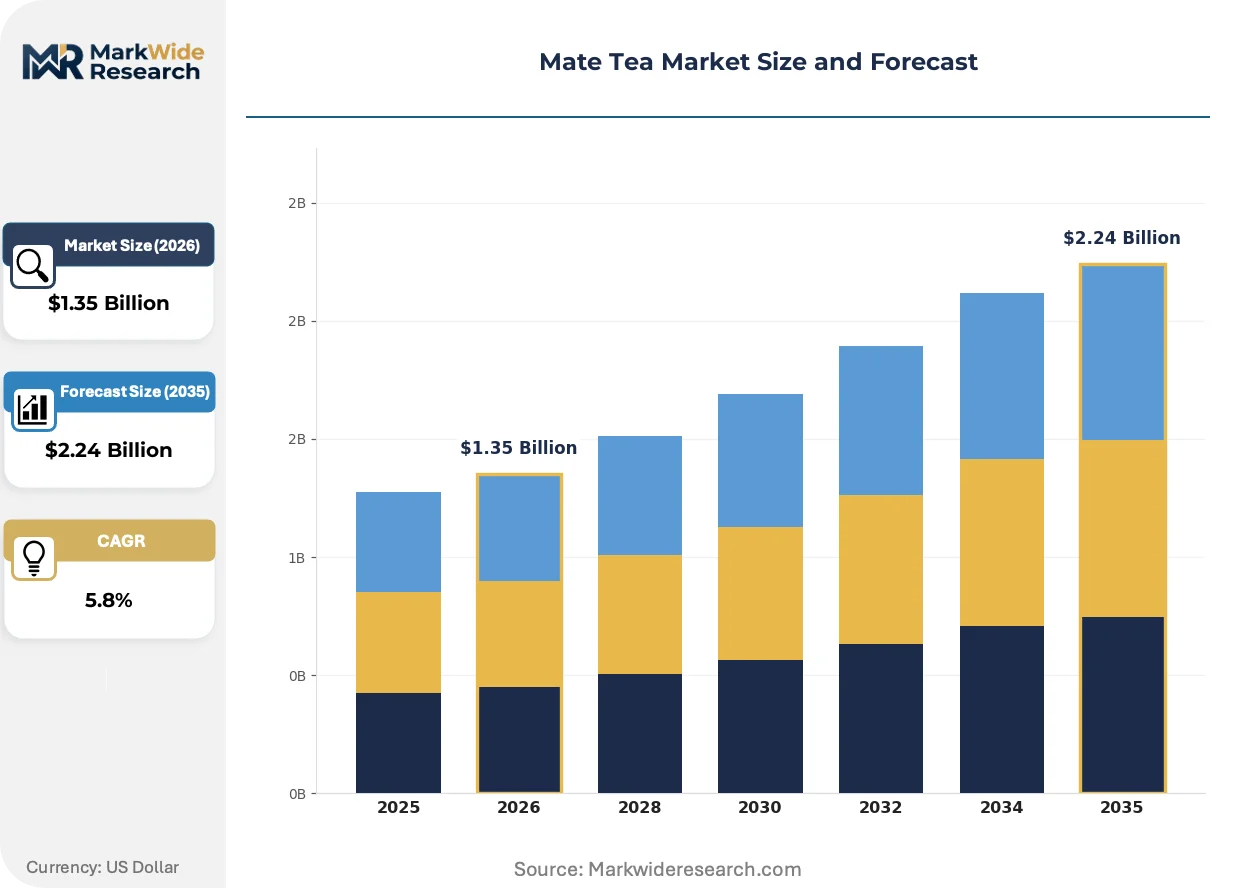
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-organic, Flavored, Loose Leaf Form: Tea Bags, Powder, Ready-to-Drink, Extract Distribution Channel: Online, Supermarkets, Health Food Stores, Specialty Stores End User: Individuals, Cafes, Restaurants, Health Enthusiasts |
| Companies Covered | Guayakí, Taragüi, Rosamonte, Amanda, Cruz de Malta, Las Marías, Canarias, Pajarito, Selecta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mate Tea Market Trends and Innovations
Processing technology and consumption rituals are diverging sharply. Traditional gourd-and-bombilla preparation persists in Southern Cone households while extraction innovation unlocks entirely new usage occasions and buyer segments in import markets.
Cold-brew extraction systems operating at ambient temperature for 12-24 hours are collapsing the quality trade-off between convenience and polyphenol retention. Premium US natural food retailers are adopting these systems for in-house beverage programs, displacing heat-pasteurized concentrates. The structural consequence is a compression of the value chain: roasters and cafes now source directly from Argentine cooperatives, bypassing legacy importers and blenders.
Argentina's SENASA is tightening phytosanitary certification protocols for organic yerba mate exports, extending documentation review periods and mandating blockchain traceability for EU-bound shipments. Industrial consequence: smaller cooperatives face compliance cost barriers while integrated processors with in-house laboratory capacity capture disproportionate export share. German and Dutch distributors are responding by consolidating supplier relationships around SENASA-preapproved facilities.
Switching cycles between beverage categories are compressing as functional claims drive trial behavior. Health food store buyers in California and New York are rotating shelf sets quarterly rather than annually, replacing slower-moving SKUs with novel formats like sparkling mate and mate-protein hybrids. This velocity is most visible in Los Angeles and Brooklyn, where direct-to-consumer subscription models are capturing repeat purchase data that informs rapid formulation pivots.
Mate Tea Market Segmentation
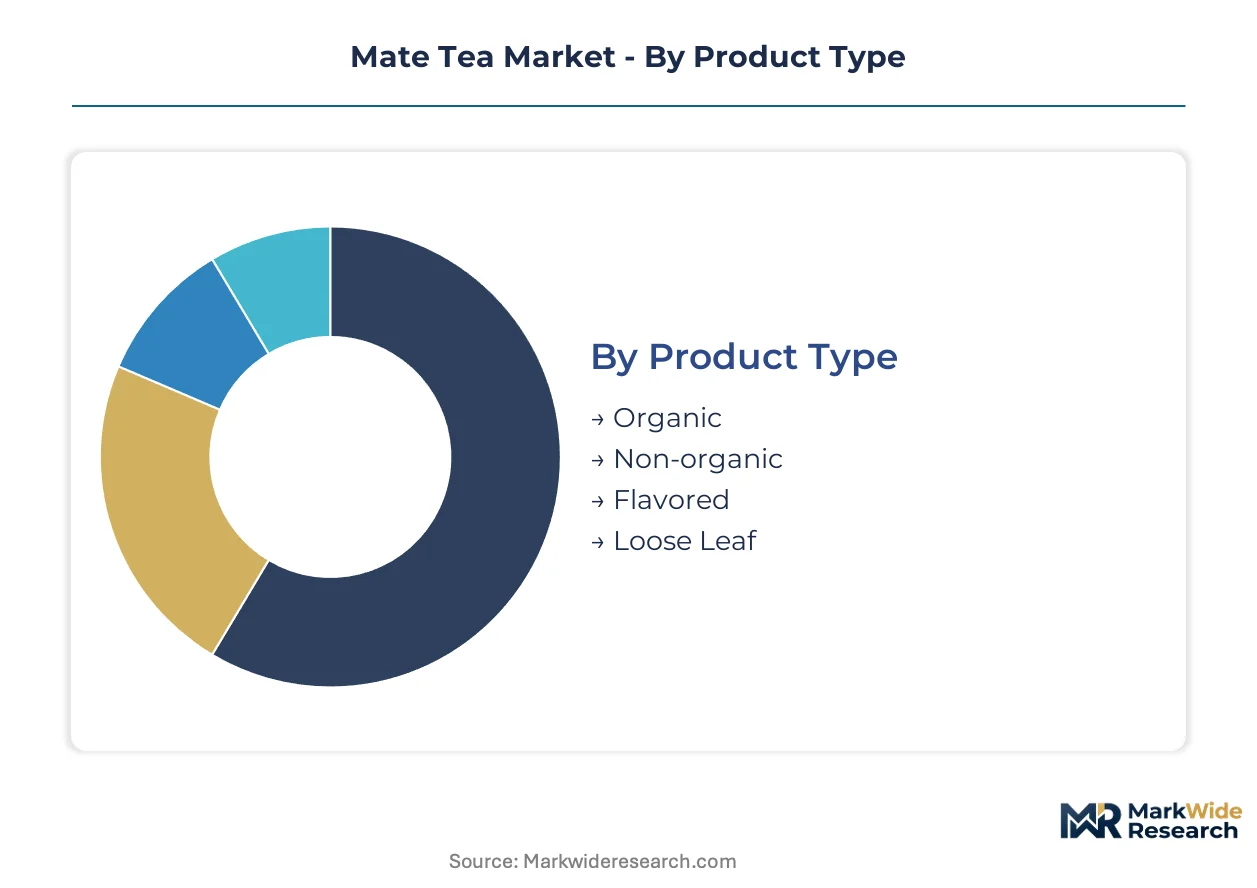
Mate tea segmentation reveals divergent margin structures across preparation formats and retail channels. Cold-brew and nitrogen-infusion systems demand minimal post-purchase service, while traditional loose-leaf formats require education-intensive support at point of sale.
Product Type:
After-sales intensity varies sharply by certification tier, with organic SKUs requiring traceability documentation and recall protocols that inflate operational overhead.
- Organic:Certified leaf from Argentina's Misiones province commands premium shelf placement in California and New York natural food retailers. SENASA blockchain traceability mandates for EU-bound shipments concentrate procurement among integrated processors with in-house laboratory capacity.
- Non-organic:Conventional cultivation dominates Brazilian domestic chimarrão consumption. Price-sensitive household purchasing in Porto Alegre and Curitiba absorbs volume despite peso-driven input volatility affecting Argentine supply contracts.
- Flavored:Citrus and mint infusions target trial behavior in US coastal urban markets.
- Loose Leaf:Traditional gourd preparation persists across generational Southern Cone households with minimal packaging overhead.
Non-organic holds the largest share; momentum sits with organic certification tiers.
Form:
Production asset intensity scales inversely with consumer preparation time, concentrating capital deployment toward extraction and packaging automation.
- Ready-to-Drink:Nitrogen-infused draft systems displace kombucha taps in Brooklyn and Los Angeles coffeehouse chains. ANVISA health claim restrictions in Brazil constrain functional positioning despite the category's steepest expansion trajectory in North American refrigerated cases.
- Tea Bags:Single-serve sachets penetrate German and Dutch retail through diaspora networks in Berlin and Hamburg. Convenience positioning captures office-channel consumption previously served by coffee vending infrastructure.
- Powder:Instant dissolution formats target protein-mate hybrid applications in sports nutrition.
- Extract:Chlorogenic acid concentrates supply nutraceutical formulators seeking standardized polyphenol content.
Ready-to-Drink commands attention; Tea Bags show durable penetration in European import markets.
Distribution Channel:
Channel selection determines compliance burden, with health food stores demanding organic certification reciprocity that supermarkets rarely enforce.
- Health Food Stores:Refrigerated grab-and-go placement in Whole Foods and Sprouts networks rotates quarterly as California buyers chase novel formats. Direct-to-consumer subscription data from Los Angeles informs rapid formulation pivots with minimal distributor intermediation.
- Online:Argentine cooperatives bypass legacy importers through Shopify-enabled direct sales to US consumers. SENASA documentation delays force air freight cost absorption or inventory stockouts during peak demand windows.
- Supermarkets:Mass retail placement in São Paulo and Buenos Aires depends on price-volume negotiations with consolidated beverage distributors.
- Specialty Stores:Ethnic grocers in Miami and Queens serve traditional preparation equipment alongside leaf sales.
Health Food Stores anchor premium positioning; Online is climbing the fastest as traceability technology matures.
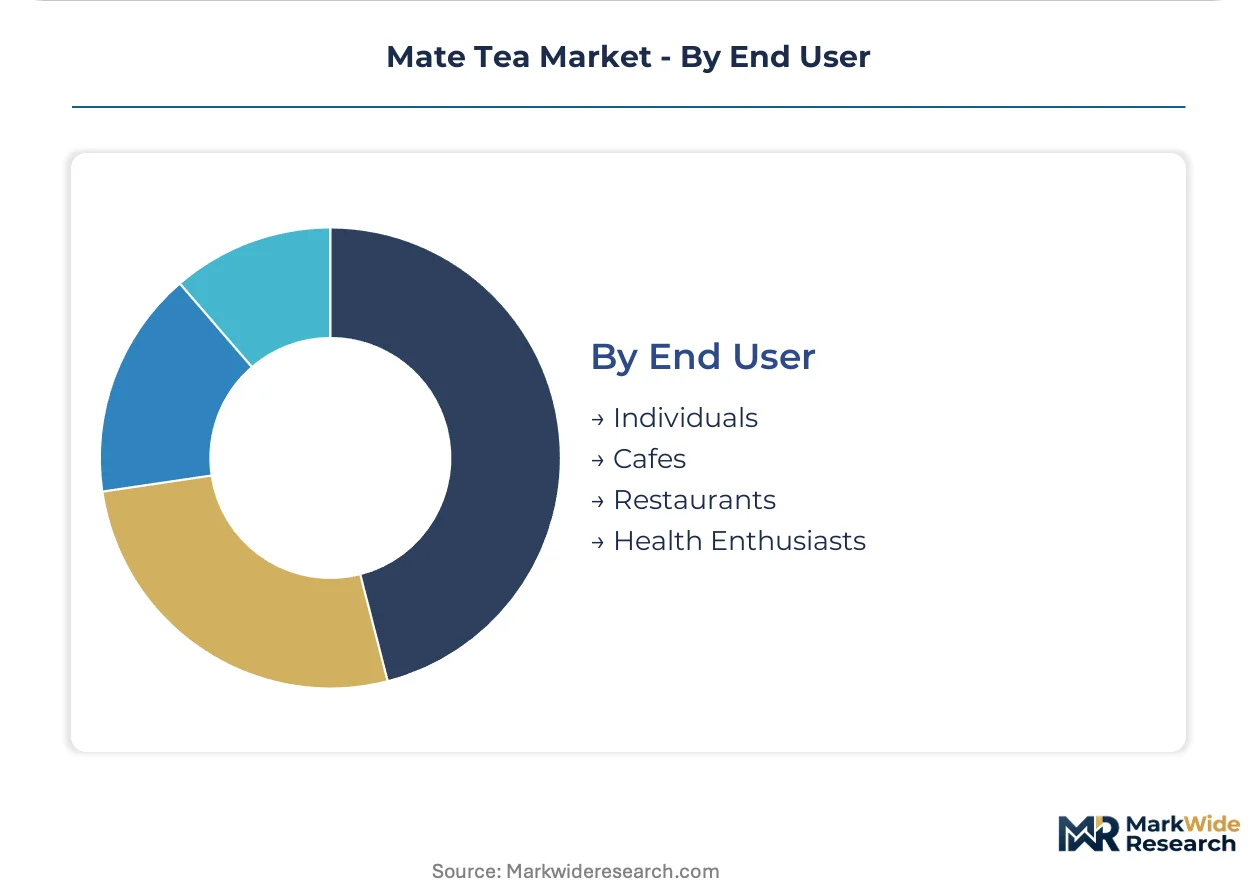
End User:
User sophistication dictates formulation complexity, with cafes demanding batch consistency that individual consumers rarely verify.
- Cafes:Nitrogen draft installation and barista training create equipment revenue streams for system suppliers. Brooklyn roasters source directly from Misiones cooperatives, collapsing the traditional importer-blender value chain through cold-brew extraction adoption.
- Health Enthusiasts:Caffeine-conscious substitution from coffee drives trial in CrossFit and yoga studio adjacent retail. Polyphenol content verification commands price premiums in supplement-adjacent consumption occasions.
- Individuals:Household preparation spans traditional gourd ritual to tea bag convenience across income tiers.
- Restaurants:Mate-infused culinary applications remain experimental, constrained by flavor standardization gaps between Argentine harvest batches.
Cafes concentrate equipment and service revenue; Health Enthusiasts show fastest adoption velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina ships dried leaf to North American natural food retailers and European distributors, with Brazil absorbing domestic volume and re-exporting processed formats. Trade flows concentrate through Buenos Aires and Porto Alegres ports, with phytosanitary clearance timelines shaping inventory cycles for refrigerated supply chains.
United States
California and New York health food retailers rotate refrigerated grab-and-go SKU sets quarterly, chasing nitrogen-infused and sparkling formats. FDA caffeine disclosure requirements for ready-to-drink beverages shape label architecture and functional claim boundaries. Los Angeles roasters source directly from Misiones cooperatives through cold-brew extraction adoption, collapsing traditional importer-blender margins.
Brazil
Traditional chimarrão consumption in Rio Grande do Sul and Paraná persists across generational households, while São Paulo metro demand shifts toward canned and bottled formats. ANVISA health claim restrictions on ready-to-drink labeling constrain functional positioning despite steepest category expansion in Latin America. Curitiba processors blend Argentine leaf with domestic supply to balance cost and quality tiers.
Germany
Berlin and Hamburg diaspora networks sustain loose-leaf demand through ethnic grocers, though per-capita consumption remains minimal against European peers. EU organic certification reciprocity with Argentina's SENASA accelerates import clearance for certified producers. Frankfurt distributors consolidate procurement around SENASA-preapproved facilities to minimize blockchain traceability compliance costs.
Argentina
Misiones province cultivation anchors global organic leaf supply, with harvest variability and peso devaluation destabilizing export pricing. SENASA phytosanitary protocols mandate laboratory documentation and blockchain traceability for EU-bound shipments, favoring integrated processors over smaller cooperatives. Posadas processing clusters capture disproportionate export share through in-house certification capacity.
Canada
Toronto and Vancouver specialty beverage channels experiment with nitrogen draft installations displacing kombucha taps. Health Canada natural health product regulations govern polyphenol concentrate imports for nutraceutical applications. Montreal distributors bridge Argentine supply with US cross-border demand through preferential tariff treatment under trade agreements.
Mate Tea Market Competitive Landscape
On the supply side, the industry is bifurcated between heritage South American processors with captive cultivation and North American beverage multinationals deploying extraction technology. Argentine cooperatives and integrated processors control upstream leaf quality, while US-based brands command retail shelf space and direct-to-consumer channels. Two strategic archetypes dominate: vertically integrated plantation-to-package operators in Misiones, and technology-enabled brand builders leveraging cold-brew and nitrogen systems for format innovation. Competitive moves concentrate on supplier consolidation to secure organic certification capacity, and equipment partnerships to deploy draft systems in cafe channels.
Among heritage Argentine processors, Taragüi and Las Marías exemplify distinct operational models—one scaling cultivation dominance across Misiones province, the other controlling integrated processing infrastructure from harvest through packaging. Guayakí occupies a position as the archetypal North American brand builder, translating certified organic supply chains into premium natural food retail placement. These three entities represent the structural tension between origin-controlled supply and destination-market brand equity.
| Leading Market Players |
|---|
| Guayakí |
| Taragüi |
| Rosamonte |
| Amanda |
| Cruz de Malta |
| Las Marías |
| Canarias |
| Pajarito |
| Selecta |
| Others |
Pricing and Supply Chain Analysis
Argentine peso devaluation and climate-driven harvest variability in Misiones province determine both the spread between organic premium and conventional economy tiers and the geographic configuration of procurement relationships. Buyers respond to input cost instability by consolidating supplier relationships around SENASA-preapproved integrated processors, compressing margins for smaller cooperatives unable to absorb certification overhead.
Pricing Analysis
Cold-brew extraction technology commands substantial premiums over traditional heat-pasteurized concentrates, while nitrogen-infusion systems occupy an emerging next-generation tier. Three-tier pricing structure across premium organic certification, standard conventional leaf, and economy non-certified grades reflects SENASA compliance costs and blockchain traceability investments. Pricing pressure stems from Argentine currency volatility forcing dollar-denominated contract renegotiations. Brazilian domestic buyers exhibit highest price sensitivity, while North American natural food retailers absorb organic premiums with minimal volume pushback.
Supply Chain Analysis
Integrated processors in Argentina's Misiones province and Curitiba blending facilities in Brazil hold dominant contract-manufacturing capacity for international brands. Geographic supply concentration centers on Argentina for premium organic leaf and Brazil for volume chimarrão production, with secondary sourcing from Paraguayan cooperatives. Raw material dependencies include Ilex paraguariensis harvest cycles, nitrogen gas supply for draft systems, and biodegradable packaging substrates. Single-source vulnerability to regional drought in Misiones creates inventory risk for refrigerated supply chains. Distribution runs through Buenos Aires and Porto Alegres ports to North American and European destination markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: SENASA certification capacity and EU organic reciprocity agreements create switching costs that lock in supplier-buyer relationships across multi-year contract horizons.
For Market Incumbents: Entrench market position through backward integration into captive Misiones cultivation acreage and in-house laboratory certification capacity that smaller competitors cannot replicate. Consolidate procurement relationships with German and Dutch distributors seeking SENASA-preapproved facilities to minimize blockchain compliance costs. Cold-brew extraction technology patents and nitrogen draft system equipment partnerships provide additional barrier construction against beverage multinational entrants. For New Entrants and Emerging Players: German per-capita consumption gaps relative to European diaspora penetration rates in Berlin and Hamburg offer the most penetrable white-space target for loose-leaf and tea bag formats. Nitrogen draft system deployment in underpenetrated Canadian specialty coffee channels—specifically Toronto and Vancouver—provides equipment and training revenue streams with lower competitive density than saturated US coastal markets. Direct-to-consumer subscription models leveraging Shopify infrastructure bypass legacy importer margins while capturing repeat purchase data for rapid formulation pivots. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors integrated processors with in-house certification capacity over pure-play brand builders dependent on third-party supply. Long-term viability over the next decade rests on securing SENASA-preapproved organic leaf supply as climate variability intensifies harvest concentration among laboratory-equipped facilities. Acquisition targets should demonstrate established EU organic certification reciprocity and existing blockchain traceability infrastructure. The signal to watch is SENASA documentation timeline compression or extension, which directly impacts inventory carrying costs and air freight absorption requirements.| Strategic Initiative | Industry Significance |
|---|---|
| SENASA Certification Investment | In-house laboratory capacity captures disproportionate export share as blockchain mandates tighten. |
| Cold-Brew Extraction Scale-Up | Direct sourcing from Misiones cooperatives collapses traditional importer-blender value chain margins. |
| Nitrogen Draft System Partnership | Equipment and training revenue streams displace kombucha taps in Brooklyn and Los Angeles coffeehouses. |
| EU Organic Reciprocity Expansion | Streamlined SENASA mutual recognition accelerates Frankfurt and Rotterdam distributor consolidation. |
| Direct-to-Consumer Channel Launch | Shopify-enabled subscription models capture Los Angeles repeat purchase data for formulation pivots. |
Research Methodology
Initial hypotheses were tested against primary input from yerba mate processors, SENASA regulatory affairs officers, natural food retail category buyers, and cold-brew equipment manufacturers and refined through secondary validation against customs export records, SENASA phytosanitary certification databases, EU organic import clearance statistics, and refrigerated beverage distributor financial disclosures. Bottom-up volume modeling from cultivation acreage and harvest yield data was triangulated against top-down category spending estimates from health food retail audit services.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning organic certification tier, preparation format, distribution channel, and end-user sophistication. CAGRs were derived from trend extrapolation of historical trade flows adjusted for technology adoption curves and regulatory timeline shifts. Forecast inputs incorporated SENASA documentation processing speeds, nitrogen draft system installation rates in US coffeehouse chains, and EU Green Deal circular economy packaging mandate compliance costs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by beverage multinationals acquiring Argentine integrated processors or deploying proprietary extraction technology would shift outcomes substantially. Quarterly review of SENASA certification backlog indicators, Misiones province rainfall patterns, and nitrogen draft system placement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Plant Based New Tea Drink Market
Tea
White Tea Market
Tea
Tea Essence Market
Tea
Global Tea Market
Tea
Spray-Dried Tea Products Market
Tea
Europe Green Tea Market
Tea
Bottled Tea Market
Tea
Asia-Pacific Organic Tea Market
Tea
Smart Tea Set Market
Tea
Edible Tea Market
Tea
Slimming Tea Market
Tea
Africa Tea Market
Tea
Camellia Sinensis Leaf Extract Market
Tea
Tea Polyphenols Market
Tea
Oolong Tea Market
Tea
US RTD Organic Tea Market