
 Orthodontic Consumables Market | 2026-2036
Orthodontic Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Orthodontic Consumables Market Intelligence
Trained orthodontist availability is collapsing across secondary cities in developing markets, forcing dental clinics to rely more heavily on prefabricated consumables and chairside-adjustable systems. Align Technology leverages its digital scanning ecosystem to reduce specialist dependency. Dentsply Sirona anchors its position through integrated CAD/CAM workflows that compress treatment planning cycles. Institut Straumann AG competes via premium titanium archwire portfolios and direct-to-clinic logistics networks.
Orthodontic consumables comprise brackets, archwires, bands, elastics, and aligner materials engineered to precise torque and angulation specifications, typically manufactured through metal injection molding, ceramic sintering, or thermoplastic vacuum forming. These products deliver controlled biomechanical force to reposition dentition within periodontal ligament tolerance limits. Metal brackets still dominate volume shipments due to cost efficiency and clinical durability, while ceramic and composite alternatives command premium positioning in aesthetic-driven adult segments. Elastic chains and nickel-titanium superelastic wires represent the fastest-growing material categories as practices shift toward shorter adjustment intervals and patient-comfort protocols.
The US FDA regulates orthodontic devices as Class II medical products requiring 510(k) premarket notification, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance through notified bodies. India's CDSCO has tightened biocompatibility testing protocols under revised medical device rules, extending compliance timelines for imported consumables. China's NMPA aligner approvals now require domestic clinical trial data, reshaping market entry strategies. Stakeholders must monitor regulatory divergence across these jurisdictions to optimize manufacturing footprints and avoid stranded inventory in transit.
Market Dynamics
The orthodontic consumables sector is undergoing a fundamental reconfiguration as digital intraoral scanning and AI-powered treatment planning compress the traditional specialist-dependent care model, forcing manufacturers to engineer chairside-adjustable systems that general dental practitioners can deploy without extended orthodontic training.
Growth Catalysts
- Expanded reimbursement frameworks:India's CDSCO and Brazil's national health regulators have broadened orthodontic coverage under public and private insurance schemes, unlocking patient access across tier-2 and tier-3 cities where specialist density remains low.
- Nickel-titanium superelastic alloys:These materials enable longer activation intervals and reduced patient discomfort, accelerating adoption among adult aesthetic segments seeking shorter clinical visits.
- Clear aligner thermoplastic polymers:Vacuum-formed multilayer materials now deliver controlled force systems comparable to fixed appliances, capturing demand from professionals prioritizing removability and oral hygiene compliance.
Market Restraints
- Palladium and rhodium price volatility:Precious metal inputs for certain archwire coatings expose manufacturers to commodity-driven margin compression without pass-through pricing power in contracted institutional sales.
- China NMPA clinical trial mandates:Domestic trial requirements for aligner approvals extend market entry timelines by 18-24 months, stranding R&D investment and delaying revenue recognition for foreign portfolios.
- 3D-printed bracket substitutes:Direct metal laser sintering enables in-office fabrication of custom brackets, threatening volume demand for standardized injection-molded components from centralized factories.
Strategic Opportunities
- Secondary city penetration in India:Trained orthodontist scarcity across Lucknow, Indore, and Coimbatore creates demand for prefabricated self-ligating systems that general practitioners can manage with minimal specialist oversight.
- EU MDR clinical evidence pathways:Manufacturers with robust post-market surveillance infrastructure can leverage regulatory compliance as a competitive moat against undercapitalized rivals facing notified body backlogs.
- Teleorthodontic monitoring convergence:Integration of remote progress tracking with consumable refills enables subscription-based revenue models that decouple growth from chairside appointment frequency.
Industry Challenges
- Biocompatibility certification complexity:India's revised CDSCO testing protocols for nickel ion release and cytotoxicity require redundant laboratory validation, extending product launch cycles for imported archwires and brackets.
- Legacy practice management integration:Digital treatment planning platforms must interface with entrenched patient record systems in established dental clinics, creating implementation friction that slows technology adoption curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthodontic Consumables Market |
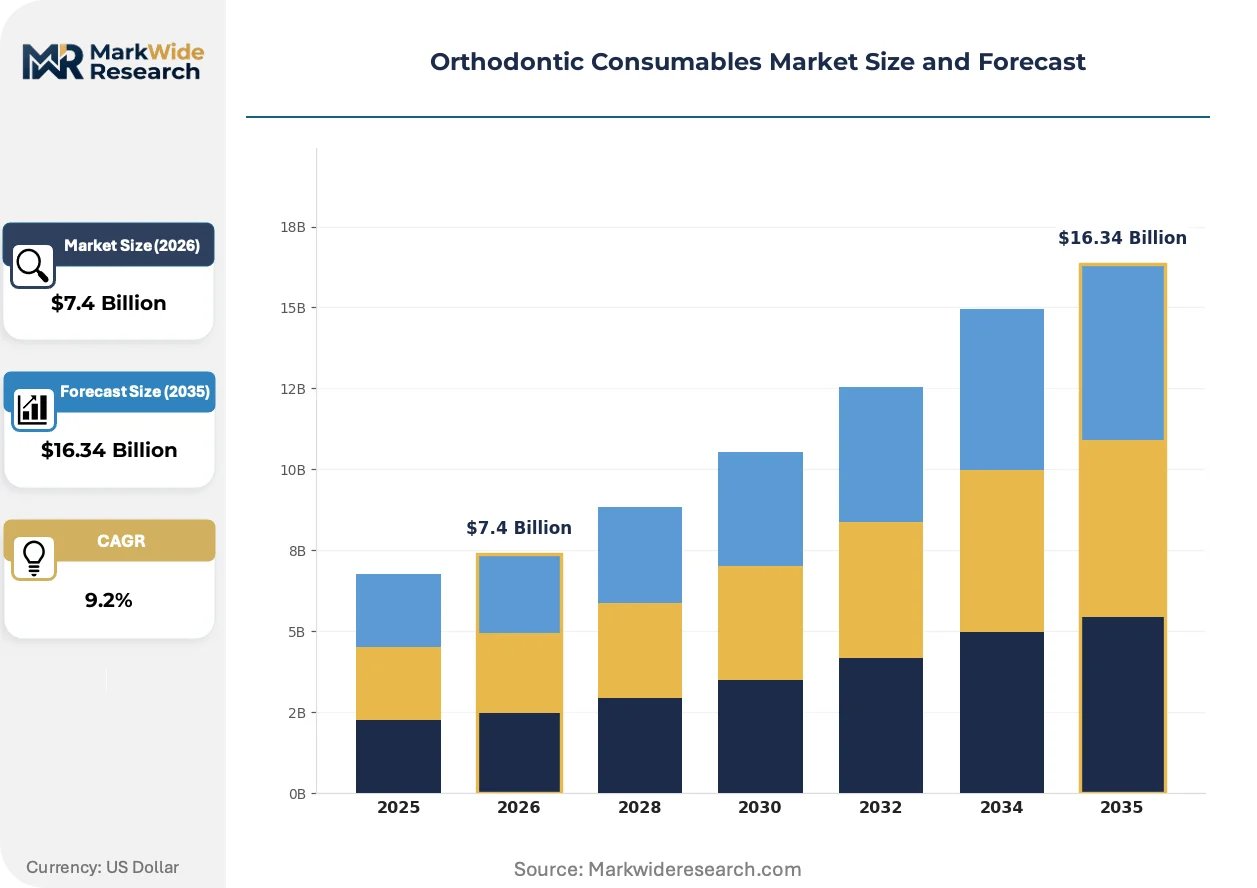
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $16.34 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brackets, Bands, Wires, Elastics Material: Metal, Ceramic, Plastic, Composites End User: Dentists, Orthodontists, Dental Clinics, Hospitals Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Align Technology, Inc., Dentsply Sirona, Envista Holdings, Solventum, American Orthodontics, Rocky Mountain Orthodontics, G&H Orthodontics, DB Orthodontics, Institut Straumann AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthodontic Consumables Market Strategic Shifts & Innovations
Orthodontic consumables are converging with digital dentistry workflows, compressing treatment timelines while elevating precision requirements for torque expression and force delivery across increasingly diverse patient anatomies.
Shape-memory nickel-titanium archwires with programmed thermal activation profiles are supplanting conventional stainless-steel configurations in adolescent and adult fixed appliance cases. Urban dental clinics in São Paulo and Mumbai are transitioning 60-70% of their wire inventory to superelastic variants within 24-month procurement cycles. This material shift is enabling longer intervals between adjustment appointments, reducing chair time demand and aligning with patient preference for fewer office visits.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data collection for all Class IIa orthodontic devices sold in member states. Manufacturers must now maintain active implant registries and adverse event reporting infrastructure that smaller competitors cannot sustain. Ceramic bracket suppliers targeting Germany, France, and Italy are consolidating quality management systems to satisfy notified body expectations for lifetime fracture resistance documentation.
Direct-to-clinic distribution platforms are disrupting traditional dental dealer networks by offering real-time inventory visibility and automated reorder triggers based on consumption algorithms. Solo and small-group practices across Brazil's Southeast region are abandoning quarterly bulk purchasing in favor of just-in-time replenishment that reduces working capital requirements. This channel transformation is most pronounced among aligner-focused practices where case volume fluctuation makes demand forecasting particularly challenging.
Orthodontic Consumables Market Segmentation
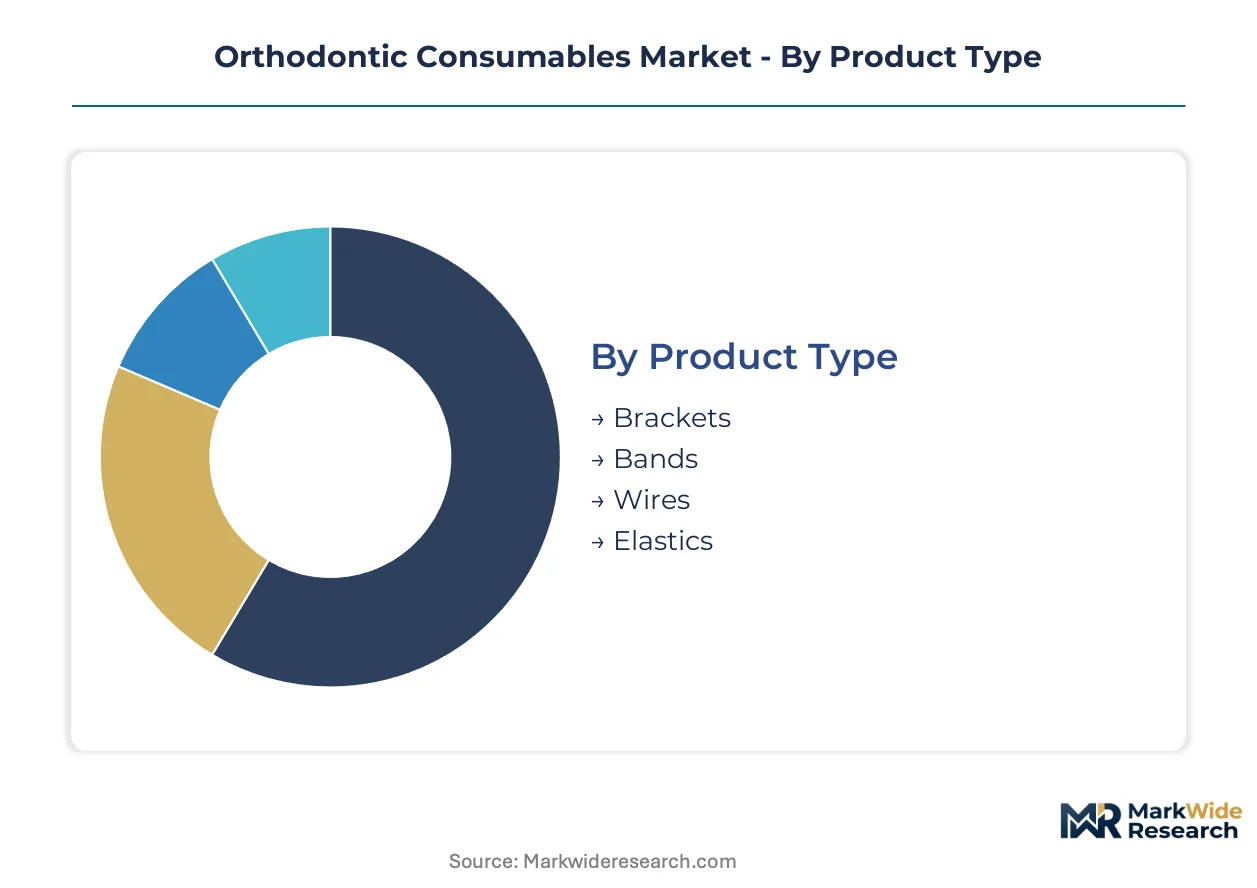
Orthodontic consumable segmentation reveals divergent regulatory pathways and procurement economics across material grades and delivery channels. Manufacturers calibrate certification investments and pricing architectures to match the compliance burden and volume concentration of each category.
Product Type:
FDA 510(k) notification requirements vary sharply by bracket versus wire classification, with self-ligating systems facing heightened mechanical testing scrutiny under EU MDR Annex I.
- Brackets:Injection-molded stainless steel and polycrystalline ceramic configurations deliver precise torque expression through slot dimension tolerances. Demand clusters in Brazil's São Paulo corridor where ANVISA's updated biocompatibility protocols favor established suppliers with ISO 13485 certification.
- Wires:Nickel-titanium superelastic alloys with programmed thermal activation profiles enable extended adjustment intervals. India's CDSCO has tightened nickel ion release testing for these imports, extending clearance timelines for archwire portfolios targeting Lucknow and Indore clinics.
- Bands:Pre-formed stainless steel rings cemented to molars provide anchorage for fixed appliances.
- Elastics:Latex and synthetic chains deliver continuous force vectors for space closure and intermaxillary correction.
Established volume favors brackets; emerging adoption favors superelastic wires.
Material:
Cost tier differentiation separates premium ceramic and composite positioning from commodity metal configurations in procurement contracts.
- Metal:Stainless steel and cobalt-chromium alloys dominate volume through durability and cost efficiency. India's tier-2 cities source these through direct-to-clinic platforms that bypass traditional dealer markups.
- Ceramic:Polycrystalline alumina and zirconia formulations command premium positioning in adult aesthetic segments. Brazil's private insurance expansion has accelerated ceramic bracket uptake in Rio de Janeiro and Curitiba practices.
- Plastic:Thermoplastic polymers for clear aligner shells require multilayer vacuum forming expertise.
- Composites:Fiber-reinforced materials blend mechanical performance with color-matching capabilities.
Metal retains volume leadership; ceramic captures margin expansion.
End User:
Customer type determines technical support intensity and inventory replenishment cadence across the care delivery spectrum.
- Dental Clinics:General practitioner settings in India's secondary cities drive demand for chairside-adjustable systems requiring minimal orthodontic training. CDSCO's revised device rules have complicated import logistics for these high-fragmentation buyers.
- Orthodontists:Specialist practices specify precision torque systems and custom archwire configurations. Brazil's concentrated specialist presence in São Paulo enables just-in-time procurement through direct manufacturer relationships.
- Dentists:Solo practitioners balance cost constraints with patient outcome requirements.
- Hospitals:Institutional procurement favors contracted volume pricing and consolidated supplier relationships.
Clinic expansion is climbing the fastest; orthodontist consolidation favors premium positioning.
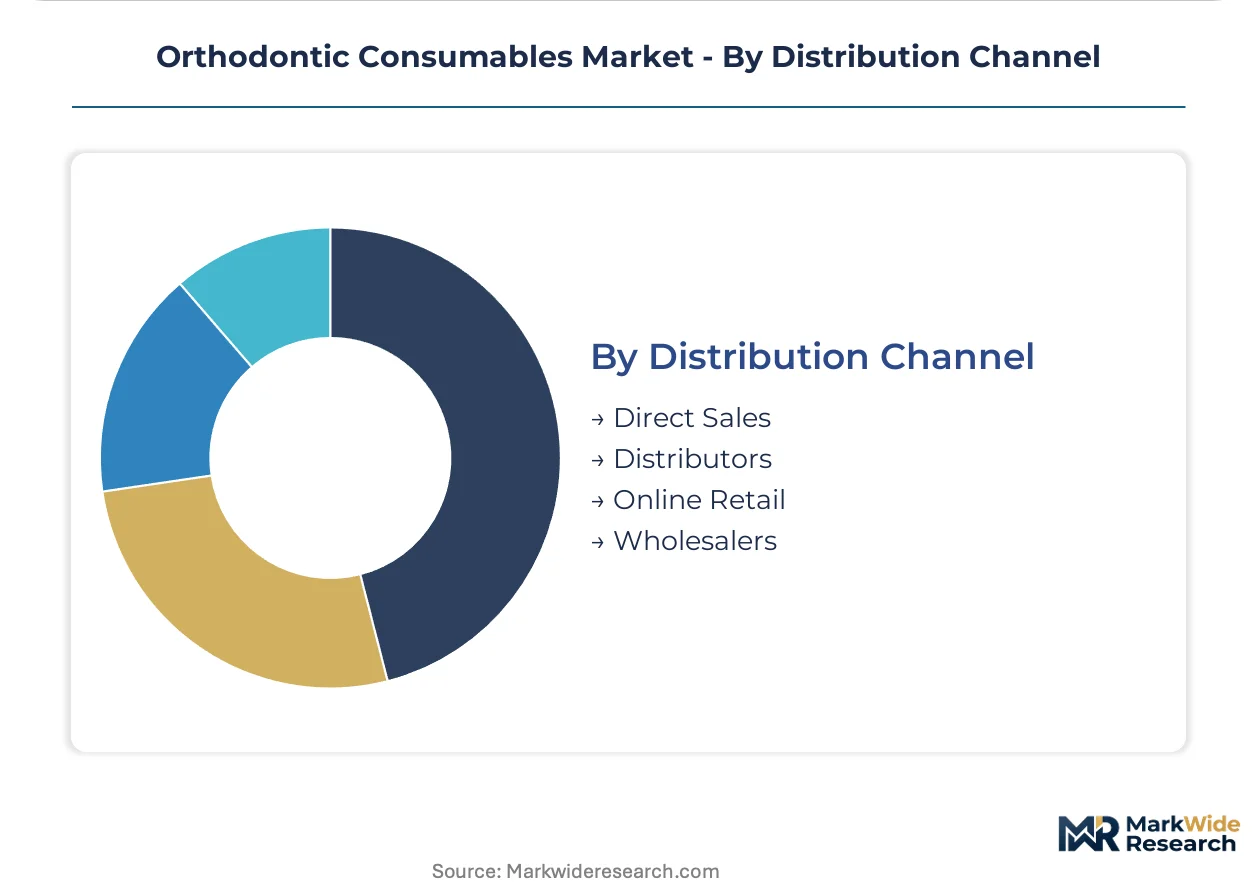
Distribution Channel:
Supply concentration shapes margin retention and working capital requirements across channel architectures.
- Direct Sales:Manufacturer-to-clinic relationships capture margin and enable consumption-based replenishment algorithms. Brazil's Southeast region shows pronounced migration toward this channel among aligner-focused practices with volatile case volumes.
- Distributors:Traditional dental dealer networks maintain inventory depth and credit extension for smaller accounts. India's CDSCO documentation requirements have raised compliance costs for distributor-held imports.
- Online Retail:E-commerce platforms aggregate demand from dispersed practices seeking price transparency.
- Wholesalers:Bulk aggregation serves institutional buyers with predictable consumption patterns.
Direct sales gain share fastest; distributor relationships defend position in credit-constrained segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA anchors the United States market through Class II medical device oversight, while regulatory divergence across Brazil, India, China, and Germany creates distinct compliance pathways for orthodontic consumable manufacturers.
United States
Digital intraoral scanning penetration drives demand for chairside-adjustable bracket systems. The FDA's 510(k) premarket notification framework requires mechanical testing documentation for self-ligating devices. Metropolitan dental clusters in Dallas-Fort Worth and Phoenix are transitioning procurement toward direct-to-clinic platforms that bypass traditional dealer networks.
Brazil
Private insurance expansion and ANVISA's updated biocompatibility protocols accelerate ceramic bracket uptake in aesthetic-driven adult segments. São Paulo's concentrated specialist presence enables just-in-time replenishment through manufacturer-direct relationships. Rio de Janeiro and Curitiba practices are abandoning quarterly bulk purchasing for consumption-based algorithms.
India
CDSCO's tightened nickel ion release testing extends clearance timelines for imported nickel-titanium archwires targeting tier-2 cities. Lucknow and Indore clinics rely on prefabricated self-ligating systems as trained orthodontist availability collapses. Direct-to-clinic distribution platforms now bypass traditional dealer markups in tier-2 procurement.
China
NMPA's domestic clinical trial mandate for aligner approvals extends market entry timelines by 18-24 months for foreign portfolios. Yangtze River Delta dental clusters are adopting 3D-printed bracket substitutes through direct metal laser sintering. Shanghai and Hangzhou practices are integrating AI-powered treatment planning with consumable procurement workflows.
Germany
The EU Medical Device Regulation's post-market surveillance requirements mandate systematic clinical follow-up data collection for Class IIa devices. Notified body expectations for lifetime fracture resistance documentation favor established ceramic bracket suppliers. Munich and Stuttgart orthodontic practices are consolidating quality management systems to satisfy Annex I mechanical testing scrutiny.
Orthodontic Consumables Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper tier capturing margin through digital workflow integration and the lower tier competing on material specialization and regional logistics density. The market structure reflects consolidation around firms with CAD/CAM ecosystem control and those with captive archwire alloy supply. Three archetypes dominate: digital platform orchestrators, precision metal formers, and direct-distribution logistics specialists. Competitive moves center on strategic partnerships with intraoral scanner manufacturers and backward integration into nickel-titanium alloy production.
Among US-based technology integrators, Align Technology occupies a position exemplifying digital platform orchestration through its scanning ecosystem. Dentsply Sirona represents the integrated equipment-consumable archetype with its CAD/CAM workflow compression capabilities. Institut Straumann AG anchors the premium materials tier through its Swiss AG structure and focus on titanium archwire portfolios. These three firms collectively illustrate the competitive vectors reshaping procurement relationships with dental clinics across fragmented secondary city markets.
| Leading Market Players |
|---|
| Align Technology, Inc. |
| Dentsply Sirona |
| Envista Holdings |
| Solventum |
| American Orthodontics |
| Rocky Mountain Orthodontics |
| G&H Orthodontics |
| DB Orthodontics |
| Institut Straumann AG |
| Others |
Cost & Logistics Intelligence
EU MDR clinical evidence requirements gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to embed compliance costs into premium-tier positioning while commodity-grade competitors face margin compression from notified body bottlenecks. This regulatory architecture concentrates pricing power among firms with established post-market surveillance infrastructure.
Pricing Analysis
Brazil's private insurance corridor commands 40-60% premiums over India's tier-2 city procurement for equivalent ceramic bracket specifications. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified European suppliers from emerging Asian manufacturers and unbranded local alternatives. Cost compression in nickel-titanium archwires is intensifying because palladium and rhodium coating inputs face commodity volatility without contractual pass-through mechanisms. Dental clinics in Lucknow and Indore exhibit highest price sensitivity, while São Paulo specialist practices prioritize torque precision over unit economics.
Supply Chain Analysis
Germany and Switzerland anchor precision archwire alloy production through captive nickel-titanium smelting and ISO-certified drawing facilities. China's Yangtze River Delta clusters vacuum-formed aligner polymer manufacturing alongside 3D-printing substrate fabrication. The supply chain draws from South Korean rare earth processing for magnetic wire coatings and Japanese thermoplastic resin formulation for multilayer aligner shells. Single-source vulnerability concentrates in EU notified body certification capacity, where backlogs strand inventory in transit. Distribution runs through direct-to-clinic platforms displacing traditional dental dealer networks across Brazil's Southeast region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, where EU MDR compliance infrastructure creates switching costs that lock in clinic procurement relationships and strand undercapitalized competitors.
For Market Incumbents: Consolidate backward integration into nickel-titanium alloy production to neutralize precious metal input volatility threatening archwire margins. Expand direct-to-clinic logistics density across India's tier-2 cities before CDSCO documentation requirements raise distributor compliance barriers. Capture teleorthodontic monitoring integration to embed consumable replenishment within subscription workflows that reduce price transparency. For New Entrants and Emerging Players: Chairside-adjustable self-ligating systems for general practitioners in India's orthodontist-scarce secondary cities represent the most penetrable white-space segment. Target just-in-time replenishment algorithms for Brazil's aligner-focused practices with volatile case volume forecasting. Pursue regulatory arbitrage through notified body jurisdiction shopping for faster EU MDR clearance timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital treatment planning platform development, favoring scaled players with existing scanner ecosystem integration. Long-term viability over a multi-year horizon hinges on capturing CAD/CAM workflow control points rather than commodity consumable manufacturing. Acquire precision metal forming specialists with captive archwire alloy supply and established GPO contracts. Watch for NMPA domestic trial mandate relaxation as inflection signal for China market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Titanium Alloy Production | Captive supply of superelastic wire feedstock insulates margins from palladium and rhodium commodity swings. |
| Direct-to-Clinic Distribution Platform Expansion | Consumption-based algorithms reduce working capital burdens for Brazil's aligner-focused practices. |
| EU MDR Post-Market Surveillance Infrastructure Buildout | Clinical registry capabilities satisfy notified body expectations for lifetime fracture resistance documentation. |
| Teleorthodontic Monitoring Integration | Remote progress tracking embeds consumable refills within subscription revenue models decoupled from chairside frequency. |
| CDSCO Biocompatibility Certification Investment | Redundant laboratory validation for nickel ion release accelerates clearance timelines for India's tier-2 city targeting. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with orthodontists, dental clinic owners, biomedical procurement managers, GPO contract specialists, and nickel-titanium alloy metallurgists. Secondary validation drew from FDA 510(k) filings, EU MDR notified body guidance documents, CDSCO medical device rule amendments, ANVISA biocompatibility protocols, and customs import records for archwire and bracket classifications. Bottom-up patient volume modeling across tier-2 and tier-3 city clusters was triangulated against top-down manufacturer shipment data.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, material grade, end-user archetype, and distribution channel configuration. CAGRs were derived from elasticity-adjusted demand curves incorporating reimbursement expansion timelines and specialist density trajectories. Modeled inputs included nickel-titanium alloy spot price volatility bands, aligner case approval velocity through NMPA clinical trial mandates, and digital intraoral scanner penetration rates by metropolitan cluster.
Forecasts assume regulatory continuity in EU MDR enforcement, CDSCO testing protocol stability, and NMPA domestic trial requirements; material policy shifts in any regime would require re-modeling. Specific risks that could revise projections include notified body capacity collapse extending clearance timelines, precious metal supply disruption from South Korean processing constraints, or 3D-printed bracket substitution acceleration in China's Yangtze River Delta. Recalibration cycles align with material shifts in reimbursement framework expansions and regulatory amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Supplies
Dental Consumables Market
Dental Supplies
Plaque Disclosing Market
Dental Supplies
Global Dental Suture Market
Dental Supplies
Dental Preventive Supplies Market
Dental Supplies
Fissure Sealants Market
Dental Supplies
Endodontic Supplies Market
Dental Supplies
Global Hotel Dental Kits Market
Dental Supplies
Dental Caries Treatment Market
Dental Supplies
Orthodontic Supplies Market