
 Fissure Sealants Market | 2026-2036
Fissure Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Fissure Sealants Market Analysis
Dental clinic procurement is consolidating around larger group practices and dental service organizations, concentrating purchasing power among fewer buyers. 3M leverages its adhesive technology heritage to sustain premium positioning in resin-based formulations. Dentsply Sirona competes through integrated digital workflow platforms that bundle sealants with diagnostic equipment. GC Corporation anchors market presence across Asia-Pacific manufacturing clusters with localized compomer production.
Fissure sealants are flowable dental materials—typically bis-GMA resin or glass ionomer compositions—that clinicians apply to occlusal pits and fissures to create a physical barrier against cariogenic biofilm colonization, with setting times ranging from 20 seconds to 2 minutes depending on light-cure or self-cure chemistry. Resin-based formulations dominate volume due to established clinical longevity data and broad insurance reimbursement, while glass ionomer variants capture growth in moisture-contaminated field settings where technique sensitivity limits traditional resin placement. Pediatric dentistry represents the most concentrated application segment, though preventive care programs in school-based and mobile delivery formats are expanding fastest from a smaller base.
The US FDA regulates sealants as Class II medical devices requiring 510(k) premarket notification, while the EPA oversees residual monomer environmental discharge from manufacturing facilities. Europe's MDR and REACH frameworks impose stricter biocompatibility and substance restriction requirements that reshape formulation chemistry for CE-marked products. Stakeholders must monitor evolving reimbursement codes for preventive services and material safety dossier requirements as regulatory stringency diverges across major markets.
Market Dynamics
Dental service organizations are consolidating procurement decisions, concentrating purchasing power among fewer buyers and forcing manufacturers to restructure pricing and service models around volume commitments and integrated supply contracts.
Growth Catalysts
- Smiling Brazil Program:Brazil's national oral health initiative funds school-based sealant applications for millions of children, creating sustained public procurement demand.
- REACH Substance Restrictions:Europe's chemical framework is accelerating reformulation toward biocompatible monomers, opening premium positioning for compliant manufacturers.
- Light-Cure Chemistry:Faster polymerization systems reduce chair time and enable higher patient throughput in high-volume community clinics.
Market Restraints
- Bis-GMA Monomer Volatility:Epoxy resin feedstock costs fluctuate with petrochemical pricing, compressing margins on resin-based formulations.
- Technique Sensitivity:Moisture contamination during placement compromises resin sealant retention rates, limiting effectiveness in non-clinical field settings.
- Glass Ionomer Substitution:Fluoride-releasing alternatives capture share in pediatric applications where moisture control is problematic.
Strategic Opportunities
- Mobile Dental Units:Self-cure glass ionomer formulations enable sealant delivery in rural and underserved areas without fixed clinic infrastructure.
- US Preventive Services Mandate:Medicaid expansion of pediatric dental benefits creates reimbursement tailwinds for preventive sealant procedures.
- Digital Workflow Convergence:Intraoral scanning and 3D printing are integrating with sealant placement protocols for precise fissure mapping.
Industry Challenges
- Pediatric Behavior Management:Young patient cooperation limits application success rates, demanding specialized training for dental auxiliaries.
- ISO 10993 Biocompatibility Certification:Cytotoxicity testing timelines extend product launch schedules by 12-18 months for new formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fissure Sealants Market |
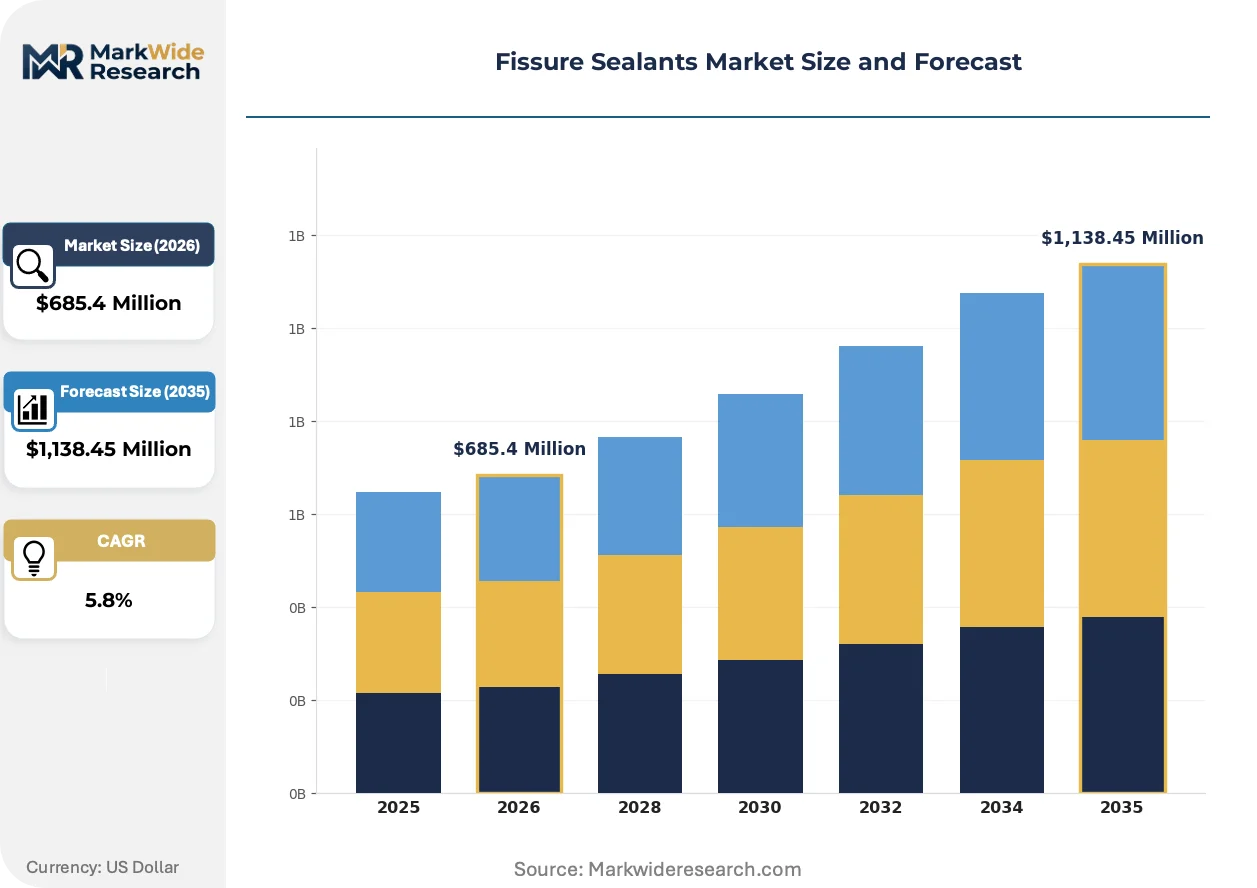
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin-based, Glass Ionomer, Polyacid-modified Resin, Compomer Application: Pediatric Dentistry, General Dentistry, Preventive Care, Orthodontics End User: Dental Clinics, Hospitals, Research Institutions, Mobile Units Distribution Channel: Online Retail, Direct Sales, Distributors, Dental Supply Stores |
| Companies Covered | 3M, Dentsply Sirona, Ivoclar Vivadent, GC Corporation, PULPDENT Corporation, SHOFU Dental, Ultradent Products, Kerr Corporation, Coltene Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fissure Sealants Market Emerging Trajectories
Material science advances and regulatory chemistry requirements are converging to reshape formulation portfolios, while procurement centralization alters how manufacturers engage with end-users.
Nanofilled resin composites are integrating hydroxyapatite particles to enhance wear resistance and remineralization capacity. Pediatric group practices in the United States are adopting these materials for permanent molar applications. The technology is integrating preventive and therapeutic functions into single-application protocols, compressing the traditional separation between sealants and restorative materials.
Europe's MDR framework now classifies fissure sealants under stricter biocompatibility surveillance than prior directives. Manufacturers must maintain post-market clinical follow-up data and update technical documentation annually. Medium-sized European dental material suppliers are responding by consolidating regulatory affairs functions and outsourcing notified body interactions to specialized consultancies.
Consolidated buying through dental service organizations is replacing individual practice procurement across the United States. Large DSOs negotiate enterprise pricing and exclusive supply agreements directly with manufacturers. This concentration is most visible in Texas and Florida, where multi-location pediatric chains now control significant sealant volume.
Fissure Sealants Market Segmentation
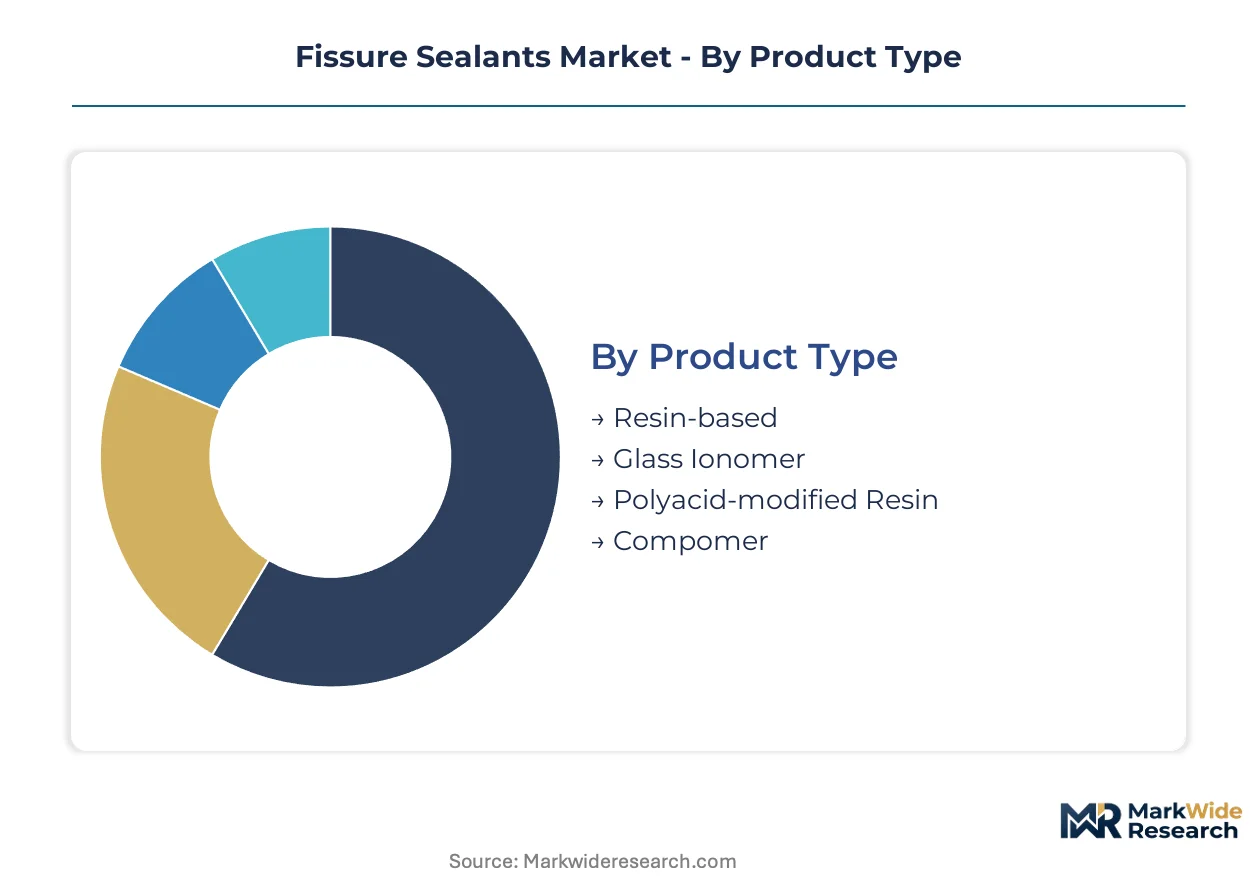
Segmentation in fissure sealants reveals how material chemistry, clinical setting, and procurement channel create distinct competitive arenas. Manufacturers must align formulation portfolios with the specific performance and regulatory demands of each slice.
Product Type:
Supply concentration in resin monomer production shapes competitive dynamics across chemistry families, with epoxy-Bis-GMA feedstock controlled by a handful of petrochemical refiners.
- Resin-based:Bis-GMA and urethane dimethacrylate formulations polymerize via light-cure or self-cure initiation, delivering superior wear resistance and color stability. Demand clusters in US private pediatric practices where insurance reimbursement favors established longevity data, though monomer cost volatility compresses margins.
- Glass Ionomer:Fluoroaluminosilicate glass powders react with polyacrylic acid to release fluoride and bond chemically to enamel. Brazilian public health clinics under the Smiling Brazil program drive volume here, prioritizing moisture tolerance over aesthetic longevity in school-based field settings.
- Polyacid-modified Resin:Hybrid chemistry combining resin esthetics with ionomer fluoride release captures niche positioning in European preventive programs.
- Compomer:Resin-modified glass ionomer formulations from GC Corporation and similar Asia-Pacific manufacturers serve cost-sensitive clinic chains.
Today's leader: Resin-based. Tomorrow's challenger: Glass Ionomer.
Application:
Cost tier stratification separates high-reimbursement specialty procedures from commodity preventive programs, with pediatric dentistry commanding premium material specifications.
- Pediatric Dentistry:Permanent molar sealant placement in children aged 6-14 represents the highest-volume application globally. US Medicaid expansion and Brazilian school-based initiatives concentrate demand here, though behavior management challenges limit application success rates.
- General Dentistry:Adult preventive applications and occlusal rehabilitation in mixed dentition patients. European REACH-compliant formulations gain preference in German and French adult clinics where biocompatibility certification carries marketing weight.
- Preventive Care:Community health programs and mobile delivery formats in rural India and Southeast Asia.
- Orthodontics:Band cementation adjuncts and bracket-adjacent sealant applications in adolescent treatment protocols.
Pediatric Dentistry commands current volume. Preventive Care climbs fastest as public health infrastructure expands.
End User:
Customer type fragmentation—solo practitioners versus consolidated buyers—forces manufacturers to maintain parallel sales organizations with incompatible incentive structures.
- Dental Clinics:Independent practices and dental service organizations account for the majority of sealant volume. Texas and Florida pediatric chains negotiate enterprise pricing directly with manufacturers, displacing distributor intermediaries.
- Hospitals:Academic medical centers and children's hospitals with residency programs favor research-backed formulations with extensive clinical documentation.
- Research Institutions:Universities and government laboratories evaluating novel remineralization technologies.
- Mobile Units:Self-contained field clinics serving remote populations in Brazil's Amazon regions and India's rural districts.
Dental Clinics dominate procurement today. Mobile Units represent the steepest expansion trajectory as governments fund decentralized oral health access.
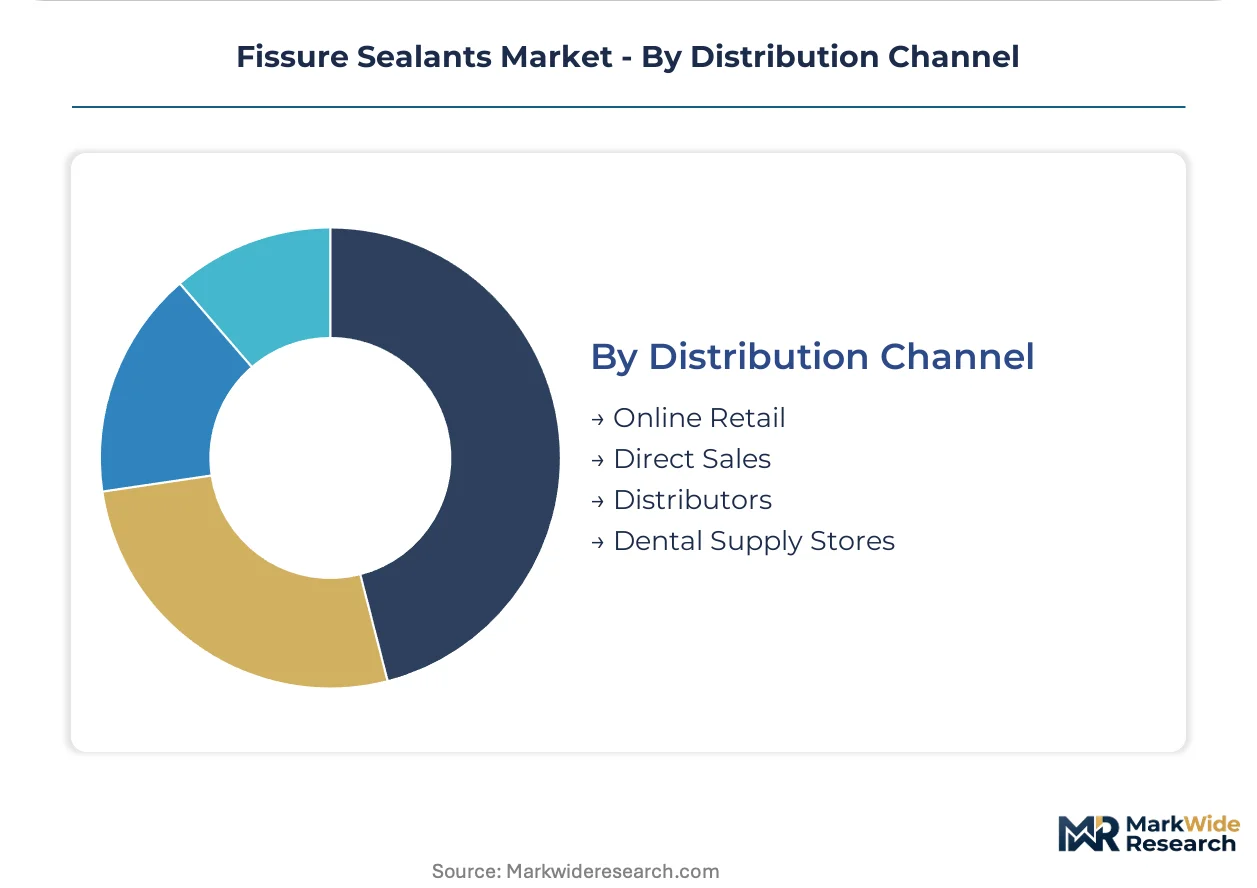
Distribution Channel:
Margin structure varies dramatically by channel, with direct sales to large buyers capturing value that distributors formerly extracted from fragmented clinic bases.
- Direct Sales:Manufacturer representatives negotiate supply contracts with dental service organizations and hospital purchasing consortia. 3M and Dentsply Sirona deploy dedicated account teams for multi-location pediatric chains.
- Distributors:Henry Schein and Patterson Dental maintain inventory breadth for independent practitioners without procurement consolidation.
- Online Retail:E-commerce platforms serve small practices and international buyers seeking price transparency on standardized SKUs.
- Dental Supply Stores:Regional brick-and-mortar outlets with same-day availability for emergency replenishment.
Direct Sales leads value capture. Online Retail gains share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's public procurement volume dwarfs that of Germany, where private pediatric practices drive premium material specifications instead of government-funded school programs.
United States
Texas and Florida pediatric dental chains concentrate sealant volume through direct manufacturer contracts. The FDA's 510(k) premarket notification pathway governs Class II device approvals. Dallas-based dental service organizations negotiate enterprise pricing that displaces traditional distributor relationships.
Brazil
The Smiling Brazil program funds school-based applications for millions of children annually. ANVISA regulates dental biomaterial safety alongside Ministry of Health procurement standards. Amazon region mobile units deploy self-cure glass ionomer formulations where fixed clinic infrastructure remains absent.
Germany
Private pediatric practices prioritize REACH-compliant formulations with extensive biocompatibility dossiers. The BfArM and Federal Institute for Drugs and Medical Devices enforce MDR post-market surveillance requirements. Bavarian dental material suppliers consolidate regulatory affairs functions to manage annual technical documentation updates.
Japan
GC Corporation anchors domestic manufacturing of compomer formulations for cost-sensitive Asian markets. The PMDA and MHLW impose pharmaceutical-grade purity standards on resin monomer imports. Osaka-based production clusters supply fluoride-releasing variants to Southeast Asian preventive care programs.
India
Rural mobile dental units expand fastest among government-funded oral health initiatives. The CDSCO regulates medical device imports while state health departments manage tender-based procurement. Maharashtra community health networks deploy field-tolerant glass ionomer sealants in moisture-compromised settings.
Fissure Sealants Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across chemistry families and geographic markets. The vendor base splits between adhesive technology heritage players and dental-specific material formulators. Three archetypes dominate: multinational healthcare conglomerates with cross-sector adhesive portfolios, Asia-Pacific manufacturing specialists with localized compomer production, and regional European suppliers with MDR compliance expertise. Competitive moves center on direct sales force expansion for dental service organization penetration and regulatory dossier consolidation for European market access.
Among multinational healthcare conglomerates, 3M and Dentsply Sirona exemplify divergent strategic positioning. 3M represents the adhesive technology heritage archetype, leveraging cross-industrial polymer science capabilities into premium resin formulation positioning. Dentsply Sirona occupies the integrated digital workflow tier, bundling sealant materials with diagnostic and treatment equipment. GC Corporation anchors the Asia-Pacific manufacturing specialist category, with Japanese-origin production clusters serving cost-sensitive regional demand through localized compomer supply chains.
| Leading Market Players |
|---|
| 3M |
| Dentsply Sirona |
| Ivoclar Vivadent |
| GC Corporation |
| PULPDENT Corporation |
| SHOFU Dental |
| Ultradent Products |
| Kerr Corporation |
| Coltene Holding |
| Others |
Supply Flow & Price Mechanics
Dental service organization consolidation across Texas and Florida pediatric chains concentrates purchasing power into volume-based contract negotiations, compressing distributor margins and forcing manufacturers toward direct sales models with transparent tiered pricing.
Pricing Analysis
Capacity additions in Japanese compomer manufacturing are reshaping price floors for fluoride-releasing formulations across Asia-Pacific markets. Three-tier pricing structure across premium resin, standard glass ionomer, and economy compomer levels stratifies by certification grade and volume commitment scale. Pricing pressure stems from Brazilian public tender processes under the Smiling Brazil program, where lowest-compliant-bid rules dominate procurement. Small independent clinics exhibit highest price sensitivity, while hospital purchasing consortia prioritize biocompatibility certification over unit cost.
Supply Chain Analysis
Expired sealant material returns and batch recalls flow through specialized dental waste handlers rather than reverse logistics networks, reflecting biomedical disposal regulations. Bis-GMA monomer production concentrates in China, South Korea, and Germany, with epoxy resin feedstock drawing from petrochemical refiners in each jurisdiction. Polymerization initiator chemicals and fluoroaluminosilicate glass powders represent critical dependencies with limited qualified suppliers. Single-source vulnerability in photoinitiator compounds creates exposure to pharmaceutical-grade purity disruptions. Distribution runs through Henry Schein and Patterson Dental for independent practices, while direct manufacturer contracts serve consolidated dental service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Europe's MDR biocompatibility surveillance and Brazil's Smiling Brazil procurement mandates jointly determine viable competitive positioning.
For Market Incumbents: Hedge against glass ionomer substitution by securing backward integration into fluoroaluminosilicate glass powder production. Anchor premium resin positioning through ISO 10993 cytotoxicity certification investment, defending against REACH-compliant European entrants. Dentsply Sirona's integrated digital workflow bundling represents the channel control model to emulate. For New Entrants and Emerging Players: E-commerce platforms targeting Southeast Asian preventive care programs offer the lowest barrier to initial traction. India's rural mobile dental units present the most penetrable white space, with Maharashtra community health networks actively tendering for field-tolerant formulations. A direct-to-clinic digital sales model bypasses established distributor relationships that 3M and GC Corporation dominate. For Investors and Strategic Acquirers: Dental service organizations are the most active acquirer in this space, consolidating pediatric chains to capture procurement scale. The five-to-ten year viability window favors manufacturers with dual resin-ionomer formulation portfolios and MDR dossier readiness. Mid-sized European suppliers with outsourced notified body relationships represent prime acquisition targets. Watch for Medicaid expansion signals in US state budgets as inflection indicators for preventive services reimbursement tailwinds.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation | Europe's MDR framework rewards biocompatible monomer chemistry with premium market access. |
| Direct Sales Force Expansion | Texas pediatric chains now negotiate enterprise pricing that displaces distributor intermediaries entirely. |
| Mobile Unit Formulation Development | Self-cure glass ionomer variants enable Brazil's Amazon region delivery without fixed clinic infrastructure. |
| Regulatory Dossier Consolidation | Annual MDR technical documentation updates favor outsourced notified body specialist relationships. |
| Digital Workflow Integration | Intraoral scanning convergence bundles sealant placement with diagnostic equipment procurement decisions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pediatric dentistry clinic directors, dental service organization procurement officers, biomedical engineers at children's hospitals, and regulatory affairs specialists at notified bodies with secondary validation. FDA 510(k) premarket notification databases, ANVISA registration filings, ECHA REACH substance restriction updates, and hospital GPO contract repositories anchored the secondary foundation. Bottom-up sealant volume modeling triangulated against top-down preventive services expenditure estimates.
Historical reference periods anchored the projection horizon through documented clinical longevity data and reimbursement code evolution patterns. Segmentation dimensions spanned material chemistry families, application settings from private practice to mobile delivery, procurement channel concentration levels, and regional regulatory clusters. CAGRs derived from slope analysis across modeled volume trajectories, with inputs including Brazilian Ministry of Health procurement disclosures and US Medicaid pediatric dental benefit expansion timelines.
REACH substance list amendments, FDA biocompatibility guidance revisions, and Brazilian federal budget allocations are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about regulatory stability and public health program continuity. Practitioners should monitor these triggers for early signals of trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Supplies
Global Dental Suture Market
Dental Supplies
Dental Caries Treatment Market
Dental Supplies
Dental Preventive Supplies Market
Dental Supplies
Orthodontic Supplies Market
Dental Supplies
Endodontic Supplies Market
Dental Supplies
Global Hotel Dental Kits Market
Dental Supplies
Dental Consumables Market
Dental Supplies
Plaque Disclosing Market
Dental Supplies
Orthodontic Consumables Market