
 Dental Caries Treatment Market | 2026-2036
Dental Caries Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Caries Treatment Market Intelligence
The consolidation of dental service organizations (DSOs) and large clinic groups is rewriting traditional distributor-led sales models. Dentsply Sirona Inc. leverages its comprehensive product portfolio and established channel partnerships to maintain a significant footprint. 3M Company differentiates through its materials science innovation, particularly in adhesives and composites. GC Corporation sustains a strong position in the market for restorative materials like glass ionomers.
Dental caries treatment encompasses procedures to remove decayed tooth tissue and restore the tooth's form, function, and aesthetics. These interventions often use high-speed burs for excavation and light-cured materials that polymerize to create a durable bond. While the restorative treatment approach remains the largest segment, preventive care therapies are gaining traction. Within materials, composite resins continue to displace traditional amalgam for fillings due to superior aesthetics and patient preference.
Market access for dental materials and devices is governed by stringent regulatory frameworks. The U.S. FDA, Europe's Medical Device Regulation (MDR) requiring CE marking, and China's NMPA mandate rigorous testing for biocompatibility and clinical efficacy. These regulations ensure patient safety and standardize product performance across geographies. The central strategic decision for manufacturers now involves allocating R&D capital between enhancing existing material classes and pursuing breakthrough regenerative therapies.
Market Dynamics
The consolidation of dental service organizations (DSOs) is the central force altering market structure. These large clinic groups are standardizing procurement and clinical protocols, shifting purchasing power away from individual practitioners and rewriting traditional distributor-led sales models.
Growth Catalysts
- Advanced Composite Resins:The development of composite resins with improved durability, aesthetics, and biocompatibility enables the wider practice of minimally invasive dentistry, stimulating demand for restorative procedures that preserve tooth structure.
- Aging Demographics:An increasing elderly population in developed nations like Japan and Germany, coupled with higher rates of tooth retention, results in a greater lifetime need for restorative dental care and maintenance procedures. li>Public Health Initiatives: Government-sponsored dental health programs and insurance coverage expansions in countries such as Germany encourage regular check-ups and early intervention, leading to higher diagnosis rates and subsequent treatment volume.
Market Restraints
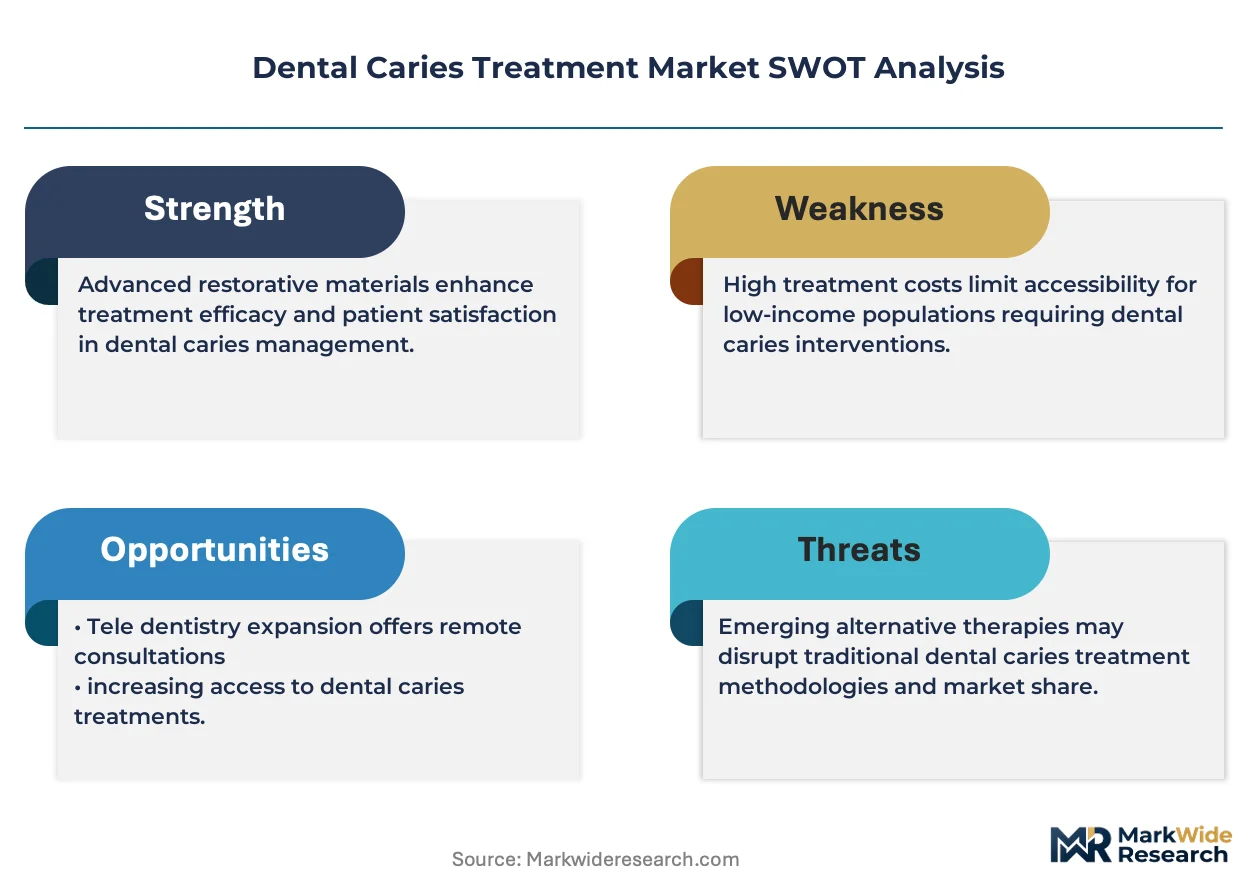
- Regulatory Compliance Costs:Stringent market access requirements, including Europe's Medical Device Regulation (MDR) and the FDA's premarket approval process, impose significant testing and documentation costs on material and device manufacturers.
- Technique Sensitivity:The clinical success of advanced adhesive and composite systems is highly dependent on meticulous application technique, creating a barrier to adoption for practitioners without specialized training.
- Reimbursement Disparities:Inconsistent reimbursement policies for newer, more expensive materials like certain composite resins versus traditional amalgam can limit their use, particularly in public health systems or price-sensitive markets.
Strategic Opportunities
- Emerging Market Penetration:Expanding dental infrastructure and a growing middle class in markets across Southeast Asia and Latin America present significant opportunities for introducing modern caries treatment technologies and materials.
- Regenerative Dentistry R&D:Investment in developing bioactive materials and therapies that can stimulate natural tooth repair and regeneration represents a frontier beyond traditional restorative approaches, offering high-value treatment options.
- Digital Treatment Platforms:The development of integrated digital platforms that connect diagnostic imaging, treatment planning software, and chairside fabrication equipment creates an opportunity to streamline workflows for DSOs and large clinics.
Industry Challenges
- Practitioner Skill Gaps:The rapid evolution of materials and digital technologies necessitates continuous education and training for dentists and their staff, creating a challenge in keeping clinical skills current with available tools.
- Intellectual Property Protection:Securing and defending patents for novel polymer chemistries in composite resins and bonding agents is a complex and costly process, particularly across multiple international jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Caries Treatment Market |
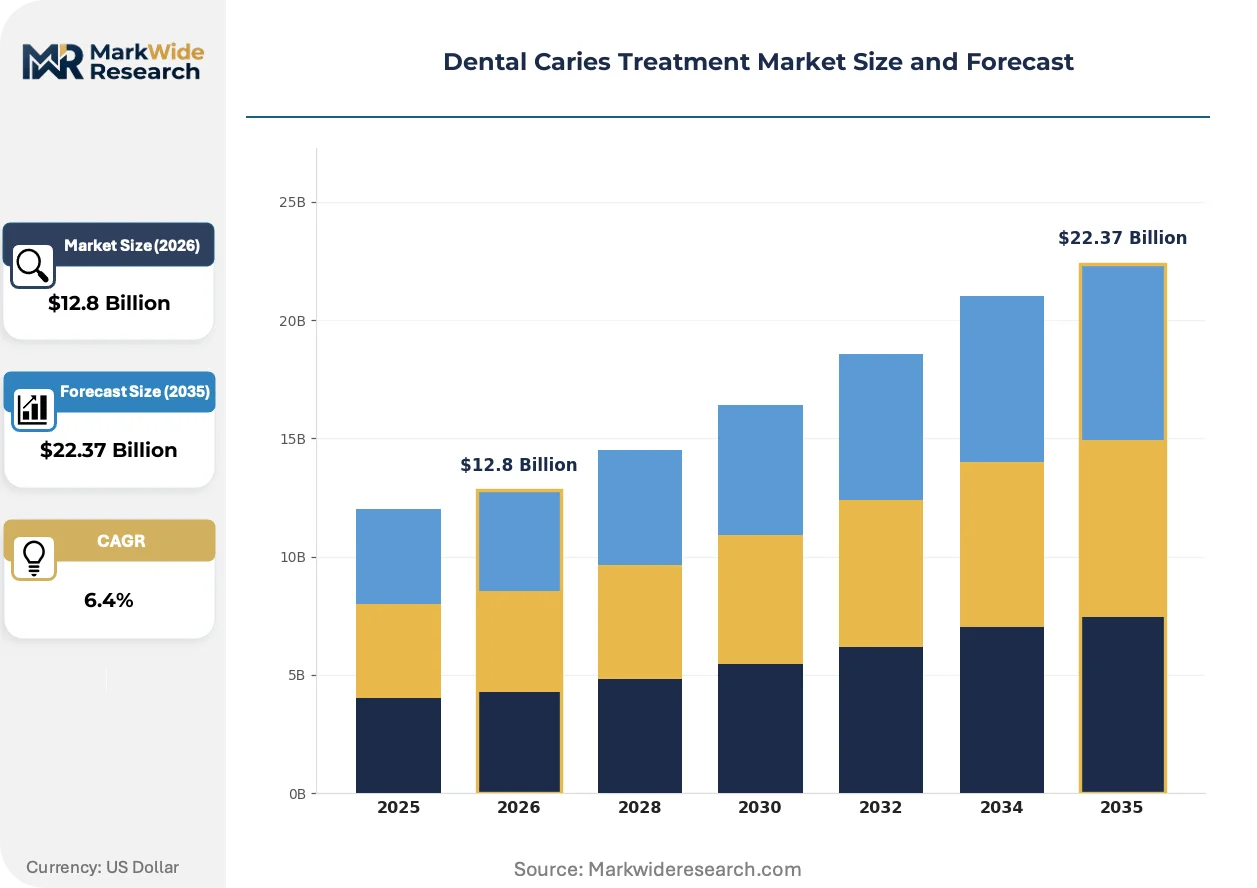
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fillings, Crowns, Sealants, Root Canals Material: Composite Resin, Amalgam, Glass Ionomer, Resin Ionomer Therapy Approach: Preventive Care, Restorative Treatment, Surgical Intervention, Palliative Care End User: Dental Clinics, Hospitals, Research Laboratories, Educational Institutions |
| Companies Covered | 3M Company, Dentsply Sirona Inc., Coltene Group, Shofu Dental Corporation, Institut Straumann AG, Zimmer Biomet, GC Corporation, Septodont Holding S.A., Acteon Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Caries Treatment Market Strategic Shifts & Innovations
The convergence of materials science and digital technology is fundamentally changing the delivery of restorative dental care. This integration enables more precise, personalized, and efficient treatment protocols, moving the field towards a more predictable and patient-centric model.
Intraoral scanners and CAD/CAM systems provide the core technology for digital impressions and in-office restoration design. Dental clinics and laboratories are progressively adopting these tools to improve accuracy and turnaround times. This technology is virtualizing the entire workflow from diagnosis to the fabrication of crowns and fillings, compressing patient chair time and reducing manual errors.
The European Union's Medical Device Regulation (MDR) has elevated the requirements for clinical evidence and post-market surveillance. This forces manufacturers to invest more heavily in generating robust data to support the safety and efficacy claims of their products. Restorative materials like composites and bonding agents, which have long-term patient contact, are under particular scrutiny, impacting product development timelines and costs for CE marking.
A discernible shift toward centralized purchasing models is evident, driven by the expansion of large dental service organizations (DSOs). This trend is disrupting the traditional sales channel where individual dentists made autonomous procurement decisions. This consolidation favors manufacturers who can provide standardized product portfolios and negotiate volume-based pricing directly with corporate management, a pattern most visible in North America.
Dental Caries Treatment Market Segmentation
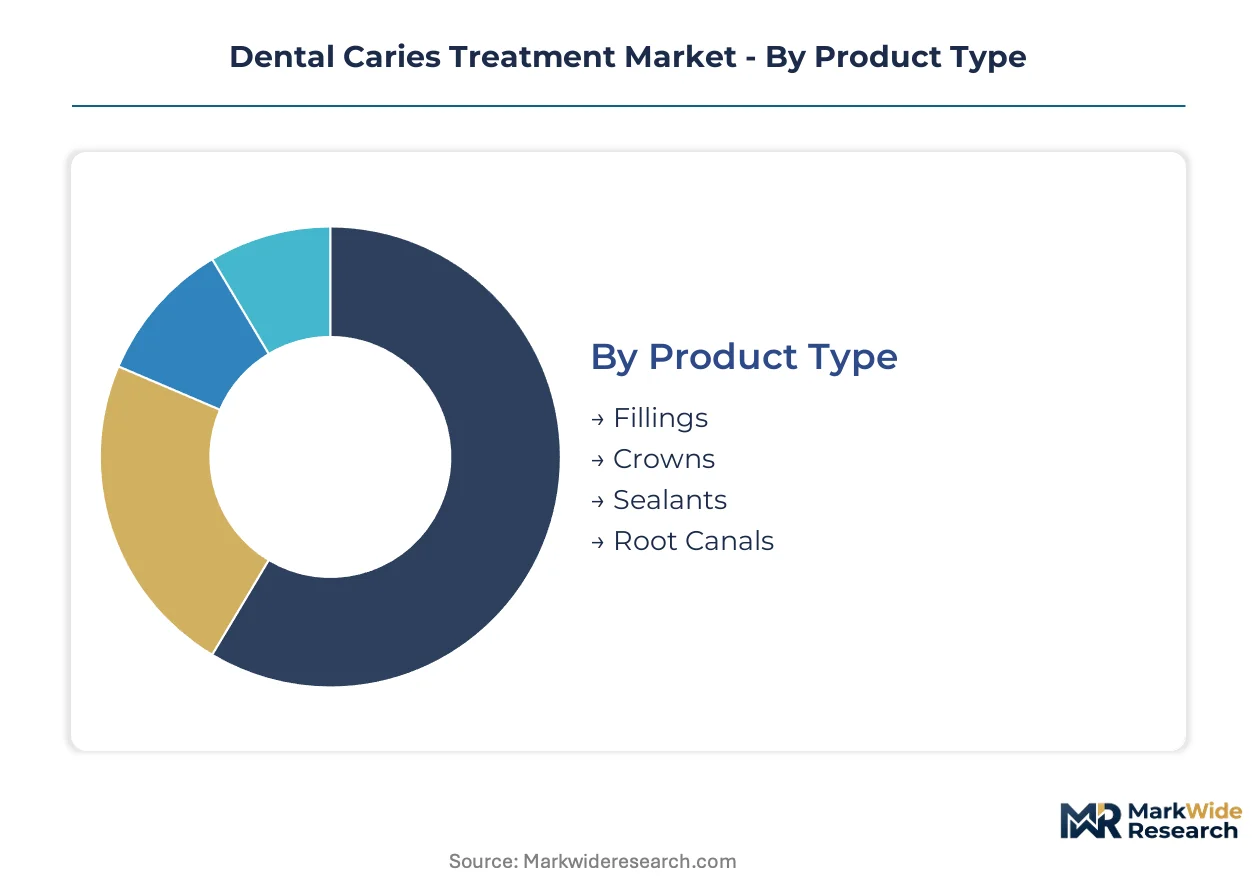
Understanding the segmentation of the dental caries treatment market provides critical insight into demand patterns and technological adoption. The market's structure reflects diverse clinical needs, material science advancements, and varied patient demographics across different product types, materials, therapy approaches, and end-user settings.
Product Type:
The product type segmentation reveals the maturity and innovation cycles within restorative dentistry.
- Fillings:These materials restore tooth structure lost to caries, with composite resins now dominating due to superior aesthetics and bonding capabilities. Demand for fillings is consistently high across all age groups, driven by widespread caries prevalence.
- Crowns:Full coverage restorations encapsulate a damaged tooth, providing strength and functional integrity, often fabricated from ceramic or metal-ceramic materials. Developed economies like Germany and Japan show high procedure volumes for crowns, supported by an aging demographic and greater tooth retention.
- Sealants:Applied to the chewing surfaces of posterior teeth, sealants create a protective barrier against decay, primarily used in pediatric and adolescent populations.
- Root Canals:This endodontic procedure removes infected pulp and seals the tooth's root canal system, preserving a severely decayed tooth from extraction.
Fillings retains volume leadership; Crowns holds the steepest expansion curve.
Material:
Material choices directly influence treatment outcomes, aesthetics, and longevity, reflecting evolving clinical preferences and regulatory standards.
- Composite Resin:These tooth-colored materials consist of a resin matrix and inorganic filler particles, offering excellent aesthetics and direct bonding to tooth structure. Patient preference in developed markets like the US and Europe increasingly favors composite resins over traditional options.
- Amalgam:A metallic alloy of mercury, silver, tin, and copper, amalgam has historically been used for its durability and cost-effectiveness. Regulatory restrictions and environmental concerns in regions like the European Union are progressively limiting amalgam's use.
- Glass Ionomer:These materials release fluoride, offering a therapeutic benefit against secondary caries, and bond chemically to tooth structure, often used for pediatric restorations.
- Resin Ionomer:Combining properties of both composite resins and glass ionomers, these materials offer improved aesthetics and strength over traditional glass ionomers.
Material selection increasingly depends on a balance between aesthetic demands and long-term durability, with regulatory shifts influencing market availability.
Therapy Approach:
The therapy approach segment categorizes interventions based on their primary clinical objective, from prevention to complex surgical procedures.
- Restorative Treatment:This approach focuses on repairing damaged tooth structure and restoring function, encompassing procedures like fillings and crowns. The shift towards minimally invasive dentistry is driving innovation within restorative treatment techniques.
- Preventive Care:Strategies such as fluoride application and dental sealants aim to avert the onset or progression of dental caries. Public health initiatives in countries like Germany actively promote preventive care, increasing patient engagement.
- Surgical Intervention:These procedures involve more extensive tissue manipulation, such as tooth extractions or complex periodontal surgeries related to caries complications.
- Palliative Care:Focusing on pain relief and symptom management rather than definitive cure, palliative care is often employed in advanced or complex cases.
The volume of preventive care procedures is expanding most quickly, while restorative treatment maintains its dominant clinical footprint.
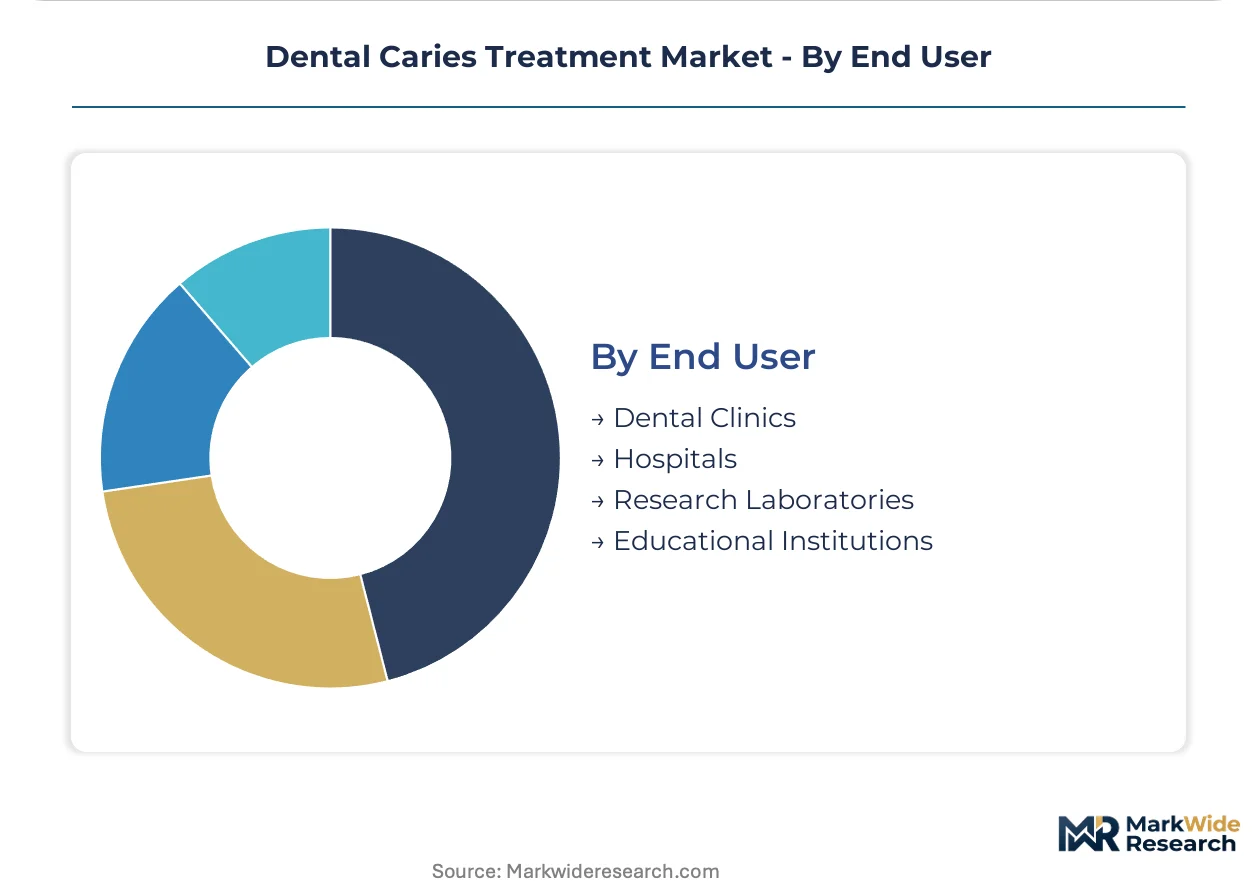
End User:
The end-user segmentation highlights the primary settings where dental caries treatments are delivered, reflecting varied operational scales and patient populations.
- Dental Clinics:These facilities, ranging from individual practices to large dental service organizations, represent the largest end-user segment for caries treatment. Consolidation of DSOs in North America is standardizing procurement for these clinics.
- Hospitals:Hospital dental departments primarily handle complex cases, emergency treatments, and patients with systemic health conditions requiring specialized care. These institutions often require advanced equipment and multidisciplinary teams.
- Research Laboratories:These facilities focus on developing new materials, diagnostic tools, and treatment methodologies for dental caries, driving future market innovation.
- Educational Institutions:Dental schools and teaching hospitals provide clinical training for future dentists and often offer treatment services to the public, contributing to overall procedure volume.
Dental clinics represent the largest service delivery channel, while hospitals provide specialized care for medically compromised patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between developed economies like Germany and emerging markets such as China. Developed nations exhibit higher per-procedure values due to advanced treatment modalities and robust insurance frameworks. Conversely, expanding dental infrastructure in developing regions drives volume growth, but with different pricing dynamics.
United States
High demand for aesthetic restorations and advanced materials drives market expansion in the United States. The FDA's stringent approval processes ensure product safety and efficacy for new dental devices and materials. Major dental supply clusters around cities like Chicago and Anaheim facilitate distribution and innovation for the North American market.
Germany
An aging demographic and strong public health initiatives underpin consistent demand for restorative procedures in Germany. Europe's Medical Device Regulation (MDR) significantly influences product development and market access for dental materials. The Rhine-Main region, with its strong industrial base, hosts numerous dental manufacturing and research facilities.
Japan
Japan's elderly population contributes to sustained demand for crowns and complex restorative treatments. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates dental products, emphasizing clinical evidence and quality. Tokyo's dense urban centers and surrounding prefectures represent significant hubs for dental clinics and material consumption.
China
Expanding dental infrastructure and a growing middle class are accelerating the adoption of modern caries treatment technologies in China. The NMPA's evolving regulatory framework standardizes product performance and market entry requirements for domestic and international manufacturers. The Yangtze River Delta region is witnessing rapid growth in dental service organizations and material distribution networks.
Dental Caries Treatment Market Key Industry Players
Comprehensive portfolio players and specialized materials science innovators split the market for dental caries treatments. This structure allows large entities to offer integrated solutions while niche players focus on specific material advancements. Competitive moves often involve strategic partnerships to expand geographic reach or M&A activities to consolidate product lines.
Within the comprehensive portfolio tier, Dentsply Sirona Inc. represents a significant force due to its broad product offerings and established distribution channels. 3M Company exemplifies innovation in materials science, particularly through its advanced adhesive and composite technologies. GC Corporation anchors the market for restorative materials like glass ionomers, sustaining a strong position through specialized product development.
| Leading Market Players |
|---|
| 3M Company |
| Dentsply Sirona Inc. |
| Coltene Group |
| Shofu Dental Corporation |
| Institut Straumann AG |
| Zimmer Biomet |
| GC Corporation |
| Septodont Holding S.A. |
| Acteon Group |
Cost & Logistics Intelligence
Under-utilized manufacturing capacity for traditional dental materials in established European markets drives competitive pricing strategies among suppliers. This capacity surplus influences procurement decisions for large dental service organizations across the region.
Pricing Analysis
Configured-to-order pricing for advanced digital dentistry solutions contrasts with standard per-unit transactional pricing for commodity restorative materials. The dominant pricing model for basic consumables is transactional, while specialized restorative materials often feature value-based pricing linked to clinical outcomes. Price differentiation stems from material quality, often tied to FDA or CE certification, and the level of customization for patient-specific digital restorations. Pricing softness for traditional materials reflects increased competition and the bulk purchasing power of dental service organizations; public health systems exhibit high price sensitivity, whereas private clinics in developed markets prioritize premium, aesthetically superior materials.
Supply Chain Analysis
Export-control regimes on specific chemical precursors for advanced composite resins limit their global flow, impacting manufacturing hubs. Geographic supply concentration for high-performance dental materials centers in Germany, the United States, and Japan, while basic chemical inputs often originate from China. The industry draws from polymer resins, inorganic fillers like silica, and specialized photoinitiators. A structural risk involves single-source vulnerability for certain proprietary monomers, while distribution runs through established dental distributors for individual practices and direct procurement for large dental service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental caries treatment market is experiencing a cyclical recovery, primarily driven by deferred patient care during economic downturns and the subsequent rebound in elective dental procedures. This rebound supports sustained demand for restorative materials and services.
For Market Incumbents: Entrench market share by investing in advanced R&D for regenerative therapies, countering the threat of breakthrough biomaterials. Consolidate distribution channels by offering integrated digital treatment platforms to large dental service organizations. This approach mitigates margin pressure from commoditized product segments and secures long-term partnerships.
For New Entrants and Emerging Players: Establish a beachhead in emerging markets across Southeast Asia, targeting underpenetrated rural and peri-urban areas. Focus on cost-effective, high-performing glass ionomer and resin ionomer materials for pediatric restorations. A direct-to-clinic sales model, leveraging digital outreach and training, offers a viable go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among dental software providers and integrated digital platform developers. The market exhibits long-term viability, driven by demographic shifts and continuous material science innovation. Target acquisition profiles include mid-sized manufacturers specializing in advanced composite resins or digital dentistry components. The signal to watch is the adoption rate of chairside CAD/CAM systems within consolidating dental service organizations.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Workflow Integration | Streamlines clinic operations, reduces chair time for patients, and improves restoration accuracy. |
| Advanced Biomaterial R&D | Develops regenerative options, displacing traditional restorative approaches and enhancing patient outcomes. |
| Emerging Market Expansion | Captures demand from growing middle-class populations in Southeast Asia and Latin America. |
| DSO Partnership Programs | Secures volume-based procurement contracts with large dental service organizations. |
| Regulatory Compliance Upgrades | Ensures market access for new products under stringent frameworks like Europe's MDR. |
Research Approach
Desk research of regulatory filings, academic publications, and industry association reports preceded structured interviews with dental clinicians, material scientists, and procurement managers from dental service organizations. This approach combined primary insights with secondary validation. Bottom-up data collection from material manufacturers and top-down market sizing from dental associations ensured comprehensive coverage.
Assumptions regarding consistent regulatory environments and stable economic growth were held fixed, while technological adoption rates varied across regions. The analytical framework modeled segmentation dimensions including product type, material, therapy approach, and end-user settings. Compound Annual Growth Rates were derived from historical trends and projected future demand, considering inputs like aging demographics and public health spending.
Sensitivities concentrate around unforeseen changes in dental insurance coverage and the pace of new material development. The forecasts reflect these underlying assumptions. Material shifts in global economic stability or major regulatory changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Supplies
Dental Preventive Supplies Market
Dental Supplies
Global Dental Suture Market
Dental Supplies
Endodontic Supplies Market
Dental Supplies
Fissure Sealants Market
Dental Supplies
Global Hotel Dental Kits Market
Dental Supplies
Orthodontic Supplies Market
Dental Supplies
Plaque Disclosing Market
Dental Supplies
Orthodontic Consumables Market
Dental Supplies
Dental Consumables Market