
 Dental Preventive Supplies Market | 2026-2036
Dental Preventive Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Preventive Supplies Market Intelligence
The divergence in R&D investment for novel bioactive materials versus sheer distribution scale is bifurcating the market. Large multinationals like 3M Company leverage deep material science portfolios to innovate in areas such as glass ionomers and fluoride-releasing technologies. Dentsply Sirona sustains its leadership position through a comprehensive product and equipment ecosystem targeted at dental professionals. In contrast, GC Corporation specializes in a focused range of professional-use consumables, building a strong brand reputation among dentists.
Dental preventive supplies encompass a range of products designed to inhibit the onset of oral diseases like caries and gingivitis. These items, from toothpastes with specific fluoride concentrations to professionally applied pit and fissure sealants, aim to maintain oral health and prevent costly restorative procedures. While toothbrushes and toothpaste represent the high-volume foundation of the market, the professional care application segment commands higher price points for specialized products. Distribution through pharmacies and supermarkets captures the mass market, while dedicated dental supply stores serve clinical end users.
Regulatory frameworks establish the guardrails for product safety and marketing claims. In the United States, the FDA oversees therapeutic products, while in Europe, items used in clinics may fall under the Medical Device Regulation (MDR). China's NMPA requires stringent registration for imported dental supplies. These regulations directly influence product formulation and labeling. Navigating the distinction between consumer wellness products and regulated medical devices remains a critical strategic challenge for manufacturers.
Market Dynamics
The central dynamic shaping the market is the bifurcation between high-volume, low-margin consumer goods and low-volume, high-margin professional products. This divide is driven by material science advancements that create a widening performance and cost gap between professionally applied therapeutic materials and mass-market oral hygiene items.
Growth Catalysts
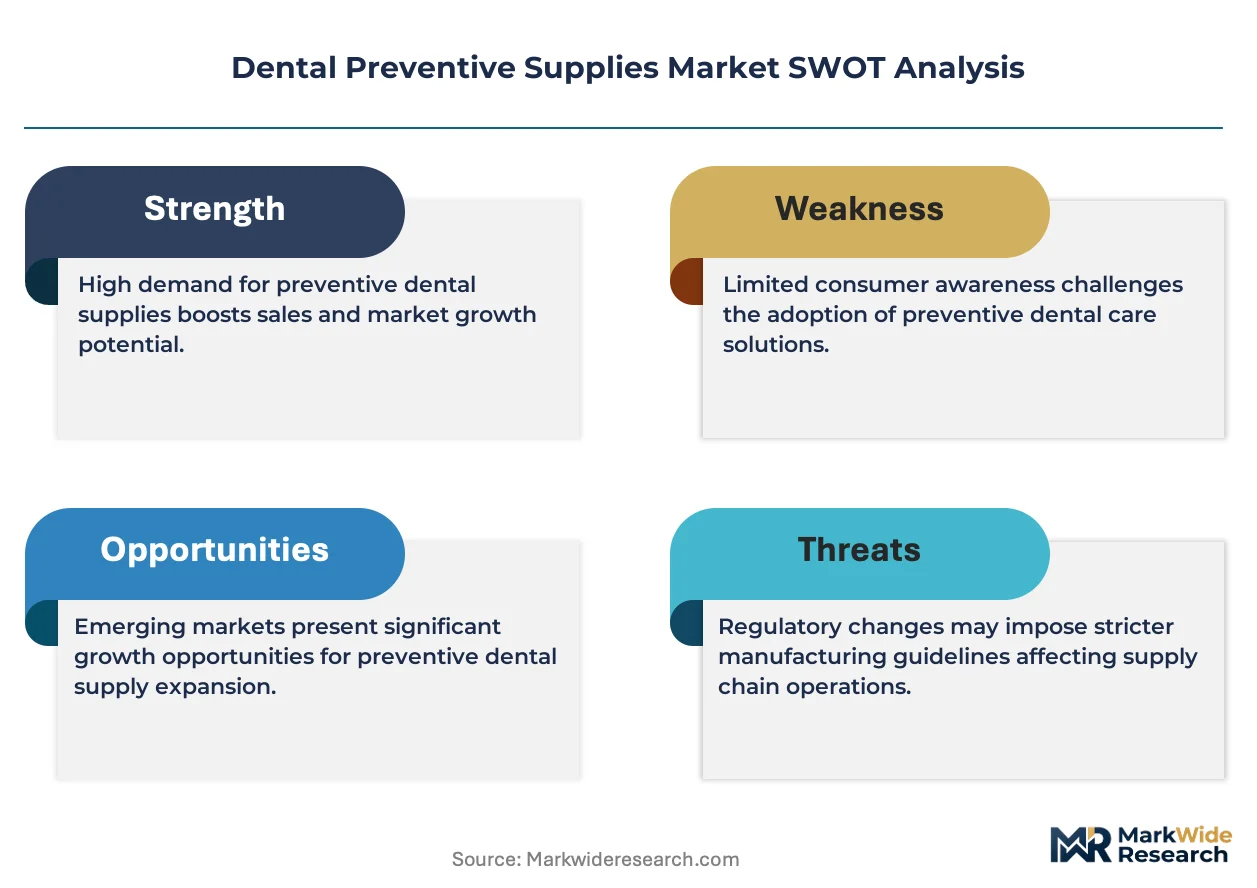
- Public Health Initiatives:Government-funded oral health programs, particularly in China, are expanding access to professional preventive care and subsidizing the use of products like fissure sealants in school-aged children.
- Bioactive Material Innovation:The development of new glass ionomers and resin composites that release fluoride, calcium, and phosphate ions is enhancing the therapeutic value of sealants and varnishes, driving adoption by clinicians.
- Rising Disposable Income:An expanding middle class in several Asian and Latin American countries is increasing per capita spending on both consumer oral care products and elective professional preventive treatments.
Market Restraints
- Regulatory Fragmentation:Divergent requirements from bodies like the FDA, the EU's MDR, and China's NMPA create significant compliance costs and extend time-to-market for manufacturers operating across multiple regions.
- Cost of Professional Care:The high out-of-pocket cost for professionally applied preventive treatments in markets without comprehensive dental insurance coverage limits uptake, especially for non-essential procedures.
- Efficacy of OTC Products:Advanced formulations in over-the-counter toothpastes and rinses, offering benefits like sensitivity reduction and whitening, can reduce consumer motivation to seek professional preventive services.
Strategic Opportunities
- Geriatric Dentistry:Developing and marketing products specifically for the elderly, such as high-fluoride varnishes for root caries and solutions for medication-induced dry mouth, addresses a large and underserved demographic.
- Teledentistry Integration:Creating preventive kits and monitoring tools compatible with teledentistry platforms allows for remote patient consultations and personalized home care regimens, expanding a clinic's reach.
- Emerging Market Penetration:Focusing on market entry and education in Southeast Asian nations, where dental infrastructure is improving and awareness of preventive care is nascent, offers long-term growth potential.
Industry Challenges
- Clinician Training and Education:Ensuring dental professionals are adequately trained on the application techniques for new, moisture-sensitive bioactive materials is critical for achieving optimal clinical outcomes and maintaining brand reputation.
- Supply Chain Complexity:Managing a global supply chain for specialized raw materials while navigating varied customs, import regulations, and registration requirements for finished goods remains a significant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Preventive Supplies Market |
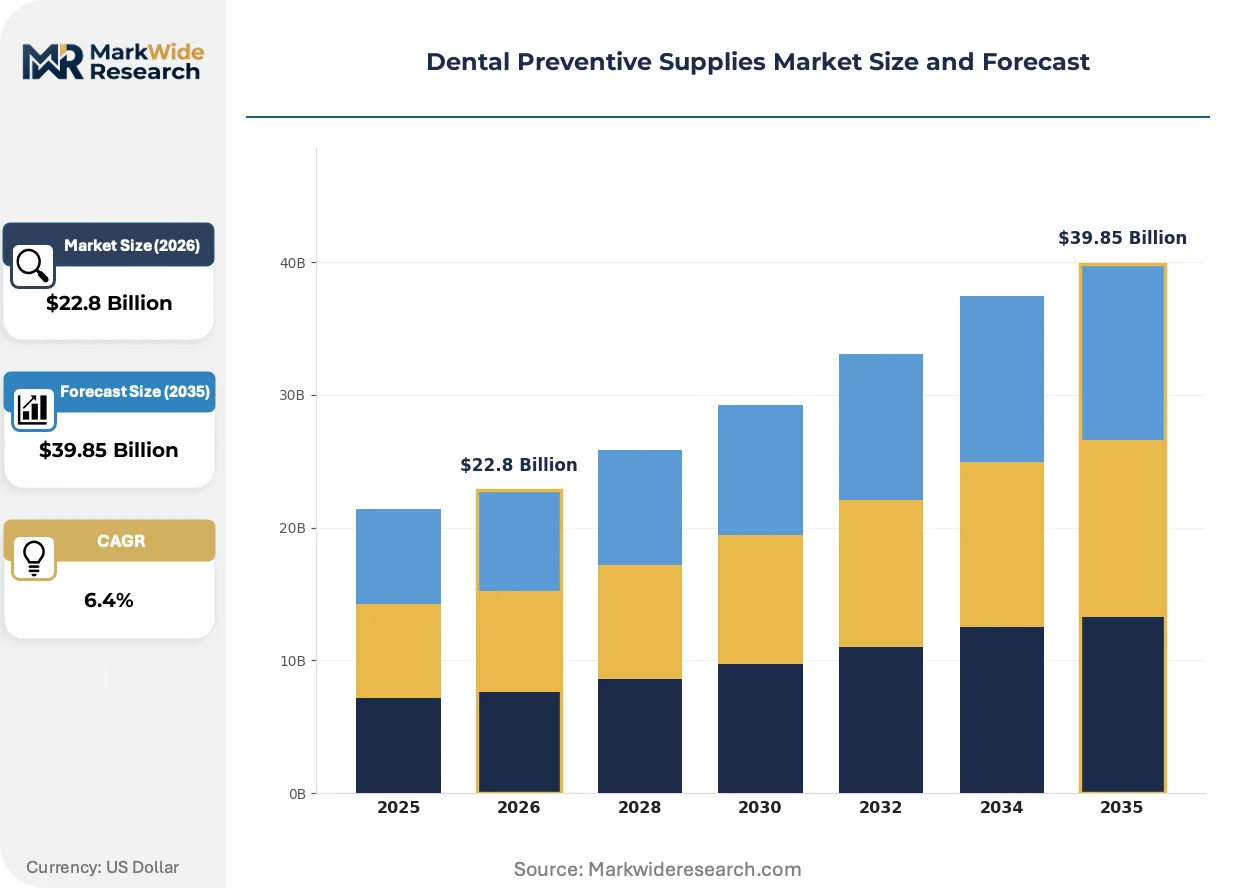
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothbrushes, Toothpaste, Mouthwash, Floss Application: Home Care, Professional Care, Institutional Use, Educational Programs End User: Dentists, Hospitals, Dental Clinics, Consumers Distribution Channel: Online Retail, Supermarkets, Pharmacies, Dental Supply Stores |
| Companies Covered | 3M Company, Dentsply Sirona, KaVo Kerr, Ivoclar Vivadent, Henry Schein, Young Innovations, GC Corporation, Colgate-Palmolive, Sunstar Suisse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Preventive Supplies Market Strategic Shifts & Innovations
Innovation in the dental preventive supplies market is defined by the convergence of advanced material science with more personalized care models. The evolution from passive, mechanical barriers to active, therapeutic agents is changing clinical protocols and patient outcomes.
Bioactive materials that interact with the tooth structure are gaining significant traction. These formulations, including glass ionomers and specific composites, release ions like fluoride and calcium to actively support remineralization and inhibit bacterial activity. This technology is displacing older, inert sealants and filling materials, particularly in pediatric dentistry where long-term tooth preservation is paramount.
Europe's Medical Device Regulation (MDR) is forcing a re-evaluation of product classification and clinical data requirements. The regulation elevates many professional-use items, such as certain therapeutic varnishes, to a higher-risk class, demanding more rigorous evidence of safety and efficacy. Consequently, manufacturers targeting the European market are increasing investment in clinical trials and post-market surveillance systems to ensure compliance.
Dental practices are beginning to favor direct-to-practitioner e-commerce channels for replenishing consumable supplies over traditional distributor relationships. This shift allows for just-in-time inventory management and often provides more transparent pricing, disrupting the business model of regional dental supply companies. This purchasing behavior is most advanced in North America, where practice management software frequently integrates with online supplier portals.
Dental Preventive Supplies Market Segmentation
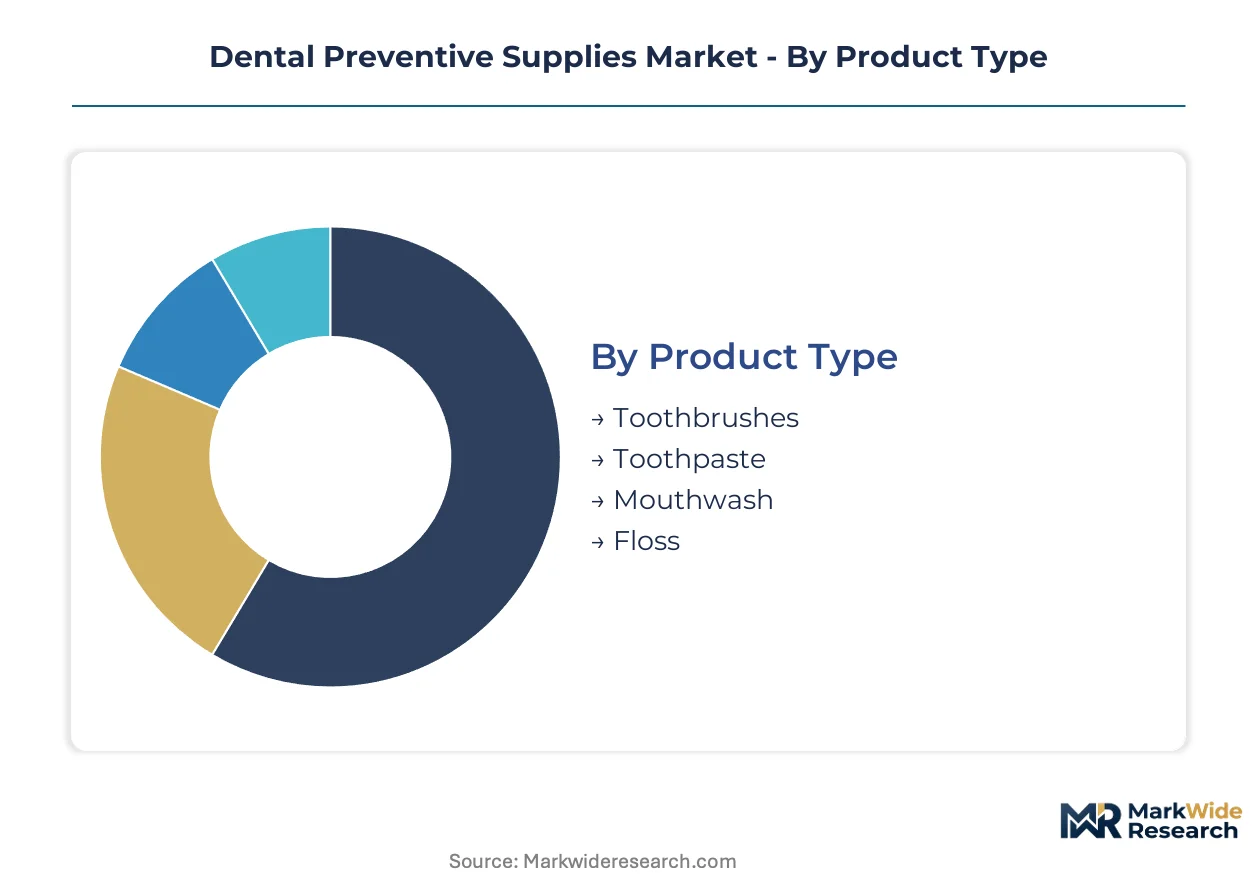
The dental preventive supplies market exhibits distinct segmentation across product types, applications, end users, and distribution channels. Understanding these divisions reveals the varied commercial strategies and operational complexities manufacturers encounter. This segmentation highlights the bifurcation between high-volume consumer goods and specialized professional products.
Product Type:
The product type segmentation directly influences the primary distribution channels, with mass-market items flowing through retail and specialized products often requiring professional recommendation. These categories range from daily oral hygiene essentials to more targeted therapeutic formulations.
- Toothpaste:Formulations often include specific fluoride concentrations, abrasive agents, and desensitizing compounds to address various oral health concerns. Demand for advanced formulations is concentrating in urban areas of China, driven by public health campaigns promoting fluoride use and rising consumer awareness.
- Toothbrushes:These include manual, electric, and sonic varieties, designed for effective plaque removal and gum stimulation. Global consumer spending on electric toothbrushes is increasing in developed markets like the United States, reflecting a preference for technology-enhanced oral care solutions.
- Mouthwash:This segment includes antiseptic, cosmetic, and therapeutic rinses, often containing fluoride or chlorhexidine for bacterial control.
- Floss:Dental floss, including waxed, unwaxed, and specialized interdental cleaners, removes plaque and food particles from between teeth.
By volume, toothpaste leads the product type category. By growth pace, specialized therapeutic mouthwashes are ahead.
Application:
Application segments are differentiated by the margin profiles they command, with professional services typically yielding higher value per unit compared to mass-market consumer applications. This distinction impacts manufacturing scale and marketing strategies for suppliers.
- Professional Care:This segment includes treatments like fluoride varnishes, pit and fissure sealants, and desensitizing agents applied by dental professionals. Demand is strong in European clinics, where regulatory frameworks like MDR emphasize evidence-based treatments and patient safety for advanced materials.
- Home Care:Products for daily personal use, such as over-the-counter toothpastes, mouthwashes, and toothbrushes, form this high-volume segment. Consumer spending on advanced home care products is increasing in Latin American countries, driven by rising disposable incomes.
- Institutional Use:This involves bulk purchasing of supplies for settings like hospitals, nursing homes, and military bases for general oral hygiene.
- Educational Programs:This application focuses on distributing basic oral hygiene tools and materials for public health initiatives and school-based prevention programs.
The professional care segment generates higher average revenue per application. Home care applications represent the largest volume of units consumed annually.
End User:
End user categories reflect distinct purchasing behaviors and product requirements, ranging from individual consumer choices to procurement processes of large healthcare institutions. Manufacturers tailor product portfolios to meet these specific user needs.
- Consumers:Individual purchasers of oral hygiene products for personal use, primarily through retail channels. The expanding middle class in Southeast Asian nations is driving increased per capita spending on consumer oral care products, particularly in urban centers.
- Dentists:Professional practitioners who utilize specialized preventive materials and instruments in their clinical practice. Their purchasing decisions are influenced by clinical efficacy and regulatory compliance, particularly for bioactive materials in the United States.
- Hospitals:These institutions procure dental preventive supplies for inpatient care, emergency dental services, and specialized oral health departments.
- Dental Clinics:Private and group practices represent a significant end-user segment for professional-grade consumables and equipment.
Consumers represent the broadest end-user base by sheer numbers. Dentists drive demand for high-value, specialized preventive technologies.
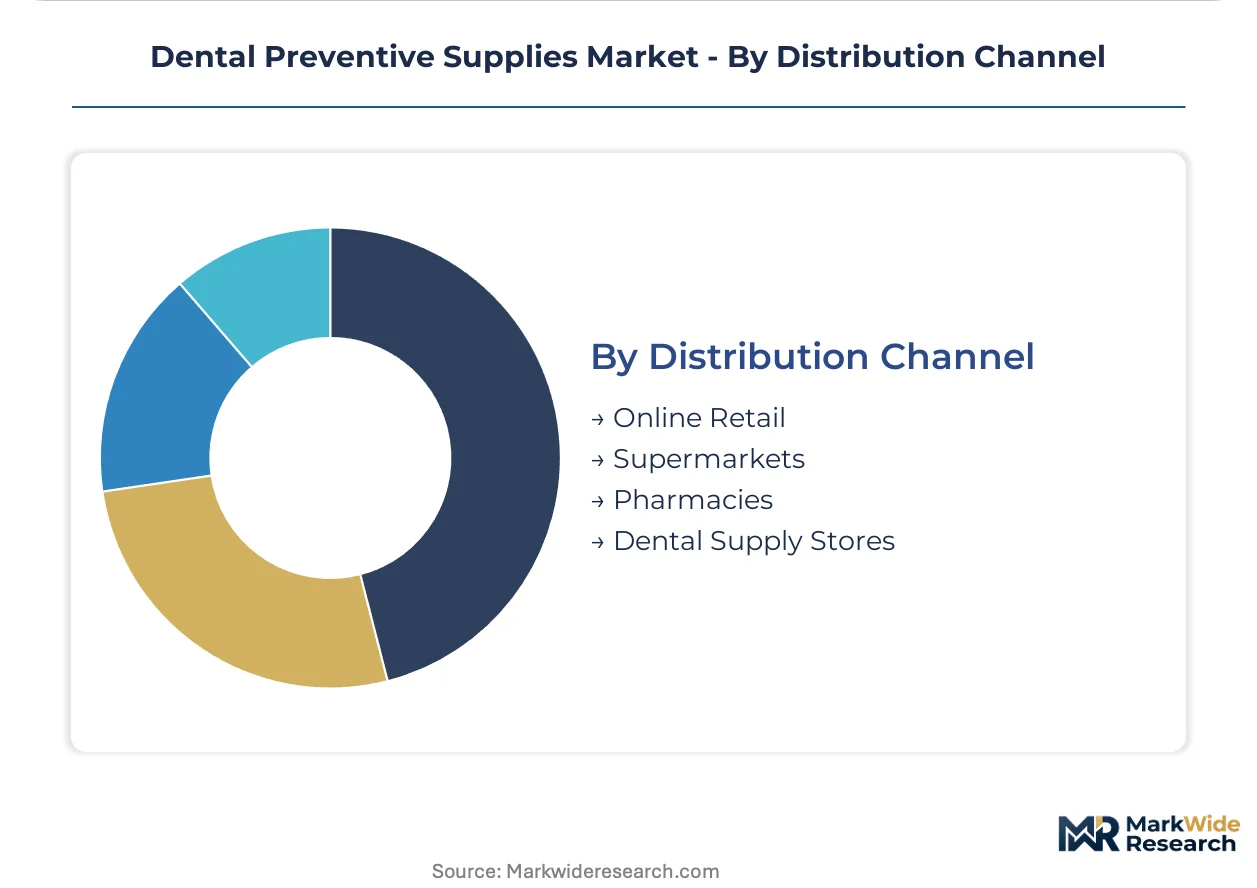
Distribution Channel:
The distribution channel landscape is shaped by the logistical complexity and regulatory requirements associated with different product types. Mass-market products require extensive retail networks, while professional items rely on specialized supply chains.
- Dental Supply Stores:These specialized outlets cater to dental professionals, offering a curated range of high-quality, regulated preventive materials and equipment. Procurement through these channels is prominent in North America, where practices increasingly use e-commerce for inventory management.
- Supermarkets:Mass consumer oral hygiene products like toothpastes and toothbrushes are widely available through these high-volume retail environments. This channel is crucial for reaching the expanding middle-class consumer base in emerging economies like India.
- Online Retail:E-commerce platforms offer convenience and price comparison for both consumer and some professional dental preventive supplies.
- Pharmacies:These establishments distribute both over-the-counter oral care products and some professional-grade items, often with pharmacist consultation.
Supermarkets account for the largest volume of consumer product sales. Online retail is gaining share fastest as a direct-to-consumer and direct-to-practitioner channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry is evident, with higher margins in developed markets like the United States contrasting with volume-driven strategies in emerging economies such as China. This divergence shapes investment priorities and product portfolio development for manufacturers across different geographies.
China
China's demand for preventive supplies is concentrating due to public health initiatives promoting oral hygiene. The NMPA requires stringent registration for imported dental supplies, influencing local manufacturing. Major urban centers like Shanghai and Beijing drive consumption with an expanding middle class increasing per capita spending.
United States
The United States market sees demand for advanced professional care applications, driven by clinician adoption of bioactive materials. The FDA oversees therapeutic products, ensuring rigorous safety and efficacy standards for new formulations. Dental supply stores in regions like California and New York facilitate procurement for specialized practices.
Germany
Germany exhibits strong demand for high-value professional preventive treatments within European clinics. Europe's Medical Device Regulation (MDR) elevates many professional-use items to higher-risk classes, mandating robust clinical data. The Rhine-Main region, with its dense network of dental practices, shows concentrated procurement of advanced materials.
Brazil
Brazil's market for home care products is expanding, propelled by rising disposable incomes and consumer awareness. ANVISA regulations govern product safety and efficacy, shaping the availability of both OTC and professional items. São Paulo and Rio de Janeiro lead consumer spending on advanced oral hygiene solutions.
Dental Preventive Supplies Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the dental preventive supplies market. The industry structure is tiered, with large multinational corporations coexisting with specialized regional manufacturers. Strategic archetypes include material science innovators and comprehensive product ecosystem providers. Companies engage in portfolio diversification and strategic partnerships to expand their market reach.
Large multinationals like 3M Company exemplify material science innovation, leveraging extensive R&D to develop advanced glass ionomers and fluoride-releasing technologies. These companies often possess deep intellectual property portfolios in biocompatible materials. Dentsply Sirona, a comprehensive product and equipment ecosystem provider, sustains its leadership through a broad offering for dental professionals, integrating equipment and consumables. GC Corporation, a Japan-based entity specializing in a focused range of professional-use consumables, builds a strong brand reputation among dentists through targeted product development and clinician training. These players collectively shape market dynamics through their varied strategic approaches.
| Leading Market Players |
|---|
| 3M Company |
| Dentsply Sirona |
| KaVo Kerr |
| Ivoclar Vivadent |
| Henry Schein |
| Young Innovations |
| GC Corporation |
| Colgate-Palmolive |
| Sunstar Suisse |
| Others |
Cost & Logistics Intelligence
Europe's Medical Device Regulation (MDR) gates the supply qualification and price differentiation for advanced dental preventive materials. This stringent framework ensures only compliant products reach the market, influencing both manufacturing costs and end-user pricing.
Pricing Analysis
Configured-to-order pricing for specialized professional products contrasts with standard pricing for mass-market consumer items. The dominant pricing model remains per-unit transactional, reflecting diverse product types. Price differentiation stems from material science innovation and regulatory compliance, particularly for bioactive compounds. Pricing softness affects consumer goods due to intense competition and the perceived efficacy of over-the-counter alternatives. Dentists purchasing specialized materials exhibit lower price sensitivity compared to individual consumers buying daily oral hygiene products.
Supply Chain Analysis
Logistics chokepoints for specialized raw materials, such as specific polymers and fluoride compounds, affect global supply. Geographic supply concentration for manufacturing centers on China and Germany, with the United States leading in advanced material R&D. The industry faces structural risk from regulatory fragmentation, which complicates cross-border movement of goods. Distribution runs through specialized dental supply stores for professionals and high-volume supermarkets for consumer products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market exhibits a buyer-power shift, as dental clinics increasingly consolidate procurement through direct-to-practitioner e-commerce platforms.
For Market Incumbents:
Shield core professional care segments from commoditization by continuously investing in material science. Deepen intellectual property portfolios in bioactive technologies, such as advanced glass ionomers. Strengthen direct-to-practitioner e-commerce channels to counter traditional distributor erosion. This strategy mitigates the threat from rapidly advancing over-the-counter products.
For New Entrants and Emerging Players:
Teledentistry integration represents a service-layer gap where incumbents under-serve. Target geriatric dentistry and nascent Southeast Asian markets as white-space opportunities. The home care segment compatible with remote monitoring platforms is most penetrable. A digital-first go-to-market angle focusing on personalized preventive regimens can capture early adopters.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upwards across bioactive material research and development. The long-term viability of companies innovating in therapeutic materials appears strong over the next five to ten years. Acquisition targets should include specialized material science firms with proprietary bioactive compounds. A key signal to watch is the pace of regulatory approvals for novel preventive technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioactive Material R&D | Advances therapeutic value of sealants and varnishes, driving adoption by clinicians. |
| Direct-to-Practitioner E-commerce | Streamlines procurement for dental clinics, improving inventory management and pricing transparency. |
| Geriatric Product Development | Addresses specific oral health needs of an underserved elderly demographic, expanding market reach. |
| Teledentistry Platform Integration | Enables remote patient consultations and personalized home care regimens, enhancing clinic accessibility. |
| Emerging Market Entry | Captures long-term growth potential in Southeast Asian nations with nascent preventive care awareness. |
Research Approach
A standing panel of dental professionals, material scientists, supply chain managers, and public health officials provided ongoing calibration for market trends. Primary interviews supplemented with secondary validation from FDA filings, NMPA registrations, EU MDR guidelines, and industry association reports informed the analysis. Bottom-up and top-down triangulation ensured data consistency.
Consistency checks against external benchmarks validated the quantitative outputs across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, distribution channel, and material composition. Compound annual growth rates were derived through a comprehensive regression analysis incorporating historical data and projected market drivers. Dental procedure volumes and per capita oral care spending served as key forecast inputs.
Underlying assumptions cover regulatory stability, material science breakthroughs, and public health funding, with deviation risk concentrated in unforeseen policy changes or economic downturns. Practitioners should keep alternative scenarios live as regulatory frameworks and consumer spending patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Supplies
Endodontic Supplies Market
Dental Supplies
Orthodontic Supplies Market
Dental Supplies
Global Dental Suture Market
Dental Supplies
Dental Caries Treatment Market
Dental Supplies
Plaque Disclosing Market
Dental Supplies
Dental Consumables Market
Dental Supplies
Fissure Sealants Market
Dental Supplies
Orthodontic Consumables Market
Dental Supplies
Global Hotel Dental Kits Market