
 Duloxetine Intermediate and Atorvastatin Intermediates Market | 2026-2036
Duloxetine Intermediate and Atorvastatin Intermediates Market Size, Share, and Industry Trends Forecast 2026-2036
Duloxetine Intermediate and Atorvastatin Intermediates Market Analysis
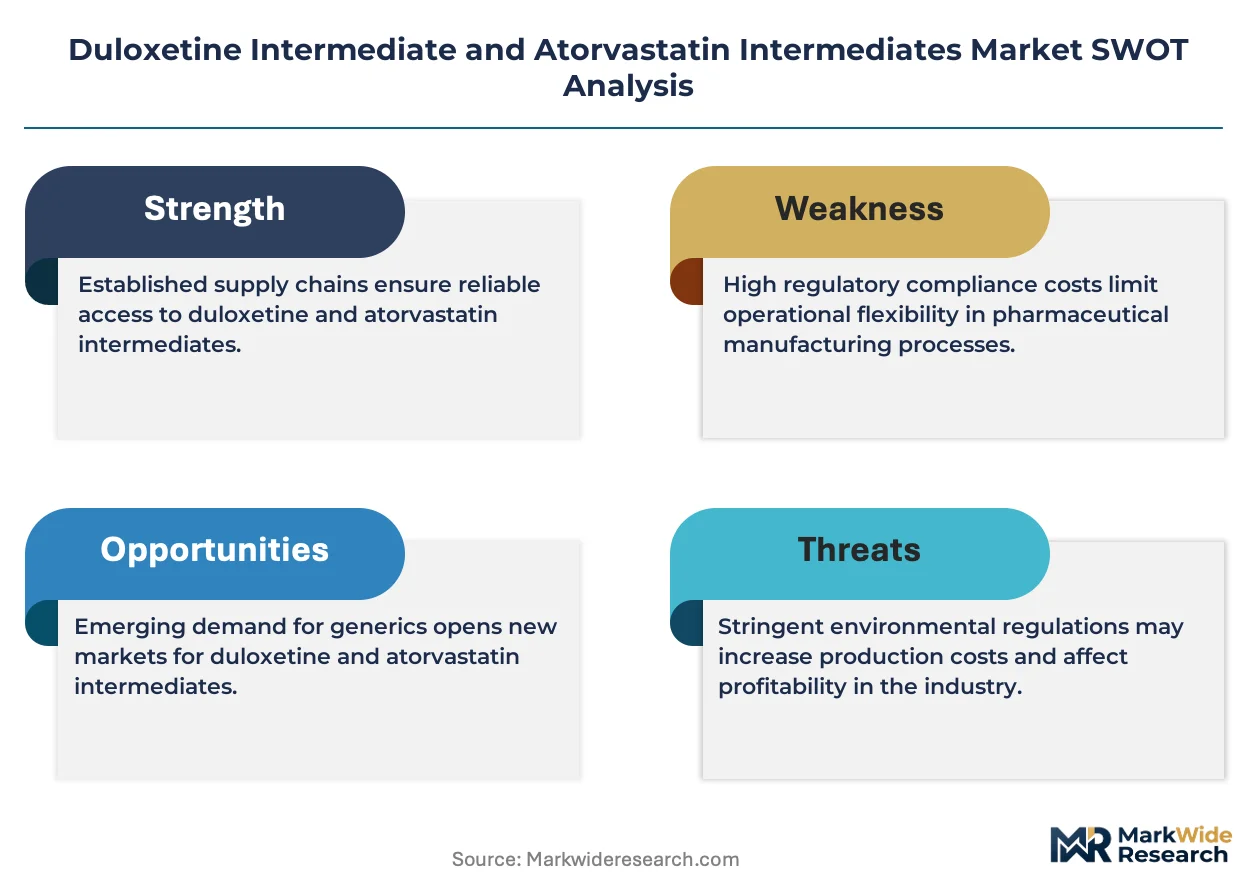
Continuous flow chemistry is tilting cost structures in chiral intermediate manufacturing toward tighter process control and higher yields. Teva Pharmaceutical Industries leverages vertical integration across its generic portfolio to secure captive intermediate supply. Sun Pharmaceutical Industries anchors South Asian production networks through backward integration into duloxetine precursor synthesis. Hubei Shunying Pharmaceutical competes on manufacturing scale for atorvastatin side-chain intermediates serving statin producers.
Duloxetine intermediate and atorvastatin intermediates comprise specialized chemical building blocks—typically chiral alcohols, acetate esters, and pyrrole derivatives—synthesized through catalytic hydrogenation or enzymatic resolution with specified enantiomeric excess exceeding 99.5%, serving as constrained inputs for antidepressant and lipid-lowering drug production. Atorvastatin intermediates dominate current value flows due to persistent statin volume requirements across cardiovascular therapy protocols, while duloxetine intermediates occupy a narrower but higher-margin niche tied to CNS indication expansion. Crystalline form factors command premium positioning over amorphous powders because particle size distribution directly impacts downstream formulation dissolution profiles.
FDA Current Good Manufacturing Practice enforcement and EMA REACH chemical safety registration shape batch release protocols and supplier qualification timelines for intermediate exporters. India's CDSCO and China's NMPA impose parallel bioequivalence-linked impurity thresholds that constrain which synthesis routes achieve commercial viability. Stakeholders must monitor evolving pharmacopoeial monograph revisions that could disqualify legacy manufacturing processes without warning.
Market Dynamics
Continuous flow chemistry is compressing batch cycle times and tightening impurity profiles across chiral intermediate manufacturing, forcing legacy batch-reactor operators into capital-intensive retrofits or contract manufacturing exits.
Growth Catalysts
- EMA REACH registration mandates:Chemical safety dossiers for atorvastatin side-chain intermediates now require full toxicological profiling, filtering out subscale suppliers and consolidating volume with qualified manufacturers.
- Cardiovascular protocol persistence:Statin therapy remains embedded in post-acute coronary syndrome guidelines across hospital formularies, sustaining offtake for (4R-cis)-6-[2-[2-(4-fluorophenyl)-5-(1-methylethyl)-3-phenyl-4-[(phenylamino)carbonyl]-1H-pyrrol-1-yl]ethyl]-2,2-dimethyl-1,3-dioxane-4-acetate intermediates.
- Enzymatic resolution scale-up:Lipase-catalyzed kinetic resolution of duloxetine precursors now achieves 99.8% enantiomeric excess at multi-tonne scale, displacing chiral chromatography for cost-sensitive generic producers.
Market Restraints
- Palladium catalyst cost volatility:Catalytic hydrogenation steps for pyrrole ring construction face margin compression when palladium prices spike, particularly affecting small-batch custom synthesis houses.
- API manufacturer concentration:Contract manufacturing organization procurement concentrates among fifteen dominant active pharmaceutical ingredient producers, creating price-taker dynamics for intermediate specialists without backward integration.
- Chiral pool depletion:Natural starting material availability for (S)-3-(dimethylamino)-1-(2-thienyl)propan-1-ol synthesis is tightening as plant-derived feedstock harvests face climate variability.
Strategic Opportunities
- India PLI scheme for bulk drugs:Production-linked incentives for critical starting materials and drug intermediates subsidize greenfield duloxetine precursor capacity with 20% financial assistance on committed investments.
- Biocatalytic cascade integration:Coupling transaminases with alcohol dehydrogenases enables one-pot conversion of prochiral ketones to chiral amines, collapsing multi-step synthetic routes for CNS-targeted intermediates.
- Direct-to-formulator distribution:Bypassing traditional merchant chemical distributors, intermediate producers are building dedicated logistics lanes to generic finished-dosage manufacturers in Gujarat and Telangana.
Industry Challenges
- Chiral chromatography specialist scarcity:Analytical method development for enantiomeric excess verification requires rare expertise in supercritical fluid chromatography, extending supplier qualification timelines.
- Legacy reactor retrofit capex:Converting stainless-steel batch vessels to corrosion-resistant Hastelloy configurations for acidic duloxetine intermediate steps demands capital commitments exceeding smaller manufacturers' balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duloxetine Intermediate and Atorvastatin Intermediates Market |
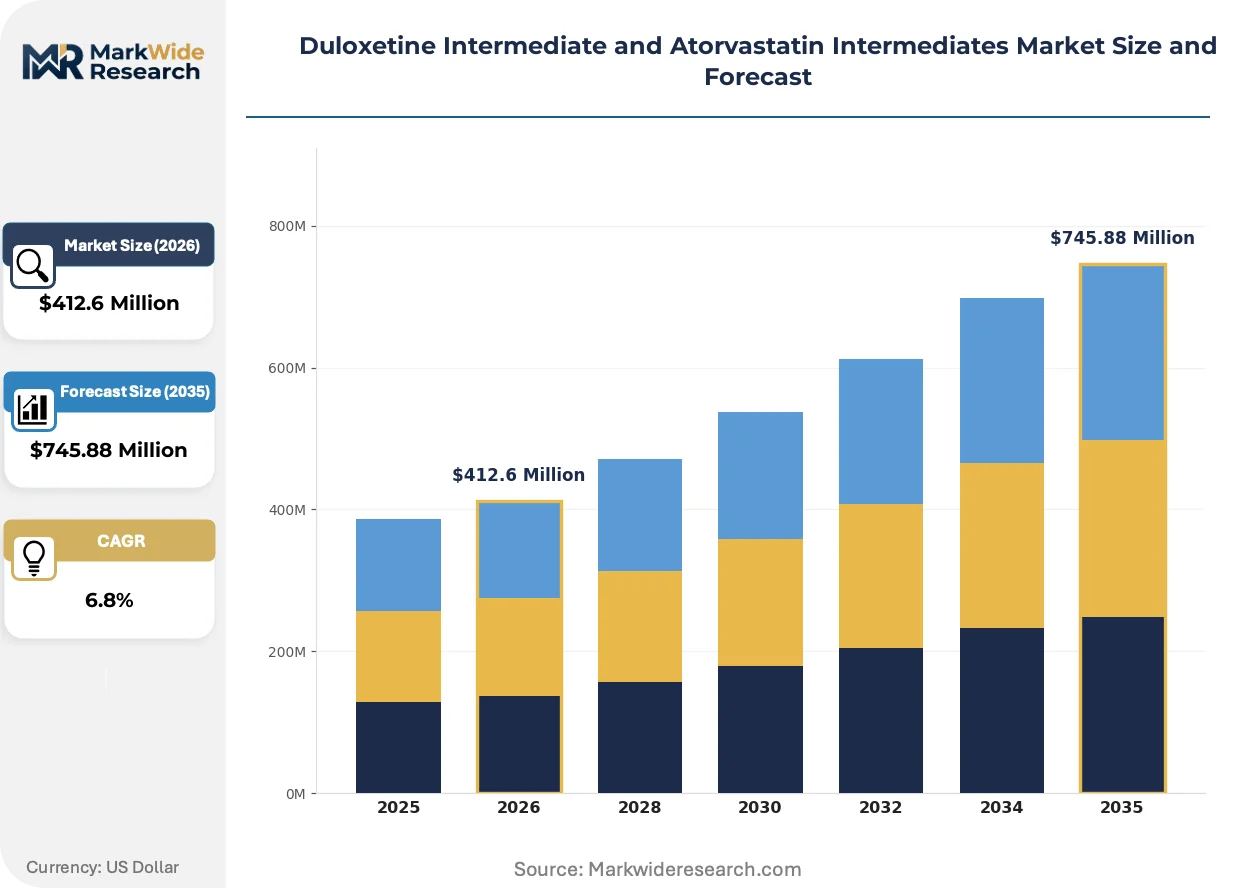
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Duloxetine Intermediates, Atorvastatin Intermediates, Active Pharmaceutical Ingredients, Custom Synthesis Form: Solid, Liquid, Powder, Crystalline Application: Pharmaceutical Production, Research and Development, Drug Formulation, Quality Assurance End User: Pharmaceutical Companies, Contract Research Organizations, Academic Institutions, Laboratories |
| Companies Covered | Pfizer, Novartis, Teva Pharmaceutical Industries, Boehringer Ingelheim, AstraZeneca, Sun Pharmaceutical Industries, Hubei Shunying Pharmaceutical, Jiangsu Lianhuan Pharmaceutical, Zhejiang Jiuzhou Pharmaceutical Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duloxetine Intermediate and Atorvastatin Intermediates Market Emerging Trajectories
Process intensification and regulatory data requirements are converging to reshape how chiral intermediates are manufactured, tested, and delivered to pharmaceutical customers.
Biocatalytic process development is hybridizing traditional chemical synthesis with enzyme engineering platforms. Contract manufacturing organizations in Hyderabad and Shanghai are deploying directed evolution pipelines to tailor transaminases for specific duloxetine precursor substrates. This convergence is collapsing development timelines for new synthetic routes while raising barriers for manufacturers lacking in-house molecular biology capabilities.
FDA Current Good Manufacturing Practice enforcement for starting materials has tightened documentation requirements for supplier change notifications. Drug master file submissions now demand full supply chain mapping back to raw material petrochemical sources. Generic atorvastatin producers are responding by qualifying dual-source intermediate suppliers to mitigate single-point-of-failure risks during facility inspections.
Formulator-led consortium purchasing is consolidating procurement volumes previously fragmented across individual generic manufacturers. Hospital group purchasing organizations in the United States are now negotiating directly with Indian intermediate producers for statin building blocks, disintermediating traditional merchant distributors. This channel compression is most visible in cardiovascular therapy supply chains where volume predictability enables long-term offtake agreements.
Duloxetine Intermediate and Atorvastatin Intermediates Market Segmentation
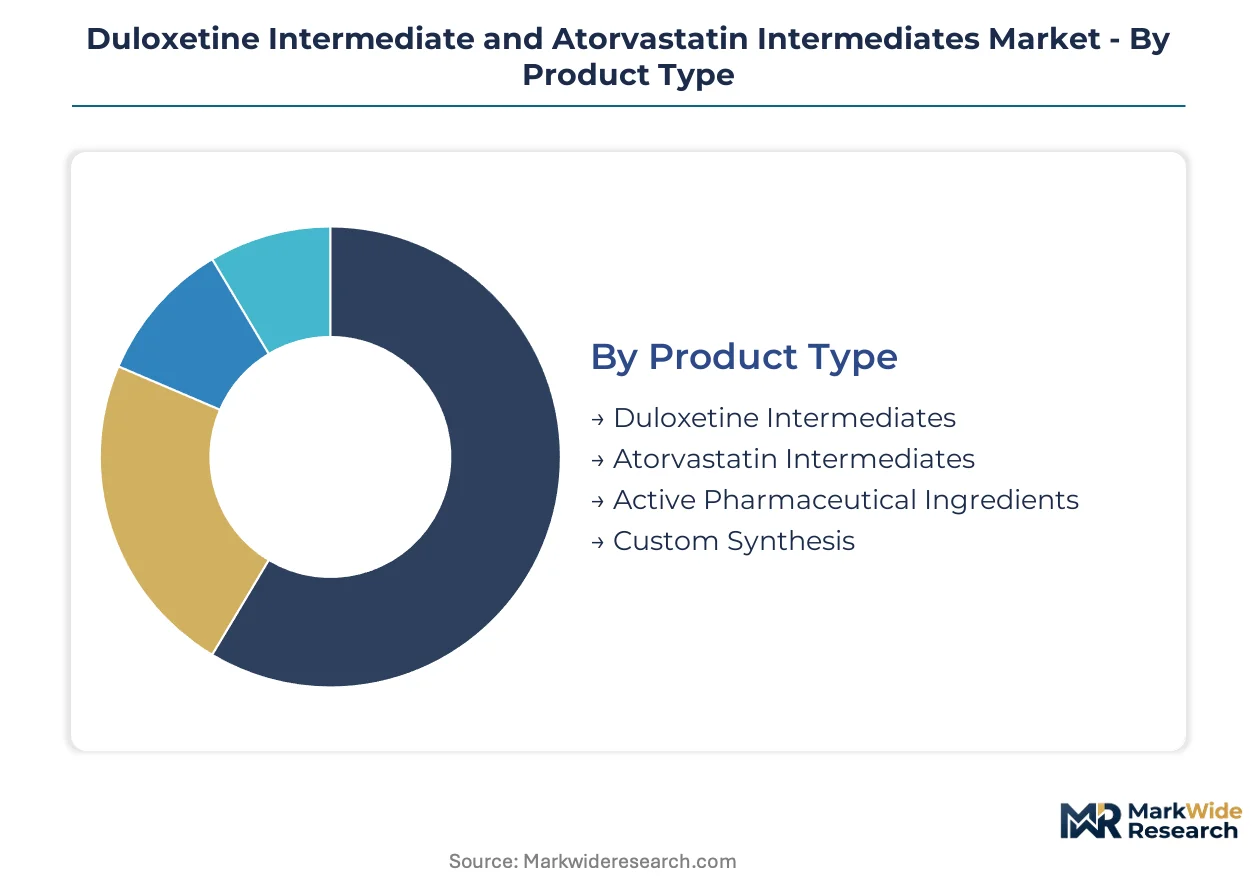
Chiral intermediate procurement patterns diverge sharply across product chemistry, physical form, and customer sophistication. Understanding these splits reveals where margin pools concentrate and which specifications command premium positioning.
Product Type:
Demand intensity tracks directly to downstream drug volume and synthesis complexity.
- Atorvastatin Intermediates:Pyrrole-derived building blocks with specified stereochemistry serve statin API manufacturers running continuous hydrogenation trains. Volume concentrates with Indian producers supplying generic finished-dosage makers in Gujarat and Telangana.
- Duloxetine Intermediates:(S)-3-(dimethylamino)-1-(2-thienyl)propan-1-ol and acetate ester variants require 99.5%+ enantiomeric excess, constraining qualified supplier pools to enzymatic resolution specialists. CDSCO bioequivalence-linked impurity thresholds filter out legacy manufacturers lacking biocatalytic capabilities.
- Active Pharmaceutical Ingredients:Penultimate-stage molecules approaching drug substance status face tightened FDA starting material documentation requirements.
- Custom Synthesis:Project-based engagements for patent-expired route redesign or novel salt form exploration.
The dominant share belongs to atorvastatin intermediates, while duloxetine intermediates is closing the gap fastest.
Form:
Physical state determines logistics economics and downstream processing compatibility.
- Crystalline:Defined particle size distribution enables direct compression into tablet formulations without micronization. FDA dissolution profile requirements favor crystalline inputs for bioequivalence submissions.
- Powder:Amorphous or partially crystalline grades suit wet granulation processes where dissolution rate modulation is required.
- Solid:Bulk crystalline or powder aggregates shipped in drum quantities for high-volume statin production.
- Liquid:Solution-phase intermediates for telescoped synthesis sequences avoiding isolation steps.
Crystalline grades capture the value premium, though powder forms are expanding most quickly in cost-sensitive generic markets.
Application:
Regulatory stringency and batch scale separate commercial manufacturing from exploratory use.
- Pharmaceutical Production:Multi-tonne campaigns for approved drug substances with validated analytical methods and supplier qualification dossiers. EMA REACH registration mandates now require full toxicological profiling for atorvastatin side-chain inputs.
- Drug Formulation:Salt selection and polymorph screening for bioavailability optimization.
- Quality Assurance:Reference standard preparation and impurity characterization.
- Research and Development:Early-route scouting with minimal regulatory documentation.
Pharmaceutical production absorbs the majority of volume, while drug formulation is gaining share fastest as complex generic filings multiply.
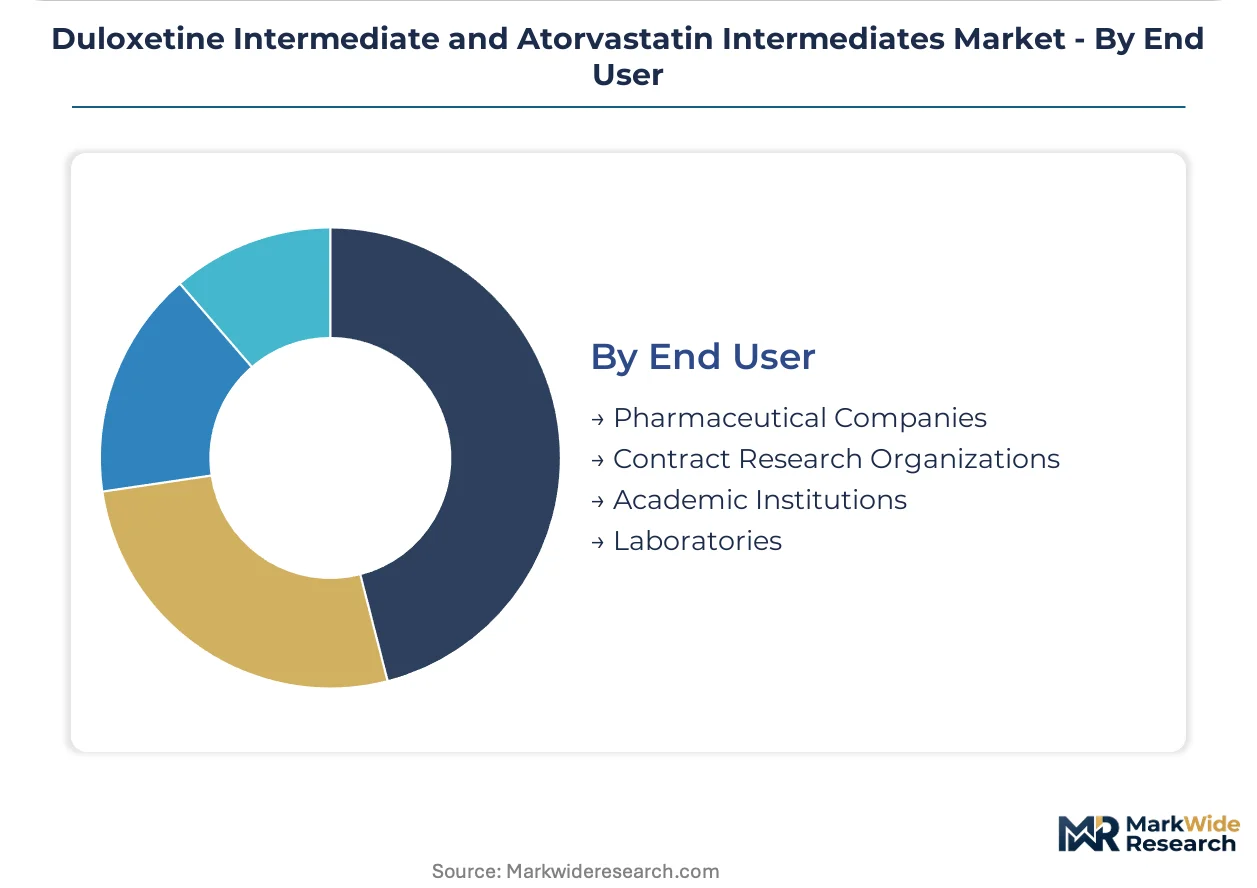
End User:
Procurement sophistication and volume commitment shape supplier relationship structures.
- Pharmaceutical Companies:Vertically integrated API manufacturers and generic finished-dosage producers with dedicated intermediate sourcing teams. Sun Pharmaceutical Industries anchors South Asian production networks through backward integration into duloxetine precursor synthesis.
- Contract Research Organizations:Project-based procurement for route development and regulatory submission support.
- Academic Institutions:Small-scale purchases for methodology papers and graduate training.
- Laboratories:Analytical reference material and method development quantities.
Pharmaceutical companies command the largest procurement volumes, while contract research organizations are climbing the fastest as outsourcing of early-stage development expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports duloxetine and atorvastatin intermediates to generic finished-dosage manufacturers across North America and Europe, while China supplies atorvastatin side-chain building blocks to Indian API producers running continuous hydrogenation trains.
India
Hyderabad and Ahmedabad clusters house enzymatic resolution specialists serving Teva Pharmaceutical Industries and Sun Pharmaceutical Industries with 99.8% enantiomeric excess duloxetine precursors. CDSCO bioequivalence-linked impurity thresholds filter out legacy manufacturers lacking biocatalytic capabilities. Gujarat's Kutch district hosts new greenfield capacity subsidized under the PLI scheme for bulk drugs with 20% financial assistance on committed investments.
China
Hubei province manufacturers dominate atorvastatin side-chain intermediate output for statin API producers in Zhejiang and Jiangsu. NMPA registration mandates now require full supply chain mapping back to raw material petrochemical sources for drug master file submissions. The Yangtze River Delta concentration around Shanghai supports telescoped synthesis sequences for pyrrole-derived building blocks.
United States
Hospital group purchasing organizations negotiate directly with Indian intermediate producers for statin building blocks, disintermediating traditional merchant distributors. FDA Current Good Manufacturing Practice enforcement for starting materials tightened documentation requirements for supplier change notifications. New Jersey and North Carolina clusters focus on analytical reference standard preparation and impurity characterization for quality assurance applications.
Germany
Specialty chemical distributors in Frankfurt and Ludwigshafen qualify dual-source intermediate suppliers to mitigate single-point-of-failure risks during facility inspections. EMA REACH registration mandates require full toxicological profiling for atorvastatin side-chain inputs, filtering out subscale suppliers. Bavaria-based contract research organizations deploy directed evolution pipelines for transaminase tailoring.
Switzerland
Swissmedic oversight shapes batch release protocols for chiral intermediates entering European formulation networks. Basel's pharmaceutical corridor concentrates on penultimate-stage molecules approaching drug substance status with tightened documentation requirements. Geneva-based logistics providers build dedicated lanes bypassing traditional merchant chemical distributors for direct-to-formulator distribution.
Duloxetine Intermediate and Atorvastatin Intermediates Market Vendor Landscape
On the supply side, the industry is consolidating around enzymatic resolution specialists and continuous flow chemistry operators while legacy batch-reactor manufacturers face capital-intensive retrofits or contract manufacturing exits. Three strategic archetypes dominate: vertically integrated generic pharmaceutical companies with captive intermediate supply, dedicated Chinese manufacturers competing on manufacturing scale for statin building blocks, and Indian specialists leveraging PLI-subsidized greenfield capacity for CNS-targeted precursors. M&A activity concentrates on acquiring biocatalytic capabilities, while capacity expansion focuses on corrosion-resistant Hastelloy configurations for acidic synthesis steps.
Among the named participants, Teva Pharmaceutical Industries and Sun Pharmaceutical Industries exemplify the vertically integrated archetype with backward integration into precursor synthesis, while Hubei Shunying Pharmaceutical occupies a position within the scale-driven Chinese manufacturer tier. Zhejiang Jiuzhou Pharmaceutical Co., Ltd and Jiangsu Lianhuan Pharmaceutical represent regional specialists serving domestic API networks. Pfizer, Novartis, AstraZeneca, and Boehringer Ingelheim sit within the diversified pharmaceutical conglomerate category with selective intermediate sourcing strategies rather than dedicated production focus.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| Teva Pharmaceutical Industries |
| Boehringer Ingelheim |
| AstraZeneca |
| Sun Pharmaceutical Industries |
| Hubei Shunying Pharmaceutical |
| Jiangsu Lianhuan Pharmaceutical |
| Zhejiang Jiuzhou Pharmaceutical Co., Ltd |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Ningbo freight corridor compresses logistics costs for atorvastatin side-chain intermediates moving from Hubei province to Indian API producers, tightening the link between supply concentration and price differentiation. Contract manufacturing organization procurement teams leverage this lane cost structure to extract volume discounts from enzymatic resolution specialists, while smaller batch-reactor operators absorb margin erosion from palladium catalyst volatility.
Pricing Analysis
Batch-reactor versus continuous flow chemistry pricing gaps separate legacy manufacturers from next-generation operators. Three-tier pricing structure across premium crystalline grades, standard powder forms, and economy amorphous inputs tracks enantiomeric excess certification levels. Cost compression in economy tiers is intensifying because CDSCO bioequivalence-linked impurity thresholds disqualify legacy synthesis routes. Generic finished-dosage manufacturers in Gujarat exhibit highest price sensitivity, while vertically integrated pharmaceutical companies show least sensitivity due to captive intermediate supply.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculations for pyrrole-derived statin building blocks. Manufacturing concentrates in China, India, and Switzerland, with Hubei province and Hyderabad clusters anchoring volume. The supply chain draws from palladium catalyst suppliers, chiral pool feedstock harvesters, and petrochemical precursors. Single-source vulnerability persists where enzymatic resolution specialists lack qualified alternatives. Distribution runs through direct-to-formulator lanes bypassing traditional merchant chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against biocatalytic cascade technologies that collapse multi-step synthetic routes, threatening batch-reactor incumbents with process obsolescence.
For Market Incumbents: Build regulatory moats through dual-source qualification dossiers that lock in formulator relationships ahead of FDA starting material documentation revisions. Anchor capacity in PLI-subsidized Gujarat greenfields to capture 20% investment assistance while competitors face legacy reactor retrofit capex. The enzymatic resolution scale-up threat from Hyderabad specialists demands accelerated biocatalytic capability acquisition. For New Entrants and Emerging Players: Build out white-space positions in direct-to-formulator distribution lanes serving Telangana generic clusters, bypassing entrenched merchant chemical networks. Target duloxetine precursor segments where 99.8% enantiomeric excess requirements filter out subscale competition. Penetrate through certified reference standard preparation for quality assurance applications, leveraging lower regulatory entry barriers than commercial pharmaceutical production. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with non-core intermediate operations stranded by backward integration trends. Long-term viability centers on biocatalytic capability ownership across the projection horizon. Watch enzymatic resolution patent expiration schedules as inflection indicators for generic producer procurement pattern shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Biocatalytic Capability Acquisition | Directed evolution pipelines for transaminase tailoring displace chiral chromatography in CNS precursor manufacturing. |
| Continuous Flow Chemistry Retrofit | Hastelloy reactor configurations tighten impurity profiles for acidic duloxetine intermediate steps. |
| Dual-Source Supplier Qualification | FDA drug master file submissions now demand full supply chain mapping back to petrochemical origins. |
| Direct-to-Formulator Distribution | Dedicated logistics lanes to Gujarat and Telangana bypass traditional merchant chemical intermediaries. |
| PLI-Subsidized Greenfield Capacity | India's production-linked incentive scheme anchors 20% financial assistance for critical starting material investments. |
Methodological Framework
A spread of perspectives from enzymatic resolution specialists, contract manufacturing organization procurement leads, regulatory affairs directors at API manufacturers, and hospital group purchasing organization formulary managers converged on the working assumptions. Primary interview intelligence combined with secondary validation from FDA drug master file submissions, EMA REACH registration dossiers, CDSCO bioequivalence guidelines, and Indian PLI scheme administrative records. Bottom-up capacity tallies across Hyderabad and Hubei province clusters triangulated against top-down demand estimates from cardiovascular therapy protocol persistence data.
Demand-supply-balance modeling anchored the analytical framework across the projection horizon. Segmentation dimensions spanned product chemistry type, physical form factor, application regulatory tier, and end-user procurement sophistication. CAGRs derived from regression analysis against historical volume trajectories and elasticity-adjusted price evolution. Industry-specific forecast inputs incorporated palladium price volatility indices and enzymatic resolution yield improvement curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biocatalytic platform operators or sudden CDSCO impurity threshold revisions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Global Electrophoresis Reagents Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
United States Cellulose Acetate Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Sequencing Reagents Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Global Chromatography Reagents Market
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Carboxylic Acid Chlorides Market
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
Fungal Staining Reagent Market