
 Poultry Seasoning Market | 2026-2036
Poultry Seasoning Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Seasoning Market Analytics
Multi-source procurement for organic spice inputs is realigning how mid-size seasoning houses secure raw material consistency. McCormick & Company leverages its direct farmer partnerships in tropical growing regions to sustain supply chain visibility. Badia Spices Inc competes through aggressive pricing and broad ethnic product lines that anchor its presence in Hispanic grocery channels. Olam International dominates bulk ingredient sourcing, extending its reach into private-label manufacturing for North American retailers.
Poultry seasoning comprises dried herb and spice formulations—typically incorporating sage, thyme, rosemary, black pepper, and garlic powder—designed to enhance flavor profiles of chicken, turkey, and game birds during preparation or cooking. Commercial blends maintain standardized Scoville-consistent heat levels and volatile oil minimums to ensure batch uniformity across food manufacturing applications. Spice blends command the largest volume share within product type segmentation, though marinades generate superior margin pools through higher per-unit pricing and extended shelf-life formulations. Powdered form leads in foodservice throughput efficiency, while liquid variants capture growth in ready-to-cook retail meal kits where convenience drives substitution from scratch cooking.
FDA Food Safety Modernization Act requirements and EFSA contamination thresholds for ethylene oxide-treated spices are tightening residue monitoring protocols across import channels. USDA organic certification and Non-GMO Project verification create tiered market access barriers that favor suppliers with dedicated clean-label production lines. Stakeholders must monitor evolving maximum residue limits for pesticide and fumigant traces, as regulatory divergence between jurisdictions threatens to fragment formulation strategies and complicate unified product portfolios.
Market Dynamics
Clean-label reformulations driven by FDA and EFSA residue thresholds are forcing seasoning houses to rebuild supply chains around certified organic inputs and ethylene oxide-free sterilization methods.
Growth Catalysts
- Quick-service restaurant expansion:Chains across the United States are adding seasoned poultry SKUs to value menus, creating pull-through demand for standardized bulk blends with consistent volatile oil profiles.
- EU Green Deal sustainable sourcing mandates:EFSA-aligned carbon footprint disclosure requirements are accelerating farm-to-fork traceability investments among European private-label manufacturers.
- Spray-drying technology advancement:Encapsulation processes that preserve heat-sensitive terpenes in rosemary and thyme extracts are extending flavor stability in retail marinades.
Market Restraints
- Tropical spice input volatility:Black pepper and clove harvest fluctuations in Indonesia and Madagascar create margin compression for blenders without forward-contract coverage.
- Ethylene oxide regulatory divergence:FDA tolerance levels for sterilization residues remain misaligned with EFSA's stricter maximum residue limits, complicating unified export formulations.
- Substitution by fresh herb kits:Meal-kit providers promoting whole-sage and fresh-thyme pouches are capturing premium home-cooking occasions from dried blend categories.
Strategic Opportunities
- India foodservice penetration:Quick-service chicken chains in Mumbai and Bangalore represent underdeveloped demand for halal-certified seasoning systems with localized heat profiles.
- Retort pouch marinades:Shelf-stable liquid formats for camping and emergency-prep segments remain underserved by incumbent powder-focused suppliers.
- USDA organic certification tiering:Dual-line production facilities that segregate organic and conventional handling capture price premiums in Whole Foods and Sprouts retail sets.
Industry Challenges
- Sensory scientist talent scarcity:Formulation chemists capable of balancing Scoville consistency with clean-label ingredient decks command premium compensation and retention difficulty.
- Legacy ERP integration with traceability platforms:Mid-size seasoning houses face capex burdens connecting batch-record systems to blockchain-enabled farm-origin verification.
- Non-GMO Project verification timelines:Six-to-nine-month certification backlogs delay product launches for retailers with mandatory non-GMO shelf sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Seasoning Market |
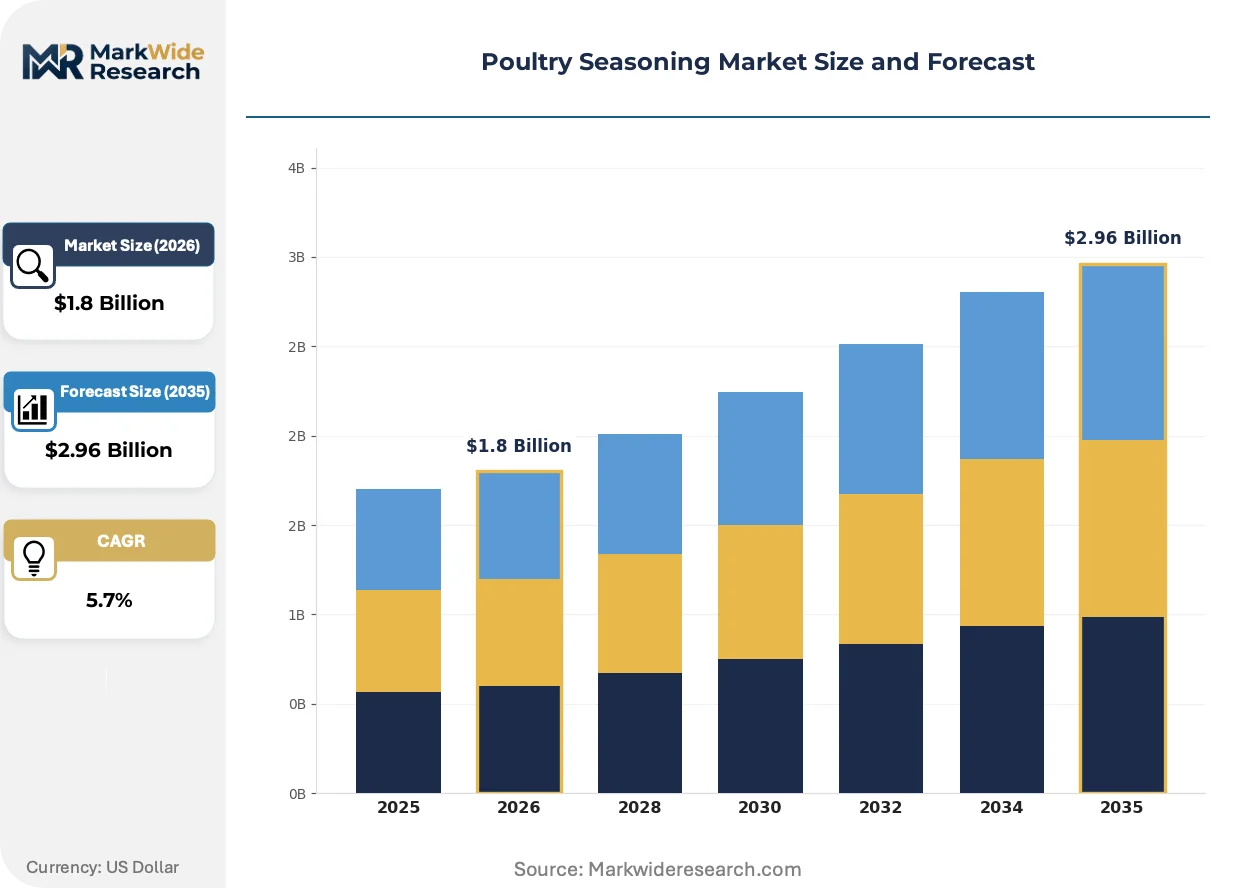
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubs, Marinades, Spice Blends, Sauces Form: Granular, Liquid, Powdered, Paste Packaging Type: Bottles, Pouches, Jars, Sachets Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Frontier Co-op, Aum Fresh, McCormick & Company, Unilever Food Solutions, Adams Flavors, Bell's Foods, Badia Spices Inc, Olam International, B & G Foods Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Seasoning Market Evolving Landscape
Formulation science and supply chain digitization are converging to reshape how poultry seasoning moves from raw spice to finished blend, with implications for shelf-life extension and origin verification.
Encapsulated essential oil microspheres are overtaking traditional spray-dried powders in premium marinade applications. Food manufacturers in Germany and the Netherlands are adopting these systems to deliver burst-release flavor profiles in sous-vide poultry products. The technology is overtaking conventional drying methods by enabling volatile oil retention above 85% through eighteen-month shelf cycles.
REACH-compliant ethylene oxide alternatives are mandating investment in steam and irradiation sterilization infrastructure. EFSA's tightening residue thresholds for imported spices are pushing European blenders toward domestic steam-treated supply bases. Mediterranean seasoning suppliers are absorbing capital costs to maintain EU market access while US exporters face divergent FDA tolerance schedules.
Direct-to-manufacturer spice sourcing is compressing traditional broker layers in North American procurement. Large quick-service chains are contracting directly with Vietnamese star anise and Turkish marjoram cooperatives, displacing regional distributors. This pattern is most visible in California and Texas, where vertically integrated restaurant groups are building captive seasoning supply lines.
Poultry Seasoning Market Segmentation
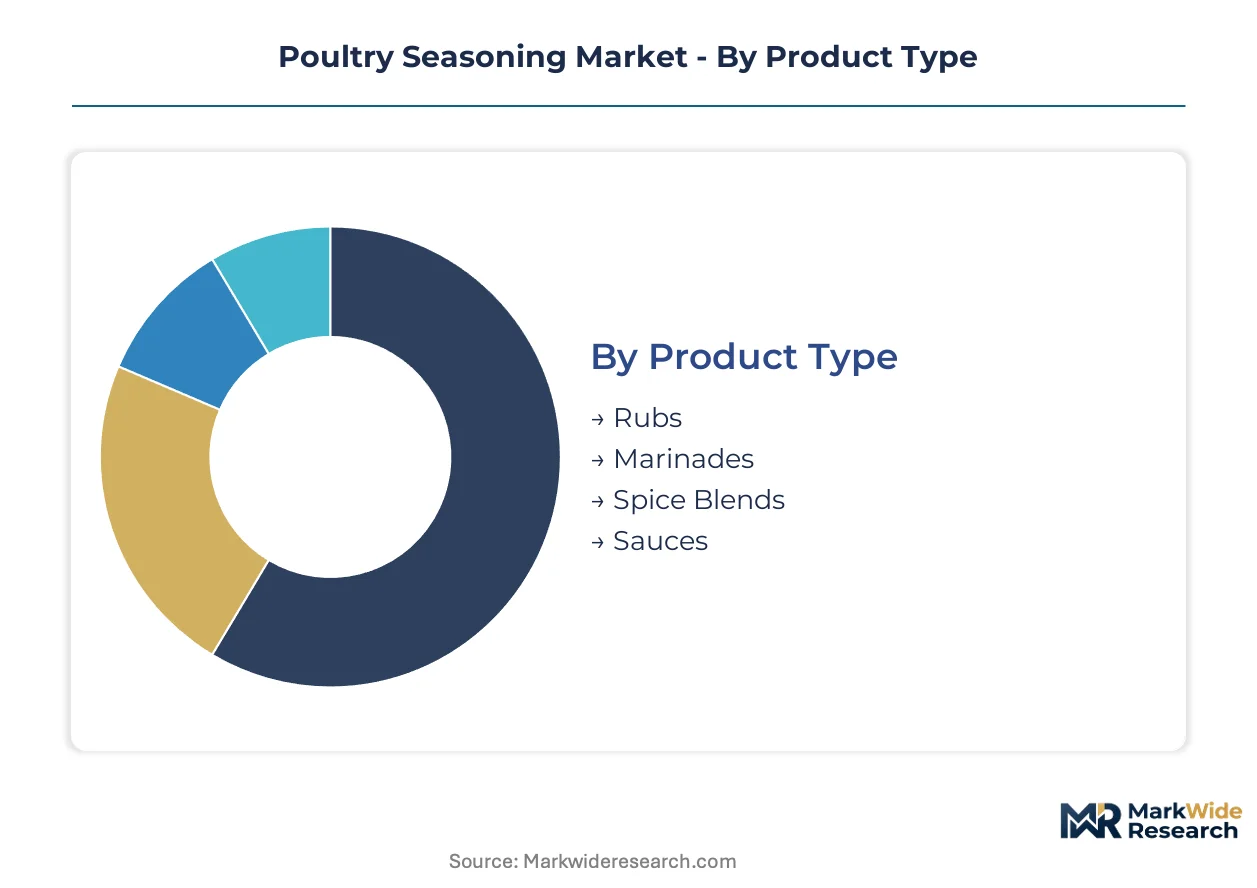
Poultry seasoning suppliers configure production lines around distinct technical specifications and channel requirements. Each segmentation dimension carries implications for formulation stability, shelf-life engineering, and margin capture.
Product Type:
Customization intensity varies sharply across this category, from standardized commodity blends to highly specified wet systems requiring pH control and preservative optimization.
- Spice Blends:Dried herb and spice formulations incorporating sage, thyme, rosemary, and black pepper with standardized volatile oil minimums. Quick-service restaurant chains in the United States specify Scoville-consistent heat profiles for value-menu poultry SKUs, pulling volume through bulk drum packaging.
- Marinades:Liquid or semi-liquid systems combining acidulants, oils, and flavor compounds with extended shelf-life formulations. German and Dutch food manufacturers adopt encapsulated essential oil microspheres for sous-vide applications, commanding premium per-unit pricing over dry alternatives.
- Rubs:Coarse-ground salt-sugar-spice mixtures applied pre-cooking for crust formation. Barbecue-focused retail channels in Texas and California drive demand for regional heat variants.
- Sauces:Post-cooking topical applications requiring thermal stability and pour viscosity control. Foodservice operators specify these for finishing-line automation compatibility.
Most installed capacity flows through spice blends. Expansion is steepest in marinades.
Form:
Cost tier separation dominates here, with powder commanding throughput efficiency at scale and liquid formats capturing premium positioning through convenience.
- Powdered:Spray-dried or ground particulate systems offering dissolution control and metering precision. Industrial food manufacturers favor these for seasoning drum application lines where uniform coating drives yield optimization.
- Liquid:Emulsion-based or dissolved systems enabling injection marination and tumble-coating processes. Ready-to-cook retail meal kits in North American markets substitute these for scratch cooking, climbing the fastest in dollar-margin contribution.
- Granular:Agglomerated particles balancing flowability with visual herb identification. Private-label programs specify these for premium shelf differentiation.
- Paste:High-solids concentrated systems requiring refrigeration but delivering flavor intensity. Ethnic grocery channels in Hispanic markets anchor volume here.
Volume concentration sits with powdered forms. Paste formats gain share in specialty ethnic retail.
Packaging Type:
Customer type and use occasion split this category, from institutional bulk to single-serve convenience.
- Pouches:Flexible film structures with oxygen barrier properties for marinades and wet blends. Camping and emergency-prep segments remain underserved by incumbent powder-focused suppliers, creating white-space opportunity.
- Bottles:Rigid PET or glass containers with shaker-fitment closures for granular and powdered products. Supermarket spice aisles in the United States standardize on these for household pantry storage.
- Jars:Wide-mouth glass or plastic containers enabling spoon access for paste and thick sauce formats. Specialty stores specify these for premium positioning.
- Sachets:Single-serve foil or paper packets for foodservice portion control and sampling programs. Quick-service chains deploy these for back-of-house consistency.
Primary procurement flows through pouches for foodservice and bottles for retail. Sachet formats expand most quickly in delivery-meal and travel channels.
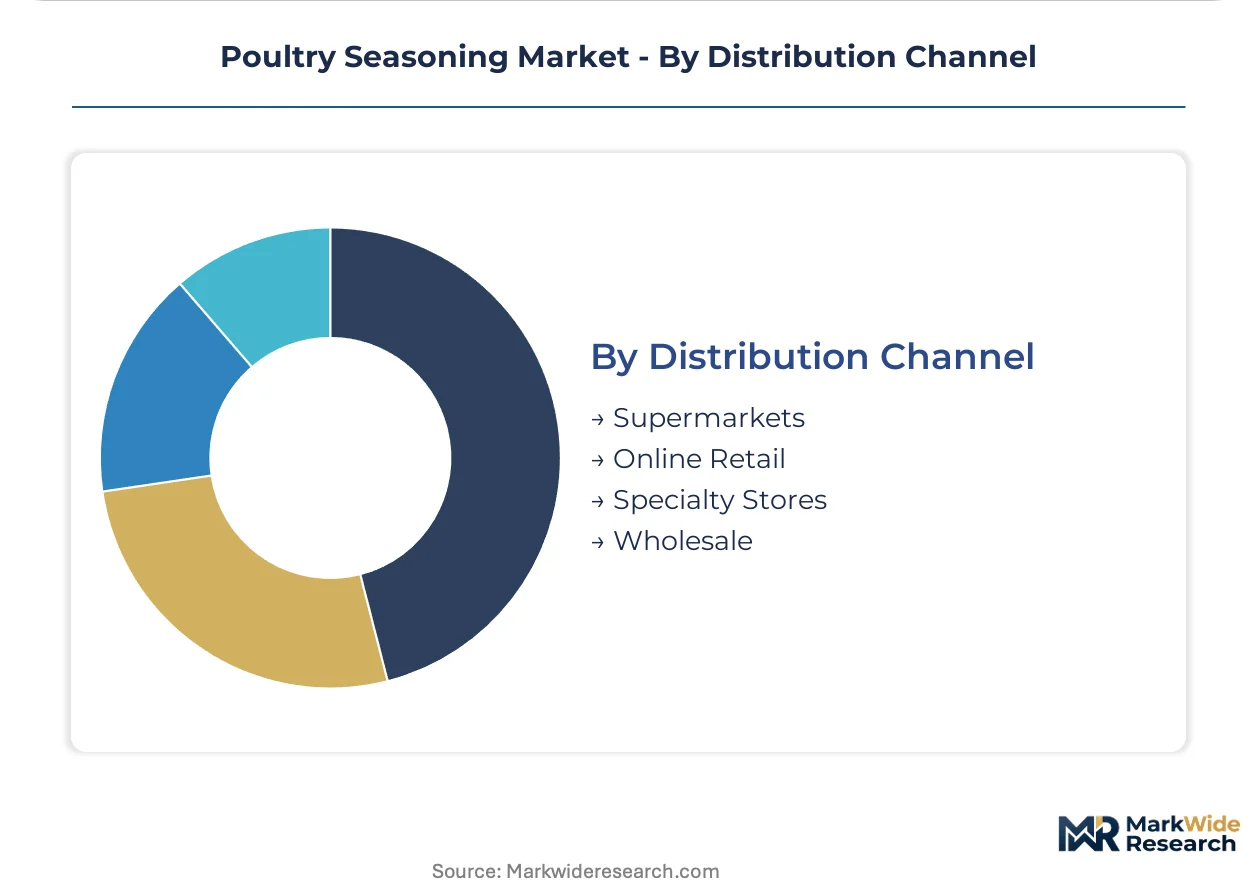
Distribution Channel:
Supply concentration and margin structure differentiate this final segmentation layer.
- Supermarkets:High-velocity retail environments with slotting fee barriers and planogram competition. Private-label programs at Whole Foods and Sprouts mandate USDA organic certification tiering.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription replenishment and discovery of ethnic variants. Digital penetration accelerates in metropolitan clusters.
- Wholesale:Institutional supply to foodservice operators, restaurant groups, and industrial food manufacturers. Direct contracting with Vietnamese star anise and Turkish marjoram cooperatives is compressing traditional broker layers here.
- Specialty Stores:Curated retail environments emphasizing provenance, craft positioning, and regional authenticity. Hispanic grocery channels anchor Badia Spices' presence through broad ethnic product lines.
Wholesale channels handle the largest absolute volume. Online retail posts the steepest expansion trajectory in percentage terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors the largest concentration of quick-service restaurant headquarters driving standardized poultry seasoning procurement. FDA Food Safety Modernization Act requirements shape formulation decisions across North American supply chains. EFSA residue thresholds for ethylene oxide-treated spices create divergent compliance pathways between Atlantic and Pacific trade corridors.
United States
Quick-service restaurant chains in Dallas and Atlanta specify Scoville-consistent bulk blends for value-menu poultry SKUs. FDA tolerance levels for sterilization residues remain less stringent than European counterparts, permitting ethylene oxide-treated imports from Vietnamese star anise cooperatives. California vertically integrated restaurant groups build captive seasoning supply lines displacing regional distributors.
Germany
Food manufacturers in Bavaria adopt encapsulated essential oil microspheres for sous-vide poultry applications commanding premium pricing. EFSA-aligned carbon footprint disclosure requirements under EU Green Deal accelerate farm-to-fork traceability investments. Cologne industrial clusters absorb capital costs for steam sterilization infrastructure to maintain EU market access.
India
Quick-service chicken chains in Mumbai and Bangalore generate underdeveloped demand for halal-certified seasoning systems with localized heat profiles. FSSAI labeling requirements reshape supplier formulations for domestic retail penetration. Maharashtra foodservice operators expand procurement of standardized volatile oil blends for regional poultry processing.
Netherlands
Rotterdam distribution hubs consolidate bulk spice imports for re-export across European private-label manufacturing networks. REACH-compliant ethylene oxide alternatives mandate investment in irradiation sterilization infrastructure. Eindhoven food technology clusters pioneer spray-drying encapsulation processes preserving heat-sensitive terpenes in rosemary extracts.
United Kingdom
London-based meal-kit providers promote fresh herb pouches capturing premium home-cooking occasions from dried blend categories. UK Food Standards Agency residue monitoring protocols tighten import channel scrutiny. Midlands industrial seasoning houses face capex burdens connecting batch-record systems to blockchain-enabled farm-origin verification.
Poultry Seasoning Market Competitive Landscape
Global majors compete with regional champions across supply chain visibility and clean-label certification tiers. The vendor base stratifies between integrated spice processors with direct farmer partnerships and mid-size seasoning houses dependent on broker-layer procurement. Three archetypes dominate: tropical-origin bulk suppliers, North American brand houses, and European clean-label specialists. Capacity expansion in steam sterilization infrastructure and backward integration into organic growing regions represent the dominant competitive moves reshaping procurement relationships.
Within the integrated processor tier, McCormick & Company and Olam International occupy positions defined by supply chain control depth. McCormick exemplifies the brand-house archetype through direct farmer partnerships in tropical growing regions sustaining visibility. Olam anchors the bulk-commodity vector dominating ingredient sourcing and private-label manufacturing reach. Badia Spices sits within the ethnic-specialist segment competing through broad product lines anchoring Hispanic grocery channel presence.
| Leading Market Players |
|---|
| Frontier Co-op |
| Aum Fresh |
| McCormick & Company |
| Unilever Food Solutions |
| Adams Flavors |
| Bell's Foods |
| Badia Spices Inc |
| Olam International |
| B & G Foods Inc |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap seasoning houses in Kerala and Gujarat anchor bulk spice procurement, translating generational farmer relationships into forward-contract pricing discipline that insulates against Indonesian black pepper harvest volatility. Their ownership structure enables patient capital deployment into organic certification tiering, creating price premiums that multinational blenders struggle to replicate through spot-market sourcing.
Pricing Analysis
Input-cost pass-through from Vietnamese star anise and Turkish marjoram cooperatives operates on six-month lag structures, compressing margins for blenders without captive supply agreements. Three-tier pricing structure across USDA organic, Non-GMO Project verified, and conventional grades separates Whole Foods shelf sets from foodservice bulk drums. Pricing pressure stems from ethylene oxide regulatory divergence forcing dual-formulation inventory carrying costs. Quick-service restaurant chains exhibit highest price sensitivity through competitive tendering, while sous-vide manufacturers in Germany absorb premiums for encapsulated essential oil microspheres.
Supply Chain Analysis
EU Green Deal local-content mandates are reshaping sourcing toward Mediterranean steam-sterilization facilities and away from ethylene oxide-dependent Asian export hubs. Supply concentrates in Vietnam for star anise, Madagascar for clove, and Indonesia for black pepper, with Turkish marjoram cooperatives gaining share. Raw material dependencies rest on tropical spice harvest cycles, volatile oil concentration thresholds, and organic certification backlogs. Single-source vulnerability runs through Indonesian pepper belt weather disruptions. Distribution runs through Rotterdam consolidation hubs for European private-label networks and direct-to-manufacturer contracting for North American quick-service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in poultry seasoning hinges on clean-label certification tiering that captures price premiums exceeding organic input cost inflation, particularly in European retail and North American natural-channel sets.
For Market Incumbents: Anticipate substitution pressure from fresh herb meal-kit providers by accelerating encapsulated essential oil microsphere capacity in Eindhoven and Cologne industrial clusters. Defensive consolidation should prioritize backward integration into Turkish marjoram and Vietnamese star anise cooperatives to displace broker-layer margin extraction. Steam sterilization infrastructure investments will preserve EU market access as EFSA residue thresholds tighten further. For New Entrants and Emerging Players: Halal-certified quick-service chains in Mumbai and Bangalore offer the most penetrable white-space, with localized heat profile development as the critical go-to-market angle. Retort pouch marinades for camping and emergency-prep segments remain underserved by incumbent powder-focused suppliers, enabling premium positioning through shelf-stable liquid convenience. Direct contracting with Maharashtra foodservice operators bypasses established distribution layers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size seasoning houses burdened by legacy ERP integration costs for blockchain traceability platforms. Long-term viability over the next decade favors suppliers with segregated organic-conventional production lines and direct farmer partnerships in tropical growing regions. The signal to watch is FSSAI labeling requirement harmonization with FDA and EFSA standards, which would unlock India export scalability for certified domestic players.| Strategic Initiative | Industry Significance |
|---|---|
| Steam Sterilization Infrastructure Investment | Cologne and Rotterdam facilities absorb capital costs to maintain EU market access under REACH-compliant ethylene oxide alternatives. |
| Direct Farmer Partnership Expansion | McCormick-style tropical growing region contracts sustain supply chain visibility that broker-dependent competitors cannot replicate. |
| Encapsulated Essential Oil Microsphere Capacity | Eindhoven food technology clusters pioneer spray-drying processes preserving terpenes for German sous-vide premium pricing. |
| Halal Certification Line Segregation | Mumbai and Bangalore quick-service penetration requires dedicated handling systems capturing underdeveloped India foodservice demand. |
| Blockchain Traceability Platform Integration | Midlands industrial seasoning houses face capex burdens connecting batch-record systems to farm-origin verification for EFSA-aligned disclosure. |
Research Methodology
Direct dialogue with seasoning house formulation chemists, quick-service restaurant procurement directors, spice cooperative export managers, and EFSA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from FDA Food Safety Modernization Act guidance documents, EFSA contamination threshold advisories, USDA organic certification databases, and EU Green Deal farm-to-fork traceability specifications. Bottom-up volume builds across product type, form, packaging, and channel segmentation triangulated against top-down macroeconomic drivers.
Top-down macroeconomic filtering established boundary conditions for bottom-up segment-level modeling across the analysis window. Segmentation dimensions included product type intensity, form factor convenience premium, packaging barrier technology, and distribution channel concentration. CAGRs were derived from volatility-adjusted growth trajectory fitting. Industry-specific forecast inputs incorporated tropical spice harvest cycle variance and clean-label certification adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ethylene oxide regulatory divergence, tropical weather disruption frequency, and fresh herb substitution elasticity in meal-kit channels. Assumptions reflect current FDA tolerance schedules and EFSA maximum residue limit trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Wasabi Market
Spices and Seasonings
Garlic Salt Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Basil Essential Oil Market
Spices and Seasonings
US Gourmet Salt Market
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
North America Spice and Herb Extracts Market
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Turkey Flavors Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Cajun Spice Market