
 Cardamom Oil Market | 2026-2036
Cardamom Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Cardamom Oil Market Analysis
Synthetic vanillin is expanding its share in budget flavor formulations, yet natural cardamom oil retains pricing power in premium applications where clean-label positioning commands shelf space. Givaudan SA leverages captive sourcing relationships in Guatemala and India to secure consistent oleoresin supply. Firmenich SA anchors its competitive stance through proprietary CO2 extraction technology that preserves heat-sensitive terpenoids. Synthite Industries Ltd dominates bulk steam-distilled output from its Kerala processing campus, supplying institutional buyers across Europe and North America.
Cardamom oil is a volatile essential oil obtained from Elettaria cardamomum seeds, typically containing cineole as the principal active constituent alongside terpinyl acetate and linalool, with steam distillation yielding a pale yellow liquid at specific gravities between 0.917 and 0.947. The oil serves as a flavoring agent, fragrance fixative, and traditional digestive aid across food, pharmaceutical, and cosmetic systems. Steam distilled grades occupy the volume tier, supplying mass-market food and beverage manufacturers where cost efficiency governs procurement decisions. CO2 extracted variants capture margin pools in aromatherapy and prestige cosmetics, where residual solvent-free certification supports premium positioning. Cold pressed offerings remain a niche within the broader product type matrix, constrained by lower yields and limited commercial scale.
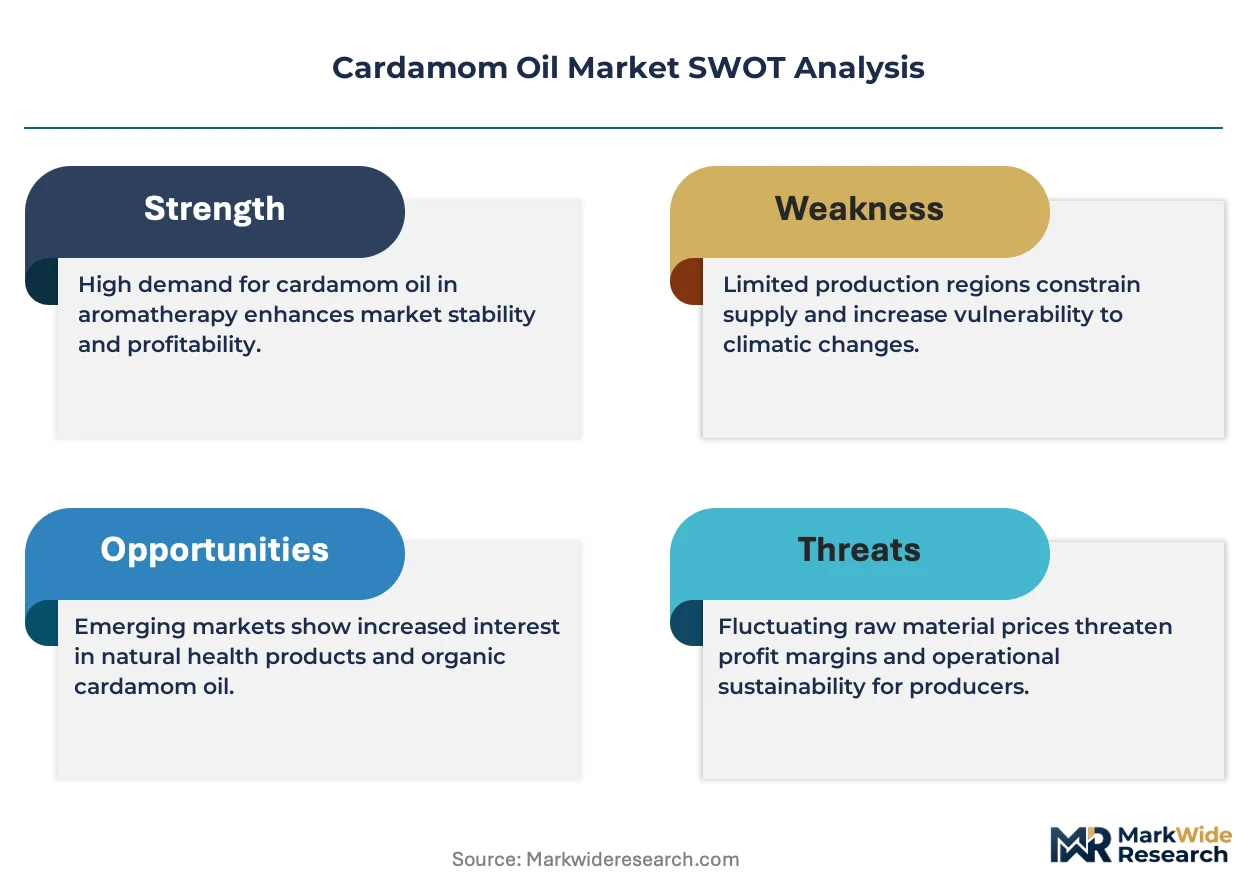
FDA food additive regulations under 21 CFR 182.20 govern cardamom oil's GRAS status in US flavor applications, while the EU REACH framework imposes full substance registration and safety data requirements on imported botanical extracts. India's FSSAI mandates pesticide residue limits and heavy metal thresholds for domestically processed essential oils destined for food contact. Stakeholders must monitor evolving MRL standards across destination markets and assess backward integration into cardamom cultivation as a hedge against raw material price volatility.
Market Dynamics
Clean-label mandates across food and fragrance sectors are compressing demand for synthetic alternatives while amplifying procurement scrutiny on extraction method transparency and botanical provenance documentation.
Growth Catalysts
- EU REACH substance registration:Importers of botanical extracts into European markets face mandatory safety data filing requirements that favor established suppliers with compliant documentation systems.
- CO2 extraction technology:Supercritical fluid processing preserves heat-sensitive terpenoid profiles that steam distillation degrades, unlocking premium positioning in aromatherapy and prestige cosmetics.
- Kerala's Idukki district:Dense clustering of smallholder cooperatives around centralized distillation infrastructure creates efficient raw material aggregation for bulk oleoresin production.
Market Restraints
- Raw material price volatility:Cardamom seed costs fluctuate with monsoon-dependent harvest yields in India's Western Ghats, compressing processor margins during poor crop cycles.
- Supply concentration risk:Guatemala and India collectively dominate global green cardamom cultivation, creating geographic vulnerability to climate events and trade disruptions.
- Synthetic vanillin substitution:Budget flavor manufacturers increasingly deploy artificial alternatives in mass-market baked goods and confectionery, constraining volume-tier cardamom oil offtake.
Strategic Opportunities
- India's PLI scheme for essential oils:Production-linked incentive frameworks subsidize processing infrastructure expansion, lowering capital barriers for integrated cultivation-distillation operations.
- Direct-to-brand e-commerce channels:Artisanal distillers bypass traditional wholesale brokers to supply niche perfumers and independent cosmetic formulators with traceable small-batch extracts.
- Pharmaceutical encapsulation applications:Enteric-coated cardamom oil softgels for digestive health formulations represent an underdeveloped therapeutic segment with clinical trial validation potential.
Industry Challenges
- Pesticide residue compliance:India's FSSAI maximum residue limit enforcement requires expensive testing infrastructure that small-scale processors struggle to fund.
- Extraction technician scarcity:Skilled operators capable of optimizing supercritical CO2 parameters for terpenoid recovery remain concentrated in European and North American technical institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardamom Oil Market |
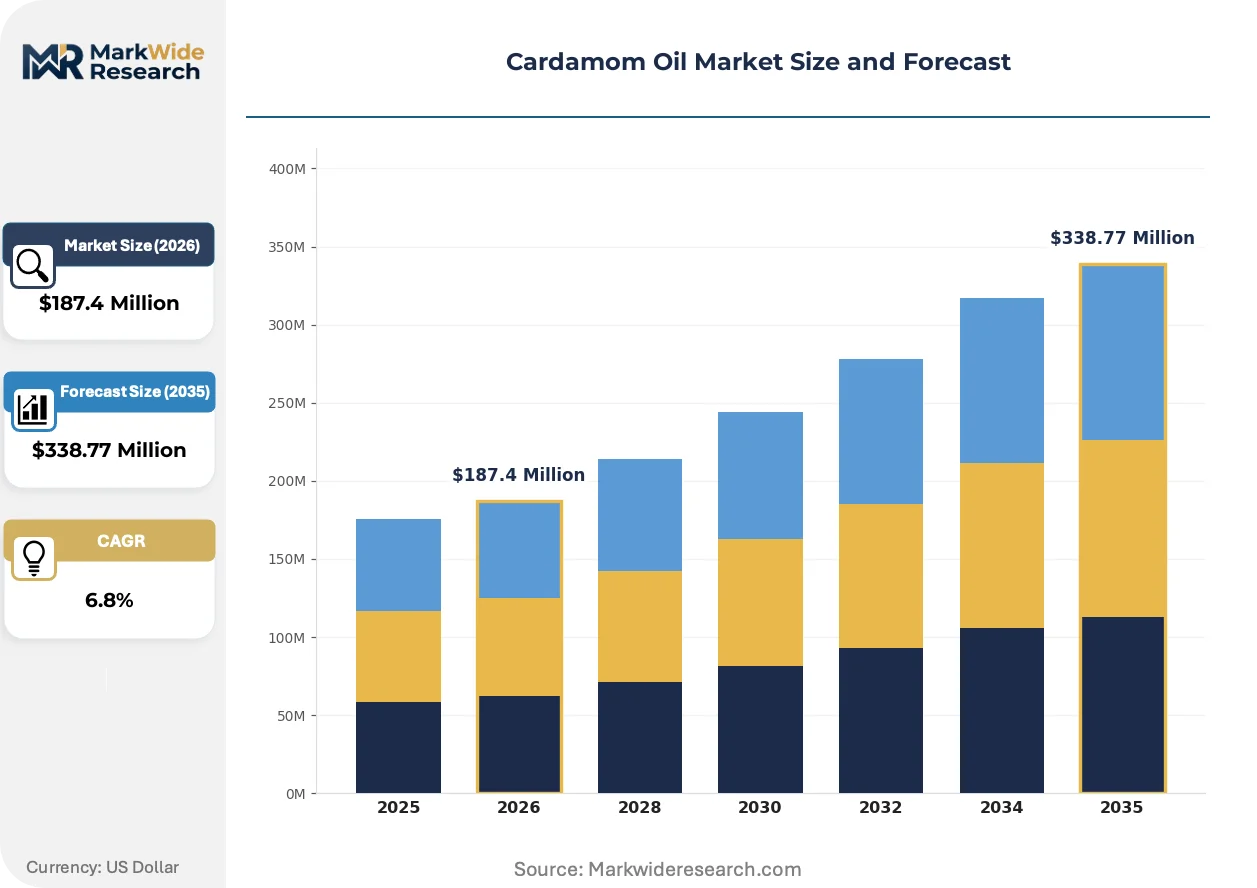
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Distilled, CO2 Extracted, Cold Pressed, Others End Use: Food & Beverage, Pharmaceutical, Cosmetics, Aromatherapy Packaging Type: Glass Bottles, Plastic Bottles, Drums, Others Distribution Channel: Online, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Synthite Industries Ltd, doTERRA International, Plant Therapy Essential Oils, Young Living Essential Oils, Givaudan SA, Firmenich SA, International Flavors & Fragrances Inc., AOS Products Private Limited, Kancor Ingredients Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardamom Oil Market Emerging Trajectories
Extraction methodology divergence is fragmenting competitive positioning between volume-efficient steam distillation and margin-capturing supercritical technologies.
Supercritical CO2 extraction systems are rewriting quality benchmarks for heat-labile botanical constituents. Prestige fragrance houses in Grasse and Paris specify CO2-extracted cardamom grades for fine perfume formulations where terpenoid integrity determines olfactory performance. This technology is compressing addressable market share for conventional steam-distilled output in premium tiers.
India's FSSAI pesticide residue regulations are tightening traceability documentation requirements for exported essential oils. Domestic processors must now maintain batch-level agricultural input records to satisfy destination market standards. Smallholder-dependent supply chains in Kerala face particular strain adapting record-keeping systems to these protocols.
Certification-driven procurement preferences are displacing price-first buying patterns among North American and European flavor houses. Organic and Fair Trade certified cardamom oil commands shelf space in clean-label product lines despite 15-30% cost premiums. This behavioral shift concentrates demand on processors with established third-party certification infrastructure.
Cardamom Oil Market Segmentation
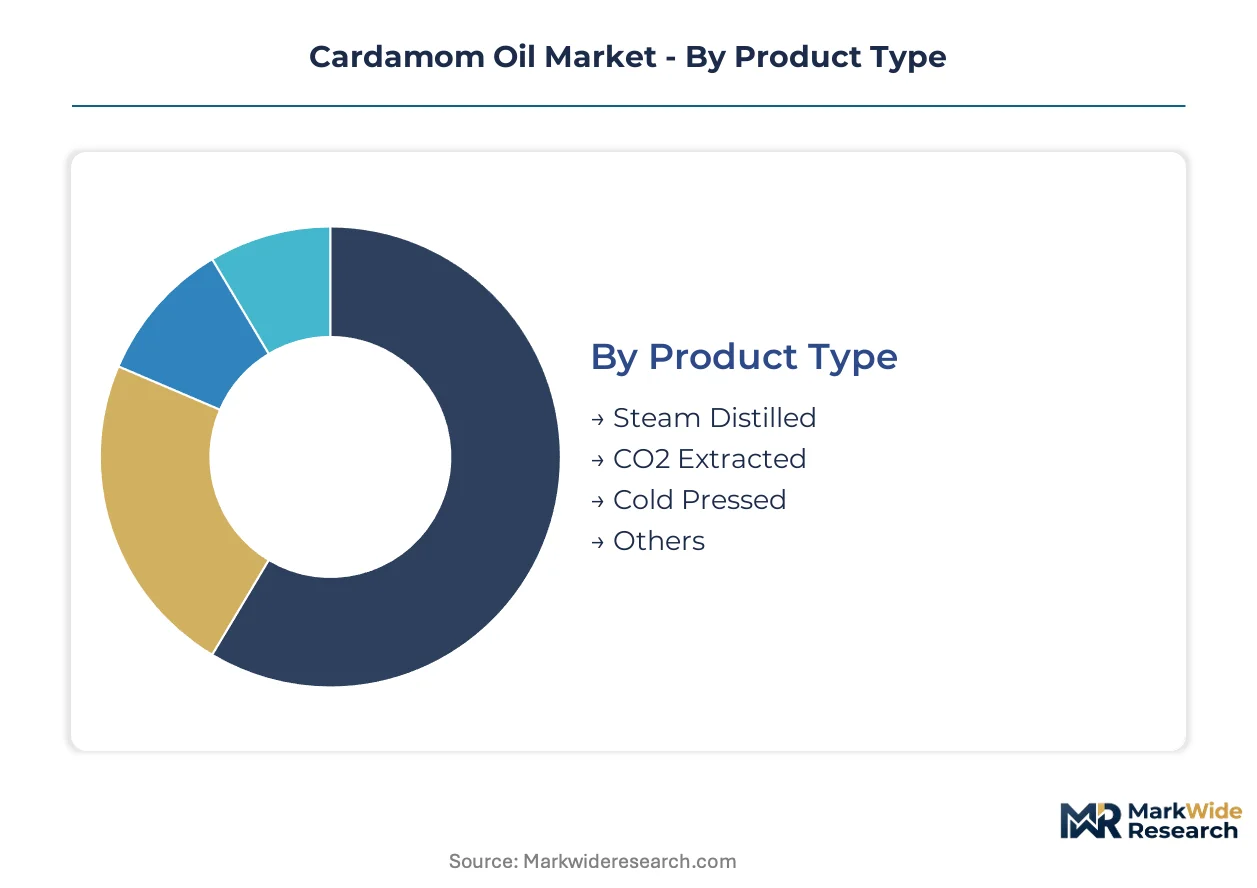
Extraction methodology and end-use specifications fragment procurement behavior across the cardamom oil value chain. Buyers prioritize heat-sensitive terpenoid preservation in prestige applications while cost efficiency governs mass-market food and beverage sourcing.
Product Type:
Procurement decisions in this category hinge on residual solvent tolerance and terpenoid integrity requirements across end-use applications.
- Steam Distilled:Conventional hydrodistillation yields pale yellow oil with cineole concentrations between 35-50%, supplying institutional flavor houses in North America and Europe where cost efficiency trumps terpenoid complexity. India's Synthite Industries dominates bulk output from its Kerala processing campus, feeding multinational baked goods and confectionery manufacturers.
- CO2 Extracted:Supercritical fluid extraction at pressures above 7,300 psi preserves heat-labile terpinyl acetate and linalool fractions that steam degradation destroys. Grasse-based perfumers and Parisian fragrance houses specify these grades for fine perfume formulations where olfactory fidelity commands three-to-four-fold price premiums over conventional distillates.
- Cold Pressed:Mechanical expression without thermal input yields limited commercial volumes due to seed oil recovery rates below 3%.
- Others:Solvent-extracted oleoresins and molecular distilled fractions serve niche pharmaceutical encapsulation requirements.
Steam Distilled leads volumes today; CO2 Extracted is gaining share fastest in margin-rich cosmetic and aromatherapy tiers.
End Use:
Application-specific regulatory thresholds and certification requirements reshape supplier qualification criteria across downstream industries.
- Food & Beverage:FDA 21 CFR 182.20 GRAS status and EU REACH substance registration govern flavor house procurement, with FSSAI pesticide residue limits tightening for Indian-origin shipments. Mass-market baked goods, chewing gum, and beverage formulations absorb the majority of steam-distilled volume.
- Pharmaceutical:Enteric-coated softgels and digestive health formulations demand pharmacopeial-grade specifications with heavy metal thresholds below 10 ppm lead and 3 ppm arsenic. Clinical validation for carminative and gastroprotective indications remains underdeveloped relative to peppermint and ginger oil.
- Cosmetics:Prestige skincare and fine fragrance applications drive CO2-extracted grade uptake, with clean-label positioning requiring residual solvent-free certification.
- Aromatherapy:Therapeutic-grade specifications emphasize batch-specific gas chromatography profiles and organic certification for diffuser and topical applications.
Food & Beverage commands absolute volume; Pharmaceutical applications are expanding most quickly as clinical trial investment accelerates.
Packaging Type:
Volume scale and shelf-life sensitivity determine container selection across customer tiers.
- Glass Bottles:Amber and cobalt glass containers with nitrogen headspace preservation serve premium cosmetic and aromatherapy brands where oxidation protection justifies unit costs exceeding plastic alternatives by 200-400%.
- Plastic Bottles:High-density polyethylene and fluorinated ethylene propylene containers balance chemical resistance with freight efficiency for mid-tier institutional buyers.
- Drums:Stainless steel and epoxy-lined carbon steel vessels handle 180-200 kg net weights for flavor house and pharmaceutical manufacturer bulk procurement.
- Others:Aluminum cans and bag-in-box configurations serve niche food service and industrial compounding requirements.
Drums dominate institutional procurement today; Glass Bottles are climbing the fastest in premium branded segments.
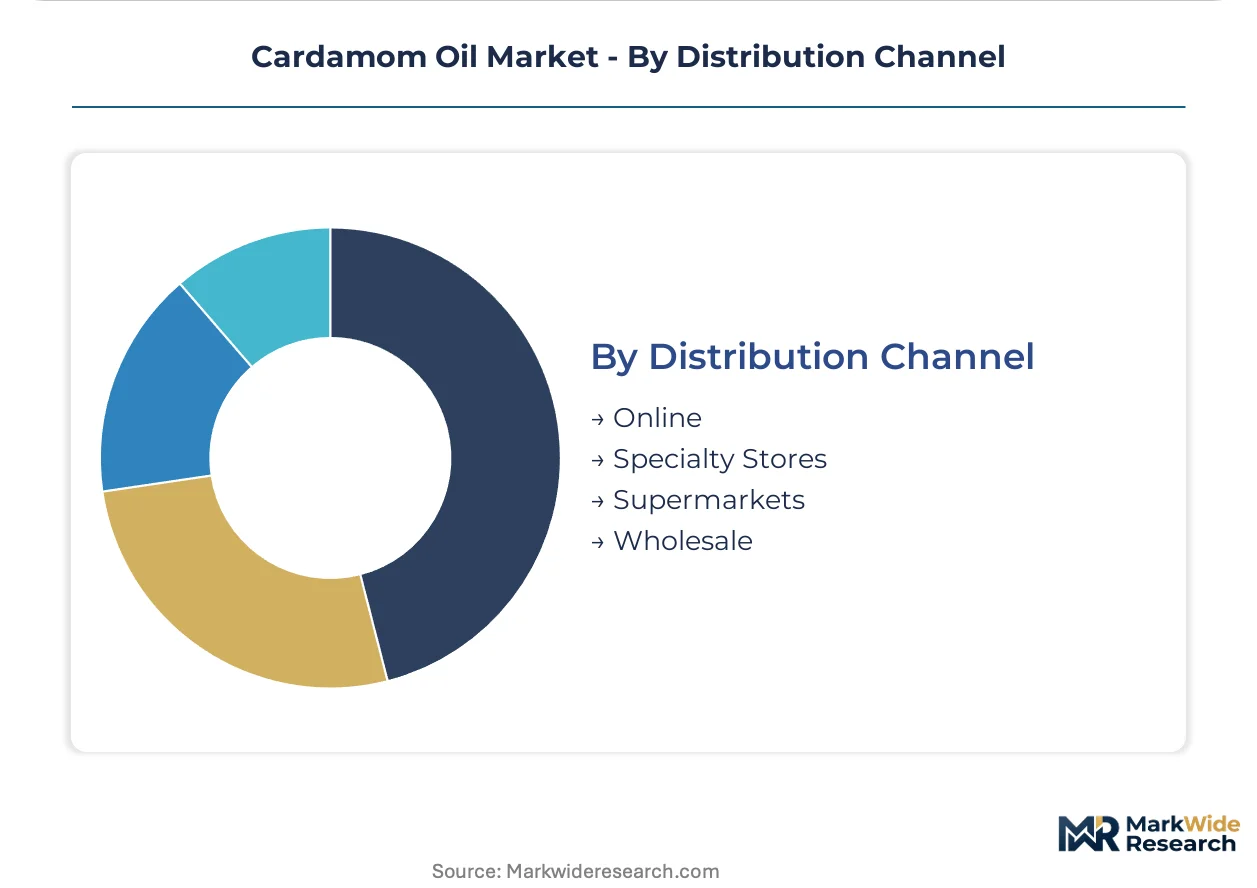
Distribution Channel:
Customer scale and traceability documentation requirements stratify route-to-market selection.
- Online:Direct-to-brand e-commerce platforms enable artisanal Kerala distillers to bypass wholesale brokers and supply independent perfumers with batch-level agricultural input records.
- Specialty Stores:Aromatherapy retailers and natural product apothecaries stock certified organic grades for consumer self-selection, with staff training on extraction method differentiation driving attachment rates.
- Supermarkets:Mass-market retail placement remains limited to blended spice oil assortments rather than pure cardamom oil SKUs.
- Wholesale:Traditional broker networks aggregate smallholder production for institutional flavor and fragrance house procurement, though documentation gaps strain FSSAI compliance adaptation.
Wholesale channels capture the majority of volume today; Online direct sales are expanding most quickly among traceability-focused niche buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kerala's Idukki district anchors global cardamom oil processing capacity, with smallholder cooperatives feeding distillation units across the Western Ghats. National regulatory frameworks and extraction technology adoption patterns create distinct competitive conditions across major producing and consuming markets.
India
FSSAI pesticide residue limits and heavy metal thresholds govern domestic processing standards for export-bound essential oils. The Production-Linked Incentive scheme subsidizes integrated cultivation-distillation infrastructure expansion in Kerala and Karnataka. Idukki district's cooperative network aggregates raw cardamom for bulk oleoresin production serving European and North American flavor houses.
United States
FDA 21 CFR 182.20 GRAS status enables broad food and beverage flavor applications, with clean-label procurement preferences concentrating demand on certified organic grades. EPA registration requirements for botanical pesticide applications create compliance barriers for non-domestic suppliers. New Jersey and New York-based fragrance compounding facilities specify CO2-extracted grades for prestige cosmetic formulations.
Guatemala
Alta Verapaz and San Marcos departments supply substantial green cardamom volumes to international distillation markets, with harvest yields fluctuating against monsoon patterns. The national agricultural export framework lacks equivalent residue monitoring infrastructure to Indian or US standards. Smallholder-dependent supply chains face documentation gaps when serving REACH-registered European buyers.
France
Grasse-based perfume houses specify supercritical CO2-extracted cardamom grades for fine fragrance formulations where terpenoid integrity commands substantial price premiums. ANSM cosmetic safety regulations mandate comprehensive substance documentation for botanical raw materials. Parisian fragrance laboratories drive premium-tier demand for solvent-free extraction certification.
Germany
EU REACH substance registration requirements favor established importers with compliant safety data filing systems for botanical extracts. KBA-equivalent industrial chemical oversight extends to essential oil processing equipment standards. Hamburg and Frankfurt trading houses aggregate Indian and Guatemalan supply for redistribution across European flavor and fragrance manufacturers.
Cardamom Oil Market Vendor Landscape
Global majors compete with regional champions across extraction technology tiers and certification infrastructure depth. The market structures around three player categories: integrated agro-processors with captive raw material access, specialty extraction technology licensors, and artisanal distillers serving traceability-focused niche buyers. Consolidation pressures concentrate among mid-scale processors lacking organic certification or REACH documentation capabilities. Strategic moves center on backward integration into cultivation assets and supercritical CO2 capacity expansion.
Within the integrated processor tier, Synthite Industries Ltd exemplifies scale-driven bulk supply positioning through its Kerala-based operations. Among specialty extraction specialists, Givaudan SA and Firmenich SA occupy positions defined by proprietary technology portfolios and captive sourcing relationships across Guatemala and India. These three entities represent distinct competitive archetypes: regional agro-industrial scale, global fragrance house vertical integration, and technology-differentiated premium positioning.
| Leading Market Players |
|---|
| Synthite Industries Ltd |
| doTERRA International |
| Plant Therapy Essential Oils |
| Young Living Essential Oils |
| Givaudan SA |
| Firmenich SA |
| International Flavors & Fragrances Inc. |
| AOS Products Private Limited |
| Kancor Ingredients Limited |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction adoption is redrawing cost structures and supplier concentration simultaneously, as European fragrance houses pay three-to-four-fold premiums for terpenoid-preserved grades while Kerala's steam-distilled bulk processors compete on throughput scale. This technology bifurcation concentrates margin capture among equipment-capable operators while compressing returns for conventional hydrodistillation units dependent on volatile seed input costs.
Pricing Analysis
Input-cost pass-through from cardamom seed procurement governs processor margin stability, with monsoon-dependent harvest yields in India's Western Ghats and Guatemala's Alta Verapaz creating cyclical price volatility that steam-distilled tier producers cannot fully recover. Three-tier pricing structure across CO2-extracted premium, certified organic mid-tier, and conventional steam-distilled economy levels reflects extraction method transparency and certification grade as primary differentiation drivers. Pricing pressure stems from synthetic vanillin substitution in mass-market baked goods and confectionery applications. Budget flavor manufacturers exhibit highest price sensitivity, while Grasse-based perfumers and Parisian cosmetic formulators absorb substantial premiums for solvent-free extraction certification.
Supply Chain Analysis
Regional distribution centers in Hamburg and Frankfurt aggregate Indian and Guatemalan supply for redistribution across European flavor and fragrance manufacturers, with hub-and-spoke patterns reflecting REACH documentation compliance clustering. Raw material sourcing concentrates in Kerala's Idukki district and Guatemala's western highlands, with seed quality and pesticide residue profiles as critical input variables. Single-source vulnerability to climate events in these dual-origin supply bases creates structural risk exposure. Distribution runs through wholesale broker networks for institutional buyers and direct-to-brand e-commerce channels for traceability-focused niche purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in this market rests on CO2 extraction technology diffusion enabling premium-tier capture, alongside India's PLI scheme subsidizing integrated cultivation-distillation infrastructure that compresses unit costs.
For Market Incumbents: Hedge against raw material volatility through backward integration into cardamom cultivation assets in Kerala and Karnataka, securing captive seed supply when monsoon failures spike spot market prices. Invest in supercritical CO2 capacity expansion to defend margin position against technology-differentiated competitors like Firmenich SA, while maintaining FSSAI-compliant testing infrastructure as India's pesticide residue enforcement tightens. For New Entrants and Emerging Players: The gap between premium CO2-extracted and economy steam-distilled pricing creates white-space opportunity for mid-tier certified organic positioning. Target pharmaceutical encapsulation applications for digestive health formulations, where clinical trial validation remains underdeveloped relative to peppermint and ginger oil competitors. Pursue direct-to-brand e-commerce channels supplying independent perfumers with batch-level agricultural input records that wholesale brokers cannot provide. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale processors lacking organic certification or REACH documentation capabilities, where consolidation pressure concentrates. Long-term viability favors integrated agro-processors with captive raw material access and supercritical extraction technology portfolios. Watch for India's FSSAI enforcement intensity as inflection indicator, as compliance cost burdens will accelerate acquisition activity among documentation-deficient smallholders.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Enables terpenoid-preserved grade capture in Grasse and Paris fragrance house procurement. |
| Backward Integration into Cultivation | Secures seed supply against Western Ghats monsoon volatility and price spikes. |
| Organic and Fair Trade Certification Investment | Unlocks 15-30% price premiums in North American and European clean-label procurement. |
| Direct-to-Brand E-Commerce Channel Development | Bypasses wholesale documentation gaps for traceability-focused niche buyers. |
| Pharmaceutical Encapsulation Partnership | Positions cardamom oil for enteric-coated softgel digestive health formulations. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with Kerala distillation unit operators, FSSAI compliance officers, European fragrance house procurement leads, and specialty extraction equipment manufacturers with secondary validation. Trade data from India's DGFT, EU REACH substance registration filings, FDA 21 CFR 182.20 GRAS documentation, and FSSAI pesticide residue enforcement records anchor supply-side quantification. Customs records, essential oil industry association reports, and certification body disclosure databases complete secondary source triangulation.
Historical trendline analysis across extraction technology adoption curves and certification penetration rates informs projection modeling. Segmentation dimensions include extraction methodology, end-use application, certification tier, packaging format, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated against input cost elasticity estimates and buyer substitution behavior patterns. Monsoon harvest yield correlations and PLI scheme uptake trajectories serve as India-specific forecast inputs.
Caveats apply where FSSAI enforcement intensity, EU REACH substance registration scope expansion, or synthetic vanillin cost-performance improvements could materially shift the outlook. Forecasts reflect documented assumptions regarding technology diffusion rates and certification adoption thresholds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Garlic Salt Market
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Malaysia Spices and Seasonings Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Celery Seed Extract Powder Market
Spices and Seasonings
Pumpkin Pie Spices Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Jalapeno Salt Market
Spices and Seasonings
Pepper Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
North America Seasonings Market
Spices and Seasonings
Mullein Leaf Market
Spices and Seasonings
Turmeric Oleoresin Market