
 Jalapeno Salt Market | 2026-2036
Jalapeno Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Jalapeno Salt Market Foresight
Himalayan pink salt is expanding its share in jalapeno salt formulations as brands reformulate away from standard iodized table salt to command premium positioning. The J.C. Spice Company leverages its heritage grinding operations to sustain regional distribution density across the southwestern United States. Dave's Jalapeno Salt anchors its identity through single-origin pepper sourcing, while Bolner's Fiesta Products dominates Texas-centric retail channels with heritage brand recognition.
Jalapeno salt is a seasoned salt product comprising dried jalapeno pepper powder blended with crystalline salt, typically at ratios between 10-30% pepper content by weight, manufactured through dehydration, milling, and homogenization processes. It functions primarily as a finishing and cooking seasoning in commercial kitchens and consumer pantries. Flavored variants lead volume given their alignment with barbecue and snack seasoning trends, while organic certification commands disproportionate margin pools due to input cost premiums and supply scarcity. Glass jar packaging sustains price positioning in specialty retail, though pouches compete aggressively in online channels where shipping economics favor lighter formats.
FDA oversight of sodium labeling and USDA organic certification requirements shape formulation transparency and sourcing documentation burdens for producers. The F-Gas Regulation in Europe and analogous refrigeration standards elsewhere influence dehydration technology choices and energy costs in processing facilities. Stakeholders must monitor evolving clean-label enforcement thresholds and pepper supply volatility from drought-prone growing regions.
Market Dynamics
Clean-label reformulation pressure from FDA and USDA is forcing jalapeno salt manufacturers to revalidate sourcing documentation and reformulate away from artificial anti-caking agents, compressing margins while creating tiered product architectures.
Growth Catalysts
- Barbecue and snack seasoning applications:Specialty food manufacturers are expanding procurement of jalapeno salt for premium snack lines as flavor-forward consumers seek authentic pepper-based heat profiles.
- USDA organic certification requirements:Clean-label mandates are altering ingredient sourcing requirements and creating disproportionate margin pools for certified organic variants due to supply scarcity.
- Single-origin pepper sourcing:Heritage grinding operations and transparent supply chains are sustaining regional distribution density and commanding premium positioning in specialty retail channels.
Market Restraints
- Drought-prone growing regions:Pepper supply volatility from concentrated agricultural zones in Mexico and the southwestern United States creates input cost instability and harvest uncertainty.
- EU F-Gas Regulation:Dehydration technology choices and energy costs in processing facilities face compliance burdens that constrain equipment upgrade cycles.
- Himalayan pink salt substitution:Standard iodized table salt is losing formulation share to specialty salts, forcing reformulation investments without guaranteed price recovery.
Strategic Opportunities
- Online channel expansion:Pouch packaging formats compete aggressively in e-commerce where shipping economics favor lighter formats over traditional glass jars.
- German flavor-forward consumers:Authentic pepper-based seasonings are concentrating demand in Germany as European palates shift toward bold, regional heat profiles.
- Dual carbon goals convergence:Solar-powered dehydration infrastructure in China and renewable energy mandates in the European Union are creating operational cost advantages for early adopters.
Industry Challenges
- Clean-label enforcement thresholds:Evolving FDA sodium labeling requirements demand continuous reformulation and documentation burdens that strain mid-tier producers.
- Dehydration equipment capex intensity:Energy-efficient processing lines require substantial capital deployment, favoring scaled operators with balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jalapeno Salt Market |
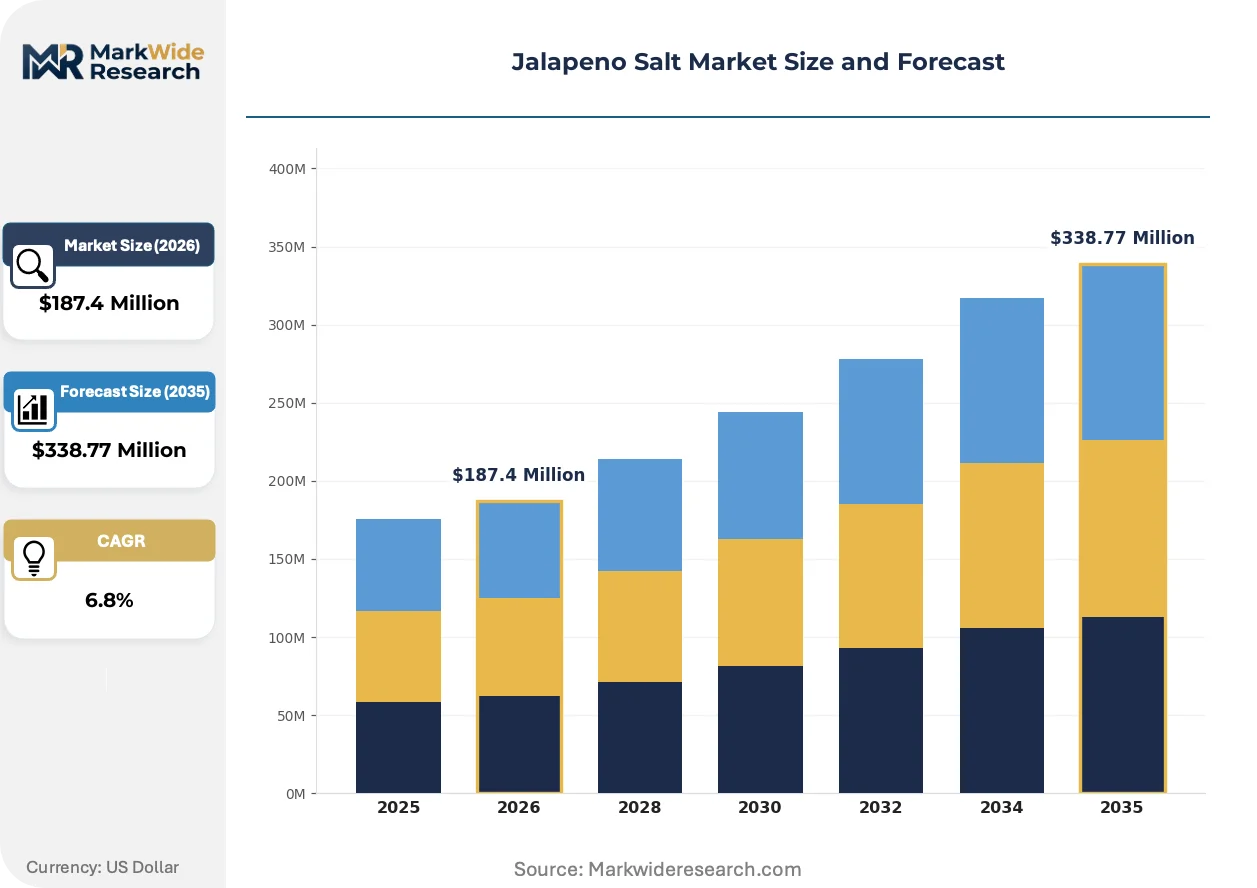
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored, Unflavored, Smoked, Organic Packaging Type: Glass Jar, Plastic Container, Pouch, Bulk Distribution Channel: Online, Supermarkets, Specialty Stores, Food Service End User: Home Cooks, Restaurants, Food Manufacturers, Caterers |
| Companies Covered | The J.C. Spice Company, Dave's Jalapeno Salt, Bolner's Fiesta Products, Inc., Home and Heritage, Hippy Pilgrim, Bacon Salt, Caravel Gourmet, Olde Thompson, Caribbean Spice Belize, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jalapeno Salt Market Shifts & Advancements
Processing technology and packaging format evolution is reshaping competitive positioning in jalapeno salt manufacturing, with sustainability mandates and channel economics driving divergent investment priorities.
Spray-dried jalapeno powder is overtaking traditional sun-dried and oven-dried methods in commercial-scale production. Large seasoning houses and co-manufacturers are adopting spray-drying for batch consistency and microbial control. This technology is overtaking heritage dehydration approaches by enabling year-round production independent of weather patterns and reducing labor intensity.
REACH chemical registration requirements in the European Union are tightening documentation burdens for imported spice blends and processed pepper derivatives. Manufacturers must now maintain substance volume tracking and safety data sheets across complex supply chains. German and Dutch importers are responding by demanding pre-certified inputs and backward integration into grinding operations.
Direct-to-restaurant distribution is fragmenting traditional wholesale relationships as chef-driven purchasing consolidates through specialty distributors. Independent restaurants and foodservice operators are bypassing broadline distributors for curated seasoning portfolios with provenance documentation. This pattern is most visible in Texas and California, where regional spice houses are building captive chef networks through tasting-room education programs.
Jalapeno Salt Market Segmentation
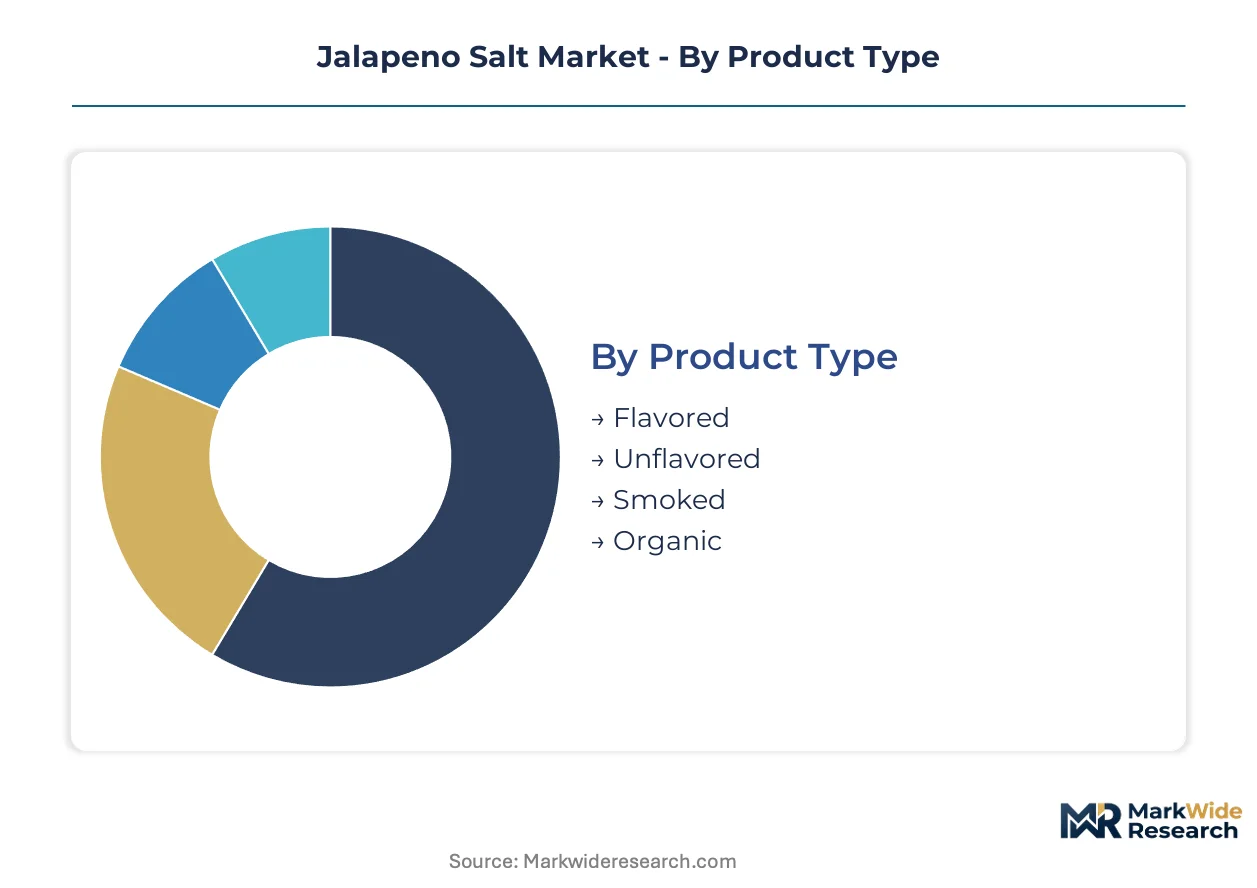
Jalapeno salt manufacturers configure product architectures around certification tiers, packaging economics, and channel-specific margin requirements. Segmentation decisions directly determine which FDA and USDA compliance burdens apply, how dehydration technology investments are allocated, and where pricing power concentrates across consumer and commercial buyers.
Product Type:
USDA organic certification requirements apply unevenly across this category, with organic variants demanding complete supply chain documentation and third-party verification while conventional products face lighter FDA sodium labeling obligations alone.
- Flavored:Blends incorporate additional seasonings such as lime, garlic, or mesquite to target barbecue and snack applications. Demand concentrates in the United States where flavor-forward consumers drive premium positioning in specialty retail channels constrained by clean-label reformulation pressures.
- Organic:Certified organic variants command disproportionate margin pools due to input cost premiums and supply scarcity of organically grown jalapeno peppers. German importers and US natural food retailers prioritize these SKUs despite price positioning at 40-60% above conventional equivalents.
- Smoked:Cold-smoked or kiln-dried variants using oak or mesquite wood appeal to Texas barbecue culture and southwestern US regional identity.
- Unflavored:Pure jalapeno-salt blends without additional seasonings serve commercial kitchen buyers seeking controlled heat profiles.
Flavored sits at the top of the volume ranking, with Organic climbing the fastest.
Packaging Type:
Cost tier stratification runs through this dimension, with glass jars sustaining premium price points in specialty retail while lighter formats capture e-commerce economics.
- Glass Jar:Airtight glass containers preserve volatile pepper oils and support premium shelf positioning in specialty stores. US and German specialty retailers favor this format for provenance-focused consumers despite higher shipping costs and breakage risk.
- Pouch:Flexible laminated pouches reduce unit shipping weight by 70-80% versus glass, enabling competitive online pricing where logistics economics dominate purchase decisions. Amazon and direct-to-consumer channels favor this format for subscription seasoning boxes.
- Plastic Container:Polypropylene shakers and tubs balance durability with cost for mass retail placement.
- Bulk:Food-service sacks and industrial totes supply restaurants and co-manufacturers with minimal packaging overhead.
Glass Jar retains the highest revenue per unit, though Pouch gains share fastest in digital channels.
Distribution Channel:
Application concentration shapes this category, with each channel demanding distinct documentation standards and relationship structures from suppliers.
- Supermarkets:Mass retail placement requires slotting fee investments and compliance with retailer-specific clean-label thresholds. Walmart and Kroger distribution in the United States demands validated sourcing documentation and consistent case-fill rates.
- Specialty Stores:Curated independent retailers in Texas, California, and Germany prioritize single-origin provenance and heritage grinding narratives. These channels tolerate higher wholesale prices in exchange for exclusive SKUs and tasting-room education support.
- Online:Direct-to-consumer and marketplace sales bypass traditional distributor markups but require pouch-format optimization and digital marketing investment.
- Food Service:Broadline and specialty distributors supply restaurants with bulk formats and chef-focused technical support.
Supermarkets dominate absolute volume, with Specialty Stores expanding most quickly among premium-positioned suppliers.
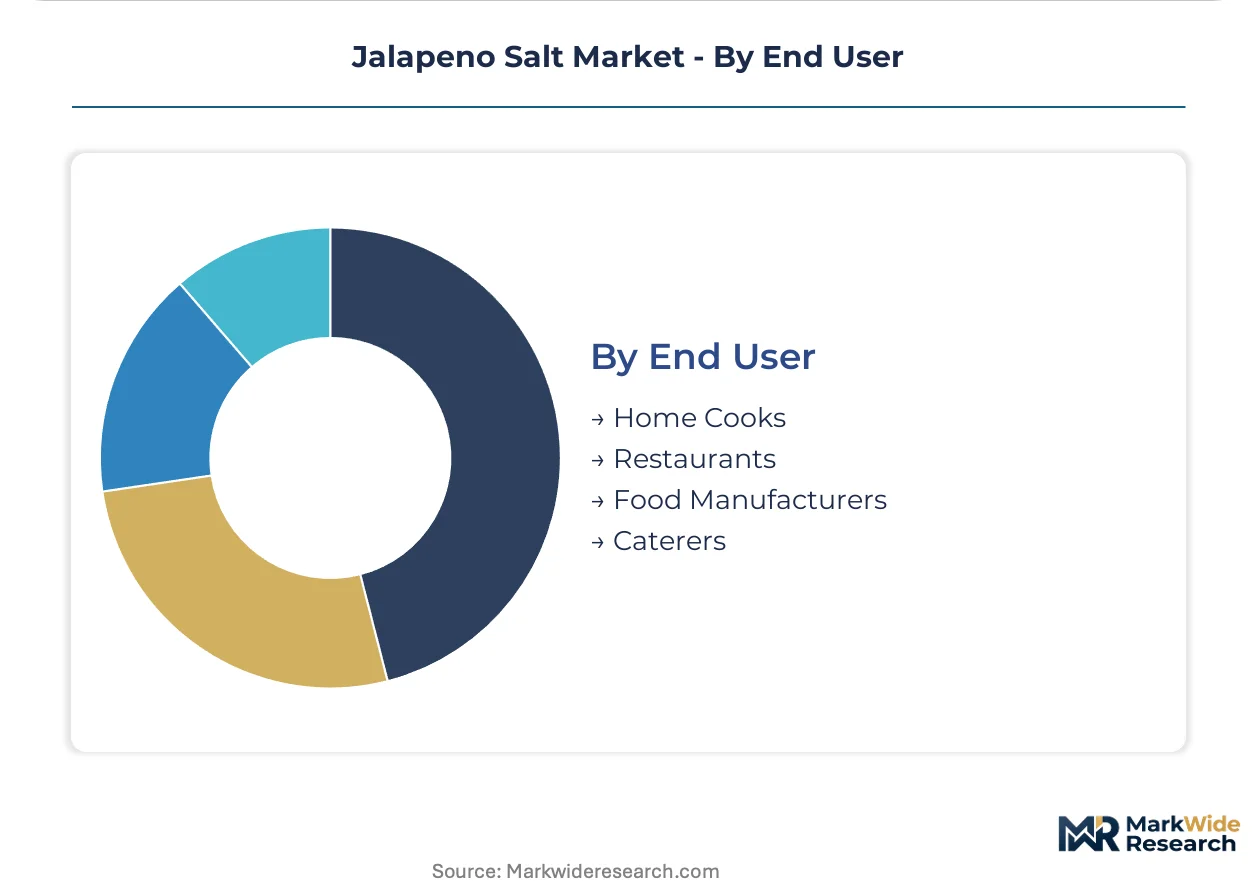
End User:
Customer type determines formulation complexity and purchase frequency, with commercial buyers demanding technical specifications that home consumers ignore.
- Restaurants:Independent and chain kitchens require batch-consistent heat profiles, food-safety documentation, and direct distributor relationships. Texas and California chef networks increasingly bypass broadline distributors for regional spice houses with provenance transparency.
- Food Manufacturers:Snack seasoning and sauce co-manufacturers procure jalapeno salt as an input ingredient, demanding spray-dried powder specifications and microbial testing certificates.
- Home Cooks:Consumer pantry purchases favor recognizable brand identity and recipe inspiration on packaging.
- Caterers:Event-service operators balance cost control with menu differentiation through specialty seasoning procurement.
Restaurants anchor commercial demand, while Food Manufacturers show the steepest expansion trajectory as snack seasoning applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southwestern United States concentrates jalapeno salt manufacturing heritage, with Texas and California hosting established grinding operations and pepper sourcing networks. Specialty retailers in Austin, San Antonio, and Los Angeles sustain demand for provenance-documented seasonings. FDA sodium labeling requirements and USDA organic certification standards shape formulation compliance across North American production facilities.
United States
Barbecue culture and snack seasoning applications drive procurement from Texas-based spice houses and California co-manufacturers. FDA oversight of sodium content disclosure and clean-label enforcement thresholds compels continuous reformulation investment. Austin and San Antonio anchor heritage grinding operations that supply chef-driven purchasing networks through direct-to-restaurant distribution channels.
Germany
Flavor-forward consumers in Berlin, Hamburg, and Munich concentrate demand for authentic pepper-based heat profiles in European specialty retail. REACH chemical registration requirements tighten documentation burdens for imported spice blends and processed pepper derivatives. The ECHA substance volume tracking mandates push German importers toward pre-certified inputs and backward integration into grinding operations.
Mexico
Jalapeno pepper cultivation in Chihuahua, Sinaloa, and San Luis Potosí supplies raw material for cross-border seasoning production. Drought-prone growing regions create harvest uncertainty and input cost volatility for dehydration facilities. The central plateau agricultural zones sustain traditional sun-drying operations alongside expanding commercial spray-drying infrastructure near Mexico City.
China
Solar-powered dehydration infrastructure in Shandong and Sichuan provinces creates operational cost advantages for seasoning powder manufacturing. Dual carbon goals convergence under MEE mandates accelerates renewable energy adoption in processing facilities. Yangtze River Delta industrial clusters host spray-drying equipment serving export markets with batch-consistent microbial specifications.
Jalapeno Salt Market Competitive Landscape
Global majors compete with regional champions across heritage brand recognition and distribution density in jalapeno salt manufacturing. The vendor base stratifies into three tiers: scaled seasoning houses with spray-drying capacity, mid-sized regional specialists with provenance narratives, and artisanal producers with single-origin sourcing claims. Strategic archetypes include heritage grinding operations leveraging generational brand equity, co-manufacturers serving private-label snack seasoning contracts, and direct-to-consumer specialists optimizing pouch-format e-commerce economics. Dominant competitive moves encompass backward integration into pepper cultivation zones and portfolio diversification toward smoked and organic certification tiers.
Within the heritage-brand tier, The J.C. Spice Company exemplifies regional distribution density sustained through southwestern United States grinding operations. Dave's Jalapeno Salt occupies a position emphasizing single-origin pepper sourcing transparency. Bolner's Fiesta Products anchors Texas-centric retail channel penetration through established heritage recognition. These three entities represent distinct competitive positioning vectors without implying specific market share claims or strategic action timelines.
| Leading Market Players |
|---|
| The J.C. Spice Company |
| Dave's Jalapeno Salt |
| Bolner's Fiesta Products, Inc. |
| Home and Heritage |
| Hippy Pilgrim |
| Bacon Salt |
| Caravel Gourmet |
| Olde Thompson |
| Caribbean Spice Belize |
| Others |
Supply & Pricing Matrix
Heritage grinding specialists concentrated in Texas and California command wage premiums that widen spreads between artisanal and commodity-grade jalapeno salt tiers. Labor-cost differentials between these craft-oriented regions and mechanized processing zones in Mexico and China feed directly into three-tier pricing architectures across retail and foodservice channels.
Pricing Analysis
Input-cost pass-through from drought-affected jalapeno harvests in Chihuahua and Sinaloa compresses margins for mid-tier processors unable to command organic certification premiums. Pricing stratifies across premium, standard, and economy tiers driven by USDA organic status and single-origin provenance documentation. Cost compression in conventional segments is intensifying because Himalayan pink salt substitution forces reformulation investments without guaranteed price recovery. Food manufacturers show highest price sensitivity due to bulk procurement volumes, while German specialty retailers tolerate elevated wholesale costs for REACH-compliant imports with traceable supply chains.
Supply Chain Analysis
Single-source vulnerability sits with Mexican pepper cultivation zones concentrated in drought-prone central plateau regions. Raw material dependencies center on jalapeno pepper supply from Mexico, crystalline salt inputs from Pakistan and the United States, and oak or mesquite wood for smoked variants. Tariff exposure on processed spice imports into the European Union creates compliance burdens under REACH substance tracking mandates. Distribution runs through specialty distributors serving chef-driven purchasing networks in Texas and California, alongside broadline operators supplying mass retail placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA sodium labeling enforcement and USDA organic certification expansion continuously reshape formulation economics and sourcing requirements.
For Market Incumbents: Cement regional distribution density through backward integration into pepper cultivation zones in San Luis Potosí and Chihuahua. Lock in spray-drying capacity advantages before EU F-Gas Regulation compliance costs constrain equipment upgrade cycles for mid-tier competitors. Prioritize organic certification tier expansion to capture margin pools insulated from conventional price erosion.
For New Entrants and Emerging Players: Specialty distributors serving independent restaurants represent the most accessible channel partners for provenance-focused market entry. White-space targets include direct-to-restaurant distribution in California chef networks and pouch-format subscription boxes optimized for Amazon logistics economics. German specialty retail offers penetrable geography where flavor-forward consumers prioritize authentic pepper-based heat profiles over established brand recognition.
For Investors and Strategic Acquirers: Snack seasoning co-manufacturers are the most active acquirer in this space, seeking spray-dried powder capabilities and microbial testing infrastructure. Long-term viability hinges on clean-label compliance scalability and renewable energy integration in dehydration facilities. Watch for inflection signals in solar-powered processing adoption rates in Shandong and Sichuan provinces.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pepper Cultivation | Captive supply from Chihuahua growing regions reduces harvest volatility exposure for Texas-based processors. |
| USDA Organic Certification Investment | Third-party verification unlocks 40-60% price premiums in German and US natural food retail channels. |
| Spray-Drying Technology Deployment | Batch-consistent microbial specifications meet FDA requirements for snack seasoning co-manufacturing contracts. |
| Pouch-Format E-Commerce Optimization | 70-80% shipping weight reduction enables competitive Amazon pricing against traditional glass jar competitors. |
| Solar-Powered Dehydration Infrastructure | MEE dual carbon mandates in China create operational cost advantages for Yangtze River Delta processing clusters. |
Research Methodology
Multiple input streams — structured interviews with specialty food procurement managers, seasoning house R&D directors, and German import compliance officers; customs and trade flow databases; FDA enforcement action records; and USDA organic certification registries — were reconciled through bottom-up volume triangulation against top-down market sizing. Primary fieldwork with Texas and California chef purchasing networks validated channel-specific demand patterns. Secondary sources included ECHA substance volume tracking disclosures, EU F-Gas Regulation implementation guidance, and regional agricultural harvest reports from Sinaloa and Chihuahua.
Historical shipment data was cross-referenced against panel input from dehydration equipment suppliers and packaging converters to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type tiers, packaging format economics, distribution channel margin structures, and end-user application concentration. CAGRs were derived from slope analysis of normalized volume trajectories, adjusted for pepper supply volatility and clean-label reformulation investment cycles specific to seasoned salt manufacturing.
Revisions become necessary when drought severity in Mexican growing regions, FDA sodium disclosure threshold adjustments, or EU REACH enforcement escalations materialize beyond baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
Garlic Oleoresin Market
Spices and Seasonings
Himalayan Salt Market
Spices and Seasonings
Bolivian Rose Salt Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market
Spices and Seasonings
Asafoetida Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
Malaysia Spices and Seasonings Market
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Frankincense Extract Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
Global Spices and Stimulants Market