
 US Spice and Seasonings Market | 2026-2036
US Spice and Seasonings Market Size, Share, and Industry Trends Forecast 2026-2036
US Spice and Seasonings Market Analytics
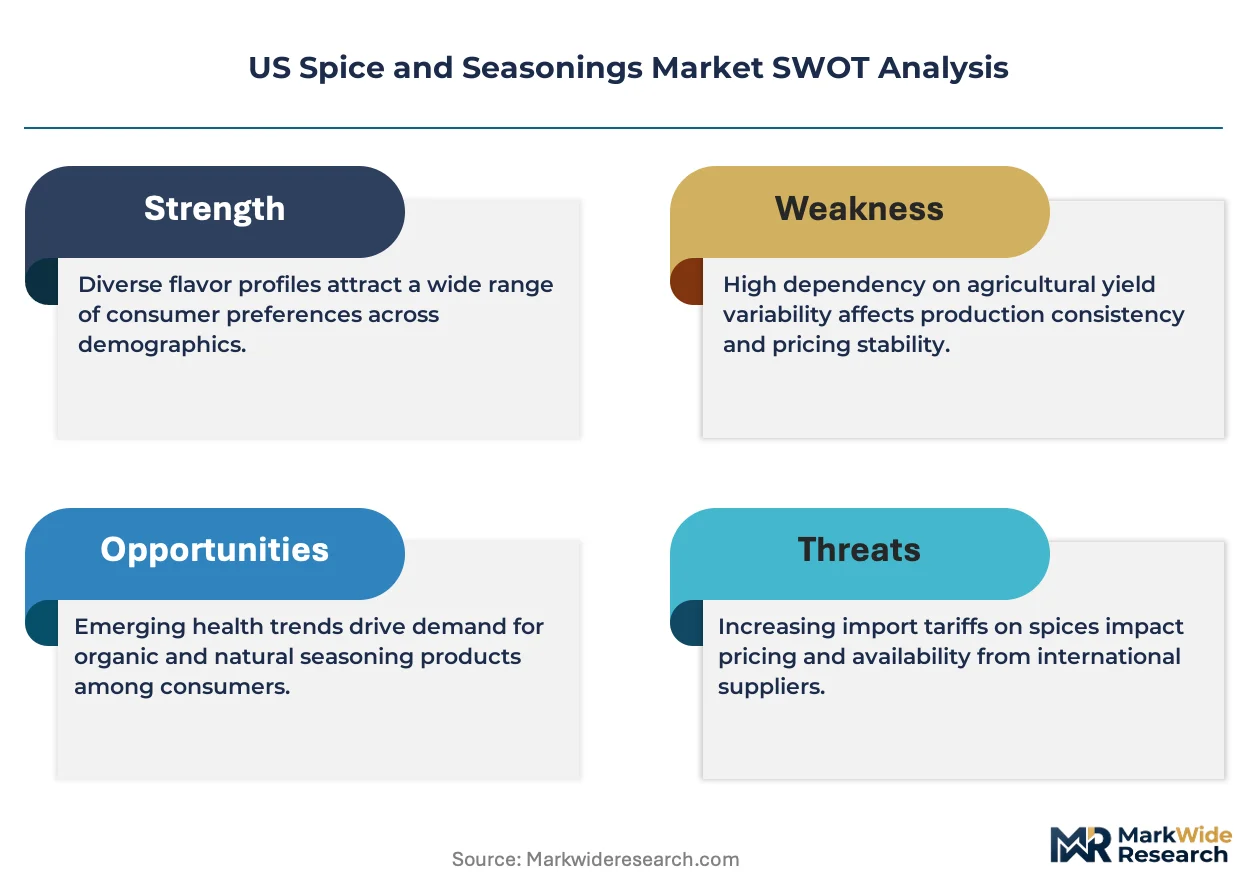
India is rewriting capacity dynamics for US-bound spice supplies as growers expand cardamom and turmeric acreage under export-oriented contracts. McCormick & Company, Incorporated anchors American retail shelf presence through its dominance of grocery channel distribution. Cargill, Incorporated leverages its integrated agricultural sourcing to control upstream pepper and chili supply chains. Kerry Group PLC differentiates through flavor technology leadership in clean-label and sodium-reduction formulations.
Spice and seasonings comprise dried plant-derived materials including seeds, fruits, roots, bark, and leaves processed through grinding, drying, steam treatment, or solvent extraction to achieve specific volatile oil concentrations and microbial reduction targets; these inputs function primarily as flavoring, coloring, preservative, or aromatic agents across food manufacturing and foodservice operations. Blends capture disproportionate margin pools relative to commodity single spices due to proprietary formulation complexity and customer switching costs. The food processing use case leads volume consumption as ready-meal manufacturers and meat processors standardize seasoning inputs for batch consistency across multiple production facilities.
The FDA enforces Current Good Manufacturing Practices and allergen labeling under FSMA, while USDA organic certification shapes premium product positioning and price architecture in retail channels. State-level cottage food laws and commercial kitchen regulations in California and Texas create fragmented compliance burdens for emerging seasoning brands entering foodservice distribution. Stakeholders must monitor evolving FDA guidance on imported spice adulteration testing and the potential harmonization of state-level salt-warning label requirements that could reformulate demand across restaurant and retail segments.
Market Dynamics
Clean-label formulation mandates from FDA's updated FSMA preventive controls are forcing food processors to requalify entire supplier bases, compressing procurement timelines while expanding documentation burdens across Midwest protein processing clusters.
Growth Catalysts
- FSMA Preventive Controls:FDA's updated rules on hazard analysis and risk-based preventive controls are mandating documented supply chain verification, driving demand for certified spice suppliers with validated microbial reduction protocols.
- Protein Processing Clusters:Texas and California meat processing facilities are expanding standardized seasoning input programs to achieve batch consistency across multi-facility operations, concentrating procurement volumes.
- Clean-Label Formulations:Consumer preference shifts toward recognizable ingredient lists are accelerating sodium-reduction and natural preservative formulations in ready-meal manufacturing.
Market Restraints
- Import Adulteration Risk:FDA's intensified testing protocols for imported turmeric and cardamom are extending customs clearance timelines and increasing rejection rates at US ports.
- Climate-Driven Supply Volatility:Indian subcontinent rainfall patterns are creating acreage instability for chili and pepper crops, transmitting price shocks through Cargill's integrated sourcing networks.
- Allergen Labeling Complexity:FALCPA-mandated allergen declarations for celery seed and mustard derivatives are complicating blend formulation and cross-contamination prevention in multi-product facilities.
Strategic Opportunities
- California Cottage Food Expansion:State-level commercial kitchen regulation reforms are lowering barriers for emerging seasoning brands to enter foodservice distribution through streamlined licensing pathways.
- Steam Treatment Technology:Non-thermal microbial reduction methods are hybridizing with traditional grinding operations to meet organic certification requirements without chemical intervention.
- Foodservice Direct Sourcing:Restaurant chain procurement teams are bypassing traditional distributor tiers to establish direct relationships with regional blend manufacturers, compressing margin capture.
Industry Challenges
- Validated Methodology Talent:Food safety laboratories face acute shortages of analysts proficient in FDA's BAM protocols for Salmonella and E. coli detection in high-fat spice matrices.
- Legacy ERP Integration:Mid-tier blend manufacturers struggle to integrate lot traceability systems with customer enterprise resource planning platforms for real-time allergen tracking.
- Organic Certification Timelines:USDA National Organic Program accreditation processes are extending 18-24 months, delaying premium positioning for reformulated product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Spice and Seasonings Market |
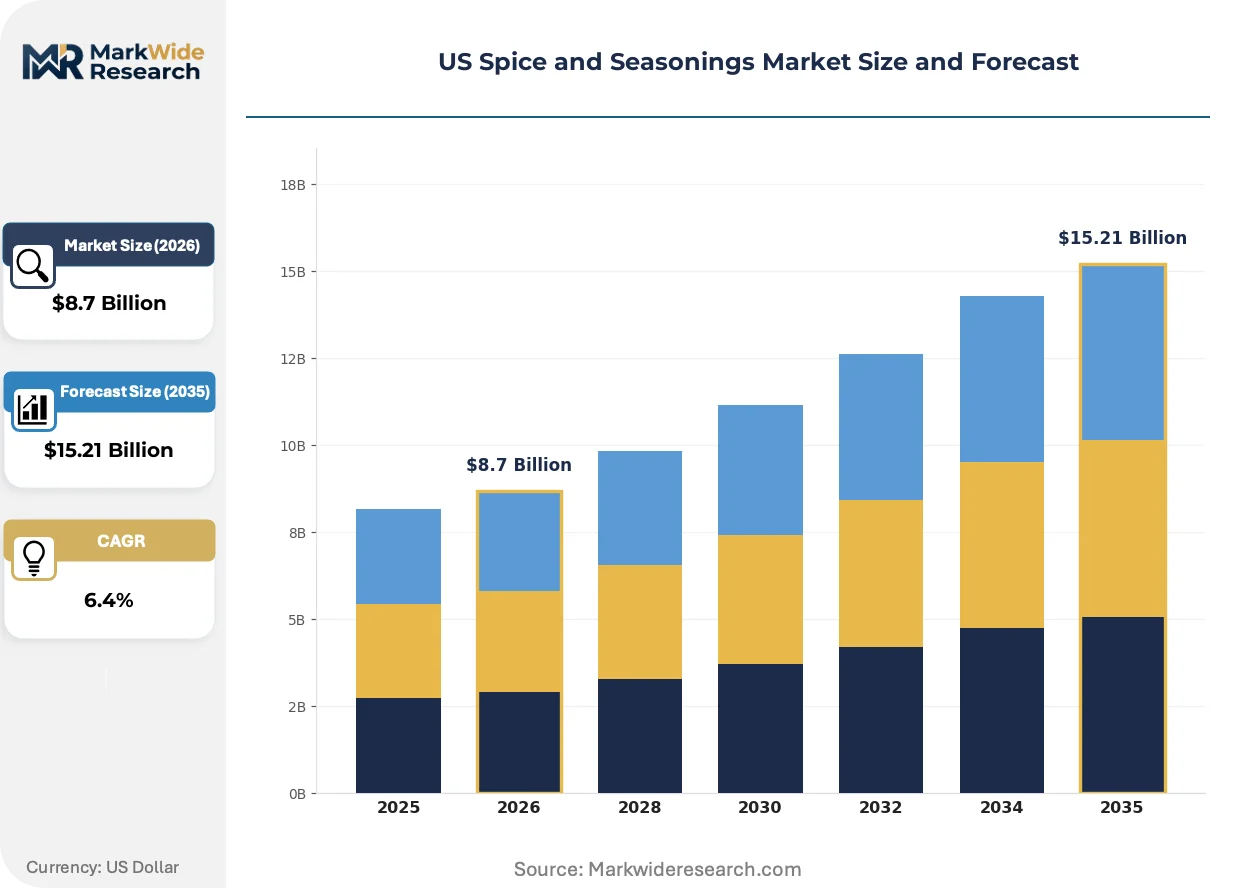
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Spices, Blends, Seasoning Mixes Use Case: Home Cooking, Food Processing, Restaurant, Catering Distribution Channel: Retail Stores, Online, Wholesale, Foodservice Packaging Type: Bags, Jars, Tubs, Bulk Packaging |
| Companies Covered | Cargill, Incorporated, Watkins Incorporated, McCormick & Company, Incorporated, Associated British Foods plc, Ajinomoto Co., Inc., Kerry Group PLC, Olam Group, SHS Group, Sensient Technologies Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Spice and Seasonings Market Evolving Landscape
Volatile oil extraction technologies and non-thermal processing methods are rewriting quality benchmarks while regulatory harmonization pressures reshape supplier qualification protocols across state boundaries.
Supercritical CO2 extraction technology is hybridizing with conventional solvent-based methods to achieve higher volatile oil concentrations in cardamom and black pepper oleoresins. Ready-meal manufacturers in the Midwest are adopting these extracts at accelerated procurement cycles to standardize flavor intensity across production batches. This technology compression is enabling cleaner-label declarations while reducing dependency on synthetic flavor adjuncts.
FDA's draft guidance on imported spice adulteration testing is mandating expanded analytical screening for undeclared dyes and heavy metals at port of entry. The industrial consequence is a bifurcation between suppliers with in-house laboratory capabilities and those dependent on third-party certification. California and Texas food processing clusters are most affected, with procurement teams demanding certificate of analysis documentation for every lot received.
Chain restaurant procurement departments are consolidating supplier rosters from twelve-vendor portfolios to three-vendor strategic partnerships, prioritizing those with multi-product capabilities and validated food safety systems. This concentration is displacing fragmented regional spice distributors who lack integrated blending and testing infrastructure. The shift is most visible in Texas protein processing corridors where QSR chains are standardizing seasoning inputs across hundreds of franchise locations.
US Spice and Seasonings Market Segmentation
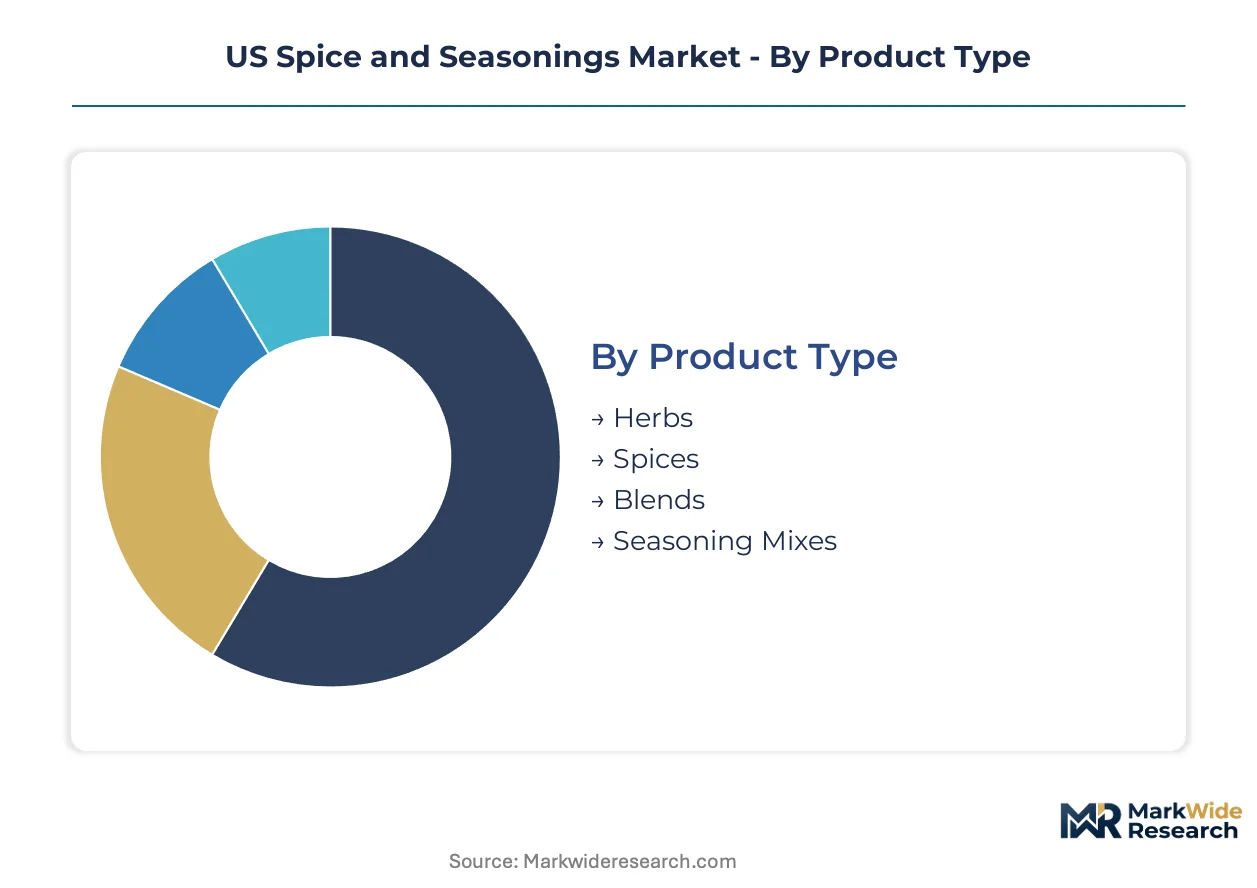
Segmentation in the US spice and seasonings market reveals how procurement patterns diverge between industrial-scale food manufacturing and fragmented foodservice operations. Understanding these divisions exposes where margin pools concentrate and where regulatory compliance burdens weigh heaviest on supplier economics.
Product Type:
The use-case spectrum spans from commodity raw materials to proprietary formulation assets that lock in customer switching costs.
- Herbs:Dried leaves and flowering parts processed to specific moisture content and volatile oil retention specifications. Demand concentrates in California organic retail channels where USDA certification commands shelf space premiums. FSSAI-exported Indian basil and oregano face extended FDA adulteration screening timelines at West Coast ports.
- Spices:Seeds, fruits, roots, and bark standardized to microbial load and volatile oil benchmarks. Texas and California protein processors dominate procurement volumes as they standardize inputs across multi-facility operations under FSMA preventive control mandates.
- Blends:Multi-component formulations with proprietary ratios and grinding specifications.
- Seasoning Mixes:Pre-formulated combinations including anti-caking agents and flow aids for industrial-scale dispensing.
Established volume favors Spices; emerging adoption favors Blends.
Use Case:
Cost tier separation runs from commodity procurement at industrial scale to premium positioning in direct-to-consumer channels.
- Home Cooking:Retail-packaged units for individual consumers.
- Food Processing:Bulk inputs for ready-meal manufacturers and meat processors requiring batch consistency documentation. Midwest protein processing clusters are expanding standardized seasoning programs to achieve uniformity across multiple production facilities under FDA's updated preventive control rules.
- Restaurant:Foodservice-grade packaging for back-of-house preparation. Texas QSR chains are consolidating supplier rosters from twelve-vendor portfolios to three-vendor partnerships, demanding integrated blending and validated food safety systems.
- Catering:High-volume institutional supply with extended shelf-life requirements.
Margin compression concentrates in Catering; pricing power accumulates in Food Processing.
Distribution Channel:
Customer type determines whether procurement flows through consolidated distributor tiers or direct manufacturer relationships.
- Retail Stores:Grocery and mass merchandiser shelf placement governed by slotting fees and planogram negotiations. McCormick's dominance of this channel reflects decades of distribution infrastructure investment.
- Online:Direct-to-consumer and third-party marketplace sales with subscription model potential.
- Wholesale:Intermediate distribution to independent retailers and regional foodservice operators.
- Foodservice:Direct supply to restaurant chains, institutional kitchens, and contract caterers. Chain procurement teams are bypassing traditional distributor tiers to establish direct relationships with regional blend manufacturers, compressing margin capture for intermediaries.
Channel control consolidates in Foodservice; fragmentation persists in Wholesale.
Packaging Type:
Supply concentration in flexible packaging versus rigid formats shapes logistics economics and shelf-life performance.
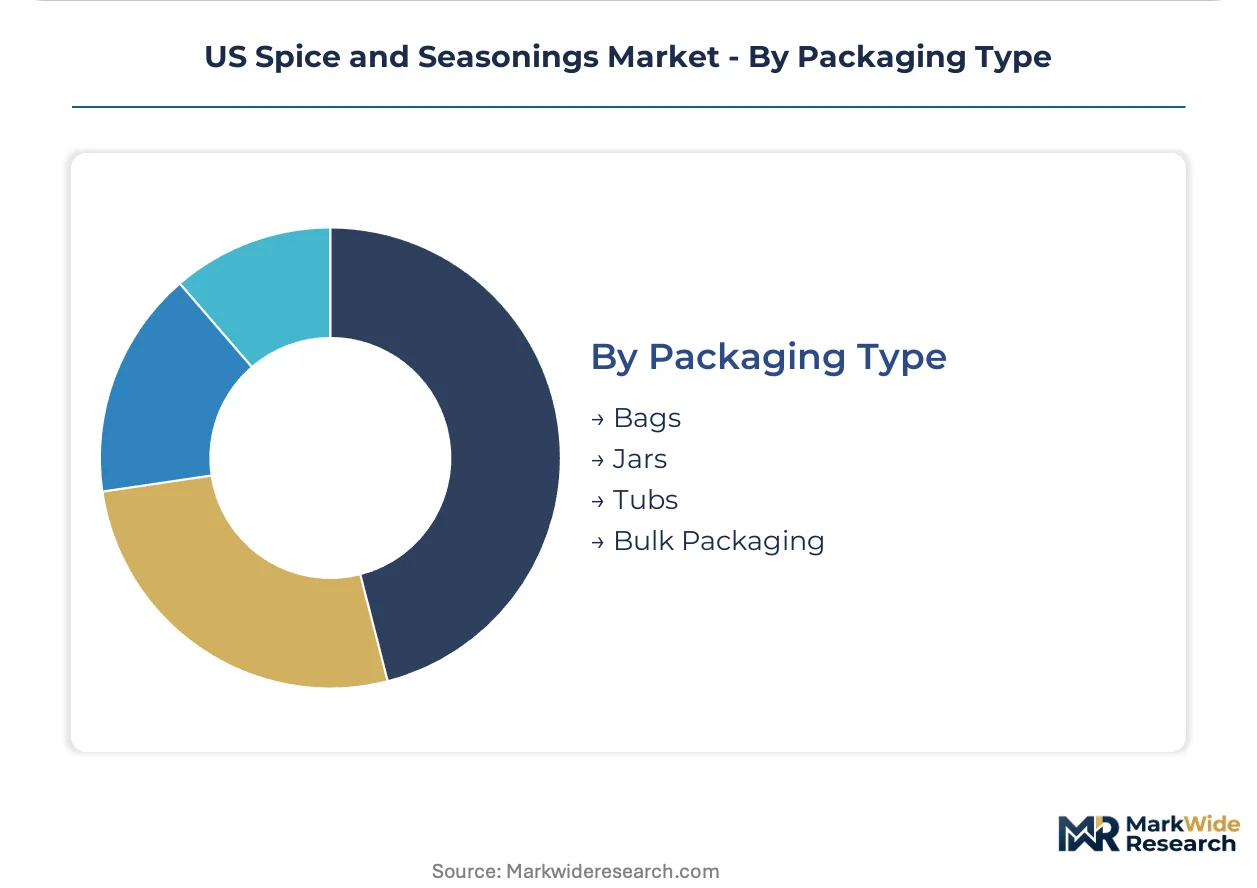
- Bags:Flexible film structures for retail and foodservice portion control.
- Jars:Glass containers for premium retail positioning with resealability.
- Tubs:Rigid plastic for industrial-scale food manufacturing with scoop dispensing. Midwest ready-meal manufacturers prefer this format for automated production line integration.
- Bulk Packaging:Supersacks and fiber drums for food processing procurement. Texas and California meat processing facilities drive demand for validated lot traceability on these shipments under FSMA supply chain verification requirements.
Operational scale favors Bulk Packaging; brand differentiation favors Jars.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spice processing capacity clusters along three distinct corridors in the United States, each shaped by proximity to agricultural inputs, protein processing demand, and port access for imported raw materials. The Midwest, Texas Gulf Coast, and California Central Valley dominate procurement volumes and supplier qualification protocols.
Texas Gulf Coast
Meat processing corridors around Houston and Dallas-Fort Worth drive concentrated seasoning demand as multi-facility operators standardize inputs across hundreds of locations. USDA FSIS inspection protocols govern slaughterhouse-adjacent spice handling facilities. San Antonio blend manufacturers are expanding validated food safety systems to capture QSR chain procurement consolidation.
California Central Valley
Organic retail channels command premium shelf space for USDA-certified herbs and spices in Los Angeles and San Francisco metro areas. FDA's intensified adulteration screening for turmeric and cardamom extends customs clearance at Port of Oakland and Port of Long Beach. Fresno County food processors are adopting steam treatment technologies to meet organic certification without chemical intervention.
Midwest Protein Belt
Chicago and St. Louis ready-meal manufacturers are expanding standardized seasoning programs to achieve batch consistency under updated FSMA preventive control mandates. Illinois and Iowa food safety laboratories face acute analyst shortages for BAM protocol execution. Minneapolis-St. Paul blenders are integrating lot traceability systems with customer ERP platforms for real-time allergen tracking.
Southeast Atlantic
Georgia and North Carolina poultry processors are requalifying supplier bases to comply with documented supply chain verification requirements. State-level commercial kitchen regulations in Florida create fragmented compliance pathways for emerging seasoning brands. Atlanta foodservice distributors are consolidating portfolios from twelve-vendor arrangements to three-vendor strategic partnerships.
Pacific Northwest
Seattle and Portland metro areas concentrate demand for clean-label and sodium-reduction formulations in specialty retail channels. Oregon and Washington cottage food law reforms are streamlining licensing for small-batch seasoning producers. Vancouver, Washington, facilities are processing Indian-sourced cardamom and turmeric under expanded export-oriented contracts.
US Spice and Seasonings Market Competitive Landscape
Vertically integrated agricultural conglomerates and flavor technology specialists split the market between upstream supply control and downstream formulation expertise. Consolidation pressures concentrate procurement power among protein processors and restaurant chains, compressing margins for mid-tier regional distributors. Three archetypes dominate: integrated agricultural traders with captive sourcing networks, retail shelf-space incumbents with decades of distribution infrastructure, and clean-label formulation specialists with proprietary extraction capabilities. Competitive moves center on supplier roster consolidation by foodservice buyers and backward integration into grinding and blending operations.
Among integrated agricultural traders, Cargill, Incorporated and Olam Group exemplify upstream control over pepper and chili supply chains through export-oriented contracting with Indian growers. McCormick & Company, Incorporated anchors retail channel presence through grocery distribution infrastructure investment. Kerry Group PLC occupies a position within the clean-label formulation tier, differentiating through sodium-reduction and natural preservative expertise.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Watkins Incorporated |
| McCormick & Company, Incorporated |
| Associated British Foods plc |
| Ajinomoto Co., Inc. |
| Kerry Group PLC |
| Olam Group |
| SHS Group |
| Sensient Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in California Central Valley steam treatment facilities is compressing margins for organic-certified spice processors while simultaneously elevating pricing power for validated suppliers serving Texas protein processing corridors under FSMA preventive control mandates.
Pricing Analysis
USDA National Organic Program certification dictates the pricing tier structure across the US spice and seasonings market. Three-tier pricing structure across premium organic, standard commercial, and economy conventional levels separates certified steam-treated products from chemically processed alternatives. Pricing pressure stems from FSMA-mandated supply chain verification documentation, which elevates compliance costs for mid-tier blenders. Food processing procurement teams demonstrate lowest price sensitivity due to batch consistency requirements, while emerging cottage food producers in California exhibit highest sensitivity to certification premiums.
Supply Chain Analysis
Extended payment terms from Texas QSR chains are straining working capital for regional blend manufacturers dependent on Indian cardamom and turmeric sourcing. Raw material flows draw from Indian subcontinent pepper and chili cultivation, Vietnamese cinnamon bark harvesting, and Indonesian clove production. Single-source vulnerability concentrates in Cargill's integrated Indian pepper networks exposed to monsoon-driven acreage instability. Distribution runs through consolidated foodservice direct channels bypassing traditional wholesale tiers, with bulk packaging dominating Midwest ready-meal manufacturer procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US spice and seasonings market functions as a defensive-moat industry where regulatory entrenchment through FSMA preventive control compliance creates substantial switching costs for food processing procurement teams.
For Market Incumbents: Harden validated food safety infrastructure against emerging regional blenders capturing QSR direct sourcing relationships. Expand backward integration into Indian turmeric and cardamom export-oriented contracting to secure supply under FDA's intensified adulteration screening protocols. Prioritize ERP integration capabilities for real-time lot traceability demanded by multi-facility protein processors.
For New Entrants and Emerging Players: Pacific Northwest sodium-reduction formulation demand represents underpenetrated white space where Kerry Group's technology leadership has not fully consolidated positioning. California cottage food law reforms enable streamlined licensing pathways for small-batch organic herb producers targeting specialty retail channels. Foodservice direct relationships with regional restaurant chains offer the most penetrable go-to-market angle against McCormick's grocery channel dominance.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among blend manufacturers with multi-year supply agreements to protein processing clusters. Long-term viability across the analysis window favors targets with integrated laboratory capabilities for BAM protocol execution and in-house steam treatment infrastructure. Monitor FDA guidance finalization on imported spice adulteration testing as the primary inflection signal for supplier roster consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indian Sourcing | Cargill's export-oriented contracting model secures upstream pepper supply against FDA rejection risk. |
| Steam Treatment Technology Deployment | Fresno County processors adopt non-thermal microbial reduction to maintain organic certification eligibility. |
| Foodservice Direct Sourcing Relationships | Texas QSR chains bypass distributor tiers to compress margin capture for fragmented regional blenders. |
| ERP Integration for Lot Traceability | Minneapolis-St. Paul blenders connect systems to customer platforms for real-time allergen tracking compliance. |
| Sodium-Reduction Formulation R&D | Kerry Group's clean-label expertise captures Midwest ready-meal manufacturer procurement for reformulated lines. |
Research Methodology
Initial hypotheses were tested against primary input from food safety laboratory directors, protein processing procurement managers, spice blending facility operators, and FDA regulatory affairs specialists and refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of FDA FSMA guidance documents, USDA National Organic Program accreditation records, customs import data for turmeric and cardamom shipments, and SEC filings from publicly traded seasoning companies. Bottom-up demand modeling from food processing facility expansion announcements triangulated against top-down market sizing from trade flow analysis.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across product type, use case, distribution channel, and packaging format plus regional regulatory cluster differentiation. CAGRs derived from historical procurement volume trajectories at Texas and California protein processing facilities, cross-referenced with Indian agricultural export data and FSMA compliance cost surveys. Forecast inputs incorporated FDA adulteration testing protocol evolution and climate-driven Indian subcontinent rainfall pattern volatility.
Practitioners should monitor FDA final guidance publication on imported spice screening, USDA organic certification timeline extensions, and Indian monsoon pattern deviation for early signals of forecast revision necessity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Herb Oil Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Cinnamon Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Ghost Pepper Salt Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Chef Bases Market
Spices and Seasonings
Habanero Salt Market