
 Tamarind Extract Market | 2026-2036
Tamarind Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Tamarind Extract Market Analysis
The capital-intensity gap between artisanal processors and industrial extractors is collapsing as automated solvent recovery and spray-drying equipment becomes accessible at smaller scales. Symrise AG leverages captive agronomy partnerships in Madagascar to secure tartaric acid-rich cultivars. Kanegrade Limited anchors European supply through BRC-certified processing in the United Kingdom. Magma Foods dominates South Asian bulk supply with integrated pulp-to-powder operations.
Tamarind extract comprises the concentrated soluble solids derived from Tamarindus indica pulp, typically standardized to tartaric acid content between tartaric acid equivalents and preserved through pasteurization or low-temperature evaporation to retain polyphenolic activity. Manufacturers deploy it primarily as a natural acidulant, viscosity modifier, and browning agent across food, pharmaceutical, and cosmetic matrices. Powder formats lead volume due to extended shelf stability and freight efficiency, while liquid concentrates capture premium positioning in beverage and sauce applications where rapid solubility matters. The pharmaceutical segment shows fastest trajectory as capsule-grade extracts gain traction in glycemic management formulations.
The FDA's GRAS self-affirmation pathway and the European Food Safety Authority's Novel Food catalog govern market access for new tamarind-derived ingredients in Western jurisdictions. India's FSSAI mandates pesticide residue limits and heavy metal thresholds that directly shape export-oriented cultivation practices. Stakeholders must monitor evolving pharmacopeial monographs and adapt extraction protocols to meet divergent purity specifications across regulatory zones.
Market Dynamics
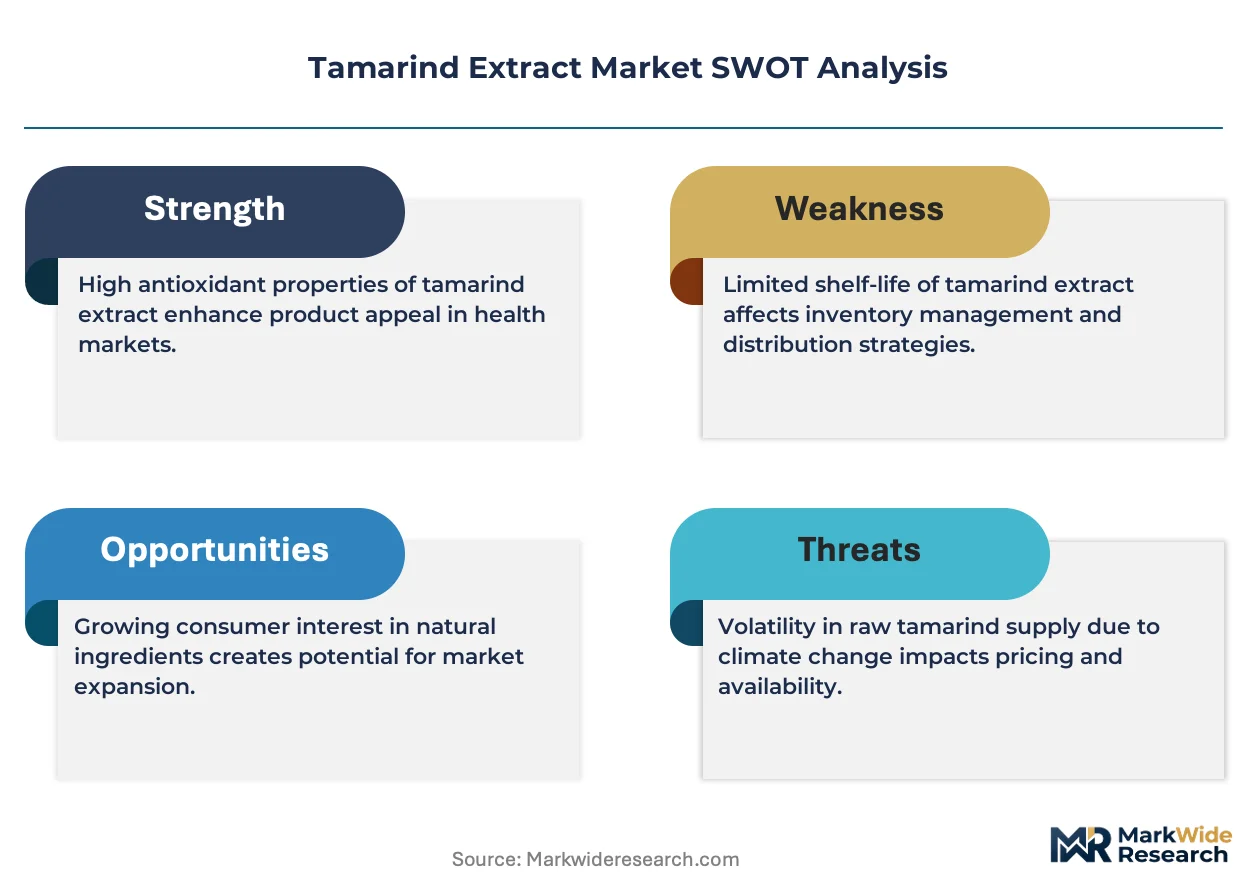
Clean-label reformulation mandates across Western food markets are compressing synthetic acidulant supply chains and forcing manufacturers toward botanical substitutes with verifiable tartaric acid standardization.
Growth Catalysts
- India's PLI scheme for food processing:Capital subsidies for integrated pulp-to-extract operations are expanding commercial-scale capacity in Tamil Nadu and Karnataka processing clusters.
- Beverage acidulant substitution:Carbonated and functional drink manufacturers are replacing citric acid with tamarind-derived alternatives to achieve non-GMO and organic certification compliance.
- Spray-drying equipment democratization:Automated solvent recovery systems at sub-industrial scale are collapsing minimum viable plant thresholds for regional processors.
Market Restraints
- Raw pulp price volatility:Irregular monsoon patterns across Maharashtra and Andhra Pradesh supply belts create tartaric acid yield uncertainty that squeezes processor margins.
- EU Novel Food Regulation friction:EFSA's extended safety assessment timelines for new extract concentrations delay product launches by 18-24 months versus GRAS jurisdictions.
- Enzymatic extraction substitution:Fermentation-derived tartaric acid from glucose feedstocks offers batch-to-batch consistency that botanical extracts struggle to match.
Strategic Opportunities
- Pharmaceutical glycemic management:Capsule-grade extracts targeting postprandial glucose modulation are penetrating clinical nutrition formulations with pharmacopeial monograph compliance.
- EU Green Deal bioeconomy incentives:Horizon Europe funding streams for circular biomass valorization are subsidizing tamarind waste-to-extract pilot plants in Portugal and Spain.
- Cosmetic active ingredient positioning:Polyphenol-rich concentrates are displacing synthetic antioxidants in K-beauty and J-beauty anti-aging serum formulations.
Industry Challenges
- Pharmacopeial monograph divergence:USP, EP, and IP specifications for heavy metal limits and microbial contamination require parallel extraction protocols that fragment quality systems.
- Skilled extraction technician scarcity:Solvent recovery optimization and polyphenol retention calibration demand specialized training unavailable in secondary processing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tamarind Extract Market |
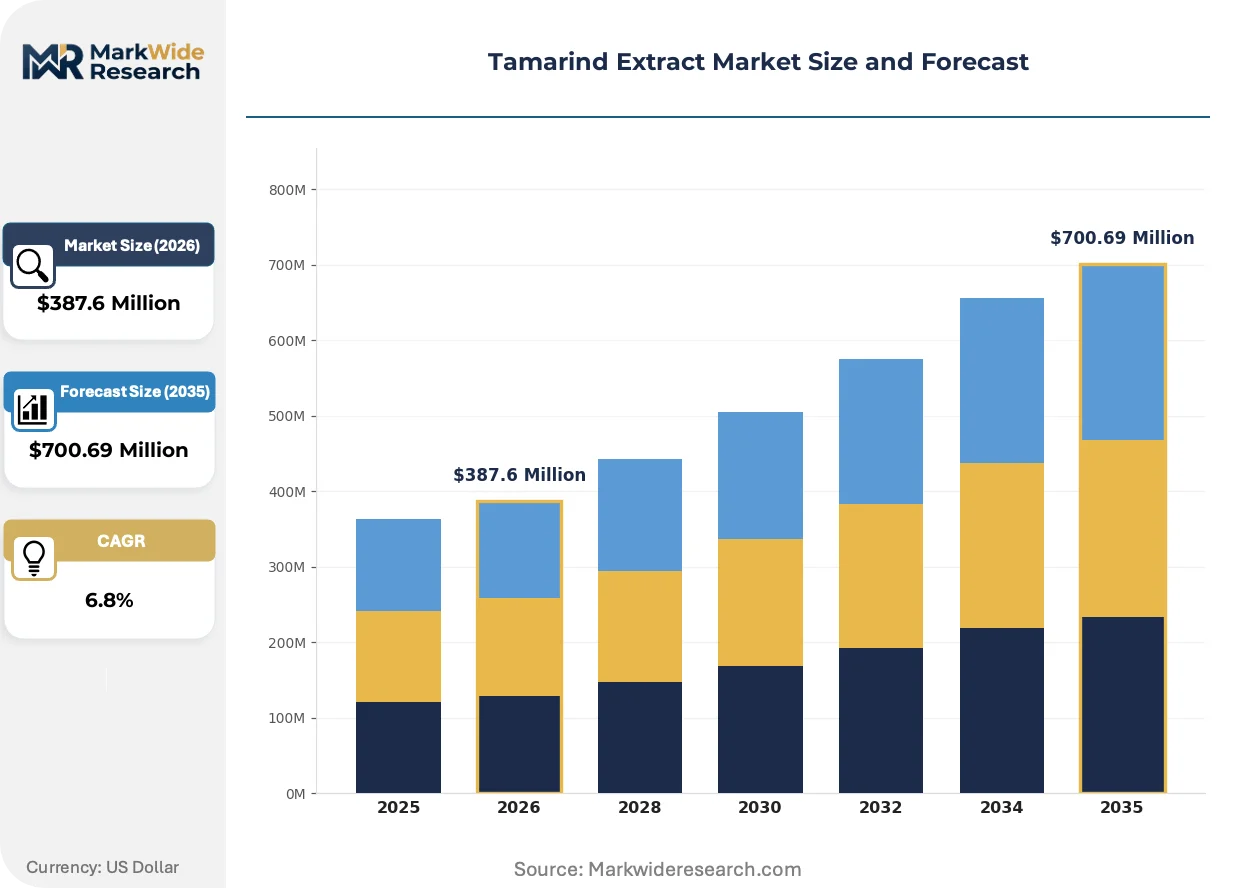
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Concentrate, Capsule End User: Food Industry, Pharmaceutical Companies, Cosmetics, Animal Feed Application: Flavoring, Preservative, Nutritional Supplement, Natural Color Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Magma Foods, ABC International, Symrise AG, Organic Herb Inc., Shimla Hills, Givaudan SA, Kanegrade Limited, The Green Labs LLC, Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tamarind Extract Market Emerging Trajectories
Extraction technology convergence with precision fermentation and AI-driven cultivar selection is compressing development cycles and reshaping competitive differentiation around bioactive standardization rather than commodity volume.
Supercritical CO2 extraction systems for polyphenol isolation are miniaturizing from industrial-scale installations to modular 50-liter units accessible to mid-tier processors. Functional food manufacturers in Germany and the Netherlands are piloting these units for custom tartaric acid-to-polyphenol ratio formulations. The capital barrier between artisanal and industrial processing tiers is dissolving, enabling regional players to compete on specification flexibility rather than scale economies.
REACH registration requirements for imported botanical extracts are tightening contaminant disclosure thresholds and forcing Southeast Asian suppliers toward third-party laboratory certification partnerships. The European Chemicals Agency's updated guidance on botanical substance dossiers is extending compliance preparation timelines. Extract importers are responding by consolidating supplier relationships with processors holding ISO 17025-accredited testing capabilities.
Direct procurement relationships between end-use manufacturers and cultivator cooperatives are displacing multi-layered trader networks in Madagascar and Thailand. Food and pharmaceutical formulators are establishing volume-commitment contracts with specific tartaric acid concentration guarantees. This disintermediation is most pronounced in French and Italian markets where traceability documentation supports clean-label marketing claims.
Tamarind Extract Market Segmentation
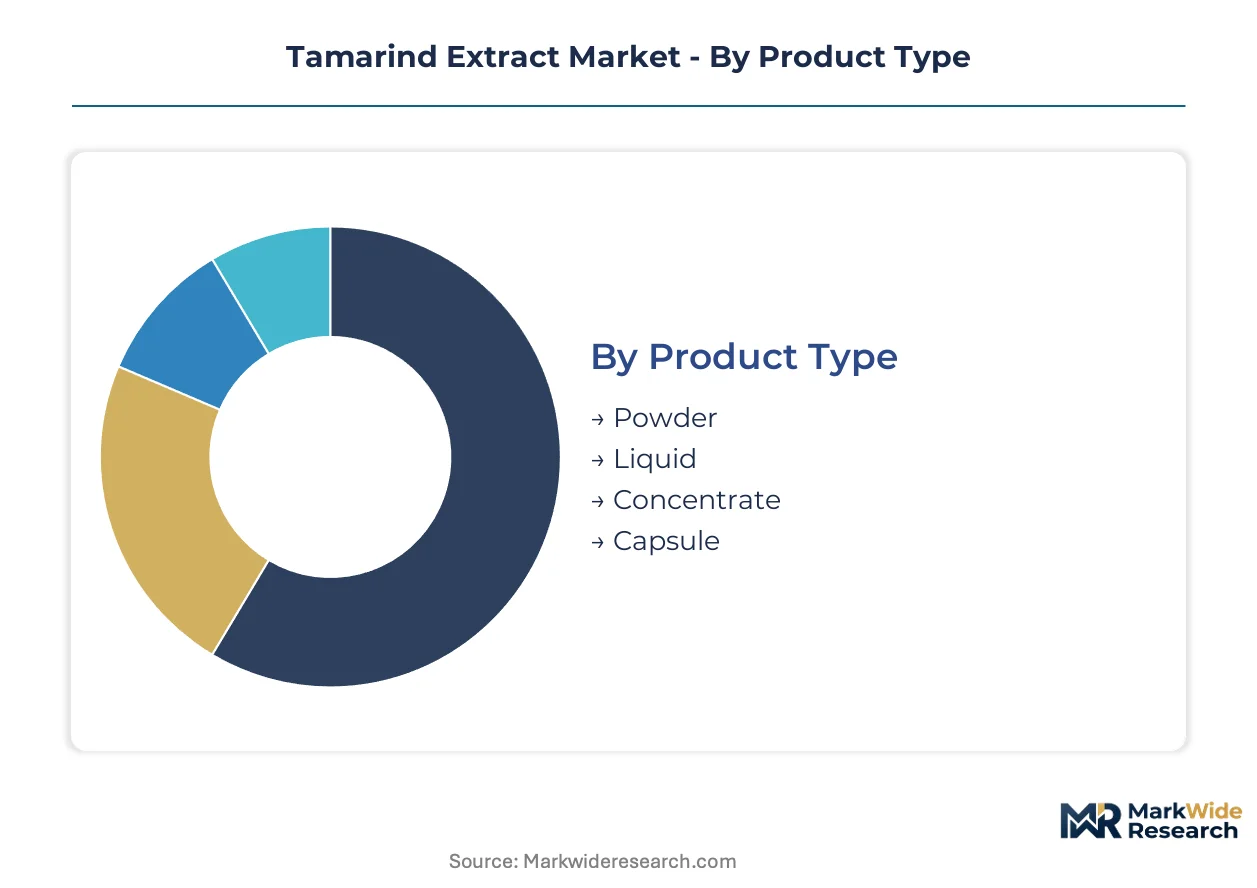
Tamarind extract segmentation reflects divergent margin structures across physical formats and regulatory complexity tiers. Pharmaceutical-grade specifications command premium positioning against commodity food-grade volumes.
Product Type:
Premium returns concentrate in formats requiring pharmacopeial certification and low-temperature processing infrastructure.
- Powder:Spray-dried soluble solids standardized to tartaric acid content between 10-20% with extended shelf stability. Demand clusters in Southeast Asian export processing zones where freight efficiency drives format selection for bulk food manufacturing.
- Liquid:Pasteurized concentrates retaining native polyphenolic activity for rapid solubility in beverage matrices. European formulation centers in Germany and the Netherlands are rotating procurement toward liquid formats for sauce and functional drink applications requiring clean-label acidulant performance.
- Concentrate:High-viscosity pulp reductions for industrial-scale viscosity modification.
- Capsule:Pharmacopeial-grade extracts meeting USP heavy metal and microbial specifications for glycemic management formulations.
Powder holds installed capacity. Liquid is rotating up the share rankings.
End User:
Application sophistication determines margin tier, with clinical nutrition and cosmeceutical specifications outpacing commodity food acidulant returns.
- Food Industry:Clean-label reformulation mandates across carbonated and functional beverage manufacturing are compressing synthetic acidulant supply chains. India's FSSAI pesticide residue limits directly shape export-oriented cultivation practices for this volume segment.
- Pharmaceutical Companies:Capsule-grade extracts targeting postprandial glucose modulation require parallel USP, EP, and IP extraction protocols. EFSA's Novel Food Regulation extended assessment timelines create 18-24 month launch delays versus FDA GRAS jurisdictions.
- Cosmetics:Polyphenol-rich concentrates for anti-aging serum formulations.
- Animal Feed:Standardized acidulant for palatability enhancement in compound feed manufacturing.
Food Industry maintains volume dominance. Pharmaceutical Companies are climbing the fastest toward margin leadership.
Application:
Functional positioning intensity separates pricing tiers, with therapeutic claims requiring substantiation investment that commodity flavoring avoids.
- Flavoring:Natural acidulant replacement for citric acid in non-GMO and organic certification pathways. Beverage manufacturers in France and Italy are establishing direct procurement relationships with Madagascar cultivator cooperatives to secure tartaric acid concentration guarantees supporting traceability marketing claims.
- Preservative:pH reduction and water activity control in sauce and condiment matrices.
- Nutritional Supplement:Standardized extracts for glycemic management positioning in clinical nutrition.
- Natural Color:Browning agent functionality in baked goods and confectionery applications.
Flavoring commands installed capacity scale. Nutritional Supplement is gaining share fastest through pharmacopeial compliance premiums.
Distribution Channel:
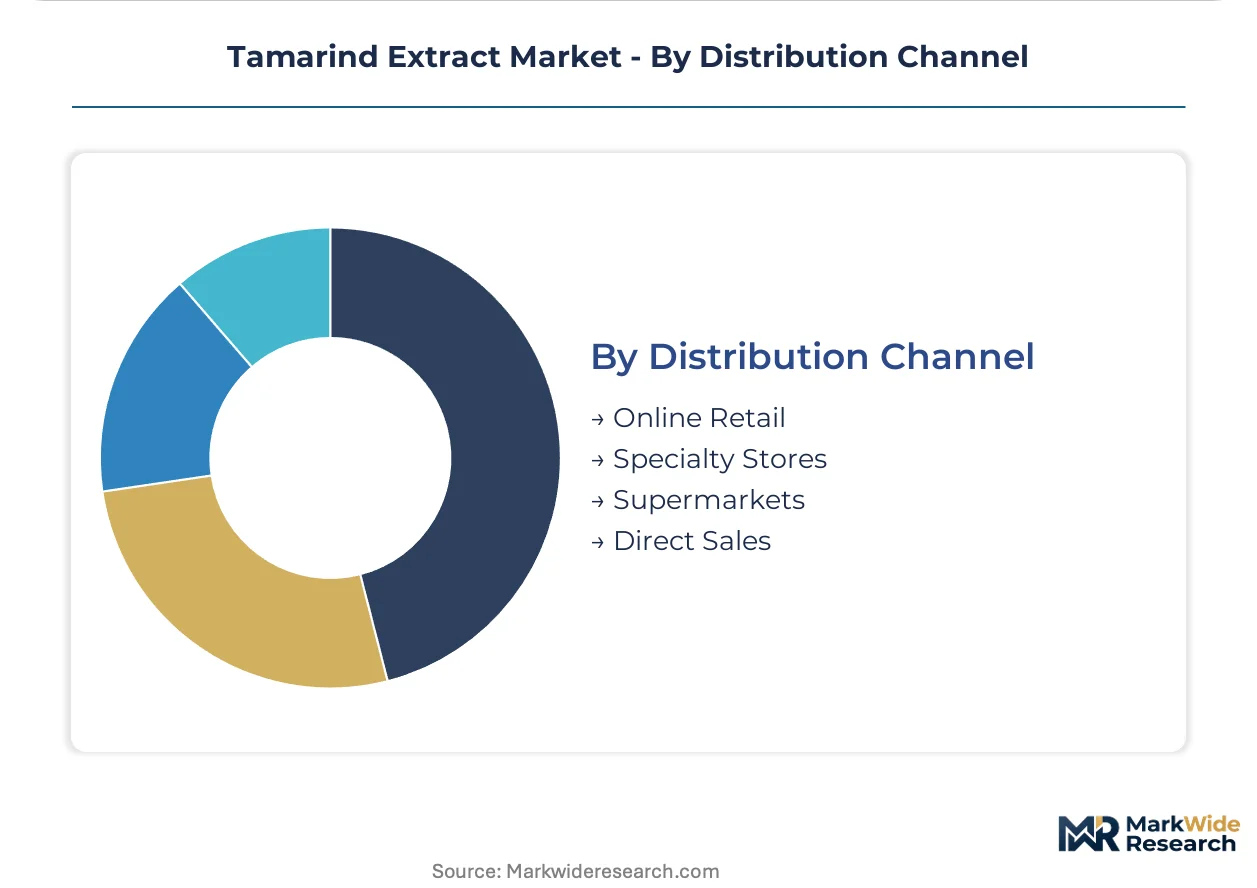
Channel selection reflects buyer scale and specification complexity, with direct relationships capturing value from disintermediated trader networks.
- Direct Sales:Volume-commitment contracts between end-use manufacturers and integrated pulp-to-powder processors. Symrise AG's captive agronomy partnerships in Madagascar exemplify this channel's traceability and tartaric acid concentration guarantee capabilities.
- Specialty Stores:Small-batch procurement for artisanal food manufacturers and regional cosmetic formulators.
- Online Retail:E-commerce platforms for mid-tier processors accessing automated solvent recovery equipment at sub-industrial scale.
- Supermarkets:Limited retail shelf presence for consumer-facing tamarind concentrate products.
Direct Sales holds installed capacity. Online Retail is rotating up the share rankings through equipment democratization enabling regional processor participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with European formulators paying pharmacopeial premiums while Indian processors absorb raw pulp volatility. Southeast Asian supply clusters compete on tartaric acid standardization. Regional differentiation sharpens around regulatory compliance tiers and extraction technology access.
India
Integrated pulp-to-powder operations in Tamil Nadu and Karnataka processing clusters drive volume. India's PLI scheme for food processing subsidizes capital equipment for commercial-scale extractors. Maharashtra and Andhra Pradesh supply belts face irregular monsoon patterns that compress processor margins through tartaric acid yield uncertainty.
Germany
Functional beverage manufacturers in Hamburg and Cologne rotate procurement toward liquid concentrates for rapid solubility applications. EFSA's Novel Food Regulation extends safety assessment timelines for new extract concentrations. Supercritical CO2 extraction pilots in the Netherlands border region enable custom tartaric acid-to-polyphenol ratio formulations for German formulators.
United States
FDA GRAS self-affirmation pathways attract capsule-grade extract launches targeting glycemic management formulations. Carbonated drink manufacturers replace citric acid with tamarind-derived alternatives to secure non-GMO and organic certification compliance. Direct procurement relationships with Madagascar cultivator cooperatives bypass multi-layered trader networks for traceability documentation.
Thailand
Bulk powder exports to Southeast Asian food manufacturing hubs sustain freight-efficient format demand. REACH registration requirements for EU-bound botanical extracts force third-party ISO 17025-accredited laboratory certification partnerships. Bangkok-centered processing operations face margin pressure from enzymatic tartaric acid substitution via fermentation-derived alternatives.
France
Cosmetic formulators in Paris and Lyon displace synthetic antioxidants with polyphenol-rich concentrates for anti-aging serum positioning. Horizon Europe funding streams under the EU Green Deal subsidize circular biomass valorization pilot plants. Direct volume-commitment contracts with specific tartaric acid concentration guarantees support clean-label marketing claims in French retail channels.
Tamarind Extract Market Vendor Landscape
Concentration sits with integrated agronomy-to-extract processors controlling captive cultivar partnerships. The vendor base spans multinational flavor houses, regional pulp-to-powder specialists, and equipment-democratized mid-tier entrants. Three archetypes dominate: captive supply chain integrators, specification-flexible regional processors, and pharmacopeial-grade compliance specialists. Competitive moves center on backward integration into cultivation partnerships and automated solvent recovery capacity expansion.
Among captive supply chain integrators, Symrise AG exemplifies agronomy partnership models securing tartaric acid-rich cultivar access. Kanegrade Limited anchors European positioning through BRC-certified processing infrastructure. Magma Foods occupies the South Asian bulk supply tier with integrated pulp-to-powder operations. These three represent distinct competitive vectors: cultivar control, certification anchoring, and vertical scale.
| Leading Market Players |
|---|
| Magma Foods |
| ABC International |
| Symrise AG |
| Organic Herb Inc. |
| Shimla Hills |
| Givaudan SA |
| Kanegrade Limited |
| The Green Labs LLC |
| Kerry Group plc |
| Others |
Supply Flow & Price Mechanics
REACH registration requirements for botanical extracts gate both supplier qualification and price differentiation simultaneously, forcing Southeast Asian processors toward ISO 17025-accredited certification partnerships that separate premium pharmacopeial tiers from commodity food-grade volumes.
Pricing Analysis
Configured-to-order pricing for custom tartaric acid-to-polyphenol ratios commands substantial premiums over standard spray-dried powder quotations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale. Pricing pressure stems from enzymatic tartaric acid substitution via fermentation-derived alternatives that offer batch-to-batch consistency. Pharmaceutical formulators exhibit lowest price sensitivity due to pharmacopeial compliance requirements, while commodity food manufacturers face acute cost compression.
Supply Chain Analysis
Strategic stockpile preferences dominate among European formulators facing EFSA Novel Food assessment delays, while just-in-time procurement characterizes beverage manufacturers with rapid reformulation cycles. Raw pulp supply concentrates in India, Madagascar, and Thailand, drawing from tamarind orchards in Maharashtra, coastal cultivation belts, and northeastern growing regions. Processor operations rest on solvent recovery equipment, spray-drying infrastructure, and tartaric acid standardization testing capacity. Single-source vulnerability runs through Madagascar's cultivar-specialized agronomy partnerships. Distribution runs through direct volume-commitment contracts that disintermediate traditional trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray-drying equipment democratization constitutes a technological inflection that collapses minimum viable scale thresholds and enables mid-tier processor entry across high-growth clean-label reformulation demand.
For Market Incumbents: Compound backward integration into captive cultivar partnerships in Madagascar and Thailand to secure tartaric acid concentration guarantees against enzymatic substitution threats. Expand automated solvent recovery capacity in Tamil Nadu processing clusters to defend margin position from regional equipment-democratized entrants. Prioritize pharmacopeial monograph compliance investment across USP, EP, and IP specifications to maintain premium tier access. For New Entrants and Emerging Players: Custom extraction service gaps in German and Dutch functional beverage formulation centers offer white-space penetration where incumbents under-serve rapid solubility specification demands. Target mid-tier cosmetic manufacturers in French and Italian markets seeking polyphenol-rich concentrates for anti-aging serum positioning with flexible minimum order quantities. Deploy modular supercritical CO2 extraction units for tartaric acid-to-polyphenol ratio customization as the primary go-to-market angle. For Investors and Strategic Acquirers: EFSA's extended Novel Food safety assessment timelines reshape the acquisition landscape toward processors with established EU regulatory dossier capabilities and ISO 17025-accredited testing infrastructure. Long-term viability centers on integrated pulp-to-extract operators with cultivator cooperative volume-commitment contracts spanning the projection horizon. Acquisition target archetype: regional processors in Portugal and Spain positioned for EU Green Deal circular biomass valorization funding. Monitor enzymatic tartaric acid cost curves as the signal for botanical extract margin compression thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cultivar Partnerships | Symrise AG's Madagascar agronomy agreements secure tartaric acid-rich genetic access against yield volatility. |
| Pharmacopeial Compliance Investment | Parallel USP, EP, and IP extraction protocols unlock capsule-grade glycemic management formulation premiums. |
| Modular Extraction Equipment Deployment | Automated solvent recovery systems at sub-industrial scale democratize regional processor market entry. |
| Direct Procurement Contracting | Volume-commitment agreements with specific tartaric acid guarantees disintermediate multi-layered trader networks. |
| Circular Biomass Valorization | Horizon Europe funding streams subsidize tamarind waste-to-extract pilot plants in Portugal and Spain. |
Methodological Framework
Cross-validation between primary interviews with extraction equipment manufacturers, food industry procurement directors, pharmaceutical formulation scientists, and cosmetic R&D directors anchors the qualitative findings. Secondary validation draws from FSSAI regulatory filings, EFSA Novel Food catalog entries, FDA GRAS notifications, and customs trade data for tamarind pulp and extract movements. Bottom-up processor capacity modeling and top-down end-use demand estimation complete the triangulation.
Sensitivity analysis across tartaric acid yield assumptions, enzymatic substitution penetration rates, and regulatory approval timeline scenarios frames the forecast uncertainty. Segmentation dimensions include product format, end-use industry vertical, application functional positioning, and distribution channel structure. CAGRs derive from fitted growth curves against historical capacity expansion patterns and documented clean-label reformulation commitments. Industry-specific inputs incorporate PLI scheme subsidy disbursement trajectories and REACH registration compliance cost burdens.
Forecasts assume regulatory continuity in FDA GRAS self-affirmation pathways, EFSA Novel Food assessment procedures, and India's FSSAI pesticide residue limits; material policy shifts would require re-modeling. Specific risks include monsoon pattern disruption affecting Maharashtra and Andhra Pradesh pulp supply belts, and accelerated enzymatic tartaric acid cost reduction. Revision becomes warranted when fermentation-derived alternatives cross price parity thresholds with botanical extracts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Europe Spice and Herb Extracts Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
North America Spice and Herb Extracts Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Vanilla Salt Market
Spices and Seasonings
Turmeric Oleoresin Market
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Bay Leaf Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Middle East and Africa Ashwagandha Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Coleus and Turmeric Market