
 Smoked Salt Market | 2026-2036
Smoked Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Smoked Salt Market Intelligence
Advancements in controlled cold-smoking equipment that minimize polycyclic aromatic hydrocarbon (PAH) formation is tilting the production landscape toward higher-purity, safer products. Maldon Salt Company leverages its heritage brand status and established distribution to maintain a premium position. SaltWorks specializes in a wide array of wood-smoked varieties, targeting both bulk and retail channels. Artisan Salt Company competes by focusing on unique flavor infusions and co-branded partnerships with food manufacturers.
Smoked salt is a finishing salt produced by slow-smoking sea salt or rock salt over burning wood for up to several weeks. This process infuses the salt crystals with a smoky flavor, with the final profile determined by wood type. Hickory-smoked salt remains a dominant product type due to its traditional barbecue association, while applewood varieties are gaining share rapidly. In terms of application, its use as a finishing seasoning for home and restaurant dishes significantly outpaces its role in food preservation.
Food safety regulations from the US FDA and the European Food Safety Authority (EFSA) set stringent limits on contaminants like PAHs. In India, FSSAI standards for food additives and labeling govern market access and consumer trust. Producers must now decide whether to invest in advanced smoking technologies to meet diverse international standards or to focus on regional markets with less stringent requirements.
Market Dynamics
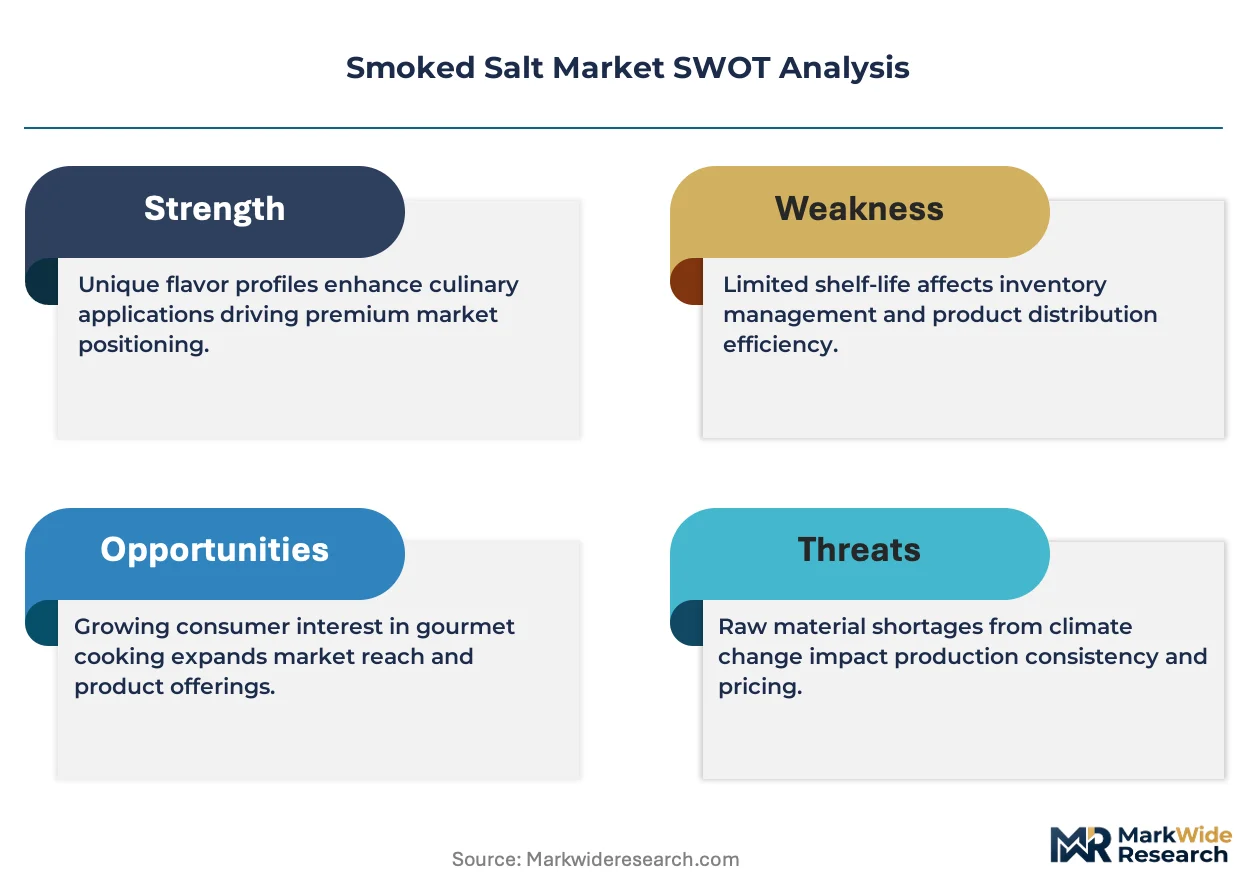
The central dynamic shaping the smoked salt market is the tension between rising consumer demand for artisanal, intensely flavored ingredients and the increasing regulatory pressure from bodies like the EFSA and FDA to minimize carcinogenic polycyclic aromatic hydrocarbons (PAHs).
Growth Catalysts
- Cold Smoking Innovation:Advancements in controlled-temperature smoking equipment enable producers to create safer products that comply with stringent PAH limits set by the EFSA, opening access to premium markets.
- Gourmet Food Sector:The expansion of the gourmet restaurant scene and a surge in sophisticated home cooking are driving demand for specialty finishing salts that add complex flavor and texture.
- Culinary Diversification:The use of smoked salts is expanding beyond traditional meat and barbecue applications into new areas like craft cocktails, baked goods, and confectioneries, creating new revenue streams.
Market Restraints
- High Production Costs:The process is input-intensive, requiring specific wood types and long smoking periods, which elevates the final product cost compared to standard sea salt or liquid smoke.
- Fragmented Global Standards:Divergent PAH limits between jurisdictions like the US FDA and the EU's EFSA create compliance burdens and trade friction for exporters seeking broad market access.
- Substitution Threat:In industrial food processing, cheaper and more easily standardized liquid smoke flavorings present a significant substitution threat, limiting smoked salt's penetration.
Strategic Opportunities
- Plant-Based Foods:The plant-based meat sector offers a key opportunity for smoked salts to provide savory and smoky notes that mimic traditional meat flavors, enhancing consumer appeal.
- Emerging Gourmet Markets:Untapped demand in Southeast Asia and Latin America, where culinary trends are evolving, offers growth potential for specialty food importers and exporters.
- DTC E-commerce Channels:Direct-to-consumer online sales allow brands to educate consumers on wood varieties and flavor pairings, bypassing traditional retail gatekeepers to build brand loyalty.
Industry Challenges
- Batch Consistency:Maintaining consistent flavor profiles and PAH levels from batch to batch is a significant operational challenge, requiring stringent process controls and frequent laboratory testing.
- Wood Sourcing Verification:Ensuring a consistent, verifiable, and sustainable supply chain for specific smoking woods like applewood or hickory is complex and subject to regional and environmental volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoked Salt Market |
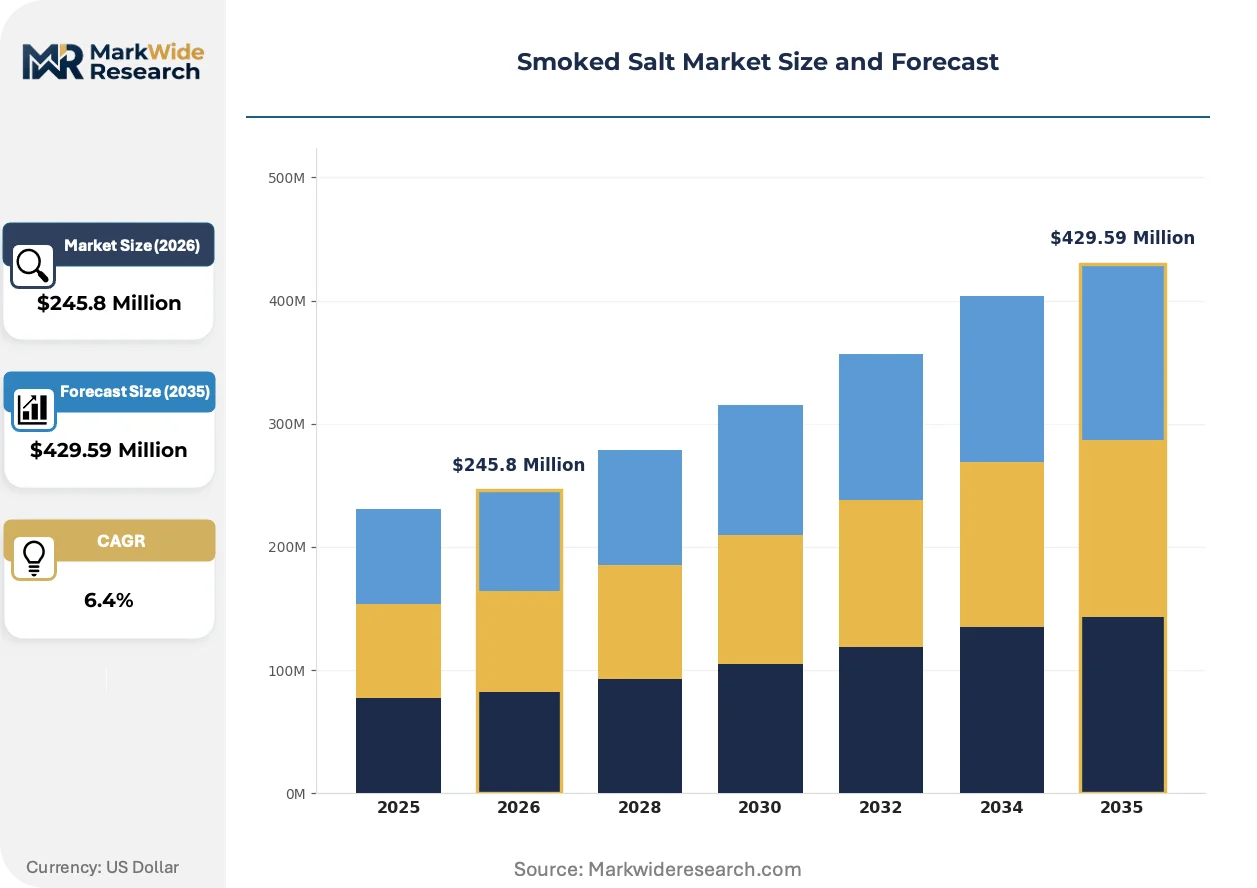
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $429.59 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hickory, Mesquite, Applewood, Cherrywood Application: Cooking, Preserving, Seasoning, Grilling Distribution Channel: Online, Retail Stores, Wholesalers, Specialty Food Shops Packaging Type: Bags, Jars, Tins, Pouches |
| Companies Covered | The Original Smoke & Spice Company Pty Ltd., Maldon Salt Company, Tassal Group Ltd., Artisan Salt Company, Saltverk, The Union Group PCL, SaltWorks, Hepps Salt Co., Gourmet Nut, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoked Salt Market Strategic Shifts & Innovations
The market is evolving through a synthesis of artisanal craft and food science. Producers are leveraging modern process control to replicate traditional smoking methods at scale. This ensures product safety and consistency without sacrificing the authentic flavor that consumers expect.
Advanced cold-smoking chambers equipped with digital sensors now monitor and control temperature, airflow, and humidity with high precision. Both industrial-scale and boutique producers are adopting these systems to achieve consistent flavor profiles and textures. This technology is digitizing the craft of salt smoking, translating subjective artisanal techniques into repeatable, data-driven parameters for quality control.
European Food Safety Authority's (EFSA) regulation on polycyclic aromatic hydrocarbons (PAHs) sets stringent maximum limits for contaminants in smoked foods. This rule forces producers to invest in cleaner smoking technologies or risk exclusion from the high-value EU market. The finishing salt category is most affected, with suppliers now implementing purification steps to comply with these rigorous standards.
A consumer-led shift toward ingredient transparency is reshaping purchasing criteria. This is disrupting the generic smoked salt category, as buyers now seek products specifying the wood type, origin, and smoking method. The trend is most prominent in North American and European specialty food stores, where product storytelling around unique woods like cherry or alder drives premium pricing.
Smoked Salt Market Segmentation
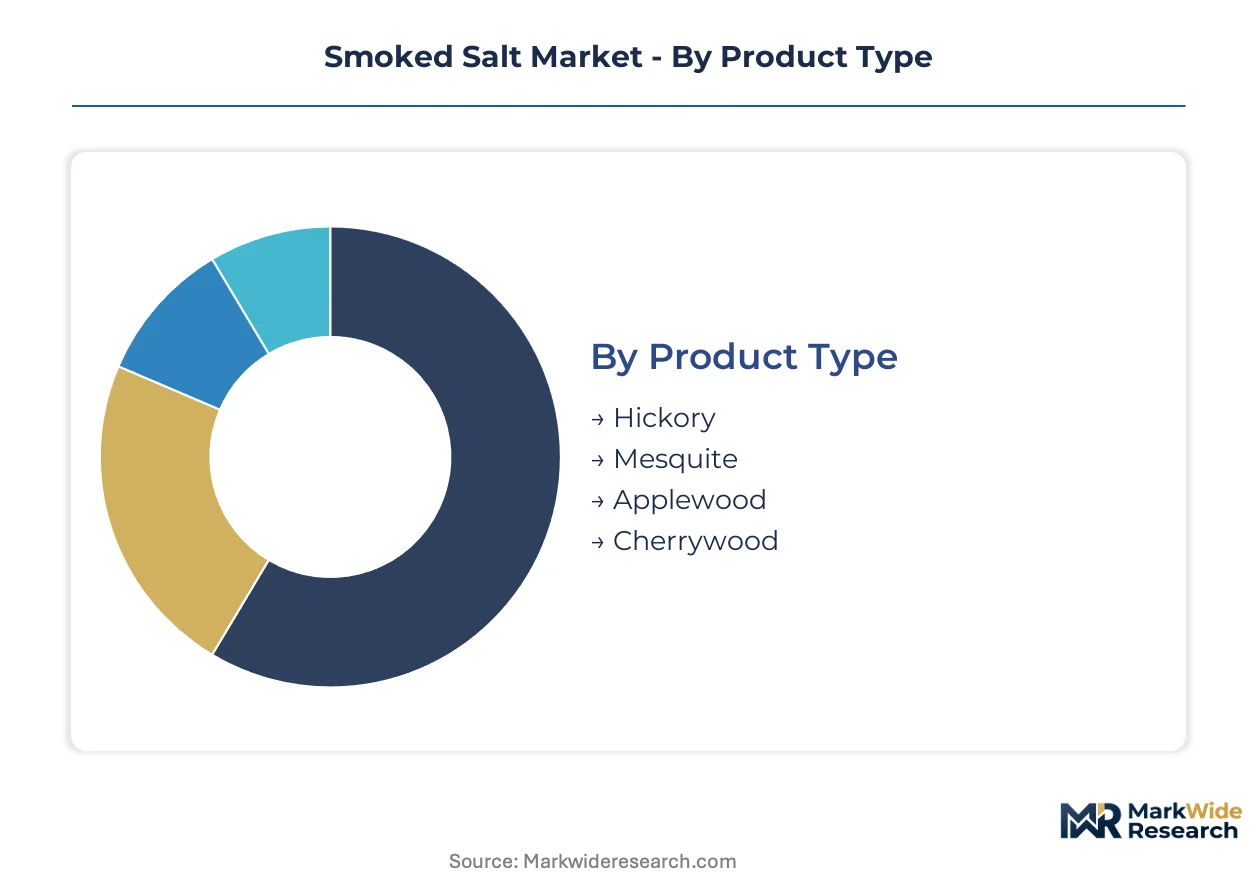
Understanding the varied segmentation within the smoked salt market is crucial for producers to align product development with consumer preferences and regulatory demands. Each segment reflects distinct production methods, application requirements, and distribution strategies. Analyzing these categories helps identify areas for innovation and targeted market penetration.
Product Type:
The intensity of after-sales service, interpreted as consumer education and guidance, varies significantly across different smoked salt product types, as discerning users often seek specific flavor profiles for their culinary endeavors.
- Hickory:This product type delivers a robust, bacon-like smoky flavor, traditionally created by smoking salt over hickory wood. Demand concentrates in the United States, driven by its strong association with barbecue and traditional American cuisine.
- Applewood:Known for its milder, subtly sweet, and fruity smoke profile, applewood smoked salt is produced by slow-smoking salt over applewood chips. Its use is expanding rapidly within gourmet restaurants and plant-based food applications due to its versatility and delicate flavor.
- Mesquite:Characterized by an earthy, intense, and somewhat pungent smoky flavor, mesquite smoked salt is popular in Tex-Mex and Southwestern cuisines.
- Cherrywood:This variety imparts a subtle, sweet, and slightly fruity smoke, making it a preferred choice for poultry, fish, and lighter dishes.
Hickory holds installed capacity. Applewood is rotating up the share rankings.
Application:
Application segments present varying cost-tier implications, with some uses commanding premium pricing for their specialized flavor contribution, while others serve more utilitarian roles in food preparation.
- Seasoning:Used primarily as a finishing salt, this application enhances the flavor and texture of prepared dishes just before serving. Demand is strong in gourmet restaurants and sophisticated home cooking environments, where complex flavor notes are highly valued.
- Grilling:Smoked salt is incorporated into rubs, marinades, and directly onto grilled foods to impart a deep, smoky essence. This application sees significant demand in North America for barbecue and outdoor cooking, adding an authentic smoky character to meats and vegetables.
- Cooking:This category encompasses the use of smoked salt as an ingredient within recipes during the cooking process, contributing a background smoky flavor.
- Preserving:Historically, smoked salt was used for curing and preserving meats, though this application now represents a smaller, niche market due to modern preservation techniques.
Seasoning applications demonstrate significant value addition. Grilling applications are gaining share fastest.
Distribution Channel:
The distribution channel for smoked salt reflects diverse customer types, ranging from individual consumers seeking convenience to bulk purchasers requiring large-scale supply chains.
- Online:This channel includes direct-to-consumer websites and e-commerce platforms, allowing brands to educate consumers on wood varieties and flavor pairings. Demand is concentrating in North America and Europe, driven by convenience and access to niche products.
- Retail Stores:Traditional brick-and-mortar establishments such as supermarkets, grocery stores, and hypermarkets form a primary access point for general consumers. These stores cater to a broad mass market, offering accessibility and immediate purchase options.
- Wholesalers:These entities supply smoked salt in bulk quantities to food manufacturers, catering services, and restaurants for industrial and commercial use.
- Specialty Food Shops:These stores offer a curated selection of premium and artisanal smoked salts, emphasizing product storytelling and unique flavor profiles to discerning customers.
Retail Stores maintain significant market reach. Online channels show the steepest expansion trajectory.
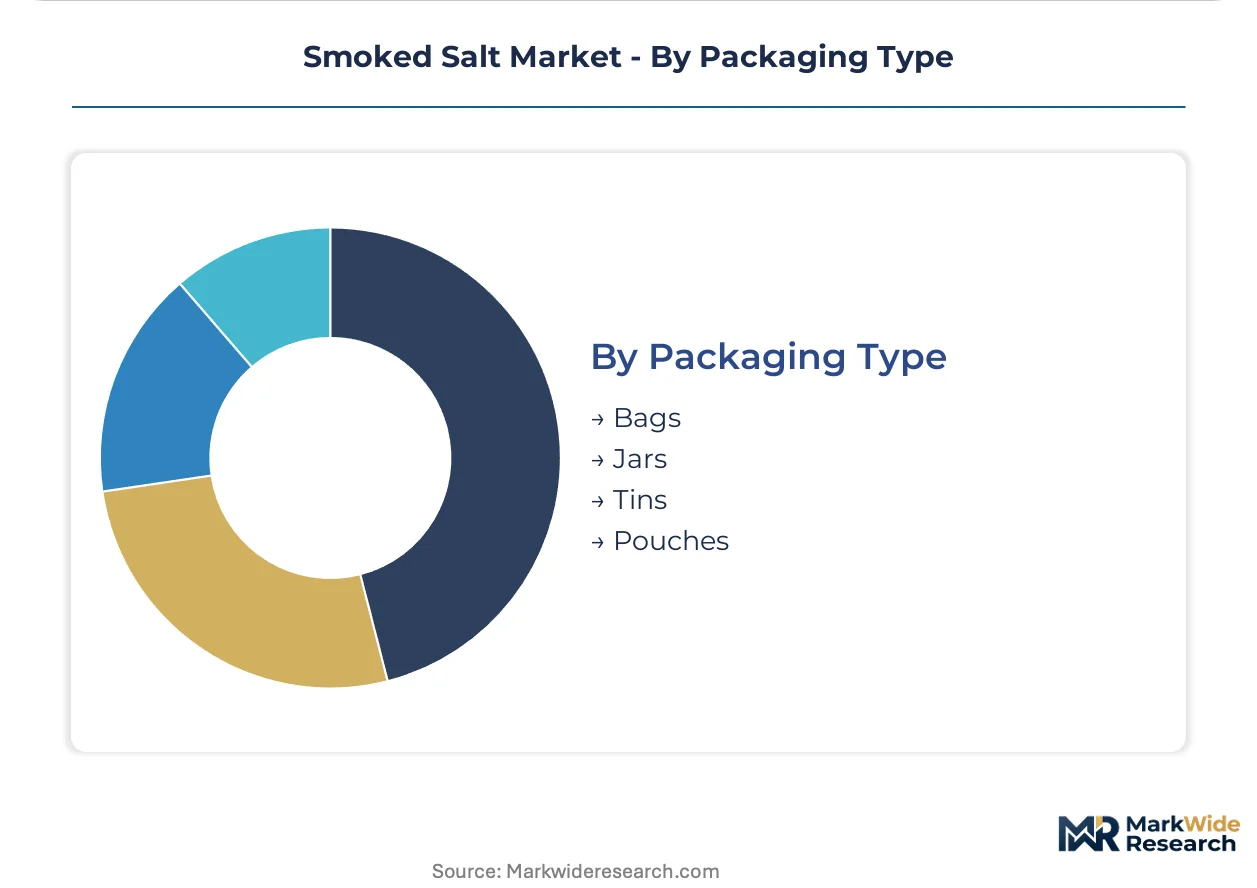
Packaging Type:
The choice of packaging type often correlates with the volume and perceived value of the product, influencing both consumer convenience and cost efficiency across the supply chain.
- Jars:Typically made of glass or ceramic, jars are favored for premium and artisanal smoked salts, offering aesthetic appeal and reusability. Demand is prominent in specialty food shops and for home cooking, supporting a higher price point and brand perception.
- Bags:Flexible bags are used for larger quantities and bulk sales, providing a cost-effective packaging solution. This type is common for industrial buyers and for consumers purchasing in higher volumes, prioritizing efficiency and lower unit cost.
- Tins:Metal tins are often associated with heritage brands or gift sets, providing excellent product protection and a classic aesthetic.
- Pouches:Resealable pouches offer convenience and portability, commonly found in smaller retail formats for everyday consumer use.
Jars command a premium position. Bags are climbing the fastest in volume-driven segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global smoked salt market exhibits a dynamic export-import balance, with key producing regions supplying a growing international demand for specialty ingredients. Trade flows are heavily influenced by local culinary traditions and the varying stringency of food safety regulations across continents. This interplay shapes regional market development and investment priorities for producers.
United States
Strong consumer demand for gourmet and artisanal foods drives the US smoked salt market, particularly for barbecue applications. The US FDA sets specific food additive standards, impacting product formulations and labeling for domestic and imported goods. Major culinary hubs like New York and Los Angeles showcase innovative uses of smoked salts in high-end restaurants.
Germany
European consumers increasingly seek high-quality, traceable food products, boosting demand for specialty salts in Germany's robust retail sector. EFSA regulations on polycyclic aromatic hydrocarbons (PAHs) necessitate advanced smoking technologies for market access. The Rhine-Main region, with its strong food processing industry, sees significant adoption of these cleaner production methods.
India
Evolving culinary tastes and a rising middle class are fueling the demand for premium ingredients like smoked salt in India. The FSSAI governs food additives and labeling, ensuring consumer trust and market entry for new products. Major metropolitan areas such as Mumbai and Delhi are experiencing a surge in gourmet food consumption and specialty ingredient sales.
Japan
Japanese consumers appreciate nuanced flavors and high-quality ingredients, driving a niche but growing market for smoked salts in gourmet cooking. Japan's Ministry of Health, Labour and Welfare oversees food safety, influencing import standards for specialty food items. The Tokyo metropolitan area leads in the adoption of unique smoked salt varieties for both home and restaurant use.
Australia
Australian demand for smoked salts is expanding due to a vibrant food culture and a preference for natural, flavorful seasonings. Food Standards Australia New Zealand (FSANZ) sets comprehensive standards for food additives and contaminants, including those in smoked products. Cities like Melbourne and Sydney are centers for artisanal food production and specialty ingredient distribution.
Smoked Salt Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing both large-scale producers and numerous specialized artisan brands. This market exhibits a blend of consolidation among established players and fragmentation within niche segments. Strategic archetypes include heritage brands leveraging their legacy, ingredient specialists offering diverse wood varieties, and innovation-driven companies focusing on compliance technology. Companies are increasingly pursuing portfolio diversification and strategic partnerships to expand their market reach.
Within the heritage brand tier, Maldon Salt Company exemplifies traditional craftsmanship and established distribution channels, maintaining a premium market position through its long-standing reputation for quality and consistency. SaltWorks, an ingredient specialist, occupies a significant position by offering a wide array of wood-smoked varieties, effectively targeting both bulk and retail channels with its extensive product catalog and diverse flavor profiles. Artisan Salt Company further enhances the market by representing innovation in unique flavor infusions, actively pursuing co-branded partnerships with food manufacturers, and focusing on product storytelling to appeal to discerning consumers. These distinct approaches underscore the varied strategies employed by key players.
| Leading Market Players |
|---|
| The Original Smoke & Spice Company Pty Ltd. |
| Maldon Salt Company |
| Tassal Group Ltd. |
| Artisan Salt Company |
| Saltverk |
| The Union Group PCL |
| SaltWorks |
| Hepps Salt Co. |
| Gourmet Nut |
| Others |
Cost & Logistics Intelligence
Advanced cold-smoking technology, concentrated among specialized equipment manufacturers, directly influences premium pricing for high-purity smoked salts. This upstream specialization allows producers to meet stringent international food safety standards.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for bulk smoked salt. Price differentiation stems from wood type authenticity and compliance with EFSA PAH limits, allowing premium pricing for certified products. Pricing softness runs through the generic smoked salt category due to substitution threats from liquid smoke flavorings. Gourmet restaurants and specialty food shops are least price-sensitive, valuing unique flavor profiles, while food manufacturers prioritize cost efficiency.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are crucial for producers sourcing specific wood types. Smoked salt production draws from sea salt suppliers in the United States and Australia, alongside specialty wood providers in North America and Europe. Raw material dependencies include specific hardwood varieties like hickory and applewood, plus high-quality sea or rock salt. Commodity price volatility for these inputs represents a structural risk. Distribution runs through a hybrid model, combining direct-to-consumer e-commerce with traditional retail stores and bulk wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smoked salt market represents a high-growth disruption, driven by advancements in cold-smoking technology that enable compliance with stringent food safety regulations. This technological shift allows for the creation of safer, premium products.
For Market Incumbents:Harden existing distribution channels by forging exclusive partnerships with gourmet retailers and restaurant groups. Invest in advanced cold-smoking technologies to meet evolving EFSA and FDA PAH limits, mitigating regulatory threats. Capacity additions in key European markets can secure market access amidst rising competition from specialized artisan brands. This strategy reinforces brand premium and market share.
For New Entrants and Emerging Players:Build out niche product lines targeting plant-based food manufacturers with unique flavor profiles like applewood or cherrywood smoked salts. Underpenetrated markets in Southeast Asia offer white-space opportunities for specialty ingredients. Leverage direct-to-consumer e-commerce channels to educate consumers on wood varieties and flavor pairings, bypassing traditional retail gatekeepers. This approach enables rapid brand building and direct customer feedback.
For Investors and Strategic Acquirers:Capital is best deployed toward mid-cap ingredient specialists with proprietary cold-smoking technology and diversified wood-smoked product portfolios. These entities demonstrate long-term viability in a market valuing both purity and flavor innovation over the next decade. Seek companies with strong intellectual property in process controls for PAH minimization. The signal to watch is successful market entry into regulated European markets, indicating robust compliance capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Smoking Technology Investment | Ensures compliance with EFSA and FDA PAH limits, opening access to premium global markets. |
| Plant-Based Food Partnerships | Captures new demand for savory, smoky notes in meat alternatives, expanding application scope. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional retail, enabling direct consumer education and fostering brand loyalty. |
| Supply Chain Sustainability Certification | Verifies ethical wood sourcing, enhancing brand reputation and meeting consumer transparency demands. |
| Regional Capacity Expansion (Europe) | Establishes local production to reduce logistics costs and adapt to specific market preferences. |
Research Approach
Cross-validation between primary interviews and extensive secondary research anchors the qualitative findings of this study. Primary data collection involved conversations with food manufacturers, specialty ingredient distributors, and gourmet chefs. Secondary validation drew from food safety agency reports (FDA, EFSA, FSSAI), industry association publications, and company financial filings. Bottom-up and top-down triangulation ensured market sizing precision.
Forecast calibration employed a multi-stage analytical framework across the analysis window. Segmentation dimensions modeled include product type, application, distribution channel, and packaging type, alongside regional consumption patterns. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and market influences. Forecast inputs included regulatory shifts in PAH limits and consumer demand for artisanal ingredients.
Practitioners should monitor advancements in cold-smoking technology and evolving food safety regulations for early signals of market shifts. This analysis reflects assumptions regarding raw material availability and consumer preferences. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Dill Oil Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
South America Spice and Herb Extracts Market
Spices and Seasonings
Celery Seed Extract Powder Market
Spices and Seasonings
Turmeric Oleoresin Market
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
Europe Spice and Herb Extracts Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Dried Herbs Market