
 Egypt Herbs and Spices Market | 2026-2036
Egypt Herbs and Spices Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Herbs and Spices Market Foresight
Traditional spice souks and open-air wholesale channels is narrowing as modern retail chains and e-commerce platforms capture urban consumers in Cairo and Alexandria. Alexandria Spices leverages vertical integration from farm-level sourcing through port-side processing to control export quality. Agro Herbs sustains dominance in organic thyme and marjoram segments through long-term contracts with European importers. Egyptian Export Center (EEC) anchors its position by operating centralized cleaning, grinding, and sterilization facilities near Damietta port.
Egypt herbs and spices encompass dried, dehydrated, or minimally processed aerial plant parts—leaves, seeds, flowers, and roots—retaining essential oil content between 0.5% and 5.0% by dry weight depending on cultivar and post-harvest handling. These materials serve as flavoring agents, natural preservatives, and phytochemical inputs across food manufacturing, pharmaceutical extraction, and aromatherapy applications. Whole and ground forms command the largest volume share, though blended formulations targeting food service buyers yield higher per-kilogram margins. The food service end-user segment leads absolute consumption, driven by restaurant chains and industrial kitchens seeking consistent batch flavor profiles.
Egypt's Ministry of Agriculture and Land Reclamation oversees phytosanitary certification for export shipments, while the Egyptian Organization for Standardization and Quality (EOS) mandates moisture content and microbial load thresholds for packaged retail products. Compliance with EOS standards and importer-country organic certifications determines market access for Egyptian processors targeting European and Gulf buyers. Stakeholders must monitor pending revisions to pesticide maximum residue limits and the expansion of cold-chain infrastructure in Upper Egypt, where post-harvest losses currently erode farm-gate returns.
Market Dynamics
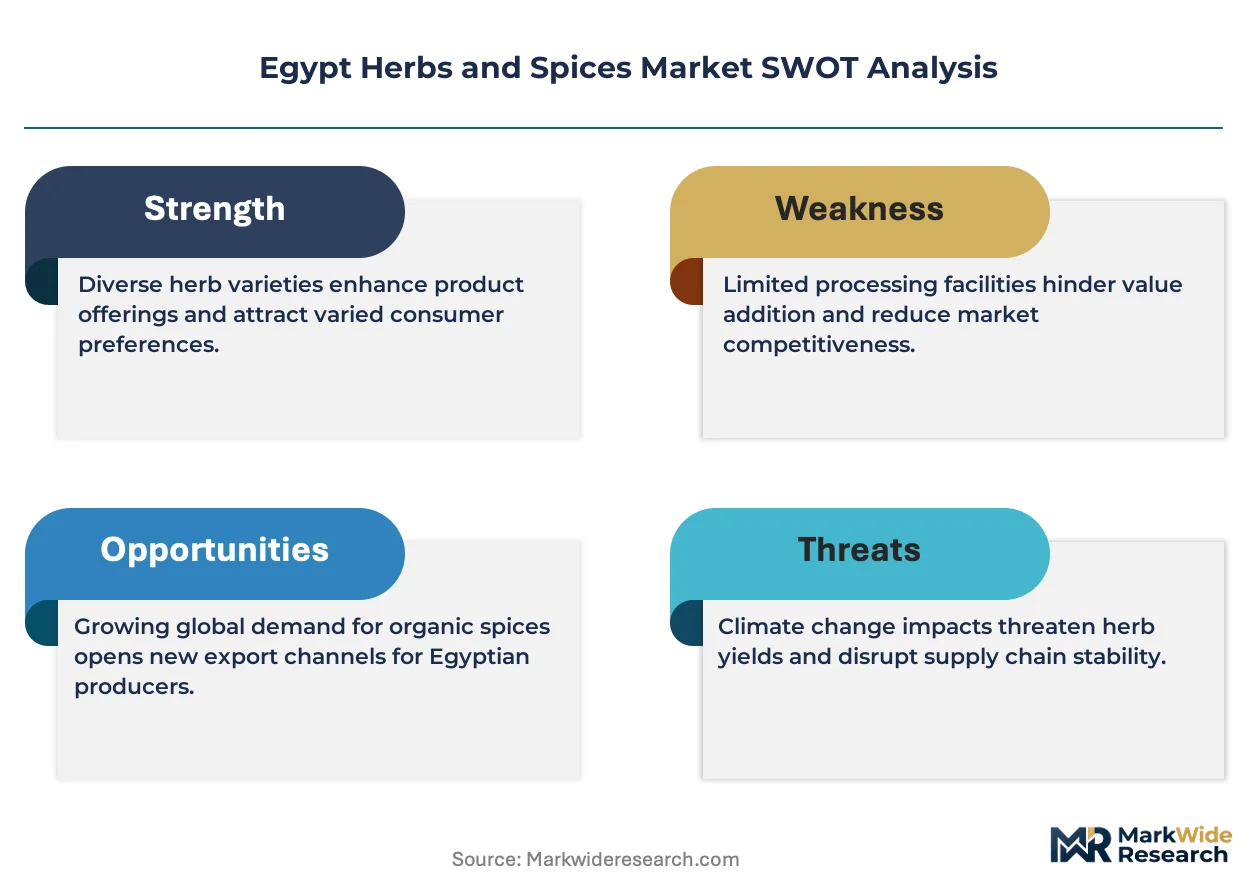
Egypt's herbs and spices sector faces structural pressure from Codex Alimentarius-aligned pesticide residue enforcement, which is redirecting capital toward certified organic cultivation and consolidating processing capacity around port-adjacent sterilization facilities.
Growth Catalysts
- Food service procurement expansion:Restaurant chains and industrial kitchens across Mediterranean and Middle Eastern cuisine segments are standardizing Egyptian oregano and basil for consistent batch flavor profiles.
- Organic certification alignment:EOS mandates for moisture content and microbial load thresholds are unlocking European and Gulf buyer access for compliant processors.
- Nile Delta processing concentration:Alexandria and Damietta port access is streamlining export logistics and reducing post-harvest transit time for volatile essential oil retention.
Market Restraints
- Upper Egypt cold-chain deficit:Post-harvest losses in arid interior regions erode farm-gate returns and compress raw material availability for processors.
- Input cost volatility:Irrigation water scarcity and energy price fluctuations for dehydration equipment squeeze margins on dried herb production.
- Substitution pressure from Turkish supply:Anatolian thyme and marjoram exporters compete on freight cost to European importers, pressuring Egyptian price positioning.
Strategic Opportunities
- Pharmaceutical extraction demand:Essential oil concentration of 0.5% to 5.0% dry weight positions Egyptian material for phytochemical inputs in aromatherapy and nutraceutical applications.
- E-commerce channel penetration:Modern retail chains and direct-to-consumer platforms in Cairo and Alexandria are displacing traditional spice souks for urban consumers.
- Pending MRL revisions:Anticipated tightening of EOS pesticide maximum residue limits will reward early adopters of integrated pest management with preferential buyer access.
Industry Challenges
- Phytosanitary certification bottlenecks:Egypt's Ministry of Agriculture and Land Reclamation processing delays for export shipments create inventory holding costs and contract fulfillment risk.
- Skilled post-harvest handling shortage:Technical expertise for essential oil preservation during drying and grinding operations remains concentrated in Alexandria and Damietta processing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Herbs and Spices Market |
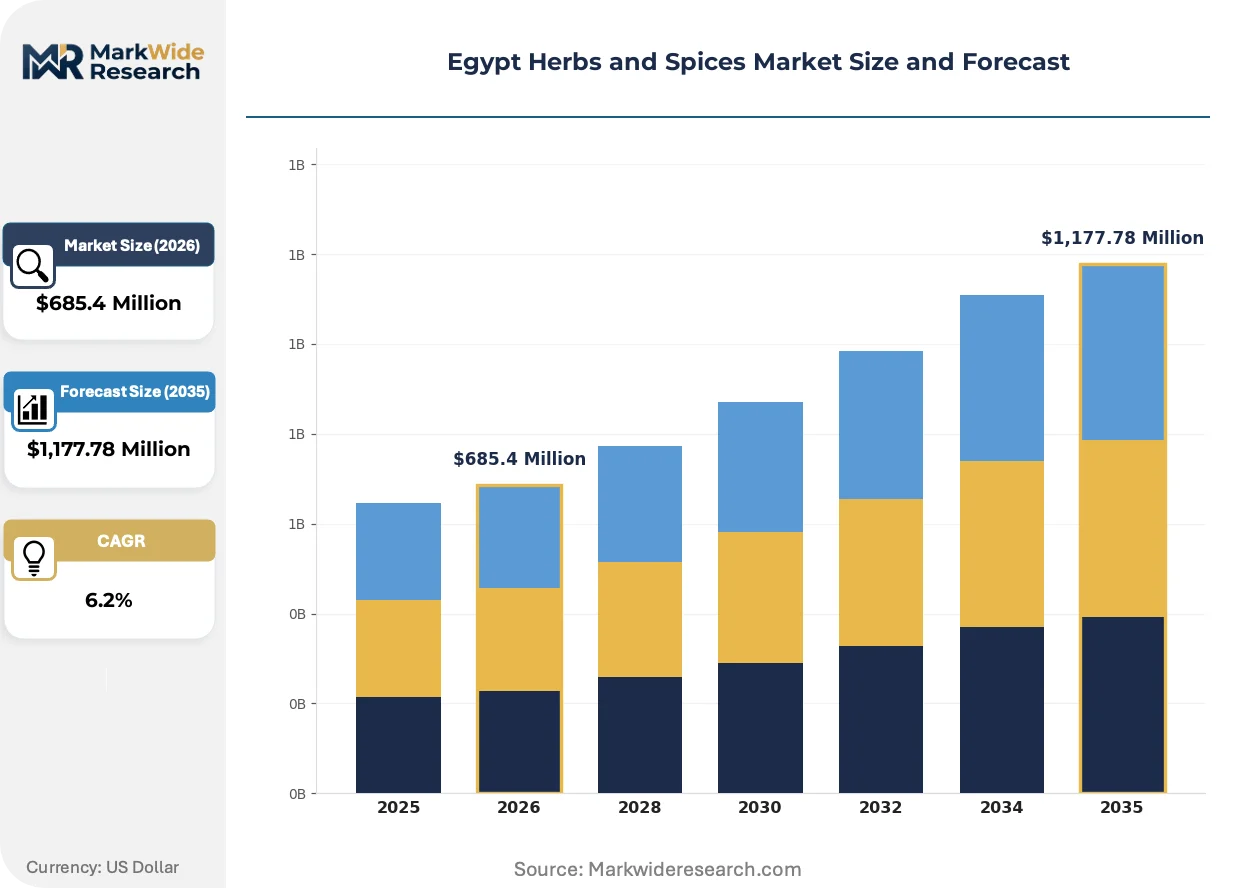
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oregano, Basil, Thyme, Dill Form: Whole, Ground, Crushed, Blended Packaging Type: Bags, Bottles, Bulk, Jars End User: Food Service, Retail, Industrial, Home Cooking |
| Companies Covered | Alexandria Spices, Agro Herbs, Egyptian Export Center (EEC), Green Herbs Export, Delta Company For Manufacturing & Export Herbs And Spices, Hortec Egypt, EGEU Foods, Olam Food Ingredients, El-Wahy Herbs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Herbs and Spices Market Shifts & Advancements
Processing technology and regulatory compliance systems are converging to reshape competitive positioning in Egyptian herbs and spices, with capital flowing toward integrated sterilization and traceability infrastructure.
Low-temperature dehydration with real-time moisture monitoring is hybridizing traditional sun-drying with controlled mechanical systems. Food manufacturers seeking consistent essential oil retention are adopting these hybrid units at pace. The technology is compressing quality variation between harvest batches and enabling premium pricing for standardized output.
EOS alignment with Codex Alimentarius standards is tightening enforcement of pesticide residue thresholds for packaged retail exports. Processors are redirecting sourcing toward certified organic farms to preempt import rejection at European ports. Smallholder cooperatives in the Nile Delta are responding by pooling resources for third-party organic audit compliance.
Urban buyers in Cairo and Alexandria are migrating from open-air wholesale channels toward modern retail chains and e-commerce platforms. Traditional spice souks are losing volume share as convenience and packaged quality assurance displace bulk purchasing. This behavioral shift is most visible among food service operators and hospitality procurement managers seeking documented traceability for menu labeling requirements.
Egypt Herbs and Spices Market Segmentation
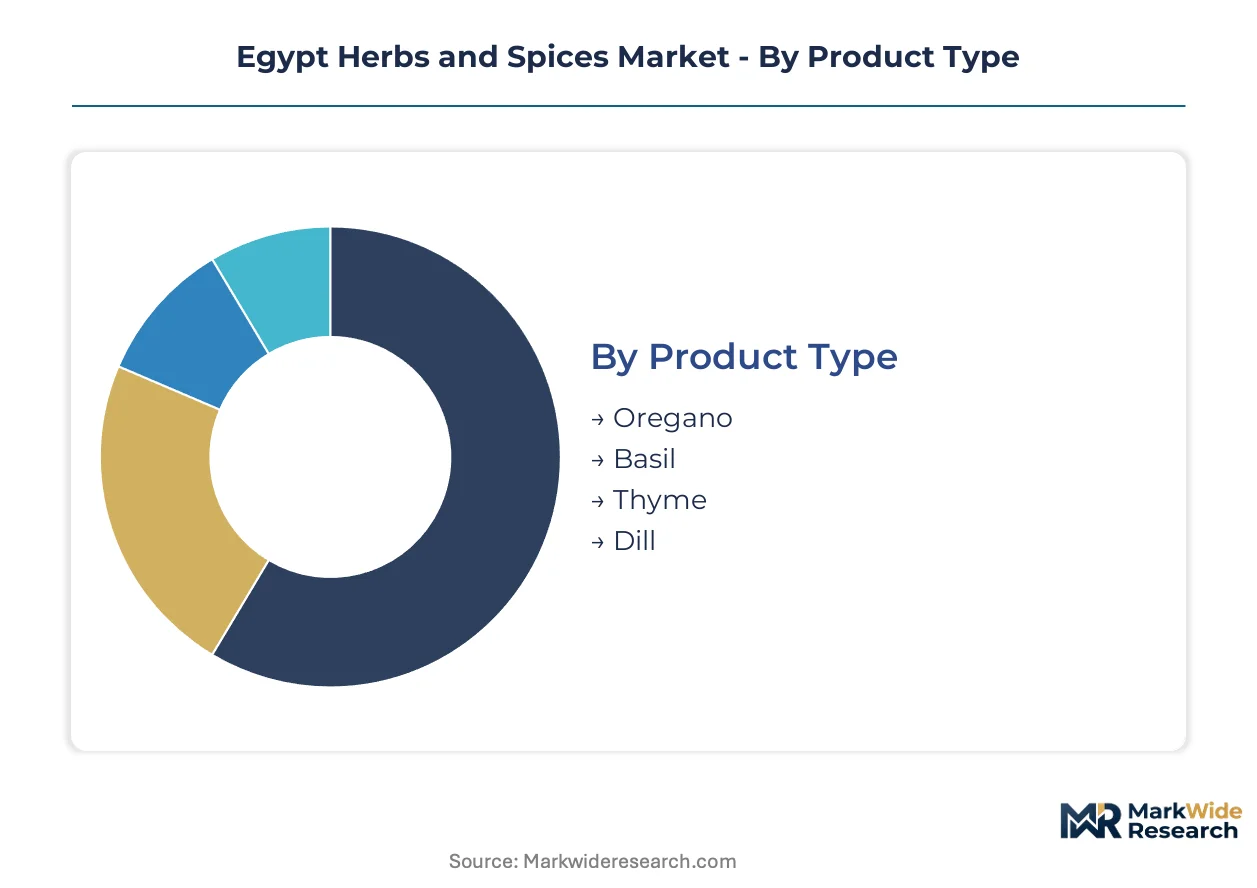
Segmentation in Egypt's herbs and spices sector reveals how procurement patterns diverge between volatile food service channels and stable retail offtake. Understanding these splits helps processors align sterilization capacity and packaging formats with buyer requirements.
Product Type:
Cycle times vary sharply across herb categories, with annual-harvest varieties turning inventory faster than perennial crops that lock working capital across growing seasons.
- Oregano:Perennial shrub harvested twice yearly with essential oil content between 1.5% and 3.0% dry weight. Cairo-based food service distributors and Alexandria export processors absorb the largest volumes, driven by Mediterranean restaurant chain procurement standardization.
- Basil:Annual herb requiring 60-90 day growing cycles with higher moisture sensitivity demanding rapid post-harvest dehydration. Nile Delta greenhouse operators supply year-round to industrial kitchens seeking consistent batch flavor profiles.
- Thyme:Drought-tolerant perennial concentrated in Upper Egypt smallholder plots with extended drying windows.
- Dill:Annual umbellifer with volatile essential oils degrading within 12 months of harvest, pushing rapid turnover in retail channels.
Oregano dominates installed base. Basil is where expansion concentrates.
Form:
Processing intensity and margin capture split across formats, with value-added stages commanding premium positioning in buyer negotiations.
- Whole:Intact leaves, seeds, or flowers retaining maximum essential oil stability through minimal mechanical handling. European importers and Gulf retail chains prefer whole form for in-house grinding, with demand concentrating at Damietta port sterilization facilities.
- Ground:Particle-size standardized powders between 0.5mm and 2.0mm mesh for immediate food manufacturing integration. Cairo industrial kitchens and quick-service restaurant chains drive volume, prioritizing batch consistency over oil retention.
- Crushed:Coarse fragmentation preserving partial cell structure for slower essential oil release during cooking.
- Blended:Formulated combinations targeting specific cuisine profiles with highest per-kilogram margins.
Whole form anchors export volume. Blended formulations are climbing the fastest.
Packaging Type:
Unit economics and shelf-life requirements dictate format selection, with moisture barrier specifications varying by distribution channel.
- Bags:Multi-layer polymer or kraft laminates with oxygen scavengers for 12-24 month shelf life. Food service distributors in Alexandria and Cairo procurement hubs favor bulk bags for back-of-house handling efficiency.
- Bottles:Glass or PET containers with desiccant inserts for retail visibility and resealability. Modern supermarket chains across Greater Cairo are displacing open-air souk purchasing with packaged bottle formats.
- Bulk:Food-grade fiber drums or supersacks for industrial extraction and manufacturing inputs.
- Jars:Wide-mouth glass with metal lug closures for premium positioning in gift and specialty segments.
Bags command food service procurement. Bottles are gaining share fastest in urban retail migration.
End User:
Demand volatility and specification stringency create distinct service requirements across buyer categories.
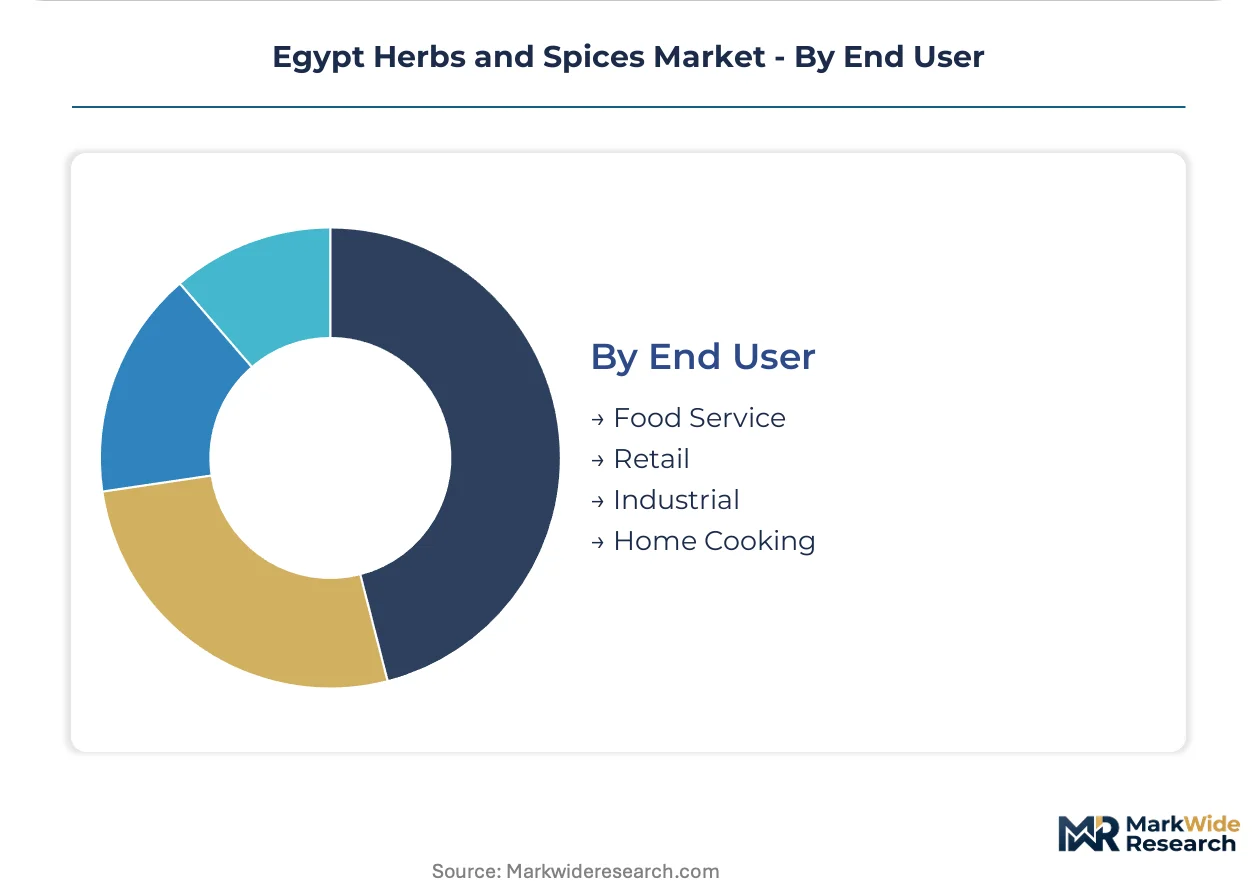
- Food Service:Restaurant chains, hotels, and institutional kitchens requiring documented traceability and consistent batch flavor profiles. Mediterranean and Middle Eastern cuisine operators in Cairo and Alexandria standardize Egyptian oregano and basil for menu engineering.
- Retail:Supermarket chains, specialty grocers, and e-commerce platforms displacing traditional spice souks. Packaged quality assurance and convenience drive Cairo and Alexandria urban consumer migration.
- Industrial:Food manufacturers and pharmaceutical extractors sourcing for ingredient inputs and phytochemical processing.
- Home Cooking:Traditional bulk purchasing through wholesale channels persisting in secondary cities and rural governorates.
Food Service leads absolute consumption. Retail is where channel expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alexandria port infrastructure anchors Egypt's herbs and spices export corridor, connecting Nile Delta processing clusters to Mediterranean shipping lanes serving European and Gulf buyers.
Cairo and the Nile Delta
Food service distributors and retail procurement hubs concentrate in Greater Cairo, absorbing standardized oregano and basil volumes for restaurant chain menus. The Egyptian Organization for Standardization and Quality enforces moisture content thresholds that determine packaged retail access. Processing facilities in Damietta cluster around port-side sterilization infrastructure, streamlining export logistics for volatile essential oil retention.
Alexandria
Vertical integration from farm-level sourcing through port-side processing defines competitive positioning among export-oriented operators. National food safety regulators align pesticide residue limits with Codex Alimentarius standards, redirecting capital toward certified organic cultivation. Alexandria Spices leverages this regulatory environment to control quality across the supply chain before Mediterranean shipping.
Upper Egypt
Thyme production concentrates in smallholder plots across arid interior governorates, where drought-tolerant perennials suit extended drying windows. Cold-chain infrastructure deficits erode farm-gate returns through post-harvest losses. Agro Herbs sources organic material from this region through long-term contracts with European importers, bypassing traditional wholesale channels.
Sinai Peninsula
Medicinal herb wild harvesting persists in Bedouin-managed territories, supplying niche aromatherapy and phytochemical extraction demand. Ministry of Agriculture and Land Reclamation phytosanitary certification requirements create bottlenecks for export shipments from this peripheral zone. Green Herbs Export operates collection networks bridging traditional gatherers with centralized cleaning facilities.
Egypt Herbs and Spices Market Competitive Landscape
On the supply side, the industry is consolidating around port-adjacent sterilization capacity and certified organic sourcing networks. Three archetypes dominate: vertically integrated exporters controlling farm-to-port quality chains, specialized organic cultivators serving European importers, and centralized processing cooperatives aggregating smallholder output. Competitive moves concentrate on backward integration into cultivation and strategic partnerships with food service distributors seeking documented traceability.
Among export-oriented processors, Alexandria Spices, Agro Herbs, and Egyptian Export Center exemplify the tier commanding premium positioning through quality control infrastructure. Alexandria Spices represents the vertically integrated archetype with farm-level sourcing discipline. Agro Herbs anchors the organic certification specialist position. Egyptian Export Center occupies the centralized processing hub role near Damietta port.
| Leading Market Players |
|---|
| Alexandria Spices |
| Agro Herbs |
| Egyptian Export Center (EEC) |
| Green Herbs Export |
| Delta Company For Manufacturing & Export Herbs And Spices |
| Hortec Egypt |
| EGEU Foods |
| Olam Food Ingredients |
| El-Wahy Herbs |
| Others |
Supply & Pricing Matrix
Damietta port sterilization capacity anchors Egypt's herbs and spices pricing power, with processors commanding premium positioning when essential oil retention meets European importer specifications. EOS moisture content thresholds and Codex Alimentarius-aligned pesticide residue enforcement create compliance cost tiers that stratify farm-gate pricing across the Nile Delta.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Egypt's herbs and spices market. Premium tiers capture certified organic oregano and basil with documented traceability for European food service distributors, while standard grades serve Cairo industrial kitchens prioritizing batch consistency. Pricing pressure stems from Turkish Anatolian thyme exporters competing on freight costs to European ports. Food service buyers exhibit highest price sensitivity due to volume procurement standardization, whereas pharmaceutical extractors accept premium positioning for verified essential oil concentration.
Supply Chain Analysis
Smallholder plots across Egypt's Nile Delta and Upper Egypt governorates feed raw material into Alexandria and Damietta processing clusters. Irrigation water scarcity and energy price fluctuations for dehydration equipment squeeze production economics. Single-source vulnerability concentrates in phytosanitary certification bottlenecks at Egypt's Ministry of Agriculture and Land Reclamation. Distribution runs through port-adjacent sterilization facilities serving Mediterranean shipping lanes to European and Gulf buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical expertise for essential oil preservation during drying and grinding operations remains concentrated in Alexandria and Damietta processing clusters, creating a persistent capability gap that shapes competitive outcomes across Egypt's herbs and spices sector.
For Market Incumbents: Entrench quality control infrastructure through backward integration into certified organic cultivation networks in the Nile Delta. Expand sterilization capacity at Damietta port to preempt phytosanitary certification bottlenecks. Anchor positioning by securing long-term offtake agreements with European importers before anticipated EOS pesticide maximum residue limit revisions tighten compliance requirements. For New Entrants and Emerging Players: Mid-market organic thyme sourcing from Upper Egypt smallholder cooperatives represents the most penetrable entry point for bypassing established Alexandria export processors. E-commerce direct-to-consumer platforms targeting Cairo and Alexandria urban consumers displacing traditional spice souks offer channel access with lower capital requirements than port-side infrastructure. Pursue third-party organic audit compliance as the primary go-to-market credential. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-premium play because escalating Codex Alimentarius enforcement and EOS standard alignment will reward early compliance infrastructure with preferential buyer access. Target acquisition archetypes: centralized processing cooperatives with existing phytosanitary certification relationships and Nile Delta greenhouse operators with year-round basil production capability. Monitor pending pesticide maximum residue limit revision announcements as the key inflection signal for compliance-cost recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Cultivation Expansion | EOS alignment with Codex Alimentarius standards unlocks European port access for compliant processors. |
| Port-Adjacent Sterilization Capacity Addition | Damietta infrastructure compression reduces post-harvest transit time for volatile essential oil retention. |
| Long-Term European Importer Contracts | Agro Herbs demonstrates pricing power through multi-year organic thyme and marjoram supply agreements. |
| E-Commerce Direct-to-Consumer Launch | Urban retail migration in Cairo and Alexandria displaces traditional spice souk purchasing behavior. |
| Integrated Pest Management Adoption | Early EOS pesticide maximum residue limit compliance rewards adopters with preferential buyer qualification. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade flow databases, EOS regulatory filings, and Mediterranean shipping manifest records. Interviews with export processors, food service procurement managers, and Ministry of Agriculture certification officers ground supply-side dynamics. Validation combines bottom-up farm-gate production estimates with top-down European import absorption analysis.
Forecast inputs span product type segmentation across oregano, basil, thyme, and dill varieties; form factors from whole through blended formulations; packaging configurations serving food service and retail channels; and end-user splits between restaurant chains, industrial kitchens, and pharmaceutical extractors. CAGRs derive from essential oil retention value capture and organic certification penetration trajectories across the projection horizon.
Practitioners should monitor EOS pesticide maximum residue limit revision timelines, Upper Egypt cold-chain infrastructure investment announcements, and Turkish Anatolian competitor freight pricing for early signals of forecast deviation. Cross-checking against European Commission import refusal alert data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Onion Powder Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Europe and Asia Juniper Berries Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Garlic Salt Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Paprika Powder Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Cajun Seasoning Market