
 Habanero Salt Market | 2026-2036
Habanero Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Habanero Salt Market Foresight
A shift from single-source chili procurement to multi-origin sourcing is repositioning supply strategies across the habanero salt value chain. McCormick & Company, Inc. leverages its integrated spice procurement network to secure consistent pepper volumes. Morton Salt, Inc. anchors its position through controlled evaporation facilities that maintain mineral consistency. Badia Spices, Inc. competes on price accessibility across Latin American and Caribbean distribution corridors.
Habanero salt denotes a seasoned crystalline product combining evaporated sodium chloride with dried Capsicum chinense fruit, typically processed through grinding, thermal drying, or cold-smoking to achieve Scoville ratings between 100,000 and 350,000 heat units. The product functions primarily as a heat-forward flavoring agent in commercial kitchens, packaged foods, and retail seasoning lines. Gourmet salt and artisan salt segments command premium shelf positioning through small-batch production claims and origin-specific pepper provenance. Flavored salt variants oriented toward snack seasoning applications are expanding fastest through food service and online retail channels.
FDA food labeling standards and EFSA novel food regulations govern capsaicin concentration disclosures and allergen cross-contamination protocols for imported spice blends. USDA organic certification and EU organic regulation requirements constrain supply pool eligibility for premium-positioned products. Stakeholders must monitor evolving Scoville measurement standardization efforts and capsaicin extract import tariffs that could reshape cost structures for heat-intense formulations.
Market Dynamics
Clean-label mandates from FDA and EFSA are compressing formulation timelines for habanero salt producers, forcing rapid reformulation of capsaicin delivery systems and mineral carriers while maintaining Scoville consistency.
Growth Catalysts
- USDA Organic Certification:Premium-positioned habanero salt lines leverage USDA organic seals to capture shelf space in specialty retail channels across North American markets.
- Capsaicin Extract Standardization:Advances in Scoville measurement protocols enable consistent heat-unit labeling that reduces consumer uncertainty and accelerates repeat purchase rates.
- Mexico:Proximity to Capsicum chinense cultivation zones reduces pepper drying and transport costs for processors operating near Yucatán and Oaxaca growing regions.
Market Restraints
- Chili Input Volatility:Drought cycles in primary Capsicum chinense regions create 18-24 month price swings that compress processor margins.
- EFSA Novel Food Thresholds:Capsaicin concentration caps for imported spice blends force reformulation of heat-intense product lines destined for European markets.
- Evaporated Salt Sourcing:Controlled brine access limits for solar evaporation facilities constrain mineral consistency for artisan-grade producers.
Strategic Opportunities
- Germany:Underpenetrated direct-to-consumer channels in German-speaking markets offer expansion potential for cold-smoked habanero salt variants.
- Snack Seasoning Applications:Food service distributors are developing proprietary habanero salt blends for kettle chip and nut coating lines.
- EU Organic Regulation:Compliance with EU organic standards unlocks premium pricing eligibility across German and Austrian retail networks.
Industry Challenges
- Cross-Contamination Protocols:Allergen segregation requirements for capsaicin processing facilities demand capital-intensive facility redesigns.
- Scoville Certification Timelines:Third-party heat-unit verification creates 6-8 week delays in product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Habanero Salt Market |
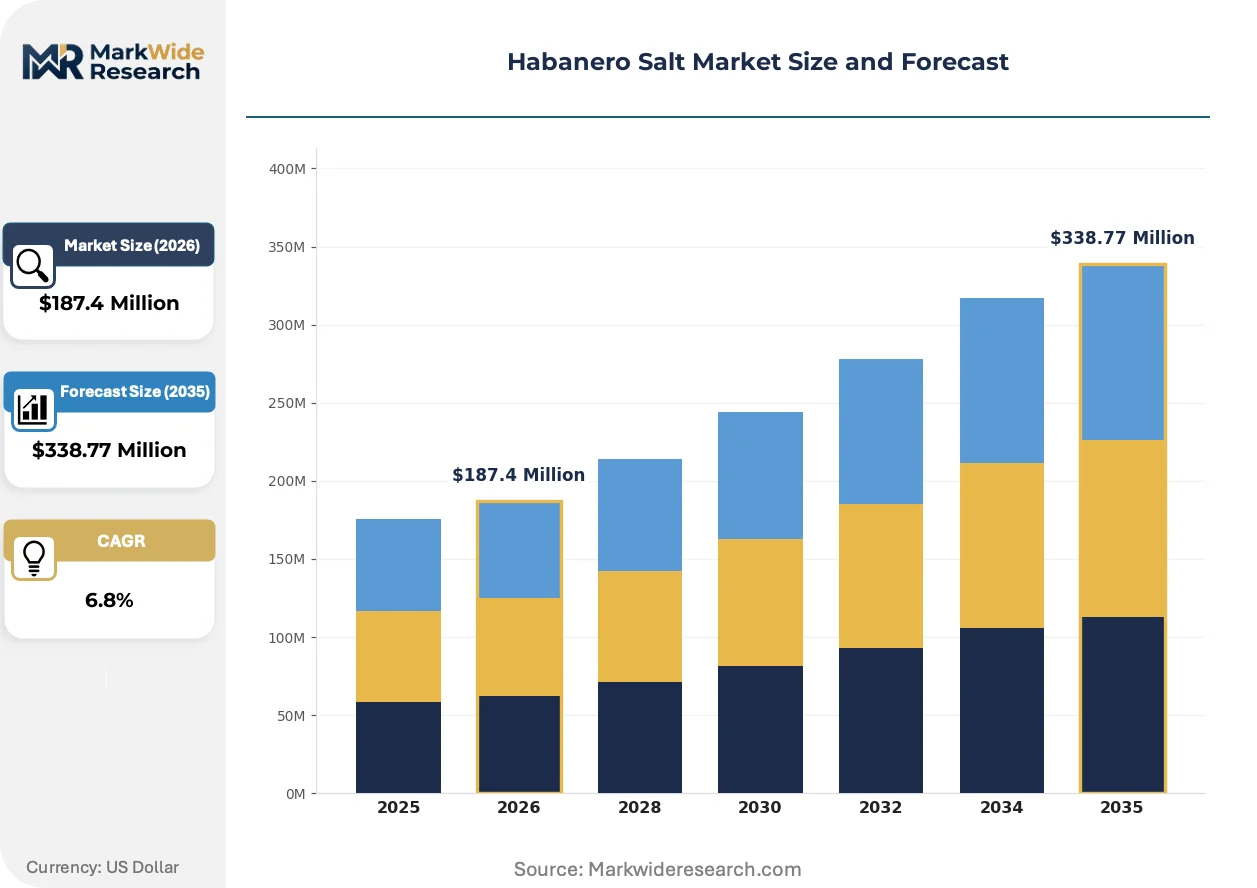
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored Salt, Gourmet Salt, Organic Salt, Artisan Salt Application: Cuisine, Snacks, Seasoning, Cooking Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Households, Restaurants, Food Manufacturers, Caterers |
| Companies Covered | Morton Salt, Inc., Badia Spices, Inc., McCormick & Company, Inc., El Yucateco S.A. de C.V., Tajin USA LLC, The Kraft Heinz Company, Lawry’s Inc., Red Monkey Foods, Inc., Olde Thompson, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Habanero Salt Market Shifts & Advancements
Thermal processing methods and regulatory disclosure frameworks are converging to reshape how habanero salt achieves heat delivery and label transparency. These shifts compress development cycles while expanding application versatility.
Cold-smoking technology is modularizing habanero salt production by enabling discrete flavor-layering stages that processors can sequence independently. Small-batch artisan producers in Mexico and the United States adopt these modular smoke chambers to create origin-specific profiles without dedicated facilities. The approach is compressing capital requirements for flavor differentiation while fragmenting competitive positioning across premium tiers.
EFSA's evolving novel food regulations governing capsaicin concentration disclosures are forcing reformulation of imported spice blends before European market entry. Industrial consequence includes mandatory third-party Scoville verification and expanded allergen cross-contamination documentation. Premium habanero salt lines destined for German and Austrian retail networks face the steepest compliance burden, with processors accelerating organic certification to bypass certain novel food thresholds.
Food service distributors are consolidating habanero salt procurement through direct-import arrangements that bypass traditional spice house intermediaries. This channel disintermediation concentrates volume with specialized seasoning blenders capable of custom Scoville specifications. The shift is most visible in United States snack manufacturing corridors, where kettle chip and nut processors demand heat-unit precision that commodity suppliers cannot match.
Habanero Salt Market Segmentation
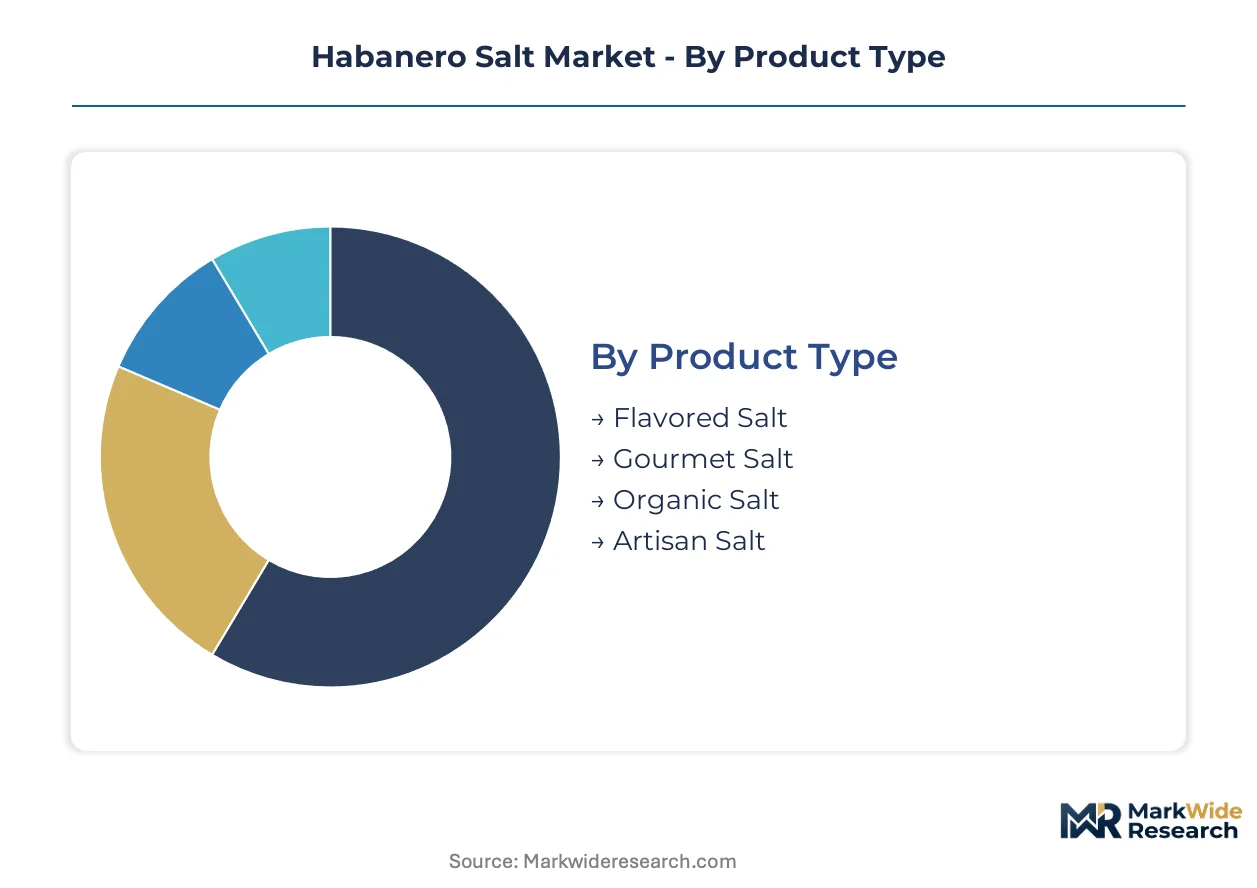
Habanero salt producers configure manufacturing assets around distinct heat-delivery specifications and mineral base grades. Segment boundaries determine sourcing protocols for Capsicum chinense cultivars and evaporated sodium chloride purity tiers.
Product Type:
Supply concentration clusters around crystalline structure complexity and pepper provenance documentation requirements.
- Flavored Salt:Combines evaporated sodium chloride with ground habanero and auxiliary flavor compounds such as lime or garlic. Snack manufacturers in the United States specify precise Scoville ranges for kettle chip coatings, driving volume procurement through food service distributors.
- Gourmet Salt:Features origin-specific pepper provenance and controlled mineral content from designated evaporation facilities. German and Austrian retail networks command premium positioning through small-batch production claims and cold-smoked variants.
- Organic Salt:Requires USDA organic certification or EU organic regulation compliance for premium shelf eligibility. Supply pool constraints limit processor options to certified Capsicum chinense farms with documented soil management protocols.
- Artisan Salt:Emphasizes hand-harvested crystalline structures and traditional drying methods. Mexican processors near Yucatán leverage proximity to cultivation zones for cost-competitive small-batch output.
Gourmet salt absorbs the bulk of installed capacity; flavored salt is expanding most quickly.
Application:
Cost tier differentiation separates commodity seasoning from precision-formulated heat delivery systems.
- Cuisine:Encompasses finished dish integration in commercial and residential kitchens. Restaurants specify consistent heat-unit profiles for menu standardization across multiple locations.
- Snacks:Demands exact Scoville measurement for coating uniformity on kettle chips, nuts, and extruded products. Food manufacturers in the United States consolidate procurement through direct-import arrangements with specialized blenders.
- Seasoning:Includes retail packaged blends and bulk food service formats. Clean-label mandates from FDA and EFSA compress formulation timelines for capsaicin disclosure compliance.
- Cooking:Covers direct heat application during preparation rather than finishing. Household penetration concentrates through online retail channels with subscription replenishment models.
Seasoning commands the widest distribution footprint; snacks is climbing the fastest.
Distribution Channel:
Customer type determines fulfillment infrastructure requirements and margin capture potential.
- Online Retail:Enables direct-to-consumer penetration with subscription-based replenishment and heat-unit customization. German-speaking markets show underpenetrated expansion potential for cold-smoked variants.
- Supermarkets:Requires slotting fee negotiations and shelf positioning competition against commodity salt brands. USDA organic seals accelerate placement in specialty retail sections.
- Specialty Stores:Prioritizes origin documentation and small-batch production narratives. Artisan-grade producers secure premium pricing through controlled scarcity positioning.
- Food Service:Consolidates volume with specialized seasoning blenders capable of custom Scoville specifications. Distributors bypass traditional spice house intermediaries for direct-import arrangements.
Food service captures the highest volume throughput; online retail is gaining share fastest.
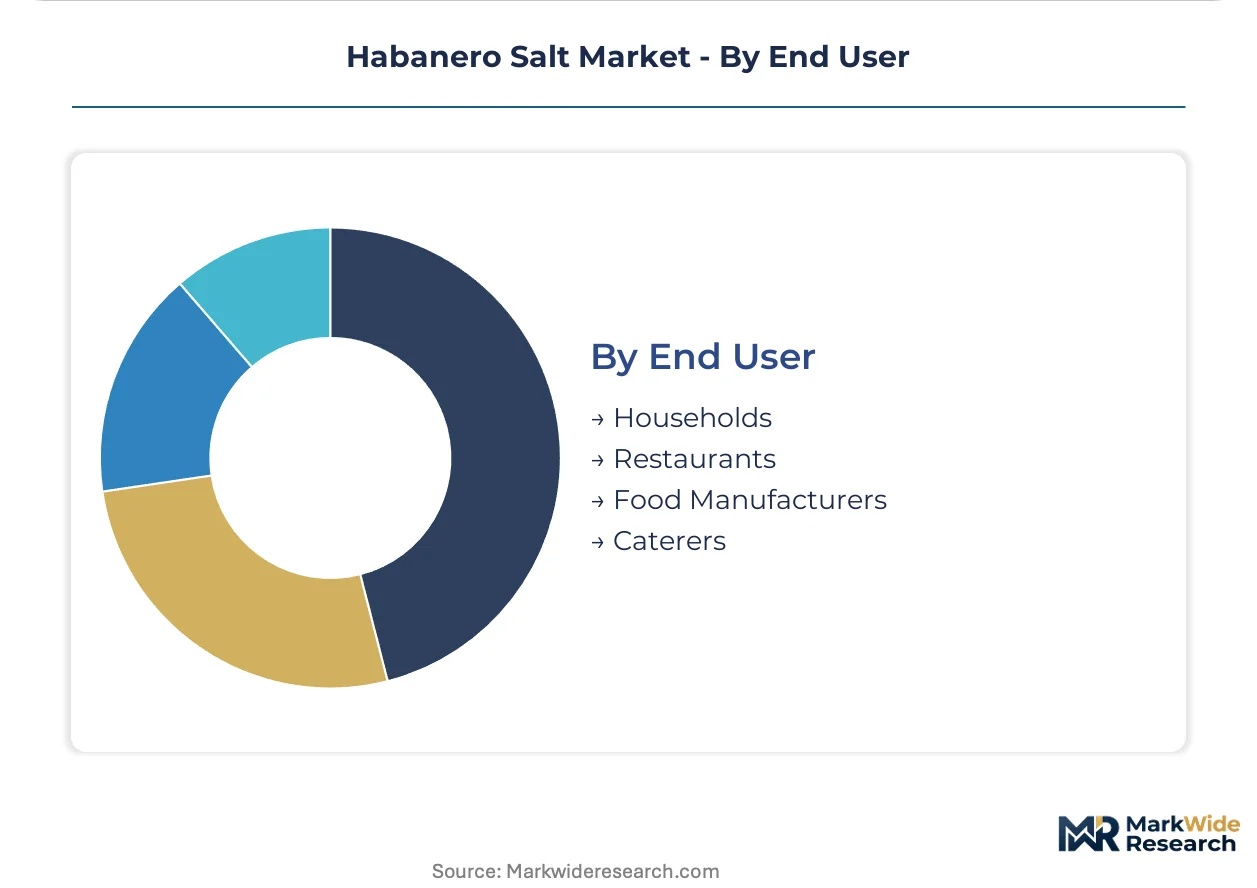
End User:
Application maturity varies across institutional procurement cycles and consumer replenishment patterns.
- Households:Purchase retail formats through supermarkets and online channels. Repeat purchase rates accelerate with standardized Scoville labeling that reduces consumer uncertainty.
- Restaurants:Demand batch-to-batch consistency for menu standardization across franchise networks. Cross-contamination protocols for allergen segregation drive capital-intensive facility requirements.
- Food Manufacturers:Specify precise heat-unit ranges for coating and blending operations. Snack processors require precision that commodity suppliers cannot match.
- Caterers:Procure bulk formats with flexible delivery scheduling for event-based demand spikes. Price sensitivity concentrates procurement through Latin American and Caribbean distribution corridors.
Food manufacturers absorb the bulk of industrial volume; households is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yucatán Peninsula cultivation zones anchor Capsicum chinense supply chains that feed processors across three continents. Habanero salt production concentrates near pepper drying corridors where mineral evaporation infrastructure intersects with established spice trade routes.
United States
Snack manufacturers in Texas and California specify precise Scoville ranges for kettle chip coatings. FDA clean-label mandates compress formulation timelines for capsain disclosure compliance. Food service distributors in Chicago and Los Angeles consolidate procurement through direct-import arrangements with specialized seasoning blenders.
Mexico
Proximity to Yucatán and Oaxaca growing regions reduces pepper drying and transport costs for artisan-grade processors. Domestic regulators enforce capsaicin concentration documentation for export-bound spice blends. Small-batch producers near Mérida leverage traditional drying methods for cold-smoked variant differentiation.
Germany
Underpenetrated direct-to-consumer channels in German-speaking markets offer expansion potential for premium-positioned variants. EFSA novel food thresholds force reformulation of heat-intense product lines before European market entry. Berlin and Munich retail networks command premium shelf positioning through USDA organic and EU organic regulation compliance.
Canada
Health Canada labeling standards govern capsaicin disclosure requirements for imported seasoning products. Toronto and Vancouver distribution corridors channel specialty retail demand for origin-specific pepper provenance claims. Cross-border procurement patterns mirror United States clean-label compression timelines.
Habanero Salt Market Competitive Landscape
Global majors compete with regional champions across procurement networks and distribution infrastructure. The vendor base spans integrated spice houses, controlled evaporation specialists, and price-accessible regional blenders. Three archetypes dominate: vertically integrated procurement networks, mineral-consistency processors, and Latin American distribution corridor competitors. Consolidation pressures concentrate volume with specialized seasoning blenders while fragmenting artisan-grade positioning.
Within the integrated procurement tier, McCormick & Company, Inc. and Morton Salt, Inc. exemplify divergent strategic anchors. McCormick represents the spice-house archetype with consolidated sourcing networks. Morton occupies the mineral-control position through evaporation facility ownership. Badia Spices, Inc. sits within the price-accessibility vector across Caribbean and Latin American corridors.
| Leading Market Players |
|---|
| Morton Salt, Inc. |
| Badia Spices, Inc. |
| McCormick & Company, Inc. |
| El Yucateco S.A. de C.V. |
| Tajin USA LLC |
| The Kraft Heinz Company |
| Lawry's Inc. |
| Red Monkey Foods, Inc. |
| Olde Thompson, LLC |
| Others |
Supply & Pricing Matrix
Capsicum chinense spot price volatility in Yucatán and Oaxaca growing regions cascades through three distinct pricing tiers, compressing margins for artisan-grade processors while concentrating margin capture with integrated spice houses that control drying and evaporation infrastructure.
Pricing Analysis
Third-party Scoville certification and organic compliance documentation are unbundled from base product pricing, creating surcharge structures that separate premium-positioned lines from commodity alternatives. Pricing stratifies across USDA organic-certified, EU organic regulation-compliant, and conventional tiers, with certification grade and volume scale driving differentiation. Cost compression in conventional flavored salt segments is intensifying because snack manufacturers consolidate procurement through direct-import arrangements. Food service distributors exhibit highest price sensitivity due to batch-volume negotiations, while specialty retail channels absorb premium positioning with lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Yucatán Peninsula Capsicum chinense cultivation, where drought cycles create 18-24 month supply disruptions that propagate through Mexican, United States, and German processing corridors. Raw material dependencies center on evaporated sodium chloride from controlled brine facilities, dried habanero fruit, and cold-smoking fuel stocks. Tariff exposure on capsaicin extract imports from Mexico into European markets constrains formulation flexibility for heat-intense variants. Distribution runs through food service direct-import channels, specialty retail networks, and online subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USDA organic-certified Capsicum chinense farm capacity constraints prop pricing premiums, creating a supply-constrained structure where certification investment outpaces available acreage.
For Market Incumbents: Anchor mineral consistency through controlled evaporation facility ownership near established pepper drying corridors, defending against price-accessible regional blenders entering through Latin American distribution corridors. Prioritize backward integration into certified organic pepper cultivation to secure captive supply of constrained raw material. For New Entrants and Emerging Players: Modular cold-smoking technology offers entry into premium tiers without dedicated facility capital, targeting underpenetrated direct-to-consumer channels in German-speaking markets with origin-specific provenance narratives. Position through online retail subscription models with heat-unit customization capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor artisan-grade processors in Mexico with established Yucatán cultivation relationships and traditional drying method differentiation. Monitor EFSA novel food threshold evolution as inflection indicator for European market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive supply of USDA-certified Capsicum chinense secures margin capture against volatile spot markets. |
| Cold-Smoking Technology Deployment | Modular smoke chambers enable flavor differentiation without capital-intensive dedicated facilities. |
| Direct-to-Consumer Channel Expansion | German online retail penetration bypasses slotting fee barriers of supermarket consolidation. |
| Third-Party Scoville Certification Investment | Standardized heat-unit labeling accelerates repeat purchase rates in household segments. |
| EU Organic Regulation Compliance | Premium shelf eligibility unlocks pricing power in Berlin and Munich retail networks. |
Research Methodology
Multi-period observation of Capsicum chinense cultivation yields, evaporated sodium chloride pricing indices, and Scoville measurement protocol adoption anchored the trend analysis, supplemented by interviews with specialty food procurement directors, artisan salt processors, FDA regulatory consultants, EU organic certification auditors, and food service distribution channel managers. Secondary validation drew from USDA organic certification databases, EFSA novel food submission records, customs trade flow data, and SEC filings of integrated spice houses. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Input-output matrices mapped product type, application, distribution channel, and end-user segmentation dimensions against regional regulatory clusters and certification tier eligibility. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs included drought cycle frequency in primary cultivation zones and EFSA capsaicin threshold evolution timelines.
Several conditions sit outside the modeled scope, including unannounced regulatory shifts, extreme weather events disrupting Yucatán harvests, and trade policy revisions affecting capsaicin extract tariffs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Ghost Pepper Salt Market
Spices and Seasonings
US Gourmet Salt Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Garlic Salt Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Wasabi Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Hot Pot Seasoning Market
Spices and Seasonings
Mint Oils Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Celery Seed Extract Powder Market
Spices and Seasonings
Garlic Oil Market
Spices and Seasonings
Paprika Powder Market