
 Chef Bases Market | 2026-2036
Chef Bases Market Size, Share, and Industry Trends Forecast 2026-2036
Chef Bases Market Outlook
Buyer concentration among multi-unit foodservice operators is rebalancing as regional restaurant groups expand faster than legacy national chains. Traulsen leverages its refrigeration heritage to cross-sell chef base storage solutions into commercial kitchens. TRUE sustains competitive pressure through specialized reach-in configurations that integrate with base-preparation workflows. Hoshizaki anchors its position with ice-making expertise that extends into temperature-controlled holding for prepared bases.
Chef bases comprise concentrated flavor foundations—vegetable, meat, seafood, or mushroom-derived—that reconstitute into stocks, sauces, and soups through dilution with water or other liquids, typically packaged in pouches or tubs for foodservice scale. Powdered bases lead volume due to extended shelf stability and lower shipping weights, while paste bases capture premium margin pools in chef-driven independent restaurants demanding fresher flavor release. Liquid bases compete in high-throughput institutional settings where speed of reconstitution outweighs per-unit cost, and granulated formats occupy niche positions in manufacturing applications requiring precise dosing control.
USDA grading standards for meat-derived ingredients and FDA allergen labeling rules shape formulation decisions and supplier qualification requirements across domestic manufacturers. NSF International certification for commercial food equipment creates parallel compliance obligations for base-dispensing systems integrated into kitchen lines. Stakeholders must monitor how state-level sodium reduction mandates in California and New York propagate into base formulation specifications.
Market Dynamics
Full-service restaurant chains are consolidating procurement of concentrated bases to standardize flavor profiles across hundreds of locations, forcing manufacturers to choose between scale-driven commoditization and premium positioning through cleaner label formulations.
Growth Catalysts
- FSMA Traceability Mandates:The FDA's updated Food Safety Modernization Act requirements for supply chain traceability are pressuring manufacturers toward reformulation investments that simultaneously reduce sodium and eliminate artificial additives.
- Chain Restaurant Expansion:Institutional foodservice operators are expanding procurement of concentrated bases to standardize outputs across dispersed kitchen networks, creating volume pull for shelf-stable formats.
- Commercial Kitchen Density:The United States maintains the highest concentration of commercial kitchen infrastructure and chain restaurant penetration globally, anchoring demand visibility for base manufacturers.
Market Restraints
- Input Cost Volatility:Meat-derived ingredient costs fluctuate with USDA grading standards and livestock supply cycles, compressing margin predictability for manufacturers dependent on animal-based stocks.
- Regulatory Fragmentation:State-level sodium reduction mandates in California and New York propagate into divergent formulation specifications, forcing product line complexity that raises compliance costs.
- Substitution Pressure:Scratch cooking resurgence in chef-driven independent restaurants threatens paste base margins as operators reject concentrated formats for house-made alternatives.
Strategic Opportunities
- Mushroom-Derived Bases:Umami-forward fungal concentrates capture white space in plant-forward menu development as operators seek depth without animal inputs.
- Granulated Manufacturing Applications:Precise dosing control requirements in co-manufacturing and CPG production create niche demand for flowable formats absent from foodservice-centric portfolios.
- NSF-Certified Dispensing Integration:Equipment manufacturers embedding base-dispensing systems into kitchen lines create bundled specification opportunities for compliant formulation suppliers.
Industry Challenges
- Clean Label Reformulation:Removing artificial preservatives while maintaining shelf stability demands R&D investment timelines that strain mid-tier manufacturers without captive flavor science capabilities.
- Allergen Segregation:FDA allergen labeling rules require dedicated production lines or validated cleaning protocols that constrain capacity flexibility and extend batch turnaround times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chef Bases Market |
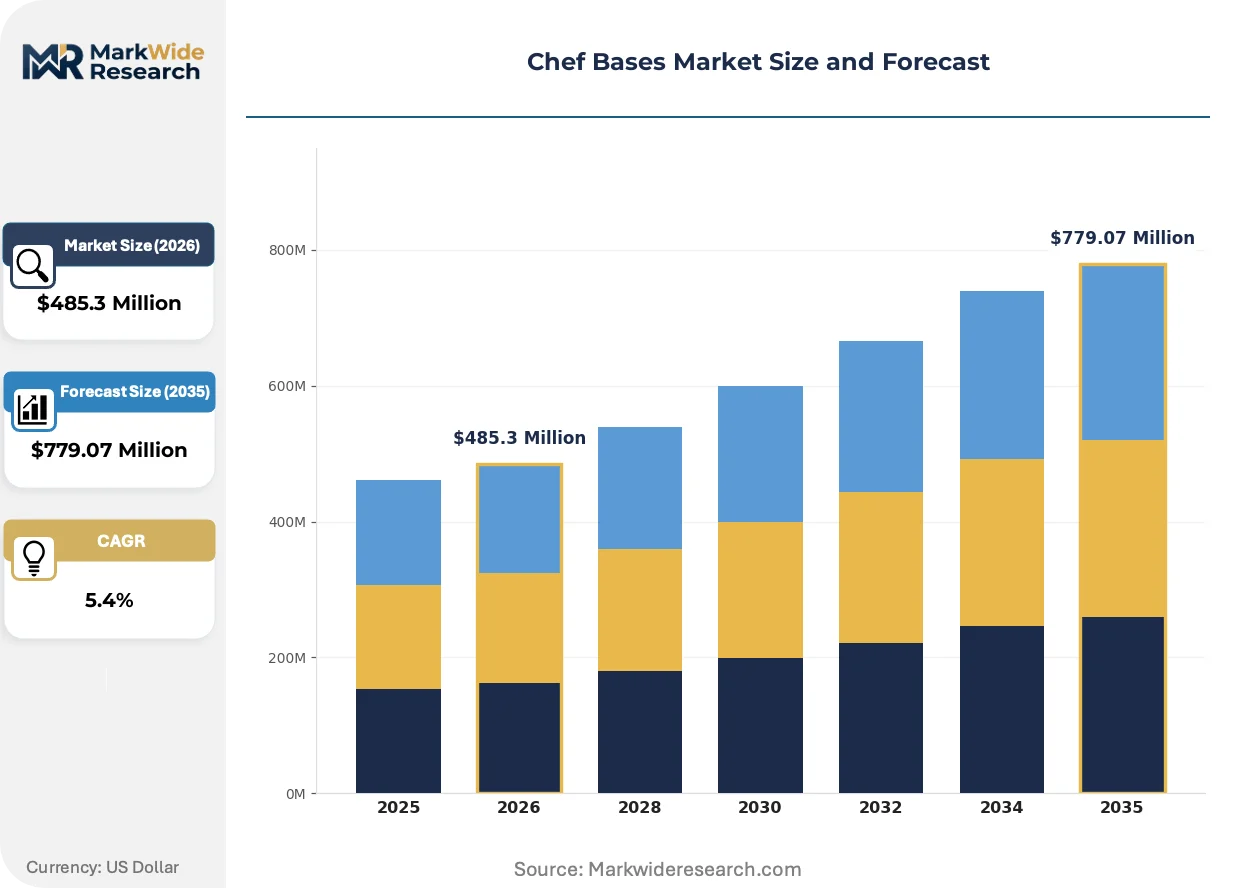
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $779.07 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Bases, Powdered Bases, Paste Bases, Granulated Bases Ingredient Type: Vegetable, Meat, Seafood, Mushroom Packaging Type: Bottles, Pouches, Tubs, Cans Distribution Channel: Retail, Food Service, Online, Wholesalers |
| Companies Covered | Traulsen, TRUE, Hoshizaki, Turbo Air, Everest Refrigeration, Delfield, Continental Refrigeration, Silver King, Illinois Tool Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chef Bases Market Strategic Shifts
Flavor extraction technologies and regulatory pressure on sodium content are compressing traditional formulation approaches while opening premium positioning for manufacturers who solve the stability-clean label tradeoff.
Spray-dried encapsulation technology is absorbing volatile aromatic compounds into lipid or carbohydrate matrices, extending flavor fidelity in powdered bases beyond conventional dehydration limits. High-throughput institutional cafeterias and healthcare foodservice operators are adopting these formats at accelerated pace to reduce reconstitution labor. The technology is absorbing market share from conventional air-dried powders by enabling cleaner ingredient decks without sacrificing shelf life.
California's state-level sodium reduction mandates are propagating into procurement specifications that exceed federal baseline requirements, forcing national suppliers to maintain dual formulation inventories. Manufacturers serving multi-state operators face SKU proliferation costs or margin sacrifice from lowest-common-denominator reformulation. Paste and liquid base categories bear disproportionate impact as their higher moisture content concentrates sodium per serving volume.
Direct procurement relationships between regional restaurant groups and specialty base manufacturers are displacing traditional broadline distributor intermediaries. Independent restaurant clusters in metropolitan areas are consolidating purchasing through group purchasing organizations that demand format customization and shorter lead times. This pattern concentrates most visibly in secondary US cities where regional chain expansion outpaces legacy national brand penetration.
Chef Bases Market Segmentation
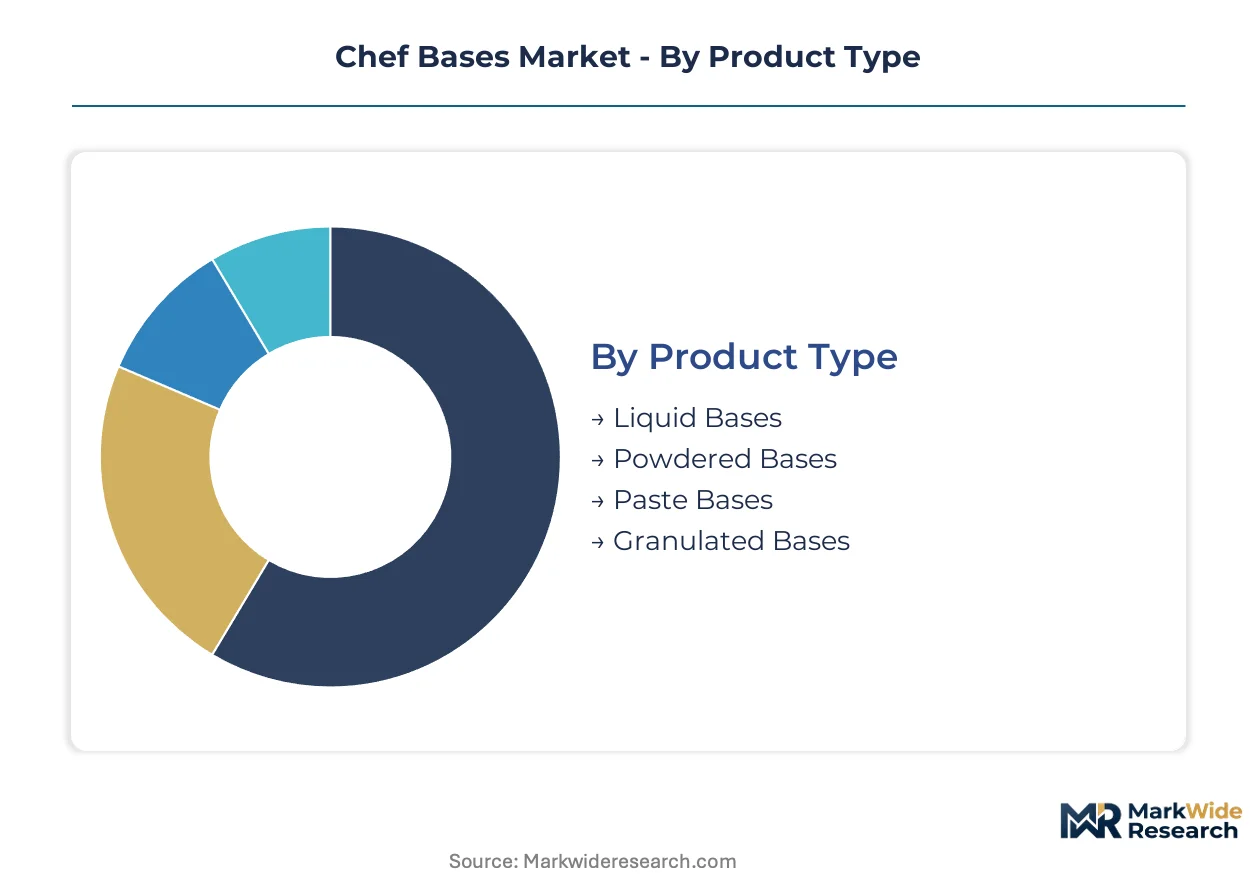
Chef base manufacturers align product formats with kitchen workflow constraints and storage infrastructure. Format selection directly determines reconstitution speed, shelf life, and compatibility with existing dispensing equipment. Procurement patterns across chain restaurants and institutional operators concentrate demand into specific category combinations.
Product Type:
Replacement cycles for base formats accelerate as operators upgrade from legacy air-dried powders to encapsulated alternatives that preserve volatile aromatics.
- Powdered Bases:Dehydrated concentrates deliver extended shelf stability and reduced shipping weights through low moisture content. Full-service restaurant chains in the United States standardize procurement across dispersed locations, leveraging bulk packaging for cost predictability.
- Liquid Bases:Pre-hydrated concentrates eliminate reconstitution labor and integrate directly into high-throughput production lines. Institutional cafeterias and healthcare foodservice operators adopt these formats where speed outweighs per-unit cost premiums.
- Paste Bases:Semi-moist concentrates balance flavor fidelity with portion control in chef-driven independent restaurants.
- Granulated Bases:Flowable particles enable precise dosing in manufacturing applications and co-manufacturing environments.
Powdered bases sit at the top of the volume ranking, with liquid bases climbing the fastest as institutional operators prioritize labor reduction.
Ingredient Type:
Ingredient sourcing strategies diverge based on USDA grading exposure and plant-forward menu development priorities.
- Vegetable:Mirepoix-derived and tomato-based concentrates provide neutral foundations adaptable across cuisines. California and New York sodium reduction mandates pressure reformulation of these high-volume categories.
- Mushroom:Umami-forward fungal extracts capture white space in plant-forward menu development as operators seek depth without animal inputs.
- Meat:Beef, chicken, and pork-derived stocks face input cost volatility tied to livestock supply cycles and USDA grading standards.
- Seafood:Fish and shellfish concentrates serve specialized coastal restaurant clusters and premium positioning strategies.
Vegetable bases command the largest production volumes, with mushroom-derived alternatives gaining share fastest among regional restaurant groups pursuing differentiation.
Packaging Type:
Packaging selection reflects storage infrastructure constraints and dispensing system compatibility in commercial kitchen environments.
- Pouches:Flexible film packaging reduces shipping cube and storage footprint for high-velocity SKUs. Chain restaurant operators favor pouch formats for back-of-house efficiency in space-constrained kitchens.
- Tubs:Rigid containers protect paste and semi-moist formats from compression damage during distribution.
- Bottles:Pour-controlled dispensing suits liquid base categories in institutional settings with standardized portion protocols.
- Cans:Metal containers provide shelf stability for long-dated inventory in remote or emergency foodservice operations.
Pouches dominate procurement volumes among multi-unit operators, with tub formats expanding most quickly in paste base premium segments.
Distribution Channel:
Channel strategy determines margin capture and customer relationship depth across operator scale tiers.
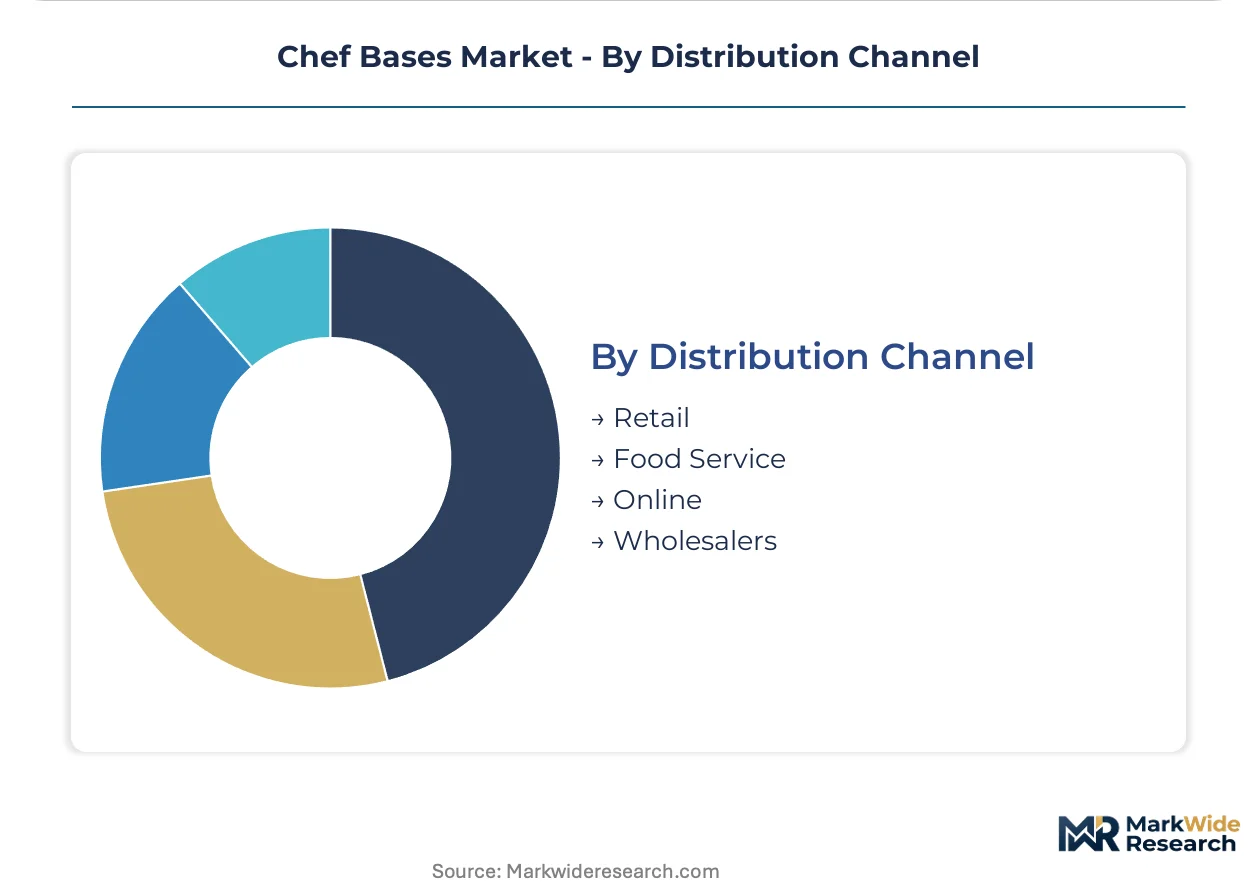
- Food Service:Direct and broadline distribution to commercial kitchens captures the majority of base volume. National broadline distributors consolidate procurement for mid-scale regional chains.
- Wholesalers:Cash-and-carry and independent distributors serve smaller independent restaurants outside major metropolitan clusters.
- Online:E-commerce platforms enable specialty base access for chef-driven independents and testing of limited-production formats.
- Retail:Consumer-packaged formats reach home cooks and small-scale catering operations through grocery and club channels.
Food service channels anchor volume concentration, with online distribution expanding most quickly as direct procurement relationships displace traditional intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial kitchen workforce density in the United States anchors global chef base procurement volumes, with specialized culinary talent clusters in Chicago, New York, and Los Angeles driving format innovation and premium positioning strategies.
United States
Chain restaurant penetration exceeding any other market concentrates procurement power among multi-unit operators standardizing flavor profiles across dispersed locations. FDA Food Safety Modernization Act traceability mandates pressure manufacturers toward cleaner label reformulations that eliminate artificial preservatives. The Chicago metropolitan area hosts dense clusters of institutional foodservice operators and broadline distributor headquarters coordinating national base procurement.
Germany
Precision manufacturing heritage extends into commercial kitchen equipment integration, creating bundled specification opportunities for base-dispensing system suppliers. EFSA clean labeling guidelines and EU Green Deal sustainability reporting requirements shape formulation transparency expectations. The Rhine-Ruhr industrial corridor concentrates food manufacturing co-packers demanding granulated base formats for precise dosing control.
Japan
Umami-forward culinary tradition drives adoption of mushroom-derived concentrates as animal-free depth alternatives in plant-forward menu development. METI food technology promotion programs support spray-dried encapsulation research extending flavor fidelity in powdered formats. The Kanto region surrounding Tokyo anchors high-density commercial kitchen infrastructure serving institutional and corporate foodservice segments.
United Kingdom
Post-Brexit regulatory divergence from EU food additive standards creates formulation complexity for suppliers serving both markets. FSA allergen labeling enforcement and salt reduction campaigns pressure sodium content reformulation in high-volume vegetable base categories. Greater London's independent restaurant clusters consolidate purchasing through group purchasing organizations demanding customized formats and shortened lead times.
France
Chef-driven gastronomic culture sustains premium positioning for paste base formats emphasizing fresher flavor release in independent restaurants. ANSM food supplement oversight and DGCCRF commercial fraud enforcement maintain strict ingredient origin documentation requirements. The Lyon gastronomic cluster represents a concentration of culinary schools and independent operators resisting concentrated base adoption in favor of scratch preparation traditions.
Chef Bases Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Refrigeration equipment heritage companies leverage temperature-controlled storage expertise to cross-sell into base preparation workflows. Three strategic archetypes dominate: equipment-integrated solution providers, format-specialized ingredient suppliers, and broadline distribution intermediaries. Competitive moves concentrate on NSF-certified dispensing system partnerships and geographic expansion through regional distributor acquisitions.
Within the equipment-integrated tier, Traulsen, TRUE, and Hoshizaki exemplify divergent specialization strategies. Traulsen represents the refrigeration heritage archetype extending into kitchen workflow optimization. TRUE occupies a position emphasizing reach-in configuration flexibility for base-preparation environments. Hoshizaki anchors the temperature-control expertise segment with ice-making heritage extending into holding equipment for prepared bases.
| Leading Market Players |
|---|
| Traulsen |
| TRUE |
| Hoshizaki |
| Turbo Air |
| Everest Refrigeration |
| Delfield |
| Continental Refrigeration |
| Silver King |
| Illinois Tool Works |
| Others |
Value Chain & Pricing Dynamics
Meat-derived ingredient costs originating from USDA-graded livestock supply chains cascade through three distinct pricing tiers before reaching institutional foodservice operators, with powder base commoditization at the bottom and encapsulated premium formats commanding significant uplifts at independent restaurants.
Pricing Analysis
Bundled equipment-formulation packages from refrigeration heritage suppliers compete against unbundled commodity procurement through broadline distributors, with price differentiation resting on NSF certification tiers and after-sales service integration. Three-tier pricing structure across premium encapsulated powders, standard air-dried formats, and economy bulk tubs dominates transaction structures. Cost compression in standard powder tiers is intensifying because input volatility from livestock cycles compresses manufacturer margins. Regional restaurant groups consolidated through group purchasing organizations exhibit highest price sensitivity, while chef-driven independents purchasing paste bases show least elasticity.
Supply Chain Analysis
Single-source vulnerability sits with concentrated meat stock processors in the United States, where USDA grading standards and livestock supply cycles create input bottlenecks. Manufacturing draws from dehydrated vegetable suppliers in California, fungal extract processors in the Pacific Northwest, and imported seafood concentrate specialists in East Asia. Regulatory fragmentation across state-level sodium mandates in California and New York introduces compliance complexity that strains multi-state distribution. Distribution runs through national broadline networks for chain restaurants, with direct procurement relationships displacing traditional intermediaries among regional operator clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in spray-dried encapsulation technology adoption and mushroom-derived base premiumization, as operators trade up from commodity powders toward cleaner-label alternatives with extended flavor fidelity.
For Market Incumbents: Deepen captive flavor science capabilities through in-house production of encapsulated powder technologies, defending against substitution pressure from scratch cooking resurgence in chef-driven independents. Secure backward integration into dehydrated vegetable supply chains in California to buffer input cost volatility from external commodity markets.
For New Entrants and Emerging Players: Begin with white-space penetration in granulated manufacturing applications for co-manufacturing environments, where precise dosing control requirements exceed incumbent foodservice-centric portfolio coverage. Target regional restaurant groups in secondary metropolitan clusters pursuing plant-forward menu differentiation through direct procurement relationships that bypass established broadline networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack R&D bandwidth to solve clean label reformulation challenges within compressed timelines demanded by FDA traceability mandates. Acquisition target archetypes include encapsulated technology specialists and mushroom-derived concentrate innovators. Watch spray-dried encapsulation patent filings as inflection indicator for premium format adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean Label Reformulation Investment | Resolves stability-preservative tradeoff demanded by FDA FSMA traceability rules. |
| Encapsulation Technology Licensing | Extends flavor fidelity beyond conventional dehydration limits for powder bases. |
| Regional Distributor Acquisition | Captures direct procurement relationships displacing broadline intermediaries. |
| Mushroom-Derived Base Development | Addresses plant-forward menu depth requirements without animal input exposure. |
| NSF-Certified Dispensing Integration | Creates bundled specification lock-in with commercial kitchen equipment buyers. |
Study Parameters
Bottom-up foodservice operator modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with executive chefs at multi-unit chains, broadline distributor procurement directors, base manufacturer R&D leads, and institutional foodservice operators combined with secondary validation from FDA FSMA guidance documents, USDA livestock grading reports, NSF International certification databases, and state-level sodium mandate regulatory filings. Triangulation across these sources ensures demand-side consumption patterns align with supply-side production volumes.
Historical trendline analysis of format adoption rates and ingredient cost trajectories informs projection frameworks across the analysis window. Segmentation dimensions modeled include product format tier, ingredient source category, packaging configuration, distribution channel structure, and operator scale archetype. CAGRs derive from curve-fitting against documented substitution elasticities between powder, liquid, paste, and granulated alternatives, incorporating spray-dried encapsulation penetration assumptions and mushroom-derived base share capture parameters.
Several conditions sit outside the modeled scope, including force majeure livestock supply disruptions, abrupt federal preemption of state sodium regulations, and breakthrough fermentation technologies displacing concentrated extraction methods. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Paprika Powder Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Turkey Flavors Market
Spices and Seasonings
Ghost Pepper Salt Market
Spices and Seasonings
Onion Essential Oil Market
Spices and Seasonings
Jalapeno Salt Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Herbs and Spices Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
South America Seasoning and Spices Market