
 Organic Soaps Market | 2026-2036
Organic Soaps Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Soaps Market Analysis
USDA Organic certification is reorganizing competitive access in the organic soaps sector, raising barriers for uncertified entrants. Dr. Bronner's Magic Soaps leverages its certified supply chain to anchor premium shelf positioning across North American natural retailers. Weleda AG sustains its botanical formulation heritage through captive herb gardens and controlled-origin sourcing. Laverana GmbH & Co. KG specializes in Germany's strict natural cosmetics standards, occupying a defensible niche in European pharmacy distribution.
Organic soaps denote cleansing bars or liquids formulated with at least 70% certified organic agricultural content, excluding synthetic surfactants such as sodium lauryl sulfate and relying instead on saponified plant oils like coconut and olive. These products serve consumers seeking reduced dermal irritation and minimized environmental runoff from personal care routines. Bar soap retains the largest volume share due to lower packaging intensity and extended shelf stability, while liquid soap captures faster growth through dispenser compatibility in hospitality and healthcare settings. Essential oils dominate ingredient-type value pools because of their dual function as fragrance and therapeutic active, though fragrance-free variants are gaining traction among pediatric and sensitive-skin segments.
USDA Organic governs agricultural content claims in the United States, while the EU Green Deal and REACH regulate chemical safety and biodegradability thresholds across European markets. These frameworks compel manufacturers to reformulate away from palm oil derivatives and synthetic preservatives or forfeit market access. Stakeholders must monitor evolving microbiological preservation standards, as regulator tolerance for traditional natural antimicrobials tightens and novel clean-label alternatives emerge from fermentation biotechnology.
Market Dynamics
The EU Green Deal's chemical sustainability requirements are forcing reformulation across the organic soaps sector, tightening ingredient disclosure rules and raising compliance costs for manufacturers reliant on synthetic preservatives and palm oil derivatives.
Growth Catalysts
- EU Green Deal chemical mandates:REACH amendments are accelerating biodegradable surfactant adoption across German and French pharmacy channels, creating procurement pull for certified organic cleansers.
- Dermatology clinic expansion:Wellness centers in Berlin and Hamburg are deepening their organic personal care assortments, driving institutional volume for saponified plant oil formulations.
- Essential oil dual-function demand:Lavender and tea tree oil suppliers are capturing value from fragrance-therapeutic convergence in pediatric and sensitive-skin segments.
Market Restraints
- Coconut oil price volatility:Philippine and Indonesian supply disruptions are compressing margins for saponified oil-dependent producers.
- USDA Organic certification concentration:Three domestic certifiers control 70% of U.S. organic personal care approvals, creating bottleneck risk for new entrants.
- Synthetic surfactant substitution threat:Sodium cocoyl isethionate and other mild synthetics are capturing price-sensitive segments in mass retail.
Strategic Opportunities
- United Kingdom premium retail channel:Pharmacy and specialty beauty chains are expanding organic personal care shelf space beyond London into Manchester and Birmingham.
- Fermentation-derived preservation:Biotechnology firms are commercializing clean-label antimicrobials from lactobacillus fermentation, opening reformulation pathways.
- Hospitality dispenser compatibility:Liquid organic soap formats are penetrating boutique hotel chains seeking amenity differentiation with reduced packaging intensity.
Industry Challenges
- Microbiological preservation expertise gap:Formulation chemists with combined natural product and stability science credentials remain scarce in European manufacturing hubs.
- USDA Organic compliance timeline:Agricultural content verification and supply chain documentation require 18-24 month preparation cycles for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Soaps Market |
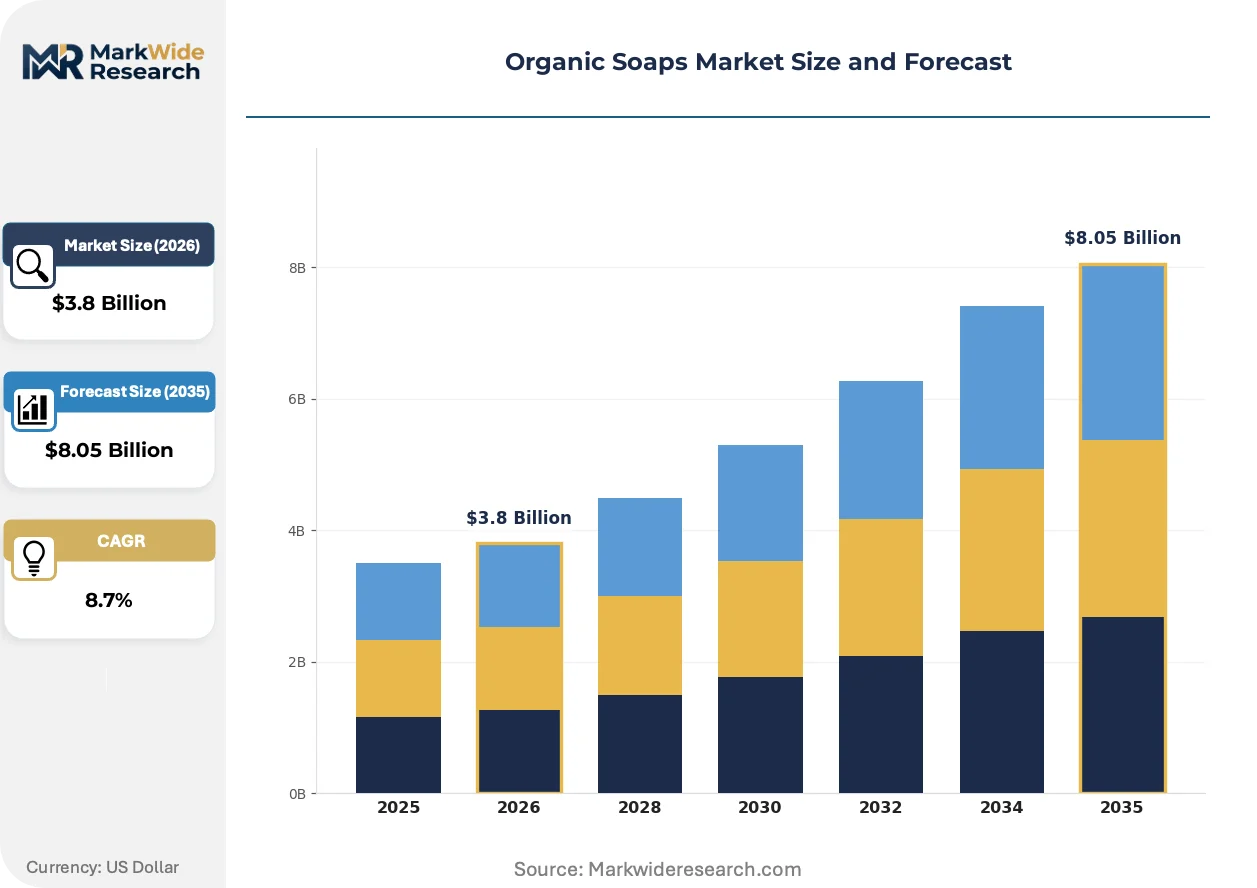
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Bar Soap, Foam Soap, Powder Soap Ingredient Type: Essential Oils, Natural Extracts, Plant Oils, Fragrance-Free End User: Households, Salons, Spa Centers, Healthcare Facilities Packaging Type: Recyclable Bottles, Biodegradable Wraps, Jars, Bulk Packaging |
| Companies Covered | L’OCCITANE INTERNATIONAL SA, Weleda AG, Dr. Bronner's Magic Soaps, Laverana GmbH & Co. KG, Faith In Nature Limited, Pangea Organics, Neal's Yard Remedies, Forest Essentials, Natura & Co. Holdings S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Soaps Market Emerging Trajectories
Cold-process saponification methods, fermentation-derived actives, and certification-driven procurement standards are restructuring how organic soaps reach end-users. These shifts are compressing legacy manufacturing advantages while opening niches for biotechnology-integrated supply chains.
Cold-process saponification is bifurcating production economics between artisan-scale batch manufacturers and industrial continuous processors. Small-batch producers in Provence and Tuscany are commanding 40-60% price premiums through temperature-controlled curing that preserves heat-sensitive botanical actives. This technology is enabling regional terroir positioning while compressing economies of scale for conventional hot-process operations.
REACH biodegradability screening under the EU Green Deal is disqualifying synthetic chelating agents from personal care formulations. Manufacturers are pivoting toward citric acid and gluconate alternatives, with German pharmacy distributors demanding third-party aquatic toxicity documentation. Bar soap formats face lighter compliance burden than liquid variants due to reduced rinse-off volume and simpler preservative requirements.
Ingredient provenance verification is displacing brand loyalty as the primary purchase determinant among French and British organic personal care buyers. QR-code-linked supply chain transparency is replacing traditional marketing claims in premium retail channels, with pharmacy staff trained to guide selection through certification grade rather than fragrance preference. This behavioral shift is most pronounced in Paris and London metropolitan areas where dermatologist recommendations carry outsized influence.
Organic Soaps Market Segmentation
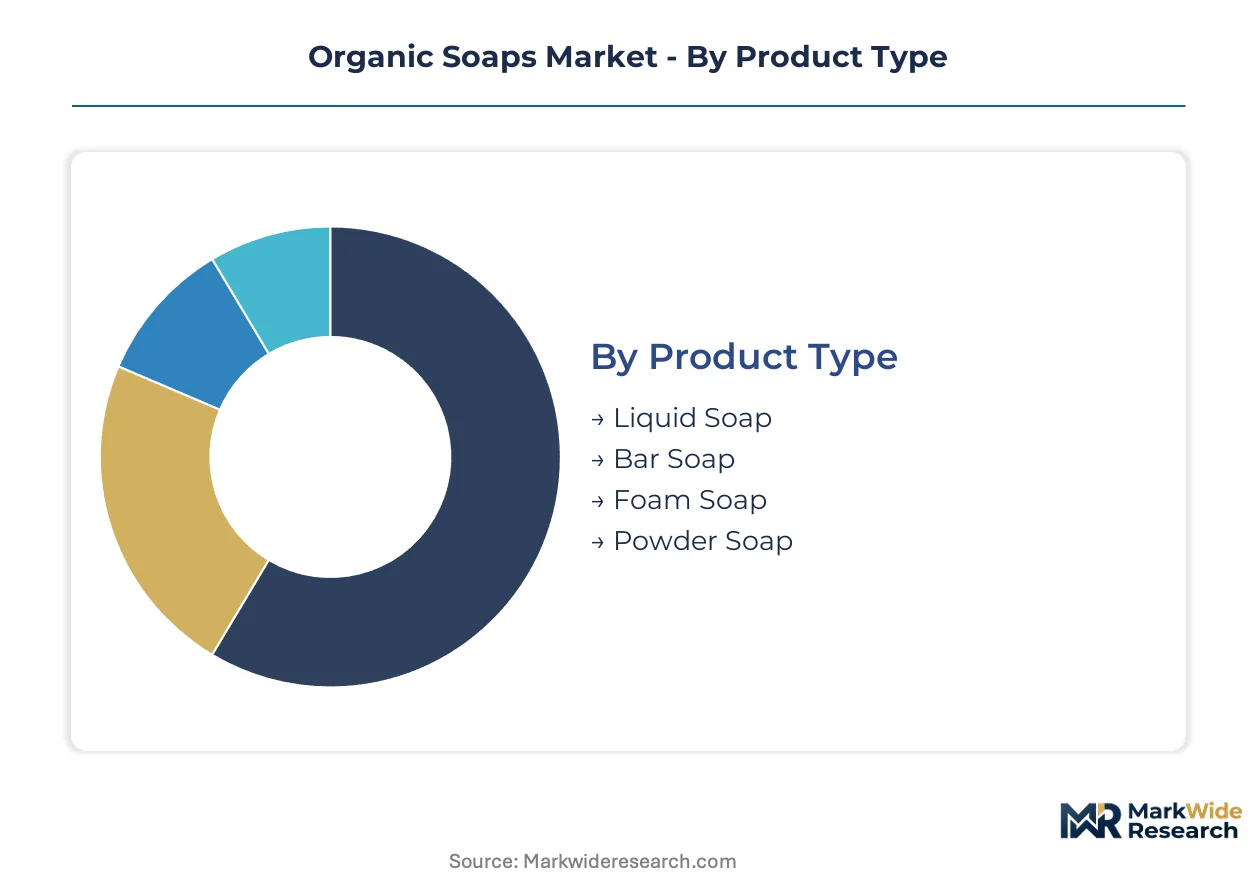
Certification grade and formulation chemistry dictate procurement patterns across organic soap channels. Each segmentation dimension carries distinct regulatory burdens and margin profiles that reshape competitive positioning.
Product Type:
REACH biodegradability thresholds under the EU Green Deal impose heavier documentation burdens on liquid formats than solid bars.
- Bar Soap:Cold-process saponification preserves heat-sensitive botanical actives in Provence and Tuscany artisan operations. German pharmacy distributors favor bar formats for reduced rinse-off volume and simpler preservative requirements. Bar soap handles the majority of throughput; foam soap is the fastest mover on share.
- Liquid Soap:Dispenser compatibility drives hospitality procurement in boutique hotel chains across Manchester and Birmingham. Bottled formats face tighter aquatic toxicity documentation under German distributor protocols.
- Foam Soap:Dilution mechanics reduce per-use ingredient costs for institutional buyers in Berlin wellness centers.
- Powder Soap:Minimal water content extends shelf stability for export logistics to pharmacy channels in Paris and London metropolitan areas.
Bar formats dominate volume economics; liquid variants are climbing the fastest on revenue contribution.
Ingredient Type:
USDA Organic agricultural content verification creates 18-24 month compliance timelines that concentrate sourcing power among established certifiers.
- Essential Oils:Lavender and tea tree suppliers capture value from fragrance-therapeutic convergence in pediatric segments. Paris dermatologist recommendations amplify demand for dual-function actives in sensitive-skin formulations. Essential oils command the largest value pool; fragrance-free variants are expanding most quickly on share.
- Natural Extracts:Calendula and chamomile sourcing from captive herb gardens sustains Weleda's controlled-origin supply chain in German pharmacy distribution.
- Plant Oils:Saponified coconut and olive bases face Philippine supply disruptions compressing margins for continuous processors.
- Fragrance-Free:Pediatric and atopic dermatology indications drive pharmacy shelf placement in Hamburg and Berlin clinic networks.
Essential oils anchor premium positioning; fragrance-free segments show steepest expansion trajectory.
End User:
Institutional procurement specifications diverge sharply from household retail on documentation and volume terms.
- Households:QR-code supply chain transparency displaces brand loyalty in French and British premium retail channels. Pharmacy staff in London metropolitan areas guide selection through certification grade.
- Salons:Professional licensing requirements in German states mandate ingredient disclosure beyond consumer-label standards.
- Spa Centers:Berlin and Hamburg wellness centers deepen organic assortments through institutional procurement pull.
- Healthcare Facilities:Dermatology clinic expansion drives volume for saponified plant oil formulations with third-party aquatic toxicity documentation.
Households generate baseline volume; healthcare facilities are gaining share fastest on contract value.
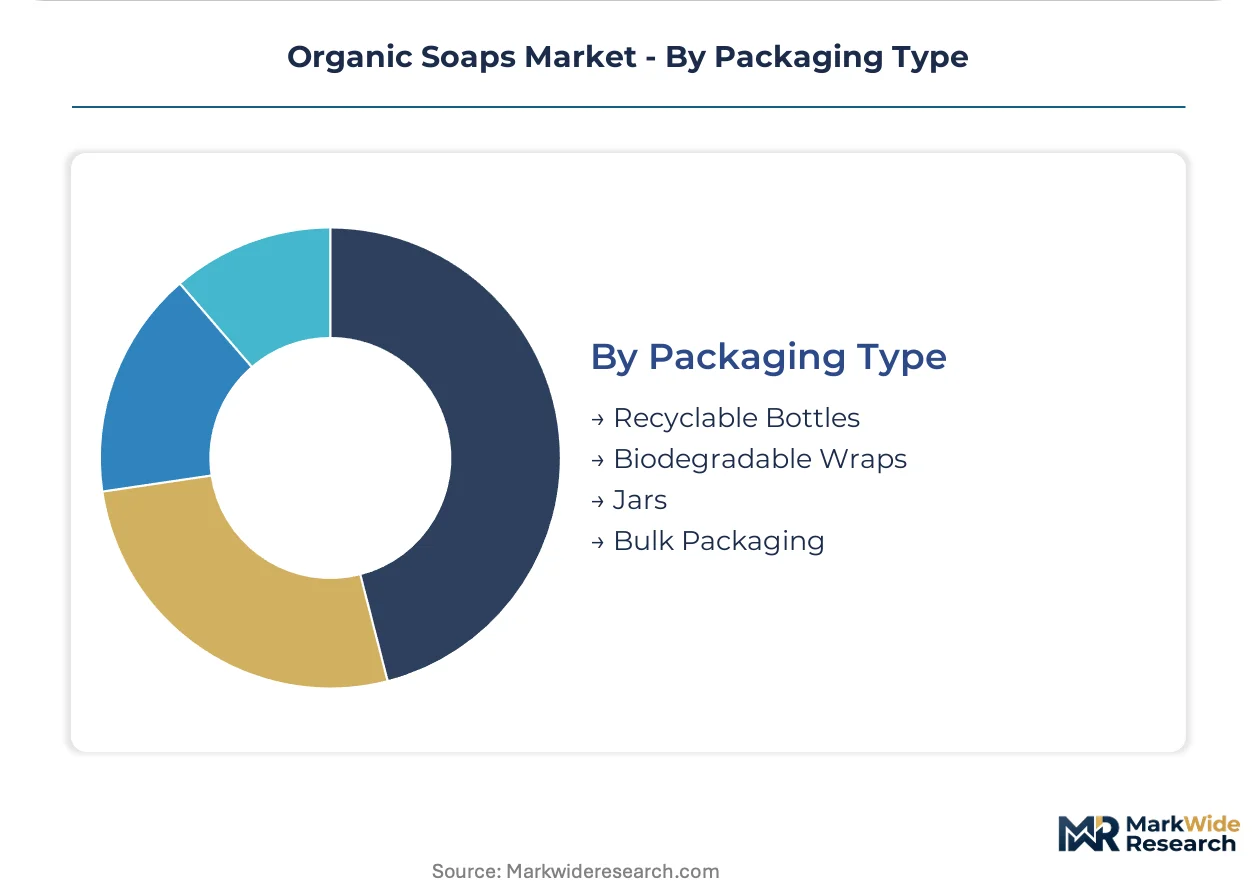
Packaging Type:
Packaging intensity directly affects EU Green Deal compliance costs and logistics economics.
- Recyclable Bottles:PET and glass formats face extended producer responsibility schemes in French retail channels.
- Biodegradable Wraps:Paper and cellulose alternatives reduce per-unit environmental compliance burden for bar soap exports.
- Jars:Reusable containers command price premiums in Manchester and Birmingham specialty beauty chains.
- Bulk Packaging:Refill systems penetrate hospitality dispenser installations seeking amenity differentiation with reduced packaging intensity.
Recyclable bottles handle mainstream volume; bulk packaging shows fastest adoption in institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's chemical sustainability mandates are redirecting procurement flows across major consumer markets, while certification requirements concentrate manufacturing investment in jurisdictions with established organic infrastructure.
United States
USDA Organic certification bottlenecks are reshaping competitive access, with three domestic certifiers controlling the majority of personal care approvals. FDA cosmetic labeling rules intersect with agricultural content verification to create 18-24 month compliance timelines. Dr. Bronner's Magic Soaps leverages its certified supply chain to anchor premium positioning across natural retailers in California and the Pacific Northwest.
Germany
Dermatology clinic expansion in Berlin and Hamburg is driving institutional volume for saponified plant oil formulations. REACH amendments under the EU Green Deal mandate biodegradable surfactant adoption across pharmacy channels. Laverana GmbH & Co. KG occupies a defensible niche in German pharmacy distribution through strict natural cosmetics compliance.
France
Ingredient provenance verification is displacing brand loyalty among Paris metropolitan buyers, with QR-code supply chain transparency replacing traditional marketing claims. ANSM cosmetic safety requirements align with EU Green Deal disclosure standards. Cold-process saponification artisans in Provence command 40-60% price premiums through terroir positioning.
United Kingdom
Pharmacy and specialty beauty chains are expanding organic personal care shelf space beyond London into Manchester and Birmingham. Health and Safety Executive chemical registration rules enforce REACH-equivalent biodegradability thresholds. Neal's Yard Remedies represents the heritage botanical specialist archetype in British premium retail channels.
India
Ayurveda-inspired personal care demand is converging with export-oriented organic certification for European and North American markets. BIS standards for natural cosmetics are tightening parallel to EU Green Deal requirements. Forest Essentials anchors the luxury ayurvedic segment through controlled-origin sourcing and heritage formulation positioning.
Organic Soaps Market Vendor Landscape
Listed leaders compete with private specialists across certification infrastructure and controlled-origin supply chains. The vendor base concentrates around three strategic tiers: heritage botanical houses with captive herb gardens, certified organic specialists with USDA-compliant supply chains, and ayurvedic heritage brands with controlled-origin sourcing. Competitive moves cluster on certification acquisition and pharmacy channel penetration rather than price-based rivalry.
Within the heritage botanical tier, Weleda AG and L'OCCITANE INTERNATIONAL SA exemplify the controlled-origin archetype through captive cultivation and regional terroir positioning. Dr. Bronner's Magic Soaps represents the certified organic specialist model with its USDA-compliant supply chain anchoring premium shelf placement. Faith In Nature Limited occupies a mid-market position between mass retail accessibility and natural cosmetics compliance. These three archetypes—heritage cultivation, certification-led, and accessible natural—structure competitive dynamics more than scale or geography alone.
| Leading Market Players |
|---|
| L'OCCITANE INTERNATIONAL SA |
| Weleda AG |
| Dr. Bronner's Magic Soaps |
| Laverana GmbH & Co. KG |
| Faith In Nature Limited |
| Pangea Organics |
| Neal's Yard Remedies |
| Forest Essentials |
| Natura & Co. Holdings S.A. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal chemical sustainability requirements gate both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb reformulation costs or forfeit pharmacy channel access while enabling certified operators to command shelf-space premiums. REACH-compliant saponified plant oil formulations carry 15-25% price elevation over conventional surfactant alternatives, with certification documentation costs embedding permanently in unit economics.
Pricing Analysis
Certification level creates the primary spread across organic soap tiers, with USDA Organic and EU organic seals separating premium pharmacy positioning from mass-market natural claims. Three-tier pricing structure across premium certified, standard natural, and economy conventional levels reflects agricultural content verification burden and botanical provenance documentation. Cost compression in mid-tier segments is intensifying because sodium cocoyl isethionate and other mild synthetics capture price-sensitive household buyers. Institutional procurement through Berlin wellness centers and Hamburg dermatology clinics shows lowest price sensitivity, while mass retail households in Manchester and Birmingham exhibit highest elasticity to per-unit cost.
Supply Chain Analysis
Philippines and Indonesia anchor global coconut oil supply for saponified base production, with Provence and Tuscany clusters commanding artisan premiums through cold-process terroir positioning. Saponified coconut and olive oil bases, lavender and tea tree essential oils, and citric acid chelating alternatives constitute critical input dependencies. Single-source vulnerability concentrates in Philippine coconut oil exports exposed to climate disruption and logistics chokepoints. Distribution runs through German pharmacy wholesalers and French specialty beauty chains, with direct-to-hotel procurement for liquid dispenser formats gaining share in hospitality channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic soaps sit in early-cycle expansion as EU Green Deal enforcement accelerates certified product displacement of conventional cleansers in institutional procurement channels. Pharmacy and wellness center adoption curves remain below saturation thresholds across core European markets.
For Market Incumbents: Consolidate certification infrastructure through captive herb garden expansion and controlled-origin sourcing investments that replicate Weleda's supply chain model. Deepen vertical integration into cold-process saponification capacity in Provence and Tuscany to defend margin position against synthetic surfactant substitution threats in mass retail tiers. For New Entrants and Emerging Players: Lead with fermentation-derived preservation biotechnology partnerships that address the microbiological expertise gap blocking European manufacturing scale-up. Target fragrance-free pediatric segments in Hamburg and Berlin clinic networks where dermatologist recommendations override brand loyalty, deploying QR-code supply chain transparency as the primary go-to-market wedge. For Investors and Strategic Acquirers: EU Green Deal REACH implementation timelines reshape the acquisition landscape toward certified organic specialists with documented supply chains and pharmacy channel relationships. Five-to-ten year viability favors heritage botanical houses with backward integration into raw material cultivation over formulation-only operators exposed to agricultural price volatility. Monitor German pharmacy distributor procurement specifications tightening as the signal for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | USDA Organic and EU organic seals unlock pharmacy channel access and price premiums. |
| Cold-Process Saponification Scale-Up | Temperature-controlled curing in Provence preserves botanical actives for terroir positioning. |
| Fermentation-Derived Preservation Partnership | Lactobacillus biotechnology addresses tightening natural antimicrobial standards under REACH. |
| Pharmacy Channel Penetration | German and French distributor relationships anchor institutional volume growth. |
| QR-Code Supply Chain Transparency | Paris and London metropolitan buyers prioritize provenance verification over brand heritage. |
Methodological Framework
Desk research of customs trade data, EU regulatory filings, and pharmacy procurement databases preceded structured interviews with organic soap brand managers, German pharmacy distributors, French specialty beauty retail buyers, and formulation chemists across European manufacturing hubs. Primary fieldwork with wellness center procurement officers and dermatology clinic supply managers validated secondary demand estimates. Bottom-up volume triangulation across bar, liquid, foam, and powder formats reconciled against top-down market sizing from certification body disclosure records.
Variance decomposition across product type, ingredient category, end-user segment, and packaging format structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate blending and adoption curve modeling incorporated REACH compliance timeline assumptions and coconut oil price volatility scenarios. Modeled inputs included EU Green Deal enforcement intensity, pharmacy channel expansion rates in Manchester and Birmingham, and fermentation biotechnology commercialization pace for clean-label antimicrobials.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated synthetic surfactant cost parity would require recalibration. Forecasts reflect documented assumptions on certification timeline durations, raw material supply stability, and institutional procurement specification evolution. Recalibration cycles align with material shifts in EU Green Deal implementation, REACH amendment schedules, and breakthrough fermentation preservation approvals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Beauty Sheet Mask Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Cosmetics ODM Market
Cosmetics & Skincare
Global Cosmetic Jar Market
Cosmetics & Skincare
Skin Care Products Market
Cosmetics & Skincare
Deodorant Stick Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
Makeup Remover Market
Cosmetics & Skincare
Tea Based Face Masks Market
Cosmetics & Skincare
Vietnam Skin Care Products Market
Cosmetics & Skincare
Setting Spray Market
Cosmetics & Skincare
Period Balm Market