
 Organic Personal Care Market | 2026-2036
Organic Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Personal Care Market Intelligence
Buyer concentration in the organic personal care sector is broadening from niche wellness enthusiasts toward mass-market pharmacy and grocery channels. Dr. Bronner's Magic Soaps, Inc. leverages its certified organic supply chain and fair-trade sourcing to sustain price premiums across conventional retail. The Honest Company, Inc. competes through pediatrician-trusted positioning and subscription-based replenishment models that anchor recurring revenue streams.
Organic personal care encompasses cosmetics and hygiene formulations manufactured with agriculturally sourced ingredients certified free from synthetic pesticides, petrochemicals, and genetically modified organisms, typically requiring cold-process emulsification or supercritical CO2 extraction to preserve bioactive compound integrity. Skincare dominates current revenue contribution due to higher per-unit pricing and repeat purchase frequency, while haircare represents the fastest-expanding margin pool as scalp-health positioning drives professional salon channel penetration. Plant-based ingredient origin categories command premium shelf placement, though mineral-based sun care formulations are gaining traction amid reef-safe regulatory momentum in coastal jurisdictions.
The USDA National Organic Program, EU REACH, and COSMOS-standard certification collectively govern ingredient disclosure thresholds and prohibit specific synthetic preservatives across major export markets. These frameworks elevate compliance costs for small-batch manufacturers while creating market access barriers for uncertified imports. Stakeholders must monitor evolving state-level clean beauty legislation in California and New York, where pending disclosure mandates could reshape labeling requirements and reformulation priorities ahead of federal harmonization.
Market Dynamics
The organic personal care sector confronts a structural pivot where EU REACH tightening on synthetic preservatives forces wholesale reformulation toward botanical actives, compressing legacy supply chains while elevating certified ingredient premiums.
Growth Catalysts
- EU Green Deal chemical phase-outs:REACH restrictions on parabens and formaldehyde-releasing preservatives accelerate clean-label migration across export-dependent manufacturers.
- Scalp-health positioning in professional salons:Trichology-informed haircare protocols drive premium service attach rates and recurring retail purchases.
- South Korean dermatologist endorsement channels:K-beauty retail infrastructure legitimizes organic claims through clinical credibility and social proof mechanisms.
Market Restraints
- Certified organic feedstock cost volatility:Climate stress on shea butter and argan oil harvests in West Africa squeezes gross margins for cold-process emulsion formulators.
- Supercritical CO2 extraction equipment concentration:German and Italian machinery suppliers command 18-24 month lead times for capacity expansion.
- Reef-safe mineral sunscreen technical limitations:Zinc oxide whitening effects and SPF efficacy gaps constrain mass-market adoption against chemical alternatives.
Strategic Opportunities
- Subscription-based replenishment models:Direct-to-consumer auto-ship programs anchor recurring revenue and reduce customer acquisition cost inflation.
- India's emerging pharmacy channel penetration:Urban tier-1 cities show rising clean beauty literacy among dermatology clinic patients.
- COSMOS-standard certification harmonization:Unified EU organic cosmetics labeling reduces multi-market compliance fragmentation for export-ready brands.
Industry Challenges
- Cold-process emulsification talent scarcity:Formulation chemists with bioactive preservation expertise command premium compensation in competitive labor markets.
- Multi-certification timeline compression:USDA National Organic Program and COSMOS dual audits extend product launch windows by 8-14 months.
- Legacy ERP integration with batch-level traceability:Blockchain-enabled supply chain transparency requires substantial middleware investment for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Personal Care Market |
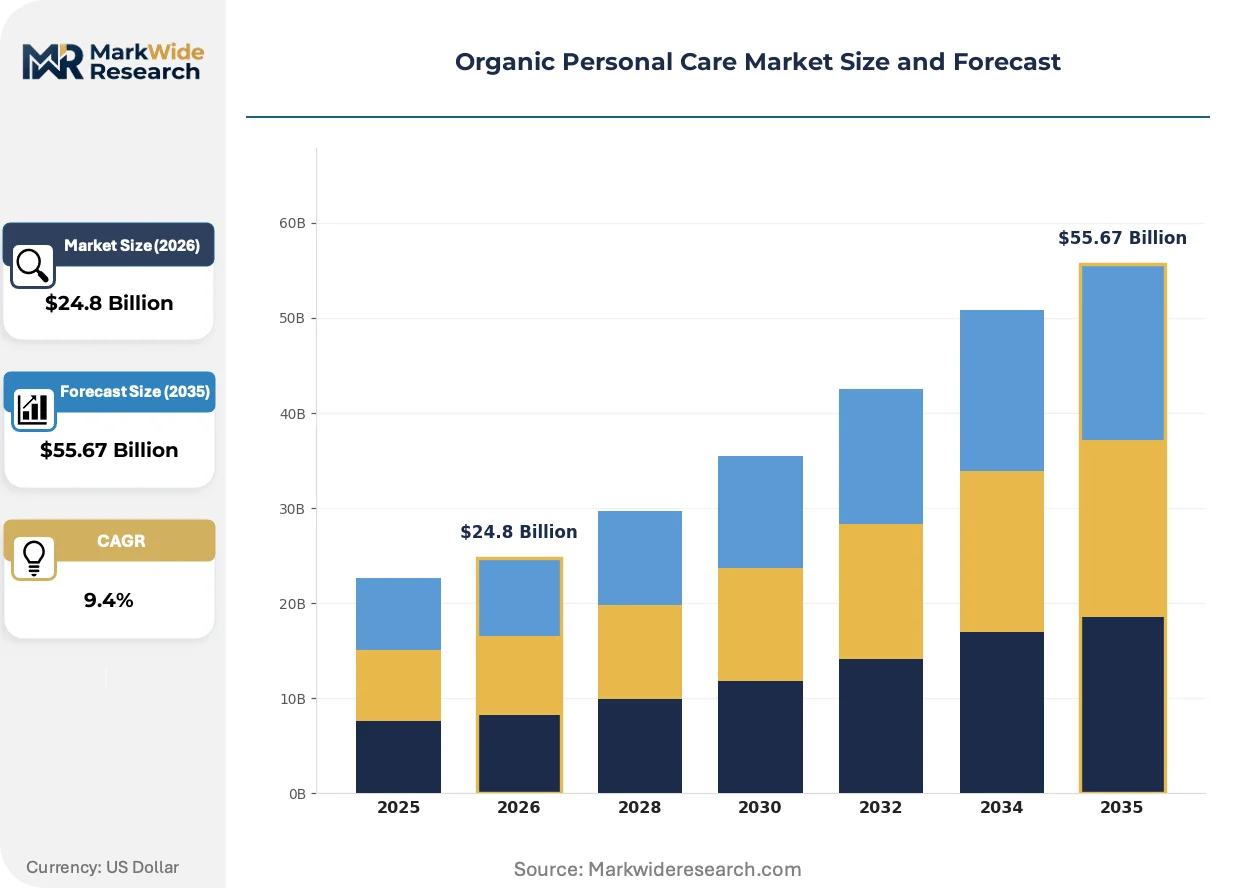
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $55.67 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrances Ingredient Origin: Plant-Based, Mineral-Based, Natural Extracts, Others End User: Women, Men, Children, Unisex Distribution Channel: Online, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Beautycounter (Counter Brands, LLC), Herbivore Botanicals, LLC, Dr. Bronner’s Magic Soaps, Inc., cocokind, Burt’s Bees, The Honest Company, Inc., Weleda Inc., Ursa Major, Juice Beauty, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Personal Care Market Strategic Shifts & Innovations
Formulation science and retail infrastructure are converging to redefine competitive advantage, with biotechnology extraction methods and regulatory disclosure mandates compressing incumbent positioning while opening white space for transparent supply chain operators.
Supercritical CO2 extraction for botanical actives is overtaking solvent-based methods across premium skincare manufacturing. European and North American clean beauty brands adopt this technology to preserve heat-sensitive compound integrity and eliminate petrochemical residue concerns. The shift compresses traditional extraction equipment vendors while elevating capital-light toll manufacturers with installed supercritical capacity.
REACH authorization requirements for synthetic preservatives are forcing reformulation roadmaps across EU-exporting formulators. The ECHA sunset clause timeline for isothiazolinone biocides compresses product lifecycle planning and accelerates partnership searches with certified organic ingredient suppliers. Haircare and baby care segments face the steepest compliance cliffs given their sensitivity-positioning and pediatric safety scrutiny.
Pediatrician-trusted positioning is displacing influencer-driven discovery as the primary customer acquisition channel for family-oriented organic personal care. Pharmacy and grocery retail buyers now prioritize clinical endorsement credentials over social media metrics when allocating shelf space. This rotation is most visible in United States coastal markets where clean beauty literacy has matured beyond early-adopter demographics.
Organic Personal Care Market Segmentation
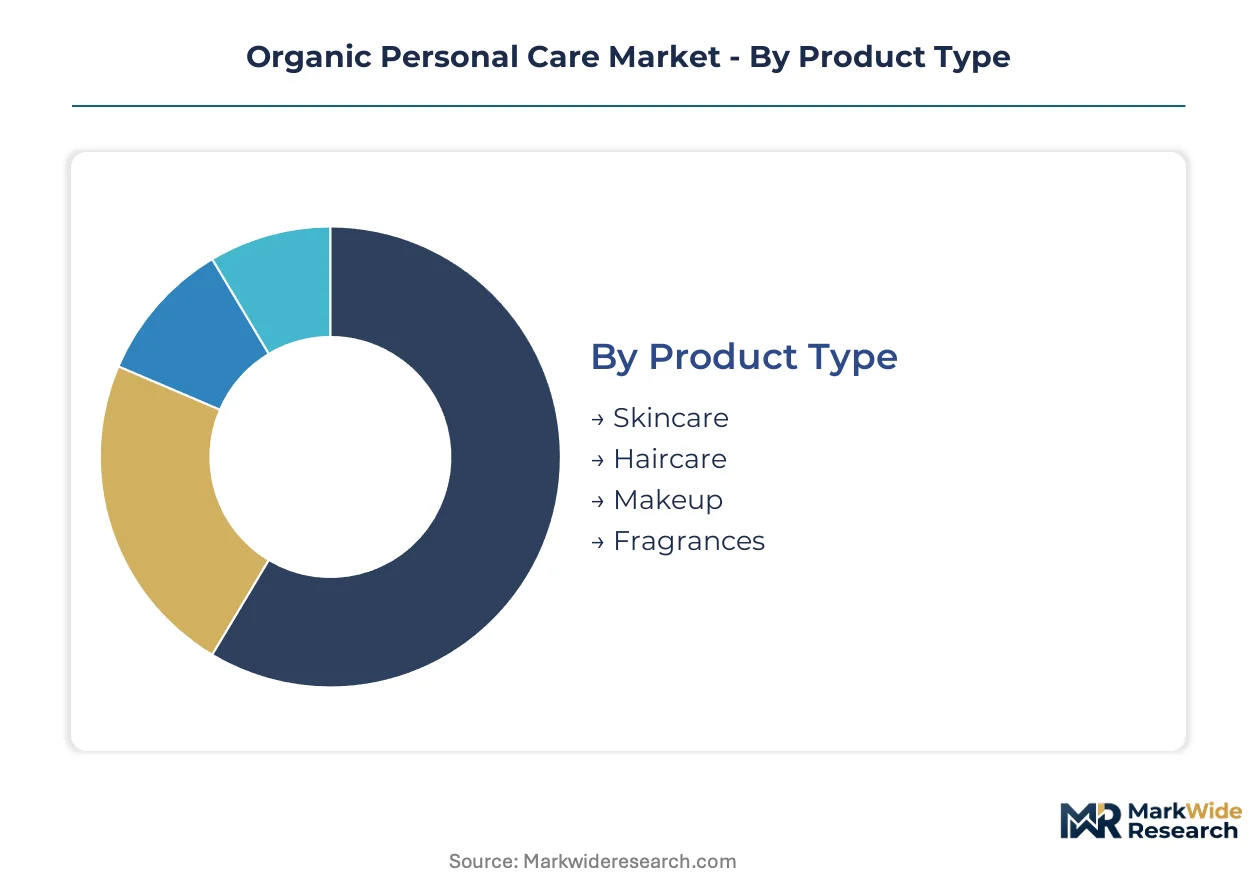
Segmentation in organic personal care reveals how certification premiums, ingredient sourcing complexity, and channel-specific trust mechanisms fragment buyer behavior across otherwise overlapping demographics. Formulators must align product architecture with distinct purchase triggers rather than assuming clean-label appeal transfers uniformly.
Product Type:
Purchase frequency and per-unit margin separate routine replenishment categories from discretionary trial segments.
- Skincare:Serums, moisturizers, and cleansers formulated with cold-process emulsification dominate current revenue contribution. United States dermatology clinic channels anchor premium positioning through clinical endorsement protocols that validate organic efficacy claims.
- Haircare:Scalp-health formulations are expanding most quickly through professional salon service attach rates. South Korean trichology-informed retail legitimizes premium pricing through technical credibility and repeat purchase programming.
- Makeup:Color cosmetics face formulation constraints from mineral pigment sourcing and preservative-free stability requirements.
- Fragrances:Essential oil-based compositions compete with synthetic alternatives on longevity and allergen disclosure transparency.
Skincare leads on scale; haircare leads on momentum.
Ingredient Origin:
Certification grade determines shelf placement hierarchy and export market access eligibility.
- Plant-Based:Agriculturally sourced botanicals certified under USDA National Organic Program or COSMOS standards command price premiums. EU REACH tightening on synthetic preservatives accelerates reformulation demand for these feedstocks.
- Mineral-Based:Zinc oxide and titanium dioxide sun care formulations gain regulatory tailwinds from reef-safe mandates in Hawaii and Palau coastal jurisdictions.
- Natural Extracts:Supercritical CO2-derived actives preserve heat-sensitive compound integrity for premium skincare applications.
- Others:Fermentation-derived and biotechnology-sourced ingredients occupy emerging regulatory gray zones between natural and synthetic classification.
Plant-based ingredients anchor volume concentration; mineral-based formulations climb the fastest on regulatory compliance demand.
End User:
Demographic targeting intensity varies with sensitivity-positioning requirements and household purchase authority.
- Women:Core segment driving premium skincare and haircare adoption through established clean beauty literacy.
- Men:Grooming category expansion concentrates in urban tier-1 pharmacy channels with simplified regimen positioning.
- Children:Pediatrician-trusted brands anchor family-oriented organic personal care through pharmacy retail credentialing.
- Unisex:Fragrance and body care formulations minimize gendered marketing to capture household consolidation purchasing.
Women's segments retain volume leadership; children's formulations gain share fastest on safety-positioning premiums.
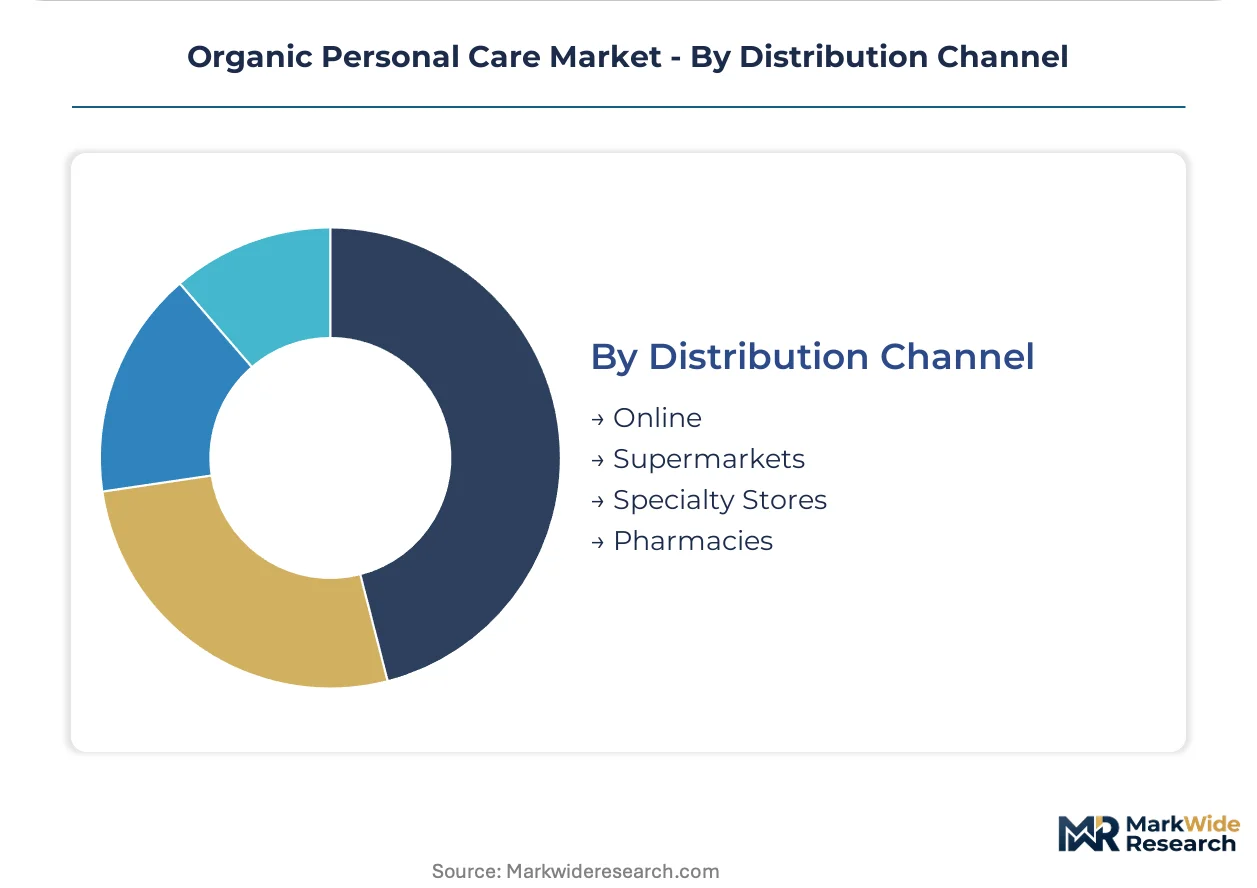
Distribution Channel:
Trust transfer mechanisms differ sharply between discovery-oriented and replenishment-oriented purchase contexts.
- Online:Direct-to-consumer auto-ship programs reduce customer acquisition cost inflation through subscription-based replenishment models.
- Supermarkets:Mass-market clean beauty placement depends on COSMOS or USDA certification visibility for shelf space allocation.
- Specialty Stores:Curated assortment and staff education justify premium pricing for complex ingredient narratives.
- Pharmacies:Clinical endorsement credentials displace influencer metrics in United States coastal market buyer decisions.
Online channels scale fastest on recurring revenue mechanics; pharmacies concentrate margin on trust-based conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with bioactive preservation expertise concentrate in Germany, South Korea, and the United States, anchoring innovation clusters that export technical know-how to emerging clean beauty markets.
United States
Clean beauty literacy has matured beyond early-adopter demographics in coastal markets, driving pharmacy retail buyers to prioritize clinical endorsement credentials over social media metrics. The FDA and pending state-level disclosure mandates in California and New York reshape labeling requirements ahead of federal harmonization. Greater Los Angeles and New York Metro anchor dermatology clinic channels that validate organic efficacy claims through professional endorsement protocols.
Germany
Supercritical CO2 extraction equipment suppliers command 18-24 month lead times for capacity expansion, concentrating technical capability in Baden-Württemberg and Bavaria. ECHA REACH sunset clauses for isothiazolinone biocides compress product lifecycle planning for EU-exporting formulators. The Rhine-Main and Stuttgart industrial clusters house toll manufacturers with installed supercritical capacity serving premium skincare brands.
South Korea
Trichology-informed retail legitimizes premium pricing through technical credibility and repeat purchase programming in scalp-health haircare. The MFDS regulates cosmetic safety while K-beauty infrastructure provides dermatologist endorsement channels that validate organic claims. Seoul Capital Area concentration of dermatology clinics drives professional channel penetration for clean beauty brands seeking clinical credibility.
India
Urban tier-1 cities demonstrate rising clean beauty literacy among dermatology clinic patients, expanding pharmacy channel penetration for family-oriented organic personal care. The CDSCO and BIS frameworks govern cosmetic safety standards while import regulations create compliance barriers for uncertified foreign brands. Maharashtra and Karnataka sub-regions concentrate formulation talent serving domestic brands with export ambitions.
France
COSMOS-standard certification harmonization reduces multi-market compliance fragmentation for export-ready brands headquartered in EU regulatory jurisdictions. ANSM oversight of cosmetic safety aligns with EU REACH chemical phase-out timelines. The Île-de-France region concentrates headquarters operations for brands leveraging unified organic cosmetics labeling across European export markets.
Organic Personal Care Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between mass-market grocery and pharmacy channels, professional salon service attach rates, and direct-to-consumer subscription mechanics. Three archetypes dominate: certified organic supply chain operators, pediatrician-trusted family brands, and biotechnology extraction method specialists. Competitive moves concentrate on subscription-based replenishment model deployment and COSMOS-standard certification acquisition for EU market access.
Within the certified organic supply chain tier, Dr. Bronner's Magic Soaps, Inc. and Weleda Inc. exemplify heritage positioning anchored in fair-trade sourcing and cold-process emulsification credibility. The Honest Company, Inc. occupies a position in the pediatrician-trusted archetype, representing subscription-based replenishment mechanics that anchor recurring revenue streams. Among K-beauty-influenced specialists, Herbivore Botanicals, LLC sits within the clean-label discovery segment.
| Leading Market Players |
|---|
| Beautycounter (Counter Brands, LLC) |
| Herbivore Botanicals, LLC |
| Dr. Bronner's Magic Soaps, Inc. |
| cocokind |
| Burt's Bees |
| The Honest Company, Inc. |
| Weleda Inc. |
| Ursa Major |
| Juice Beauty, Inc. |
| Others |
Cost & Logistics Intelligence
Shea butter and argan oil harvest volatility in West Africa feeds directly into certified organic feedstock premiums that stratify pricing across cold-process emulsion tiers. This upstream cost compression cascades through formulator margins and ultimately shapes shelf placement hierarchies in pharmacy and grocery channels.
Pricing Analysis
Subscription-based replenishment services versus per-unit transactional purchases split buyer economics across the organic personal care sector. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and dermatologist endorsement density. Pricing pressure stems from climate stress on botanical feedstocks in key sourcing regions. Mass-market grocery buyers exhibit highest price sensitivity while pharmacy channel purchasers accept premiums for clinical credibility.
Supply Chain Analysis
Direct-to-consumer auto-ship programs and professional salon service attach rates constitute the dominant downstream distribution architecture. Raw material sourcing draws from West African shea and argan cooperatives, Indian botanical extractors, and German supercritical CO2 equipment operators. Single-source vulnerability concentrates in cold-process emulsification talent pools and certified organic ingredient suppliers. Distribution runs through pharmacy retail credentialing in United States coastal markets and K-beauty dermatology clinic channels in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate where certified organic certification premiums outpace feedstock cost inflation and subscription mechanics reduce customer acquisition expenditure. Professional salon channel penetration and pediatrician-trusted positioning represent the most defensible premium-tier shifts.
For Market Incumbents: Hedge against REACH authorization timelines by accelerating botanical active partnerships before isothiazolinone sunset clauses take effect. Secure backward integration into shea butter cooperatives through fair-trade supply agreements that lock in feedstock priority allocation. Channel control through dermatology clinic endorsement protocols defends price positioning against influencer-driven discovery erosion. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting India's urban tier-1 pharmacy channels where clean beauty literacy is ascending fastest. White space exists in scalp-health haircare formulations for men and unisex body care with simplified regimen positioning. Go-to-market angle should emphasize COSMOS-standard certification as EU market access enabler. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-certification timeline compression and ERP integration costs disadvantage mid-tier manufacturers lacking capital reserves. Long-term viability favors toll manufacturers with installed supercritical CO2 capacity and brands with pediatrician-trusted pharmacy retail anchoring. Acquisition target archetype: certified organic supply chain operators with fair-trade sourcing credibility and subscription-based revenue mechanics. Signal to watch: state-level clean beauty disclosure mandates in California and New York triggering reformulation capex spikes.| Strategic Initiative | Industry Significance |
|---|---|
| COSMOS-Standard Certification Acquisition | EU REACH alignment unlocks unified labeling across European export markets. |
| Subscription-Based Replenishment Launch | Direct-to-consumer auto-ship mechanics anchor recurring revenue and reduce acquisition costs. |
| Supercritical CO2 Capacity Partnership | Toll manufacturing agreements with German equipment operators preserve bioactive compound integrity. |
| Professional Salon Channel Expansion | Trichology-informed service attach rates drive scalp-health haircare premium positioning. |
| Pediatrician Endorsement Protocol Investment | Pharmacy retail credentialing displaces influencer metrics in United States coastal markets. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's formulation chemists, pharmacy retail buyers, and dermatology clinic operators. Secondary validation draws from FDA cosmetic registration databases, ECHA REACH authorization timelines, COSMOS-standard certification records, and customs trade data for organic ingredient flows. Bottom-up product-level modeling triangulates against top-down category spending estimates.
Granularity-level framing applies country-specific regulatory cluster modeling and channel-specific trust transfer mechanics across the projection horizon. Segmentation dimensions include product type, ingredient origin certification tier, end-user demographic, and distribution channel trust architecture. CAGRs derive from volume-price elasticity modeling and repeat purchase frequency calibration. Industry-specific inputs incorporate supercritical CO2 extraction capacity utilization and REACH sunset clause compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory acceleration scenarios or climate-induced feedstock disruption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
US Sustainable Personal Care Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Sun Protection Spray Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
South America Hair Conditioner Market
Beauty & Personal Care
Scalp Massager Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Face Makeup Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
Liquid Soap Market
Beauty & Personal Care
Artificial Nails Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Intimate Hygiene Products Market