
 Philippines Beauty & Personal Care Market | 2026-2036
Philippines Beauty & Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Beauty & Personal Care Market Insights
Niacinamide is repositioning product economics across mass-market skincare by displacing higher-cost brightening actives. L'Oréal Philippines leverages its dermatological science pipeline to command shelf space in specialty stores. Unilever Group sustains volume leadership through sachet economics that reach lower-income barangays. Human Nature anchors its competitive stance with community-sourced raw materials and direct-to-consumer channels.
Philippines Beauty & Personal Care encompasses topical formulations, color cosmetics, hair treatments, and scented products designed for tropical climate resilience, humidity stability, and melanin-responsive efficacy. The category serves both daily grooming rituals and professional aesthetic services across a population of over 110 million consumers. Skincare leads value generation as consumers prioritize sun protection and barrier repair in a high-UV environment. Haircare competes for share through keratin and botanical positioning against heat and humidity damage. Online Retail is accelerating fastest as live commerce and social selling collapse the path from discovery to purchase in archipelago logistics.
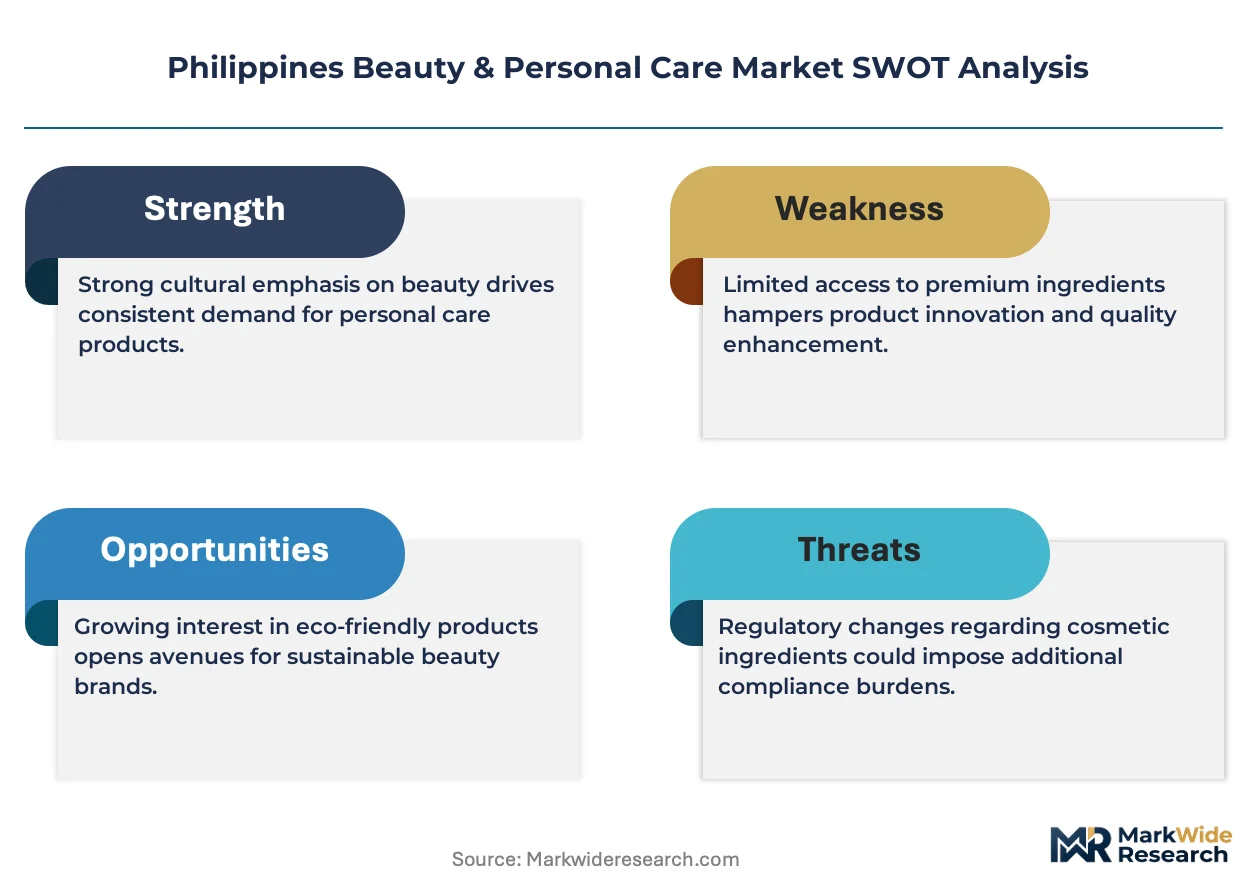
FDA Philippines enforces the ASEAN Cosmetics Directive's ingredient labeling and safety assessment requirements, while the Bureau of Philippine Standards monitors quality claims on domestic manufacturing. These frameworks elevate compliance costs for importers but create protected terrain for locally certified producers. Stakeholders must track how evolving digital commerce regulations intersect with influencer marketing disclosure rules to anticipate channel strategy adjustments.
Market Dynamics
The Philippines beauty sector is contending with a structural pivot where live commerce infrastructure is collapsing traditional distributor layers, forcing brands to rebuild fulfillment networks for archipelago logistics while FDA Philippines tightens ingredient traceability mandates.
Growth Catalysts
- ASEAN Cosmetics Directive alignment:Harmonized safety standards reduce cross-border compliance friction for importers serving Metro Manila and Cebu City.
- Barangay sachet penetration:Single-use packaging economics unlocks weekly purchasing cycles among lower-income households previously excluded from branded skincare.
- Keratin treatment demand:Humidity-driven hair damage concerns in tropical climates sustain professional salon service frequency among working professionals.
Market Restraints
- Palm oil derivative volatility:Surfactant and emollient input costs fluctuate with Malaysian export policies, compressing mass-market margin structures.
- Specialty retailer concentration:Watsons and SM Beauty collectively gatekeep premium shelf access in urban centers, elevating slotting fee burdens for emerging brands.
- Melanin-responsive formulation gaps:Limited local R&D capacity for Fitzpatrick Type IV-VI skin adaptations forces reliance on imported clinical validation.
Strategic Opportunities
- Mindanao secondary cities:Davao City and Cagayan de Oro show underpenetrated modern trade depth relative to Visayas and Luzon saturation.
- Social commerce integration:TikTok Shop and Facebook Live transactions bypass traditional distributor markups for direct creator-brand relationships.
- Botanical traceability premiums:FDA Philippines clean label recognition creates pricing separation for community-sourced calamansi and papaya extracts.
Industry Challenges
- Cosmetic chemist scarcity:Formulation talent concentrates in Metro Manila, constraining provincial manufacturing scale-up.
- Halal certification timelines:Bureau of Philippine Standards approval processes delay export readiness for Muslim-majority ASEAN markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Beauty & Personal Care Market |
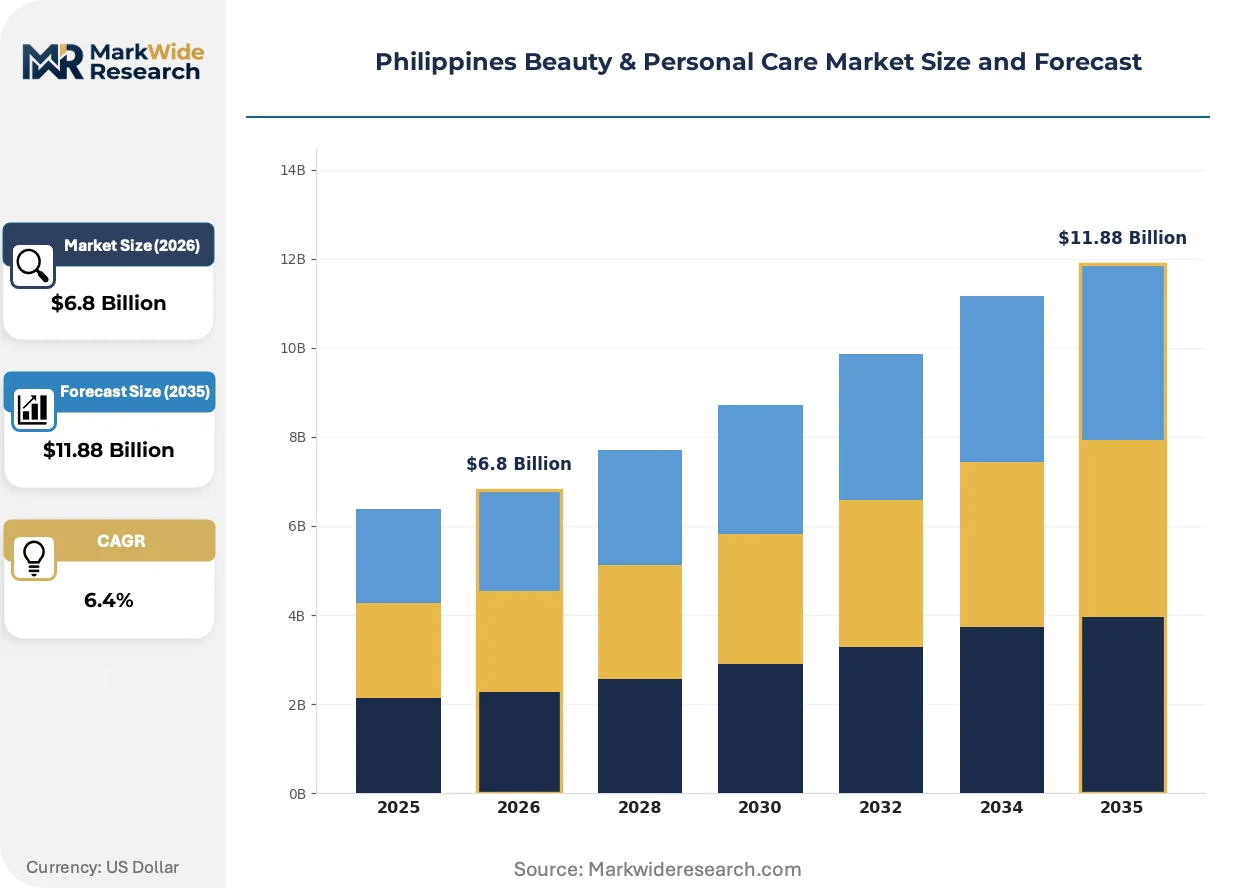
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance Distribution Channel: Online Retail, Drugstores, Supermarkets, Specialty Stores Customer Type: Women, Men, Teenagers, Kids Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | L'Oréal Philippines, Belo Medical Group, Unilever Group, Ever Bilena, Human Nature, Splash Corporation, Procter & Gamble Philippines, Kojie San, Watsons, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Beauty & Personal Care Market Trends and Innovations
Digital discovery mechanisms are compressing the path from ingredient education to purchase, while climate-adaptive formulations and regulatory transparency reshape product development priorities.
Niacinamide concentration protocols are decentralizing brightening efficacy claims previously guarded by prescription-grade hydroquinone alternatives. Young professionals in Metro Manila now access dermatologist-tier actives through mass-market channels without clinic intermediaries. This shift erodes the historical premium attached to medical-grade dispensing.
FDA Philippines enforcement of the ASEAN Cosmetics Directive's ingredient disclosure mandates is elevating documentation burdens for importers. Domestic manufacturers with pre-established safety dossiers capture shelf space as foreign brands delay registration. Specialty retailers now prioritize locally certified inventory to reduce compliance risk exposure.
Live commerce sessions on TikTok Shop are replacing static e-commerce listings as the primary discovery channel for skincare trial. Beauty creators in Cebu City and Davao City convert humidity-specific product demonstrations into immediate purchase through embedded checkout. This behavior concentrates demand generation outside traditional advertising and retail placement budgets.
Philippines Beauty & Personal Care Market Segmentation
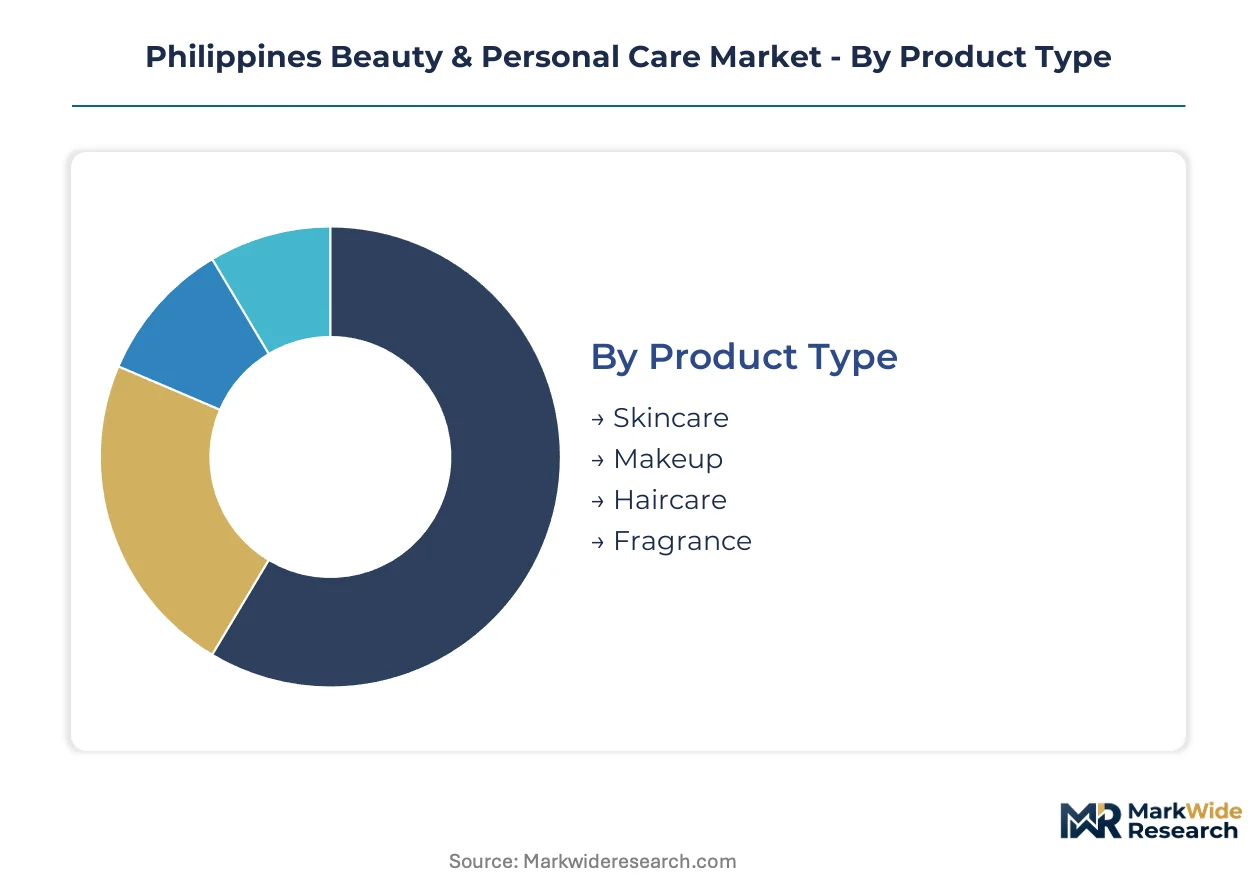
Segmentation in the Philippines beauty sector reveals how tropical climate demands and archipelago logistics reshape category priorities. Distinct consumption patterns emerge across price tiers and channels as live commerce collapses traditional purchase pathways.
Product Type:
Replacement cycles accelerate where humidity and UV exposure degrade formulation stability fastest.
- Skincare:Barrier-repair and sun-protection formulations dominate value generation. Young professionals in Metro Manila drive serum and essence adoption as daily UV defense becomes non-negotiable. FDA Philippines ingredient disclosure mandates favor domestically certified brightening actives over delayed import registrations.
- Makeup:Long-wear and sweat-resistant color cosmetics command shelf space in Watsons and SM Beauty. Cebu City working women prioritize transfer-proof foundations for tropical commute conditions. The category contends with compressed trial cycles as TikTok Shop swatches replace counter testing.
- Haircare:Keratin and botanical positioning targets humidity-driven frizz damage in professional salon channels.
- Fragrance:Body mists and alcohol-free formats outperform traditional eaux de parfum in heat-stability metrics.
Volume placements concentrate in Skincare; the faster expansion belongs to Makeup.
Distribution Channel:
Channel economics split between sachet penetration depth and premium experience delivery.
- Online Retail:TikTok Shop and Facebook Live transactions now capture discovery-to-purchase journeys previously routed through distributor layers. Embedded checkout in live sessions bypasses traditional markups for direct creator-brand relationships. Davao City and Cagayan de Oro show accelerating adoption as logistics networks deepen in Mindanao secondary cities.
- Specialty Stores:Watsons and SM Beauty gatekeep premium access through elevated slotting fees. Shelf space prioritizes locally certified inventory to reduce FDA Philippines compliance exposure. The channel sustains professional-grade service for consumers seeking dermatologist-tier actives without clinic intermediaries.
- Drugstores:Mercury Drug and Generika anchor mass-market accessibility with sachet economics for weekly purchasing cycles.
- Supermarkets:SM Supermarket and Puregold extend reach into lower-income barangays through bundled family-size formats.
Transaction velocity peaks in Online Retail; margin protection remains strongest in Specialty Stores.
Customer Type:
Demographic targeting adjusts for life-stage-specific skin concerns and grooming ritual complexity.
- Women:Multi-step routines spanning brightening, barrier repair, and sun defense generate category value concentration. Metro Manila professionals access niacinamide and peptide formulations through mass-market channels previously restricted to medical-grade dispensing. The segment drives premiumization as ingredient education spreads through social commerce.
- Men:Simplified regimens focusing on oil control and sun protection gain traction in drugstore channels. Barangay sachet formats lower trial barriers for first-time skincare adopters among working-class demographics.
- Teenagers:Acne-specific positioning and influencer-driven discovery dominate purchase behavior.
- Kids:Gentle, tear-free formulations with FDA Philippines safety certification anchor parental trust.
Revenue concentration sits with Women; the steepest expansion trajectory belongs to Men.
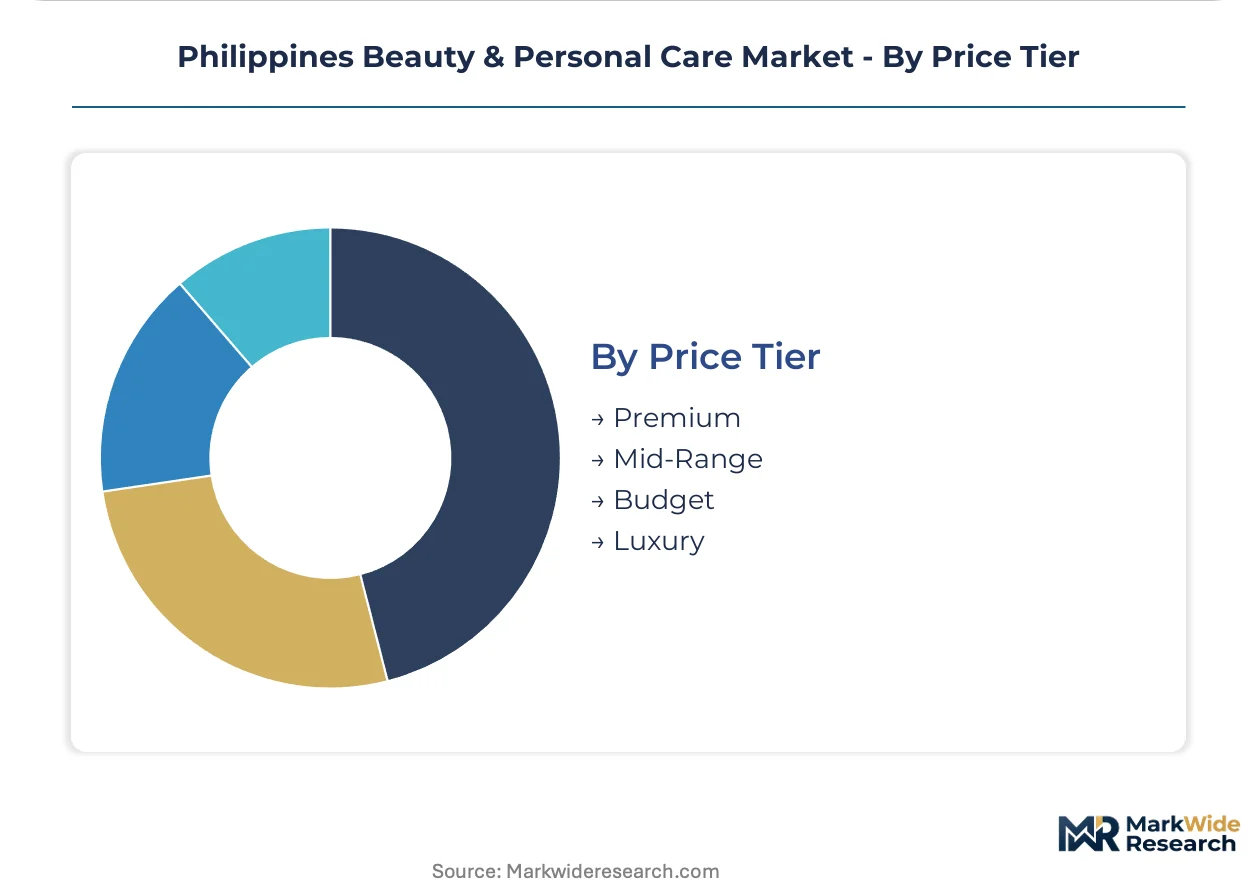
Price Tier:
Tier stratification reflects formulation complexity, certification burden, and channel access cost.
- Premium:Dermatologically tested actives with ASEAN Cosmetics Directive dossiers command specialty retailer placement. L'Oréal Philippines and similar science-backed brands leverage clinical validation for shelf space in SM Beauty. The tier absorbs compliance cost premiums as FDA Philippines tightens import registration timelines.
- Mid-Range:Hybrid positioning bridges mass accessibility and ingredient sophistication. Human Nature and comparable local brands exploit community-sourced botanical traceability for clean-label premiums. Direct-to-consumer channels bypass slotting fee burdens that constrain emerging competitors.
- Budget:Sachet economics and basic hygiene formulations serve weekly purchasing cycles in provincial barangays.
- Luxury:Imported prestige fragrances and limited-edition color cosmetics target gift-giving occasions in Metro Manila.
Unit volume clusters in Budget; value capture concentrates in Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Philippine Economic Zone Authority (PEZA) registered manufacturing enclave in Cavite anchors foreign cosmetics investment through tax holidays and duty exemptions on imported raw materials. Metro Manila, Cebu City, and Davao City concentrate demand generation while provincial manufacturing clusters deepen under PEZA facilitation.
Metro Manila
Young professionals drive serum and sunscreen adoption as daily UV defense becomes non-negotiable. FDA Philippines enforcement of ASEAN Cosmetics Directive ingredient disclosure elevates documentation burdens for importers. Quezon City and Makati host the densest specialty retail networks where Watsons and SM Beauty gatekeep premium shelf access.
Central Visayas
Cebu City working women prioritize transfer-proof foundations for tropical commute conditions. The Bureau of Philippine Standards monitors quality claims on domestic manufacturing from Mandaue industrial zones. Live commerce adoption accelerates faster here than in Mindanao as logistics networks mature.
Davao Region
Mindanao's secondary city shows underpenetrated modern trade depth relative to Luzon saturation. Community-sourced calamansi and papaya extract supply chains anchor Human Nature's direct-to-consumer operations. Davao City beauty creators convert humidity-specific product demonstrations into immediate TikTok Shop purchases.
Calabarzon
Cavite and Laguna host PEZA-registered manufacturing enclaves serving both domestic distribution and export preparation. Cosmetic chemist scarcity concentrates formulation talent in these zones while provincial scale-up lags. Palm oil derivative volatility from Malaysian export policies compresses mass-market margin structures for surfactant-dependent production.
Northern Luzon
Baguio City's cooler climate supports botanical cultivation for clean-label extract sourcing. The Cordillera Administrative Region supplies papaya and coffee derivatives to Metro Manila formulators. Halal certification timelines through the Bureau of Philippine Standards delay export readiness for Muslim-majority ASEAN markets from this cluster.
Philippines Beauty & Personal Care Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Science-backed multinationals command specialty retailer shelf space through clinical validation dossiers while local direct-to-consumer brands bypass slotting fees. Three archetypes dominate: dermatological science pipelines, community-sourced botanical traceability players, and sachet-economics volume leaders. Competitive moves concentrate on social commerce integration and PEZA manufacturing enclave expansion.
Within the science-backed tier, L'Oréal Philippines occupies a position exemplifying dermatological pipeline leverage. Unilever Group and Human Nature represent contrasting volume and values archetypes—sachet economics reaching lower-income barangays versus community-sourced raw materials with direct-to-consumer channels. These three anchors illustrate how compliance readiness, channel strategy, and sourcing philosophy differentiate positioning under tightening FDA Philippines enforcement.
| Leading Market Players |
|---|
| L'Oréal Philippines |
| Belo Medical Group |
| Unilever Group |
| Ever Bilena |
| Human Nature |
| Splash Corporation |
| Procter & Gamble Philippines |
| Kojie San |
| Watsons |
| Others |
Pricing and Supply Chain Analysis
Captive sourcing of calamansi and papaya extracts anchors Human Nature's cost position while insulating its direct-to-consumer pricing from commodity volatility that compresses mass-market competitors. This backward integration into community supply chains creates pricing separation unavailable to import-dependent brands facing FDA Philippines registration delays.
Pricing Analysis
Volume concentrates in budget sachets while margins accrue to premium dermatological tiers. Three-tier pricing structure across premium, standard, and economy levels separates L'Oréal Philippines clinical dossiers from Human Nature clean-label positioning and Unilever sachet economics. Cost compression in the budget tier intensifies because palm oil derivative volatility from Malaysian export policies squeezes surfactant-dependent formulations. Provincial barangay households show highest price sensitivity; Metro Manila professionals accessing niacinamide serums through mass channels exhibit lowest.
Supply Chain Analysis
Dual-sourcing requirements for FDA Philippines ASEAN Cosmetics Directive compliance force brands to qualify both Malaysian palm oil refiners and Indonesian surfactant specialists alongside domestic extract cooperatives. Raw material flows draw from Malaysian oleochemical plants, Indonesian botanical processors, and Cordillera Administrative Region papaya cultivators. Single-source vulnerability concentrates in specialty retailer gatekeeping where Watsons and SM Beauty slotting fees create distribution chokepoints. Distribution runs through PEZA-registered Cavite manufacturing enclaves feeding both domestic modern trade and export preparation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cosmetic chemist scarcity in provincial zones props premium pricing for Metro Manila formulation capacity, constraining supply response to demand expansion in Mindanao secondary cities.
For Market Incumbents: Deploy FDA Philippines pre-registration dossiers as shelf-space leverage against import competitors facing ASEAN Cosmetics Directive documentation delays. Deepen captive supply of community-sourced botanicals to defend margin position against palm oil input volatility. Reinforce specialty retailer relationships through exclusive niacinamide concentration protocols that emerging brands cannot replicate without clinical validation investment. For New Entrants and Emerging Players: Social commerce live-streaming infrastructure offers a technology-first wedge to bypass Watsons and SM Beauty slotting fee barriers in Davao City and Cagayan de Oro. Target underpenetrated Mindanao modern trade where logistics networks now support TikTok Shop embedded checkout. Prioritize humidity-specific formulation demonstrations that convert immediate purchase without counter testing infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in science-backed dermatological brands with ASEAN Cosmetics Directive dossiers and direct-to-consumer botanical players with traceable community supply chains. Long-term viability favors assets combining FDA Philippines compliance readiness with social commerce creator relationships. Watch FDA Philippines enforcement intensity as the inflection signal determining import competitor shelf access.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Traceability Certification | FDA Philippines clean label recognition creates pricing separation for community-sourced calamansi and papaya extracts. |
| Social Commerce Platform Integration | TikTok Shop embedded checkout collapses distributor layers for direct creator-brand relationships in archipelago logistics. |
| PEZA Manufacturing Enclave Expansion | Cavite tax holidays and duty exemptions anchor foreign investment while reducing import raw material cost exposure. |
| Direct-to-Consumer Channel Launch | Human Nature's community-sourced model bypasses slotting fees that constrain emerging competitors in specialty retail. |
| Dermatological Actives Premium Tier | L'Oréal Philippines leverages clinical validation to command shelf space where FDA Philippines tightens import registration timelines. |
Research Methodology
Independent corroboration across brand managers at L'Oréal Philippines and Human Nature, category buyers at Watsons and SM Beauty, and supply planners at PEZA-registered Cavite manufacturers underwrites the qualitative findings. Primary interviews with FDA Philippines regulatory affairs specialists, cosmetic chemists in Metro Manila formulation labs, and TikTok Shop beauty creators in Cebu City combined with secondary validation from Bureau of Philippine Standards quality claim databases, ASEAN Cosmetics Directive harmonization protocols, and Nielsen retail audit data. Bottom-up channel volume estimates and top-down economic consumption models triangulate market sizing.
Rate-of-change decomposition separates volume growth from premiumization effects across the analysis window. The analytical framework models product type segmentation by replacement cycle dynamics, distribution channel by logistics cost structure, customer type by life-stage skin concern complexity, and price tier by certification burden and formulation sophistication. CAGRs derive from trend extrapolation adjusted for regulatory enforcement intensity and live commerce adoption curves. Humidity-specific formulation stability and melanin-responsive efficacy validation serve as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including Bureau of Philippine Standards halal certification timeline acceleration for Muslim-majority ASEAN export readiness and Malaysian palm oil export policy regime shifts. Forecasts reflect assumptions about FDA Philippines enforcement consistency and TikTok Shop logistics network expansion throughout the projection horizon. Deviation in ASEAN Cosmetics Directive harmonization pace or social commerce regulatory tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Global Personal Care Market
Beauty & Personal Care
Body Care Products Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
Hairstyling Products Market
Beauty & Personal Care
E-Pharmacy Beauty and Personal Care (BPC) Market
Beauty & Personal Care
Luxury Cosmetics Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
Personalized Beauty Devices Market
Beauty & Personal Care
Medicated Personal Care Products Market
Beauty & Personal Care
Europe Lip Care Products Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Japan Beauty Fridges Market
Beauty & Personal Care
Bath and Body Products Market